
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
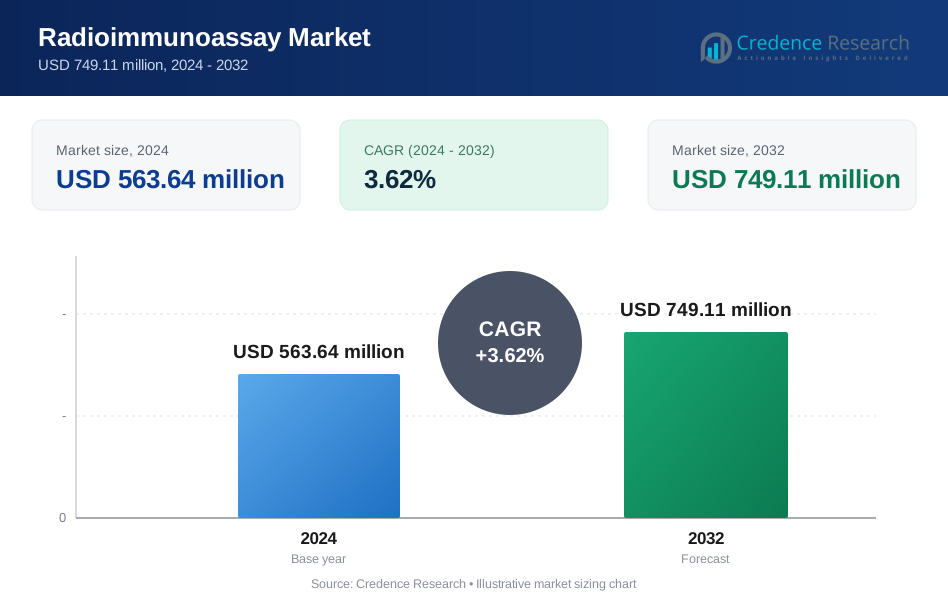
| Radioimmunoassay Market Size 2024 | USD 563.64 Million |
| Radioimmunoassay Market, CAGR | 3.62% |
| Radioimmunoassay Market Size 2032 | USD 749.11 Million |
Market Overview:
The Radioimmunoassay Market is projected to grow from USD 563.64 million in 2024 to an estimated USD 749.11 million by 2032, with a compound annual growth rate (CAGR) of 3.62% from 2024 to 2032.
Key drivers of the radioimmunoassay market include the growing prevalence of chronic diseases, such as cancer and hormonal disorders, which require precise and early diagnostic methods. RIA’s high sensitivity and specificity for detecting minute concentrations of biological substances make it ideal for these applications. Additionally, the expansion of the geriatric population globally and the rise in healthcare awareness have increased the demand for reliable diagnostic tools. However, the market faces some challenges, including regulatory restrictions around the use of radioactive materials and the availability of alternative, non-radioactive diagnostic methods such as enzyme-linked immunosorbent assay (ELISA). The growing investment in healthcare R&D and innovations in RIA techniques provide potential opportunities for market growth.
Regionally, North America dominates the radioimmunoassay market due to the advanced healthcare infrastructure, high adoption rates of RIA in diagnostic labs, and supportive government policies in the U.S. and Canada. Europe follows closely, driven by a well-established healthcare sector and increasing demand for early diagnostic tools. The Asia-Pacific region is projected to witness the fastest growth during the forecast period, largely attributed to the increasing healthcare expenditure in countries such as China, Japan, and India. As healthcare awareness and access to diagnostic technologies improve in emerging markets, the region’s demand for RIA-based testing is expected to surge, further supporting the market expansion in this area.
Market Drivers:
Growing Prevalence of Chronic Diseases:
The rising prevalence of chronic diseases such as cancer, cardiovascular diseases, and autoimmune disorders has significantly boosted the demand for radioimmunoassay (RIA) in clinical diagnostics. These diseases require precise and early detection, and RIA’s high sensitivity and specificity in measuring low concentrations of antigens or hormones make it an ideal choice. RIA’s applications in cancer diagnosis, in particular, are critical, as early detection often dictates treatment effectiveness. With a growing global emphasis on early disease diagnosis to improve patient outcomes, the demand for highly reliable diagnostic techniques like RIA is on the rise.
Expanding Geriatric Population and Healthcare Awareness:
A growing geriatric population worldwide has also driven the demand for RIA technology. As the population ages, the incidence of age-related diseases such as osteoporosis, hormonal imbalances, and diabetes increases, requiring regular monitoring and diagnostics. For instance, according to the World Health Organization, the global population aged 60 years and older is expected to reach 2.1 billion by 2050. RIA plays a key role in detecting and managing these conditions, offering precise measurements of hormones, vitamins, and other biomarkers. Moreover, with heightened awareness of healthcare practices and diagnostics, especially in developed economies, patients and healthcare providers increasingly seek accurate testing methods to support personalized treatment plans. RIA’s utility in meeting these needs has positioned it as a preferred diagnostic tool in an era of preventive healthcare.
Advancements in RIA Technology and Methodology:
Technological advancements have greatly enhanced the efficacy and application scope of radioimmunoassay techniques. Innovations in RIA have resulted in reduced sample sizes, increased sensitivity, and faster turnaround times, making RIA procedures more accessible and convenient for both patients and healthcare professionals. Automation and miniaturization have further optimized RIA procedures, enabling laboratories to perform high-throughput testing with increased accuracy and reliability. Additionally, the development of novel radiolabeled compounds has expanded the types of assays available, further supporting the widespread adoption of RIA in clinical laboratories. These advancements make RIA a competitive option in the field of immunoassays, promoting its sustained use in both clinical and research settings.
Increasing Investments in Healthcare Research and Diagnostics:
The rising investment in healthcare research and development has also contributed to the growth of the RIA market. Governments and private entities alike are investing heavily in diagnostic technologies, aiming to enhance the early detection and treatment of diseases. For instance, the U.S. National Institutes of Health (NIH) has funded numerous projects to advance RIA technology. This trend is particularly evident in emerging economies where improving healthcare infrastructure has become a priority. The emphasis on precision medicine and patient-centered care has encouraged the adoption of RIA as a valuable tool in both public health initiatives and personalized healthcare. As funding for healthcare innovation continues to grow, the adoption of RIA for diverse diagnostic applications is expected to increase, fueling market expansion and driving competition within the diagnostic industry.
Market Trends:
Rising Demand for Automated Radioimmunoassay Systems:
Automation in radioimmunoassay (RIA) systems has emerged as a significant trend, enhancing efficiency, accuracy, and throughput in diagnostic laboratories. Automated RIA systems streamline the testing process by reducing manual intervention, which minimizes errors and improves consistency in results. With the ability to process a large volume of samples rapidly, these systems cater to the growing demand for high-throughput testing, particularly in large healthcare facilities and diagnostic laboratories. Automation also enables laboratories to cut operational costs by optimizing resources, positioning automated RIA systems as a preferred choice for healthcare providers seeking to improve diagnostic efficiency.
Shift Towards Minimally Invasive Diagnostic Techniques:
Another trend in the RIA market is the shift towards minimally invasive diagnostic procedures. Patients and healthcare providers are increasingly favoring diagnostic techniques that reduce discomfort and the risk of complications. In response, the RIA market has seen advancements in procedures that require smaller sample volumes while maintaining high sensitivity and specificity. This trend aligns with the broader healthcare industry’s focus on patient-centered care, where diagnostic methods prioritize patient comfort and safety without compromising accuracy. RIA’s continued adaptation to minimally invasive procedures has further reinforced its role in modern diagnostics, attracting broader adoption across diverse healthcare settings.
Increasing Focus on Precision Medicine:
The global emphasis on precision medicine, which tailors’ medical treatment to individual patient profiles, has significantly impacted the radioimmunoassay market. RIA’s ability to deliver precise measurements of biomarkers, hormones, and other molecules makes it an essential tool in developing personalized treatment plans. As precision medicine gains traction, RIA’s applications in identifying disease biomarkers and monitoring treatment responses have expanded. This trend has encouraged greater research and development investments in RIA technology, aiming to create even more accurate and customizable assays. With the rise of precision medicine initiatives worldwide, the demand for RIA-based testing is expected to grow, further embedding the technique in cutting-edge diagnostic practices.
Rising Adoption in Emerging Markets:
The adoption of RIA technology is increasing in emerging markets, primarily due to improvements in healthcare infrastructure and rising healthcare spending. Countries in the Asia-Pacific, Latin America, and the Middle East regions are investing in advanced diagnostic technologies to cater to their growing populations and the increasing prevalence of chronic diseases. For instance, governments and private healthcare providers are prioritizing diagnostic accuracy and efficiency, driving demand for RIA as a reliable diagnostic method. Additionally, local production of RIA kits and equipment has reduced costs and improved accessibility, making the technology more feasible for a broader range of healthcare facilities. This trend indicates substantial growth potential for the RIA market in these regions, as healthcare providers seek to expand diagnostic capabilities to meet the evolving needs of their populations.
Market Restraints and Challenges:
Regulatory Restrictions and Safety Concerns:
A significant restraint in the radioimmunoassay (RIA) market is the stringent regulatory oversight surrounding the use of radioactive materials. Regulatory bodies, including the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA), enforce strict guidelines to ensure safe handling, disposal, and usage of radioactive substances. For example, the FDA requires that all facilities handling radioactive materials must comply with specific safety protocols to prevent contamination and ensure proper waste disposal. Additionally, the handling and disposal of radioactive waste pose health and environmental risks, creating barriers to broader RIA adoption. Compliance with these regulations often requires specialized facilities, equipment, and trained personnel, increasing operational costs for healthcare providers and diagnostic laboratories.
Competition from Alternative Diagnostic Techniques:
The increasing availability of alternative diagnostic methods, such as enzyme-linked immunosorbent assay (ELISA) and chemiluminescence immunoassay (CLIA), poses a challenge for the RIA market. These alternatives offer comparable sensitivity and specificity without involving radioactive materials, making them more favorable for many healthcare providers and patients. ELISA and CLIA are also generally easier to automate, which aligns with the healthcare industry's trend toward efficiency and high-throughput testing. The growing preference for non-radioactive assays, coupled with advancements in alternative diagnostic techniques, limits RIA’s market share, especially in regions with strict radiation regulations.
High Operational Costs and Specialized Training Requirements:
Operating and maintaining RIA technology can be costly, particularly for smaller diagnostic laboratories and facilities in resource-constrained regions. The requirement for specialized personnel trained in handling radioactive substances adds to the operational complexity and expenses associated with RIA. In addition, the cost of consumables, radioactive isotopes, and waste disposal further elevates the overall expenditure, which can be prohibitive for smaller healthcare providers. These financial and operational challenges hinder the widespread adoption of RIA, limiting its growth potential, especially in emerging markets with budgetary constraints.
Market Segmentation Analysis:
By product, the market includes kits & reagents, instruments, consumables, and services. Kits & reagents hold a significant share due to their essential role in assay preparation, with further sub-segmentation into kits and antibodies. Instruments and consumables, integral to efficient testing, also contribute robustly, while services offer support in operational workflows for clinical and research settings.
By application, RIA is widely applied in oncology, cardiology, endocrinology, infectious disease, autoimmune disease, therapeutic drug monitoring, and drug abuse detection. Endocrinology leads in market share, driven by the rising need to monitor hormone levels accurately. Oncology and cardiology are also prominent, fueled by the growing prevalence of chronic diseases requiring precise diagnostics.
By end user, hospitals, specialty clinics, academic and research institutes, diagnostics laboratories, reference laboratories, cancer research institutes, and veterinary hospitals are the primary sectors employing RIA. Diagnostic laboratories account for a substantial share due to their high testing volumes, while hospitals and research institutions also play key roles, benefiting from RIA’s reliability and specificity.
By purpose, the market divides into research use only and clinical use, with clinical use dominating as RIA’s diagnostic capabilities in patient care expand.
By sample type, serum, plasma, urine, saliva, and cell culture samples are widely used. Serum and plasma samples are most common, preferred for their effectiveness in detecting specific biomarkers across multiple applications, particularly in chronic disease management.
Segmentation:
By Product:
- Kits & Reagents
- Kits
- Antibodies
- Instruments
- Consumables
- Services
By Application:
- Oncology
- Cardiology
- Endocrinology
- Infectious Disease
- Autoimmune Disease
- Therapeutic Drug Monitoring
- Drug of Abuse
- Others
By End User:
- Hospital
- Specialty Clinics
- Academic and Research Institute
- Diagnostics Laboratories
- Reference Laboratories
- Cancer Research Institutes
- Veterinary Hospitals
By Purpose:
- Research Use Only
- Clinical Use
By Sample Type:
- Serum
- Plasma
- Urine
- Saliva
- Cell Culture Sample
By Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis:
North America
North America holds the largest market share in the global radioimmunoassay (RIA) market, driven by a robust healthcare infrastructure, advanced diagnostic facilities, and high adoption rates of RIA technology in the United States and Canada. The region accounts for approximately 35% of the global market share. Extensive healthcare spending, strong support for R&D, and an increasing prevalence of chronic diseases such as cancer and cardiovascular disorders contribute significantly to RIA demand. Additionally, stringent regulatory standards in the U.S. ensure the quality and reliability of RIA, making it a trusted diagnostic tool among healthcare providers. North America’s emphasis on precision medicine and early diagnostics further bolsters RIA’s adoption across hospitals, diagnostic laboratories, and research institutes.
Europe
Europe represents the second-largest market for RIA, holding about 28% of the global share. The region benefits from a well-established healthcare system, particularly in countries like Germany, France, and the United Kingdom, where RIA is widely used in diagnostic and research applications. An increasing focus on healthcare innovation and preventive diagnostics in Europe has spurred growth in RIA demand, especially in endocrinology and oncology applications. Regulatory frameworks in Europe support advanced diagnostic methods, but the market also faces challenges due to strict radioactive material handling regulations. Nevertheless, rising healthcare investments and growing awareness of chronic diseases continue to drive the adoption of RIA technology across Europe’s healthcare facilities.
Asia-Pacific
Asia-Pacific is projected to be the fastest-growing region in the radioimmunoassay market, with an expected market share increase from around 22% currently to higher levels in the coming years. Factors such as expanding healthcare infrastructure, increasing healthcare expenditure, and a growing prevalence of chronic diseases are propelling RIA demand, particularly in countries like China, Japan, and India. Rapid urbanization and an aging population in these countries have heightened the need for precise diagnostic solutions, positioning RIA as a valuable tool in the region’s healthcare industry. Additionally, local manufacturing of RIA kits has made the technology more accessible and affordable, enhancing adoption across emerging markets. The rise in cancer and endocrine-related diseases, combined with government initiatives supporting healthcare advancements, contributes to Asia-Pacific’s growth momentum.
Latin America, Middle East, and Africa
The radioimmunoassay market in Latin America, the Middle East, and Africa collectively accounts for approximately 15% of the global market share. While these regions are relatively smaller compared to North America and Europe, they represent substantial growth potential due to improving healthcare systems and increasing demand for advanced diagnostic solutions. In Latin America, particularly in Brazil and Mexico, rising healthcare awareness and investments in diagnostics are supporting RIA adoption. The Middle East and Africa are also witnessing gradual growth as governments and private sectors invest in healthcare infrastructure. However, the market in these regions faces challenges such as limited access to advanced diagnostic facilities and restrictive regulatory policies on radioactive materials. Despite these obstacles, ongoing investments in healthcare and increasing prevalence of chronic diseases suggest future growth opportunities for RIA in these regions.
Key Player Analysis:
- ALPCO
- Beckman Coulter, Inc.
- Berthold Technologies GmbH & Co.KG
- Creative Biolabs
- DiaSorin S.p.A.
- DIAsource
- DRG INSTRUMENTS GMBH
- EUROIMMUN Medizinische Labordiagnostika AG
- IBL International GmbH
- LKB Instruments
- Merck KGaA
- Montreal Biotech
- MP BIOMEDICALS
- NovoLytiX GmbH
- Padyab Teb Co.
- PerkinElmer Inc.
Competitive Analysis:
The radioimmunoassay (RIA) market is competitive, with several prominent players vying for market share through product innovation, strategic partnerships, and geographic expansion. Key players include companies like Beckman Coulter, Siemens Healthineers, and PerkinElmer, which leverage strong R&D capabilities to develop highly sensitive and specific assays that meet diverse diagnostic needs. These companies invest in automation to enhance testing efficiency, catering to the growing demand for high-throughput systems in diagnostic laboratories. Smaller, specialized companies also compete by focusing on niche applications within oncology, endocrinology, and infectious disease. Additionally, many companies pursue strategic collaborations with hospitals, research institutes, and government bodies to strengthen their market presence. As RIA technology faces competition from non-radioactive alternatives, these companies aim to maintain relevance by improving product accessibility and addressing regulatory compliance, especially in emerging markets where RIA adoption is accelerating.
Recent Developments:
- In May 2023, EUROIMMUN obtained an in vitro diagnostic regulatory (IVDR) certificate, enabling the company to transition products in higher IVD risk classes B and C to the new IVDR framework. This certification also allows EUROIMMUN to market new products within these categories as IVDR-compliant, bolstering customer confidence in its products and kits.
- In July 2022, Svar Life Science entered a strategic agreement with DIAsource ImmunoAssays to transfer ownership of the Chromogranin a Neolisa™ (ELISA) product and its portfolio of radioimmunoassays (RIA) to DIAsource.
Market Concentration & Characteristics:
The radioimmunoassay (RIA) market is moderately concentrated, with several key players dominating due to high barriers to entry, including stringent regulatory requirements and specialized technical expertise needed for RIA development and radioactive material handling. Major companies like Siemens Healthineers, Beckman Coulter, and PerkinElmer command a substantial market share, supported by robust R&D investments and extensive product portfolios that address diverse diagnostic needs. RIA market characteristics include a strong focus on product accuracy, specificity, and sensitivity, making it valuable in applications such as oncology, endocrinology, and therapeutic drug monitoring. Companies in this space prioritize compliance with global regulations, including IVDR in Europe, to meet safety standards and sustain market credibility. Additionally, as automation gains traction, RIA products are increasingly optimized for high-throughput testing environments, allowing providers to process large sample volumes efficiently, thereby meeting the growing demand for rapid, reliable diagnostics.
Report Coverage:
The research report offers an in-depth analysis based on By Product, By Application, By End User, By Purpose and By Sample Type. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising prevalence of chronic diseases, particularly cancer and hormonal disorders, will drive demand for accurate RIA diagnostics.
- Advancements in automation will enable higher throughput, making RIA more accessible in high-demand clinical settings.
- Growing adoption in emerging markets will expand the market as healthcare infrastructure strengthens in Asia-Pacific, Latin America, and Africa.
- Increasing regulatory compliance, such as IVDR in Europe, will enhance product reliability and customer confidence.
- Shifts toward minimally invasive procedures will favor RIA as it adapts to more patient-friendly diagnostic approaches.
- Precision medicine initiatives will boost demand for RIA due to its specificity in personalized treatment and monitoring.
- Technological innovations, including miniaturization and faster assay times, will improve efficiency and broaden RIA applications.
- Partnerships and acquisitions among key players will stimulate growth, bringing new technologies and products to market.
- Investment in healthcare research will continue to expand RIA’s use in both clinical and academic research.
- Increasing competition from non-radioactive alternatives will push RIA providers to innovate and maintain market relevance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Radioimmunoassay market?
What drives the growth of the RIA market?
Which region has the largest share in the RIA market?
What challenges does the RIA market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Radioimmunoassay Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Radioimmunoassay Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 563.64 million → 2032: USD 749.11 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Radioimmunoassay Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Radioimmunoassay Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Radioimmunoassay Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Radioimmunoassay Market Drivers
- 3.3 Radioimmunoassay Market Restraints & Challenges
- 3.4 Radioimmunoassay Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Radioimmunoassay Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Radioimmunoassay Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Radioimmunoassay category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Radioimmunoassay Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Radioimmunoassay Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Radioimmunoassay market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Radioimmunoassay Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Radioimmunoassay Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Radioimmunoassay Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Radioimmunoassay (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Radioimmunoassay Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Radioimmunoassay Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Radioimmunoassay Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Radioimmunoassay Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Radioimmunoassay Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Radioimmunoassay Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Radioimmunoassay Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Radioimmunoassay Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Radioimmunoassay Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
