
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
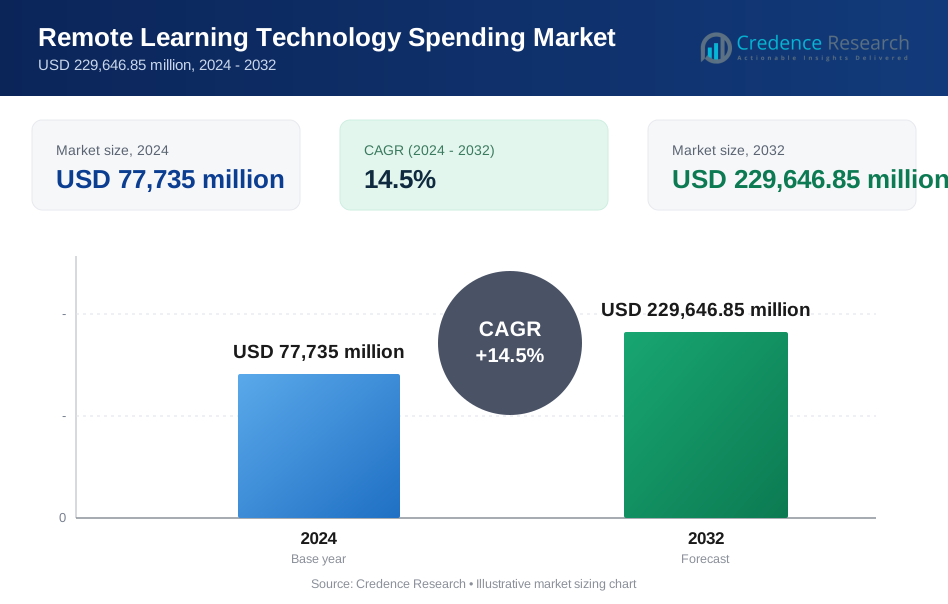
| Remote Learning Technology Spending market Size 2024 | USD 77,735 million |
| Remote Learning Technology Spending market, CAGR | 14.5% |
| Remote Learning Technology Spending market Size 2032 | USD 229,646.85 million |
Market Overview
The Remote Learning Technology Spending market is projected to grow from USD 77,735 million in 2024 to USD 229,646.85 million by 2032, with a compound annual growth rate (CAGR) of 14.5% during the forecast period (2024-2032).
The Remote Learning Technology Spending market is driven by several key factors, including the growing demand for flexible, accessible learning solutions across the globe. Increased adoption of e-learning platforms by educational institutions, corporate training programs, and government initiatives is fueling market growth. The rise of digital classrooms, online certifications, and the integration of Artificial Intelligence (AI) and Virtual Reality (VR) into educational content are key trends reshaping the industry. Additionally, the COVID-19 pandemic accelerated the need for remote learning solutions, solidifying their place in the education sector. Another significant trend is the development of advanced learning management systems (LMS) and collaborative tools, enhancing the overall user experience. The shift toward personalized, data-driven learning is also a prominent factor, enabling more effective educational outcomes. As organizations increasingly focus on upskilling and reskilling, the demand for scalable and adaptable remote learning technologies is expected to continue rising, driving market expansion.
The Remote Learning Technology Spending market exhibits significant regional variation, with North America leading the market share due to its advanced technological infrastructure and high adoption of e-learning solutions. Asia Pacific, however, is the fastest-growing region, driven by increasing internet penetration and government initiatives to enhance digital education. Key players in this market include industry leaders such as Udacity, Coursera, Zoom Video Communications, Microsoft Education, and LinkedIn Learning, who provide diverse solutions ranging from learning management systems (LMS) to video conferencing and content creation platforms. These companies are leveraging cutting-edge technologies, including AI, VR, and cloud-based solutions, to cater to the growing demand for remote education. As the market evolves, these players are expected to maintain a dominant presence, driving innovation and expanding market reach globally.
Market Drivers:
Growing Adoption of E-Learning Platforms:
The increasing preference for e-learning platforms is a major driver of growth in the Remote Learning Technology Spending market. Educational institutions, organizations, and individuals are increasingly turning to online education as it offers flexibility, convenience, and a broader range of learning opportunities. E-learning platforms allow learners to access a variety of courses, certifications, and skill development programs, driving the demand for advanced technology solutions. For instance, a survey by the International Association for K-12 Online Learning (iNACOL) highlighted that the flexibility and accessibility of e-learning platforms have significantly increased student engagement and satisfaction. This trend is further supported by the rising acceptance of digital learning models in both traditional educational systems and corporate training environments.
Technological Advancements in Educational Tools:
Innovations in learning technologies, such as Artificial Intelligence (AI), Virtual Reality (VR), and Augmented Reality (AR), are significantly enhancing the remote learning experience. These tools create immersive and interactive learning environments, improving engagement and retention rates among learners. AI-based solutions provide personalized learning paths, adapting content to the needs of individual students, while VR and AR offer hands-on experiences that simulate real-world scenarios. For instance, a report by the World Economic Forum indicated that the integration of AI and VR in educational tools has significantly improved learning outcomes and student engagement. The integration of these technologies is boosting demand for sophisticated remote learning platforms, thereby driving market spending.
Increased Focus on Upskilling and Reskilling:
As industries continue to evolve, there is a growing need for upskilling and reskilling the workforce to meet new challenges and demands. Remote learning technologies are increasingly seen as an effective way to provide continuous professional development. Organizations are investing in these solutions to deliver training programs that enhance employee skills and productivity. For instance, a survey by the Global Labor Market Conference (GLMC) found that 70% of Indian professionals are actively seeking opportunities to upskill through remote learning platforms. This shift towards remote learning for workforce development is a significant driver of market growth, as businesses aim to maintain competitive advantage in an ever-changing labor market.
Impact of the COVID-19 Pandemic:
The COVID-19 pandemic accelerated the adoption of remote learning technologies across the globe. With schools, universities, and businesses transitioning to online platforms to ensure continuity, the pandemic highlighted the importance of remote learning infrastructure. As a result, educational institutions and organizations invested heavily in technology to adapt to this new learning model. For instance, a report by the World Bank emphasized that the rapid shift to remote learning during the pandemic has significantly increased the adoption of digital learning tools and platforms. This surge in demand for remote learning solutions during the pandemic has laid the foundation for sustained growth in the market, with long-term shifts toward hybrid learning models continuing to influence spending trends.
Market Trends:
Integration of Artificial Intelligence (AI) and Automation:
A prominent trend in the Remote Learning Technology Spending market is the integration of Artificial Intelligence (AI) and automation tools. AI-driven platforms are increasingly being used to create personalized learning experiences, adapting content to the needs of individual learners. These technologies provide data-driven insights that enhance decision-making and improve student outcomes. Additionally, automation in administrative tasks such as grading, content delivery, and feedback allows educators to focus more on instructional quality. For instance, a report by the U.S. Department of Education highlighted that AI-driven platforms have significantly improved student engagement and learning outcomes by providing personalized learning paths. This trend is leading to more efficient, scalable, and adaptive learning environments.
Rise of Hybrid and Blended Learning Models:
The shift towards hybrid and blended learning models is another significant trend shaping the remote learning landscape. These models combine in-person and online education, allowing learners to access content remotely while still benefiting from face-to-face interactions when necessary. The flexibility of hybrid learning caters to diverse learning preferences and schedules, making education more accessible to a global audience. For instance, a study by the University of Zambia found that hybrid learning models have significantly increased student engagement and flexibility in learning. As educational institutions and businesses increasingly adopt these models, demand for robust, adaptable remote learning technologies continues to rise, further driving market growth.
Expansion of Mobile Learning Solutions:
Mobile learning, or mLearning, is gaining traction as more users turn to smartphones and tablets for educational purposes. This trend is fueling the development of mobile-optimized learning platforms and apps that enable learners to access content anytime, anywhere. The rise in mobile learning aligns with the global increase in mobile device usage and the growing demand for flexible learning solutions. For instance, a report by Course Method indicated that mobile learning has significantly increased user engagement and productivity. As remote learning technologies continue to evolve, mobile solutions are expected to play an even more prominent role, expanding the market's reach.
Increased Focus on Data Security and Privacy:
As remote learning platforms handle sensitive data, the focus on data security and privacy is becoming increasingly important. Educational institutions and organizations are prioritizing the implementation of secure systems to protect learner data and ensure compliance with regulations such as GDPR. This trend is prompting investments in secure remote learning technologies, driving innovation in cybersecurity solutions within the market. For instance, a study by the Ponemon Institute found that the average cost of a data breach in the education sector is significant, highlighting the need for robust data security measures. As data privacy concerns continue to grow, secure learning environments will become a critical factor in the market's evolution.
Market Challenges Analysis:
Technological Infrastructure and Accessibility Issues:
One of the significant challenges facing the Remote Learning Technology Spending market is the disparity in technological infrastructure and accessibility. While remote learning solutions are gaining momentum globally, many regions, especially in developing countries and rural areas, still face substantial barriers. Issues such as unreliable internet connectivity, insufficient hardware, and a lack of digital literacy can severely limit access to effective remote learning. These challenges create a digital divide, preventing large sections of the population from benefiting fully from the advantages of online education. Additionally, varying levels of technological readiness across educational institutions and organizations further exacerbate the issue, slowing the widespread adoption of remote learning technologies. To overcome this barrier, investments in robust infrastructure, affordable internet connectivity, and user-friendly digital tools are essential. Governments, educational bodies, and businesses must work collaboratively to ensure that the benefits of remote learning technologies reach all students, regardless of their geographical or socio-economic status. Without these efforts, the market's growth potential could be hindered by accessibility and equity challenges.
Resistance to Change and Integration Issues:
Another key challenge impacting the Remote Learning Technology Spending market is the resistance to change from traditional educational institutions and businesses. Many schools, universities, and corporations remain hesitant to fully embrace remote learning solutions due to concerns over the effectiveness of digital education, the perceived loss of face-to-face interactions, and the steep learning curve associated with adopting new technologies. For some, the shift to online learning may be seen as a threat to established teaching methods and established pedagogical practices. Moreover, integrating new remote learning platforms with existing legacy systems can be a complex and costly process, particularly for organizations with entrenched infrastructures. This challenge is compounded by the need for ongoing professional development to train educators and staff on how to use these platforms effectively. Additionally, there is often resistance from both educators and learners who may be less comfortable with technology or have limited experience with digital learning environments. These factors can delay the adoption of remote learning technologies and limit the growth of the market. To address these challenges, organizations must prioritize change management strategies, provide comprehensive training programs, and ensure seamless integration with existing systems to facilitate smoother transitions to remote learning environments.
Market Segmentation Analysis:
By Mode
The Remote Learning Technology Spending market is divided into two primary modes: synchronous and asynchronous learning. Synchronous learning involves real-time interaction between instructors and students, typically through live video sessions, webinars, or virtual classrooms. This mode is prevalent in formal education settings such as schools and universities, as well as in corporate training programs where immediate feedback and engagement are crucial. Asynchronous learning, however, allows students to access content at their own pace and time, making it ideal for adult learners and professionals with busy schedules. Asynchronous learning platforms often include pre-recorded lectures, quizzes, and discussion boards. The demand for flexible learning environments is increasing the adoption of asynchronous learning solutions, while synchronous learning remains dominant in environments that require structured interaction. Both modes are key to the growth of remote learning technologies, catering to different learning preferences and needs.
By Solution
The Remote Learning Technology Spending market is also segmented by solution, which includes hardware, software, and services. Hardware solutions consist of devices like laptops, tablets, and smartphones, which are essential for accessing remote learning platforms. As the demand for online learning grows, so does the need for affordable and high-performance devices. Software solutions include Learning Management Systems (LMS), virtual classrooms, and collaboration tools that facilitate content delivery, interaction, and assessments. These platforms enable both synchronous and asynchronous learning, enhancing the overall learning experience. Additionally, services such as cloud-based storage, technical support, and consulting ensure that these systems run smoothly and are scalable to accommodate growing user bases. The combination of hardware, software, and services contributes to the comprehensive ecosystem of remote learning, supporting its expansion across education and corporate sectors.
Segments:
Based on Mode:
- Collaborative Learning
- Self-Paced Learning
- Social Learning
- Instructor-Led Training & Learning
- Simulation Learning
- Others
Based on Solution:
- Services
- Software
- By End-User
- Academic Institutes
- Government Organizations
- Corporate Professionals
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share in the Remote Learning Technology Spending market, accounting for approximately 40% of the global market. This is primarily driven by the United States and Canada, where high levels of technological infrastructure, internet penetration, and digital literacy support the rapid adoption of remote learning solutions. The shift towards digital education accelerated by the COVID-19 pandemic has led to sustained demand for virtual classrooms, learning management systems, and other digital tools in both educational institutions and corporate training environments. In addition to the educational sector, North American companies are investing heavily in upskilling and reskilling initiatives through online platforms, further driving market growth. As North America continues to invest in educational technologies and innovations in remote learning solutions, the region is expected to maintain its dominant position, with a projected market share of 40% through the forecast period.
Asia Pacific
Asia Pacific is the fastest-growing region in the Remote Learning Technology Spending market, with a projected growth rate that could lead it to capture 30% of the global market share by 2032. This growth is driven by countries such as China, India, Japan, and South Korea, where digital education initiatives and online learning platforms are rapidly gaining popularity. Government efforts to expand internet access, especially in rural areas, combined with increasing mobile device adoption, are fueling this growth. The growing demand for flexible learning solutions, particularly among students and working professionals seeking online certifications and skill development, further supports the market expansion. In the corporate sector, companies are also investing in remote learning technologies to enhance employee training and development. With a large, young, and tech-savvy population, Asia Pacific is well-positioned to challenge North America's dominance, potentially capturing a significant share of the market in the coming years.
Key Player Analysis:
- Khan Academy
- Moodle
- Microsoft Education
- LinkedIn Learning
- Canvas by Instructure
- Zoom Video Communications
- Blackboard
- Adobe Captivate
- Coursera
- D2L (Desire2Learn)
Competitive Analysis:
The Remote Learning Technology Spending market is highly competitive, with numerous companies vying for dominance across various segments such as e-learning platforms, virtual classrooms, and learning management systems. Leading players like Coursera, Zoom Video Communications, Microsoft Education, and LinkedIn Learning continue to innovate, offering diverse solutions tailored to educational institutions and corporate clients. These companies are investing heavily in advanced technologies such as artificial intelligence, cloud-based tools, and immersive learning experiences to enhance user engagement and learning outcomes. For instance, a report by the U.S. Department of Education highlighted that AI-driven platforms have significantly improved student engagement and learning outcomes by providing personalized learning paths. Competitive strategies include expanding partnerships, offering personalized learning experiences, and integrating new tools like VR and AR into training programs. While established players benefit from strong brand recognition and large customer bases, smaller niche players are carving out spaces with specialized offerings. Overall, the market is expected to become more fragmented, with companies competing on technological advancements, user experience, and scalability.
Recent Developments:
- In September 2024, SMART Technologies launched the SMART Board MX Series and SMART Board GX Series interactive displays, aimed at enhancing education in India.
- In February 2024, Mr. Dharmendra Pradhan, the Minister of Education and Minister of Skill Development and Entrepreneurship of India, launched a partnership between the National Skill Development Corporation (NSDC) and TeamLease EdTech. This collaboration aims to enhance employability through skill development, with a particular emphasis on promoting work-integrated degree programs.
- In November 2023, Stones2Milestones, an Indian EdTech platform, partnered with Finnish Global Education Solutions Oy to incorporate the Finnish education model into Indian schools. The partnership focuses on improving numeracy and literacy, providing teacher professional development, and creating advanced technological solutions for global use.
- In April 2023, Echo360 introduced new EdTech SaaS platforms, including EchoPollTM for interactive polling, EchoVideoTM with enhanced editing tools and accessibility features, and ExamViewTM with advanced assessment capabilities. These innovations are designed to improve student engagement, accessibility, and streamline workflows, further solidifying Echo360's leadership in the EdTech sector.
Market Concentration & Characteristics:
The Remote Learning Technology Spending market exhibits a moderate to high level of concentration, with a few large players holding significant market share while a number of smaller, niche companies cater to specific needs. The market is characterized by rapid technological advancements, as leading companies continuously innovate to offer advanced features like artificial intelligence, virtual reality, and adaptive learning systems. Key players focus on enhancing user experience, scalability, and accessibility to meet the growing demand for flexible, remote learning solutions across educational institutions and businesses. As the market evolves, there is an increasing trend towards partnerships, acquisitions, and collaborations, which allow companies to expand their reach and enhance their offerings. Despite the dominance of established players, the presence of numerous smaller competitors fosters a dynamic and competitive environment, ensuring constant innovation and providing diverse solutions to cater to different segments of learners and industries.
Report Coverage:
The research report offers an in-depth analysis based on Mode, Solution and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Remote Learning Technology Spending market is expected to experience significant growth, driven by increasing demand for flexible learning solutions.
- Adoption of AI-driven personalized learning platforms will continue to rise, enhancing student engagement and learning outcomes.
- The integration of virtual reality (VR) and augmented reality (AR) technologies will become more prominent, creating immersive learning experiences.
- Cloud-based learning management systems (LMS) will see widespread adoption, enabling seamless access to learning materials and collaboration.
- Mobile learning solutions will expand, as more learners rely on smartphones and tablets for educational purposes.
- Corporate training and upskilling initiatives will increasingly leverage remote learning platforms to meet evolving workforce demands.
- The shift towards hybrid learning models, combining in-person and online education, will continue to drive market growth.
- Governments and educational institutions will increase investments in digital education infrastructure to support remote learning.
- Security and data privacy concerns will prompt further advancements in cybersecurity measures within remote learning technologies.
- The market will become more competitive, with both large and niche players innovating to meet diverse educational and training needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Remote Learning Technology Spending market?
What factors are driving the growth of the Remote Learning Technology Spending market?
What are the key segments within the Remote Learning Technology Spending market?
Who are the major players in the Remote Learning Technology Spending market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Remote Learning Technology Spending Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Remote Learning Technology Spending Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 77,735 million → 2032: USD 229,646.85 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Remote Learning Technology Spending Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Remote Learning Technology Spending Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Remote Learning Technology Spending Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Remote Learning Technology Spending Market Drivers
- 3.3 Remote Learning Technology Spending Market Restraints & Challenges
- 3.4 Remote Learning Technology Spending Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Remote Learning Technology Spending Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Remote Learning Technology Spending Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Remote Learning Technology Spending category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Remote Learning Technology Spending Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Remote Learning Technology Spending Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Remote Learning Technology Spending market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Remote Learning Technology Spending Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Remote Learning Technology Spending Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Remote Learning Technology Spending Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Remote Learning Technology Spending (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Remote Learning Technology Spending Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Remote Learning Technology Spending Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Remote Learning Technology Spending Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Remote Learning Technology Spending Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Remote Learning Technology Spending Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Remote Learning Technology Spending Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Remote Learning Technology Spending Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Remote Learning Technology Spending Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Remote Learning Technology Spending Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
