
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Industrial Wireless Remote Control Market Size 2024 | USD 610 Million |
| Industrial Wireless Remote Control Market, CAGR | 5.6% |
| Industrial Wireless Remote Control Market Size 2032 | USD 943.28 Million |
Market Overview:
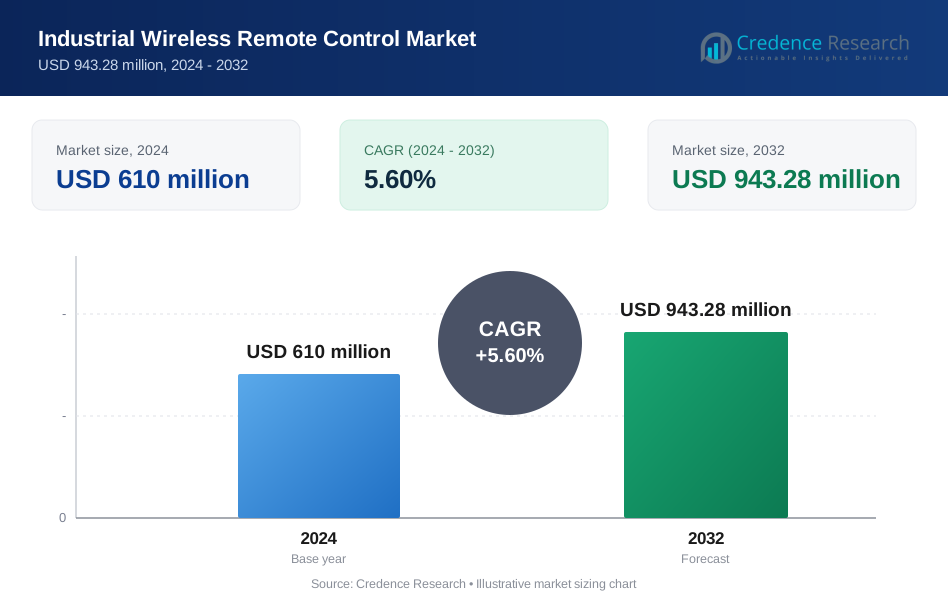
Industrial Wireless Remote Control Market size was valued at USD 610 million in 2024 and is anticipated to reach USD 943.28 million by 2032, at a CAGR of 5.6% during the forecast period (2024-2032).
One of the primary drivers of market growth is the increasing adoption of automation and remote-control solutions in industrial environments. Industries are prioritizing remote access and control to reduce workplace hazards, particularly in high-risk settings like construction sites and oil & gas facilities. The demand for wireless solutions is also driven by the growing focus on improving productivity through enhanced machine mobility and faster response times. Additionally, integration with IoT and smart industrial systems is transforming wireless remote-control devices into intelligent tools capable of real-time monitoring, diagnostics, and data-driven decision-making, further strengthening their adoption across sectors. The expanding use of wireless HMI (Human-Machine Interface) and sensor-based systems is also boosting innovation in product functionality. Moreover, the growing prevalence of Industry 4.0 initiatives is expected to drive widespread implementation across smart factories.
Regionally, North America leads the industrial wireless remote-control market due to early technological adoption and high investments in industrial automation. The presence of established players and increasing use of wireless control in sectors like manufacturing, mining, and energy contribute to regional dominance. Europe follows closely, supported by stringent safety regulations and rising demand for automation in industries such as automotive and chemicals. Government-backed digitalization initiatives and worker safety mandates are further pushing adoption across European nations. Meanwhile, the Asia-Pacific region is expected to witness the fastest growth, driven by rapid industrialization, infrastructure development, and expanding manufacturing activities in countries like China, India, and South Korea. The growing adoption of smart logistics and warehousing in the region is also expected to create new opportunities for wireless remote-control systems.
Market Insights:
- The global market size was valued at USD 610 million in 2024 and is anticipated to reach USD 943.28 million by 2032, growing at a CAGR of 5.6% during the forecast period (2024–2032).
- Increasing adoption of automation and remote-control solutions in industrial environments is a primary driver, enhancing operational efficiency and reducing workplace hazards.
- Integration with IoT and smart industrial systems is transforming wireless remote-control devices into intelligent tools capable of real-time monitoring, diagnostics, and data-driven decision-making.
- Technological advancements in wireless communication protocols, such as Bluetooth Low Energy (BLE), Zigbee, and 5G, are improving system performance and ensuring better energy efficiency and device interoperability.
- The market is experiencing growth in North America, where early adoption of automation and robust investments in industrial technology are fueling market demand.
- The Asia-Pacific region is expected to see the fastest growth in the industrial wireless remote control market, driven by rapid industrialization, government initiatives, and increasing manufacturing activities in countries like China, India, and South Korea.
- The expanding use of wireless Human-Machine Interface (HMI) and sensor-based systems is boosting innovation in product functionality, further strengthening their adoption across sectors.
Market Drivers:
Rising Demand for Industrial Automation:
The growing implementation of automation across industrial sectors is a major driver of the industrial wireless remote-control market. Industries are increasingly relying on remote control systems to enhance operational efficiency, minimize manual intervention, and ensure worker safety. Wireless remote controls allow operators to manage equipment from a distance, which is especially valuable in hazardous environments such as mining, oil and gas, and heavy machinery operations. As companies pursue lean manufacturing and smart factory initiatives, wireless systems are becoming integral to optimizing workflows and maintaining consistent production cycles.
Advancements in Wireless Communication Technologies:
Technological advancements in wireless communication protocols have significantly improved the reliability and responsiveness of industrial remote controls. For instance, Mitsubishi Heavy Industries has introduced a new wireless control system that leverages Bluetooth Low Energy (BLE) and 5G connectivity to enhance both safety and ease of use in demanding industrial settings. Enhanced signal strength, secure data transmission, and reduced latency have made these systems more suitable for mission-critical operations. Innovations such as Bluetooth Low Energy (BLE), Zigbee, and radio frequency (RF) technologies have broadened application possibilities while ensuring better energy efficiency and device interoperability. As a result, industries are adopting wireless remote controls not only for basic equipment operation but also for integration with real-time monitoring systems.
Focus on Worker Safety and Risk Reduction:
Worker safety remains a top priority in industrial environments, and wireless remote control systems contribute directly to minimizing occupational hazards. For instance, a study by the National Safety Council found that implementing radio remote control systems in high-risk environments, such as construction sites, led to a significant reduction in operator-related accidents, as crane operators could control equipment from ground level with a clear view of operations rather than from elevated or hazardous positions. These systems enable operators to control machinery from a safe distance, thereby reducing the risk of injuries in high-risk areas like construction zones or manufacturing lines. By keeping personnel away from dangerous operating zones, companies can comply with stringent safety regulations while enhancing workforce productivity. In industries where precision and rapid response are critical, remote controls offer greater reliability and help reduce human error.
Integration with IoT and Smart Systems:
The integration of wireless remote controls with IoT-enabled devices is expanding their functionality and market demand. Smart remote systems now offer advanced features such as data tracking, predictive maintenance alerts, and remote diagnostics. This connectivity allows seamless communication between equipment and centralized control systems, creating a more synchronized and intelligent operational environment. As Industry 4.0 adoption grows, the demand for wireless control solutions capable of supporting digital transformation and process automation continues to rise.
Market Trends:
Adoption of Industry 4.0 Technologies:
The integration of Industry 4.0 technologies is a key trend shaping the industrial wireless remote-control market. Companies are incorporating wireless controls into smart factory systems, enabling seamless interaction between machines, operators, and control centers. These systems allow real-time data exchange, enhancing decision-making and productivity. As factories become more connected and intelligent, demand for advanced wireless remote controls with IoT capabilities is steadily rising.
Increased Focus on Ergonomic and User-Friendly Designs:
Manufacturers are increasingly prioritizing user-centric designs in wireless remote-control devices. For instance, Tele Radio has developed remote controls with ergonomically contoured grips and customizable button layouts, allowing operators to work intuitively and comfortably for extended periods in industrial settings. There is a growing demand for compact, lightweight, and ergonomically designed remotes that enhance ease of use in challenging industrial environments. Features such as programmable buttons, haptic feedback, and customizable interfaces are gaining popularity, as they help improve operator comfort and reduce fatigue during extended use. This trend is contributing to greater adoption across sectors requiring precision and long-term handling.
Rising Integration with Safety and Compliance Systems:
Another significant trend involves the integration of wireless remote controls with safety and compliance mechanisms. Remote control devices now come with advanced safety features, including emergency stop functions, overload protection, and secure communication protocols. For instance, Microtronics LLC designs wireless remote controls with ergonomic designs, machine-stop switches, and push-to-operate buttons that enhance safety by minimizing human error and ensuring secure operations. These enhancements ensure safer operation of heavy equipment and help businesses comply with regulatory standards. As industries increasingly emphasize workplace safety, the demand for remote systems that align with safety certifications is growing.
Growth in Emerging Markets and Modular Solutions:
Emerging economies are witnessing a surge in demand for wireless remote-control systems due to rapid industrialization and infrastructure development. In response, manufacturers are offering modular and scalable solutions that cater to varying operational needs and budgets. These flexible systems allow businesses to gradually upgrade their control technologies without significant capital expenditure, supporting widespread adoption across small and medium enterprises in developing regions.
Market Challenges Analysis:
Interference and Connectivity Limitations:
One of the primary challenges in the industrial wireless remote-control market is the risk of signal interference and connectivity limitations in harsh operational environments. Industrial facilities often contain dense machinery, metal structures, and electromagnetic fields that can disrupt wireless signals. For instance, NEC’s deployment of its “wireless ExpEther” networking technology in factory environments demonstrates how advanced rateless coding can maintain stable wireless connections between computers and I/O devices, even when radio waves are reflected or attenuated by metallic objects. Such interference can lead to communication delays, operational errors, or even equipment failure, compromising safety and productivity. Ensuring reliable performance in challenging settings requires advanced frequency management and robust communication protocols, which can increase system complexity and costs. Furthermore, the need for consistent connectivity across large or multi-site facilities presents technical hurdles, especially in sectors such as mining and construction where remote areas may lack network infrastructure.
High Initial Investment and Integration Complexity:
Despite their long-term benefits, wireless remote-control systems often require significant upfront investment, particularly for advanced, feature-rich models integrated with IoT or automation technologies. Small and medium-sized enterprises may find it difficult to justify the initial costs, including installation, training, and system customization. Additionally, integrating wireless systems with existing infrastructure and legacy equipment poses technical and operational challenges. Compatibility issues and the lack of standardized protocols across devices can hinder seamless implementation, leading to increased downtime and maintenance efforts. As industries push towards digital transformation, overcoming these integration barriers becomes crucial for widespread adoption and sustained growth of wireless remote-control technologies.
Market Opportunities:
The industrial wireless remote-control market presents significant opportunities driven by the rapid advancement of smart manufacturing and digital transformation initiatives. As industries increasingly adopt Industry 4.0 practices, there is growing demand for wireless systems that support real-time data exchange, remote diagnostics, and predictive maintenance. This trend opens up opportunities for manufacturers to develop next-generation remote control devices equipped with IoT connectivity, cloud integration, and analytics capabilities. The need for flexible, user-friendly, and energy-efficient systems is encouraging innovation in both hardware and software design. Additionally, the rise of autonomous operations and robotics in sectors such as logistics, mining, and utilities offers vast potential for the integration of advanced wireless remote-control solutions.
Emerging markets, particularly in Asia-Pacific, Latin America, and the Middle East, offer untapped growth potential due to ongoing industrialization, infrastructure expansion, and increasing investments in automation technologies. Governments in these regions are promoting smart industry initiatives, creating favorable conditions for the adoption of wireless remote controls across sectors like construction, manufacturing, and oil & gas. Furthermore, the increasing focus on workplace safety and productivity optimization is pushing companies to replace traditional wired systems with wireless alternatives. With the evolution of wireless protocols and the rollout of 5G networks, remote control systems can achieve higher reliability and broader coverage, making them more suitable for large-scale and remote operations. As a result, there is ample room for solution providers to expand their market presence by offering scalable, cost-effective, and regulatory-compliant remote-control systems tailored to regional needs.
Market Segmentation Analysis:
By Types
The industrial wireless remote-control market can be segmented based on the types of remote-control systems available. These include handheld remote controls, joystick-based remote controls, and panel-mounted remote controls. Handheld remote controls hold the largest market share due to their portability and ease of use across various industrial settings. Joystick-based systems are gaining traction in industries that require precise and responsive control, such as construction and material handling. Panel-mounted remote controls are typically used in more stationary environments and are favored for operations that require centralized control of multiple systems. Each type offers unique benefits, catering to different operational needs and preferences across sectors.
By Application
The industrial wireless remote-control market is also segmented based on application across several industries. Key applications include manufacturing, oil and gas, mining, construction, and logistics. In manufacturing, remote control systems are used to optimize machinery operations and ensure safer working conditions. The oil and gas industry utilizes wireless remote controls for equipment in hazardous environments, reducing the risk of operator exposure to dangerous conditions. Mining applications require robust, long-range wireless systems to manage equipment from a safe distance. Similarly, in construction and logistics, these systems facilitate better material handling, equipment management, and overall operational efficiency. Each application drives the adoption of wireless remote controls to meet specific industry requirements for safety, productivity, and remote access.
Segmentations:
By Types:- Handheld Remote Controls
- Joystick-based Remote Controls
- Panel-mounted Remote Controls
- Manufacturing
- Oil and Gas
- Mining
- Construction
- Logistics
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share, accounting for 35% of the global industrial wireless remote-control market. The region benefits from a highly developed industrial infrastructure and rapid adoption of automation technologies across sectors such as manufacturing, oil and gas, and mining. The strong presence of key industry players, combined with substantial investment in research and development, is driving continuous innovation in wireless control systems. Strict regulatory standards on workplace safety and operational efficiency are further accelerating the deployment of wireless remote controls. Moreover, widespread access to advanced communication networks and digital platforms supports the seamless integration of wireless technologies in industrial operations.
Europe
Europe captures 29% of the global market share, supported by its well-established industrial base and stringent regulatory frameworks focused on safety and sustainability. Countries such as Germany, France, and the United Kingdom are at the forefront of integrating wireless remote-control systems with automation and robotics in manufacturing processes. The push toward energy-efficient operations and smart manufacturing, driven by initiatives like Industry 5.0 and the European Green Deal, is boosting the adoption of intelligent remote systems. Additionally, European firms are increasingly investing in wireless technologies that align with environmental compliance and worker protection standards, further strengthening market penetration across the region.
Asia-Pacific
Asia-Pacific accounts for 24% of the global industrial wireless remote-control market and is projected to experience the fastest growth rate in the coming years. The region's expanding industrial sector, particularly in China, India, and South Korea, is creating significant demand for cost-effective and scalable wireless control solutions. Government-led initiatives promoting digitalization, smart factories, and industrial safety are fueling widespread adoption. The growth of e-commerce, logistics, and infrastructure projects is also contributing to the increased use of wireless remote controls in material handling and automation. As technological capabilities and connectivity continue to improve, Asia-Pacific is positioned to become a key driver of global market expansion.
Key Player Analysis:
- OMNEX (Eaton) (U.S.)
- Danfoss (Ikusi) (Spain)
- Tele Radio (Sweden)
- HBC (Canada)
- Green Electric (Montana)
- Akerstroms (Denmark)
- Yuding (U.S.)
- Hetronic Group (U.S.)
- Laird (Cattron Group) (U.S.)
- NBB (Bahrain)
- Scanreco (Sweden)
- Autec (Germany)
Competitive Analysis:
The industrial wireless remote-control market is characterized by strong competition among established players and emerging manufacturers focused on innovation, product reliability, and industry-specific customization. Key companies such as Cattron, HBC-radiomatic, Tele Radio, Ikusi, and Autec dominate the market through their robust product portfolios and global distribution networks. These players emphasize R&D investments to integrate advanced technologies such as IoT connectivity, secure communication protocols, and ergonomic designs. Strategic collaborations, mergers, and acquisitions are common as companies seek to expand their geographical presence and enhance technical capabilities. New entrants and regional players are also gaining traction by offering cost-effective and modular solutions tailored to small and medium-sized enterprises. The competitive landscape continues to evolve, driven by the growing demand for wireless solutions that enhance operational efficiency, ensure worker safety, and support industrial automation. Continuous innovation and adherence to industry standards remain key differentiators in maintaining market leadership.
Recent Developments:
- In October 2024, Hetronic Group introduced the GL Series Wireless Remote, featuring modular design, extended range up to 150 meters, intelligent power management, multi-equipment control, real-time feedback, weather-resistant construction, and advanced integration capabilities. These enhancements are designed to improve productivity, safety, and operational flexibility in industrial environments.
- In January 2025, NBB expanded its product portfolio for explosion-proof safety radio remote controls, addressing the growing demand for use in hazardous areas such as gas explosion zones 1 and 2. The company also introduced a wide range of modular receiver variants, including the Compact-M, with multiple digital and serial interface options (RS232, RS485, CAN-Bus, CANopen).
- In March 2025, Tele Radio prepared to showcase its new PAQ line of handheld industrial remote controls at Bauma 2025. The SupraPAQ TH76 transmitter and R30 receiver were launched, featuring the new FieldManager™ app for streamlined device management, wireless firmware updates, and remote support. The PAQ line introduces advanced safety features, including PLe, CAT4, SIL3-certified emergency stop functions and redundant control functions for enhanced reliability.
Market Concentration & Characteristics:
The industrial wireless remote-control market exhibits a moderate to high level of market concentration, with a few leading players holding a significant share due to their established brand presence, technological expertise, and extensive distribution networks. These companies continuously invest in research and development to offer advanced, reliable, and industry-specific solutions, which strengthens their competitive advantage. The market is characterized by a strong focus on innovation, customization, and compliance with international safety standards. While established manufacturers dominate with premium offerings, smaller and regional players are increasingly entering the market by providing cost-effective and scalable solutions, particularly for small and medium-sized enterprises. The industry also displays a trend toward modular designs and integration with smart technologies such as IoT and machine learning, reflecting the evolving demands of industrial automation. Product differentiation, performance reliability, and customer service quality are key factors influencing purchasing decisions and long-term client relationships in this competitive landscape.
Report Coverage:
The research report offers an in-depth analysis based on Types, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The integration of wireless remote controls with IoT platforms will enhance real-time monitoring and predictive maintenance capabilities, leading to increased operational efficiency.
- Advancements in wireless communication technologies, such as 5G and Bluetooth Low Energy, will improve signal reliability and reduce latency, making remote operations more seamless.
- The demand for user-friendly and ergonomic remote-control designs will rise, focusing on operator comfort and reducing fatigue during prolonged use.
- Industries will increasingly adopt modular and scalable wireless control systems, allowing for easier upgrades and integration with existing infrastructure.
- The emphasis on workplace safety will drive the development of remote controls with enhanced safety features, including emergency stop functions and secure communication protocols.
- Emerging markets in Asia-Pacific, Latin America, and the Middle East will experience significant growth due to rapid industrialization and infrastructure development.
- The adoption of wireless remote controls in sectors like logistics, mining, and construction will expand, driven by the need for efficient and flexible operations.
- Collaborations between technology providers and industrial players will foster innovation, leading to the development of customized solutions tailored to specific industry needs.
- Environmental concerns will prompt the creation of energy-efficient remote-control systems, aligning with global sustainability goals.
- The competitive landscape will intensify as new entrants introduce cost-effective solutions, challenging established players to continuously innovate and maintain market share.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Industrial Wireless Remote-Control market?
What is driving the growth of the Industrial Wireless Remote-control market?
Which industries are adopting wireless remote-control systems the most?
Which region leads the Industrial Wireless Remote-Control market?
Which region is expected to witness the fastest growth in this market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Industrial Wireless Remote Control Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Industrial Wireless Remote Control Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 610 million → 2032: USD 943.28 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Industrial Wireless Remote Control Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Industrial Wireless Remote Control Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Industrial Wireless Remote Control Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Industrial Wireless Remote Control Market Drivers
- 3.3 Industrial Wireless Remote Control Market Restraints & Challenges
- 3.4 Industrial Wireless Remote Control Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Industrial Wireless Remote Control Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Industrial Wireless Remote Control Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Industrial Wireless Remote Control category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Industrial Wireless Remote Control Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Industrial Wireless Remote Control Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Industrial Wireless Remote Control market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Industrial Wireless Remote Control Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Industrial Wireless Remote Control Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Industrial Wireless Remote Control Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Industrial Wireless Remote Control (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Industrial Wireless Remote Control Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Industrial Wireless Remote Control Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Industrial Wireless Remote Control Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Industrial Wireless Remote Control Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Industrial Wireless Remote Control Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Industrial Wireless Remote Control Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Industrial Wireless Remote Control Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Industrial Wireless Remote Control Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Industrial Wireless Remote Control Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
