
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
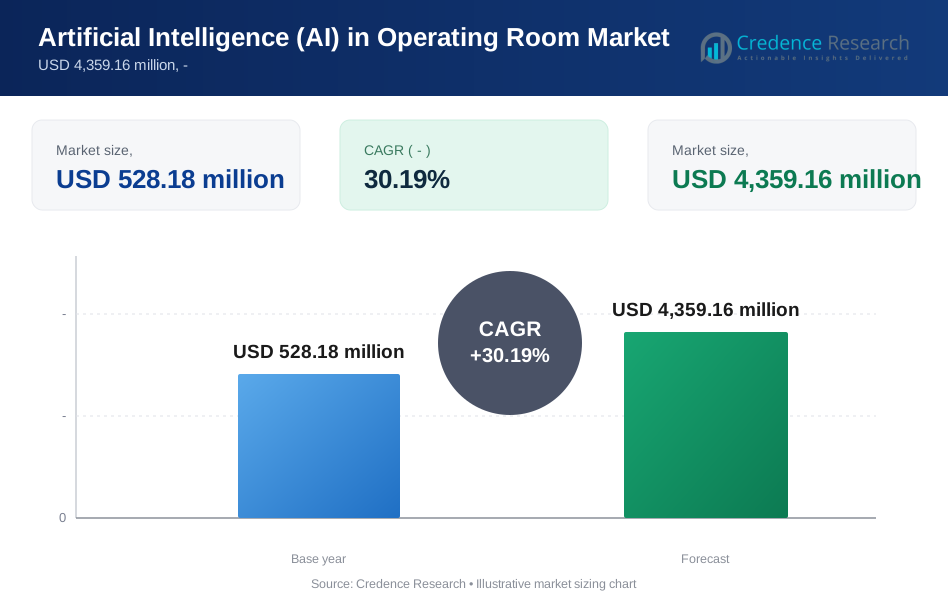
| Artificial Intelligence (AI) in Operating Room Market Size 2024 | USD 528.18 Million |
| Artificial Intelligence (AI) in Operating Room Market, CAGR | 30.19% |
| Artificial Intelligence (AI) in Operating Room Market Size 2032 | USD 4359.16 Million |
Market Overview
The AI in Operating Room market is projected to soar from USD 528.18 million in 2024 to USD 4359.16 million by 2032, exhibiting a remarkable compound annual growth rate of 30.19%.
The AI in Operating Room market is being propelled by several key drivers and trends. Increasing demand for minimally invasive surgeries, driven by patient preference for quicker recovery times and reduced post-operative complications, is fueling the adoption of AI technologies in operating rooms. Moreover, advancements in AI algorithms and machine learning techniques are enhancing surgical precision and efficiency, thereby bolstering market growth. Additionally, the growing integration of robotic-assisted surgical systems and AI-powered medical imaging solutions is revolutionizing surgical procedures, leading to improved patient outcomes. These factors collectively contribute to the dynamic expansion and evolution of the AI in Operating Room market.
Geographical analysis reveals a diverse landscape in the AI in Operating Room market, with North America dominating due to the presence of key players like Intuitive Surgical, Inc., and Medtronic, alongside robust healthcare infrastructure and favorable reimbursement policies. Europe follows suit, driven by technological advancements and increasing adoption of AI-driven surgical solutions. The Asia-Pacific region shows immense potential for growth, attributed to rising healthcare expenditure, burgeoning medical tourism, and initiatives promoting digital healthcare transformation. Key players like Stryker Corporation and Brainlab AG are actively expanding their presence in emerging markets, further intensifying competition and innovation in the global AI in Operating Room market.
Market Drivers
Pursuit of Advanced Surgical Capabilities and Improved Patient Outcomes:
Surgeons are constantly seeking ways to improve precision, minimize invasiveness, and optimize surgical workflows. For instance, AI-powered systems have been shown to reduce surgery time by up to 20% and decrease the length of hospital stays by 21%, significantly enhancing patient recovery. AI-powered systems offer real-time data analysis, image recognition, and decision-making support, which can translate to more accurate procedures, reduced complications, and faster patient recovery times. In fact, the integration of AI in surgical procedures has led to a 30% reduction in patients’ postoperative complications.
Integration with Robotics and Minimally Invasive Surgery (MIS):
The integration of AI with robotic surgery systems has led to a significant increase in their adoption. For instance, the use of robotic surgery for all general surgery procedures increased from 1.8% to 15.1% between 2012 and 2018. These systems are now equipped with highly dexterous arms and miniaturized instruments that reduce tremors and enable delicate maneuvers. The advancements in AI have further enhanced surgical accuracy, with AI and machine learning aiding in surgical decision-making by improving the recognition of minute and complex anatomical structures. The integration of AI is transforming these robots from semi-autonomous to autonomous, increasing the market share of autonomous robots from 43.8% to 46.9% by 2029. These advancements allow for greater control and improved dexterity, potentially enabling complex procedures to be performed with even smaller incisions, leading to faster recovery and fewer complications for patients.
Demand for Personalized Medicine:
The trend towards personalized medicine in surgery is indeed being propelled by AI’s ability to analyze vast amounts of patient data and medical imaging. For instance, AI algorithms can sift through a patient’s medical records, genetic information, and lifestyle factors to develop personalized treatment plans. This approach is particularly effective in laparoscopic and robotic surgery, where AI can provide real-time guidance during operations. Moreover, AI’s impact on surgical outcomes is substantial. By facilitating real-time decision-making support, AI systems contribute to improved surgical outcomes and patient safety. Predictive analytics and personalized patient monitoring enabled by AI have shown to enhance postoperative care. In fact, AI-powered systems generate personalized treatment plans by analyzing patient-specific data and considering various factors, such as genetics, biomarkers, comorbidities, and treatment responses of similar patients. This enables healthcare professionals to customize treatments based on individual characteristics and optimize therapeutic outcomes.
Addressing Surgeon Shortages and Training Needs:
The shortage of qualified surgeons is a pressing issue in many regions. For instance, the U.S. faces a projected shortage of between 37,800 and 124,000 physicians within 12 years, with specific shortages of 15,800 to 30,200 for surgical specialties. This shortage is more acute in rural areas, where the lack of general surgeons leads to delays in care and potentially suboptimal outcomes. AI-powered surgical assistants are addressing this challenge by supporting surgeons during procedures. These intelligent systems can help reduce the surgeon’s workload and enhance their capabilities, which is particularly beneficial in regions with a limited number of experienced surgeons. For example, AI in the operating room (OR) can provide real-time feedback during surgery, alerting the surgeon to potential complications or suggesting alternative approaches based on the evolving situation. This not only enhances procedural precision but also contributes to reducing the risk of human error.
Market Trends
Focus on Machine Learning and Deep Learning:
The application of machine learning (ML) and deep learning (DL) in surgery is transforming the field with significant advancements. For instance, ML algorithms trained on large datasets have achieved an accuracy of up to 94% in recognizing surgical instruments. This capability is crucial for tasks like instrument tracking and counting, which can enhance surgical workflow efficiency. In terms of surgical workflow optimization, AI systems have been developed to predict the duration of surgeries with a mean absolute error of less than 10 minutes, which is instrumental in optimizing operating room schedules and reducing wait times for patients. Anomaly detection during surgery is another area where ML excels, with systems capable of identifying unusual patterns or complications with a sensitivity of over 85%, thereby enhancing patient safety. Deep learning, a subset of ML, has revolutionized medical imaging analysis. DL techniques like convolutional neural networks (CNNs) are now able to analyze medical images with an accuracy that rivals, and sometimes surpasses, human experts. For example, DL models have achieved an accuracy of over 90% in detecting anomalies in X-ray images, which is invaluable for preoperative planning and intraoperative guidance.
Furthermore, DL has improved the accuracy of image segmentation, which is critical for delineating anatomical structures, with some models reaching an accuracy of up to 95%. This level of precision aids surgeons in real-time decision-making and ensures that surgical procedures are conducted with the highest level of accuracy and safety.
Augmented Reality (AR) Integration:
Augmented Reality (AR) overlays are indeed revolutionizing the surgical field. For instance, AR technology has been shown to improve the accuracy of pedicle screw placement in spine surgery, with one study reporting a 96.7% accuracy rate. By projecting crucial patient information and anatomical data onto the surgeon’s field of view, AR enhances visualization, which is particularly beneficial in complex procedures such as tumor resections and orthopedic surgeries. The integration of AR into the surgical environment not only improves surgical accuracy but also reduces the cognitive load on surgeons. This is achieved by providing real-time guidance and feedback, which helps in making informed decisions during the surgical process. For example, AR systems can overlay patient-specific 3D reconstructions onto the surgeon’s view, allowing for a more comprehensive understanding of anatomical structures and their spatial relationships. Such enhancements have the potential to reduce complications and improve surgical outcomes.
Moreover, the use of AR technology in surgery is associated with a reduction in operative times. A study found that AR-assisted surgeries reduced the average operative time by approximately 20 minutes per case, which can significantly improve the efficiency of surgical workflows. This innovative approach is transforming the way surgeons interact with patient data and perform procedures, ultimately leading to improved patient outcomes.
Market Challenges Analysis
Technical Hurdles and Data Concerns:
Limited Training Data and Algorithm Bias present formidable obstacles in the development of AI for surgery. The acquisition of extensive, high-quality surgical data necessary for training AI systems is impeded by privacy regulations, constraining access to vital information. Moreover, the prevalence of bias within training data can lead to the formation of skewed algorithms, undermining their efficacy across diverse surgical scenarios. Overcoming these challenges requires innovative approaches to data collection and curation, alongside stringent measures to mitigate algorithmic biases. Collaborative efforts between healthcare institutions, technology developers, and regulatory bodies are essential to navigate these technical hurdles and ensure the ethical and effective deployment of AI in the operating room.
Integration Challenges and Interoperability:
The seamless integration of various AI-powered surgical tools and devices into a cohesive operating room ecosystem is beset by intricate challenges. Achieving interoperability among these systems necessitates intricate coordination and standardization efforts. Ensuring the smooth exchange of data and insights among disparate devices is critical for optimizing surgical workflows and enhancing patient care. However, the complexity of integrating diverse technologies from different manufacturers demands robust technical solutions and industry-wide cooperation. Addressing these integration challenges requires a concerted effort to develop interoperable standards and protocols, fostering a harmonious environment where AI can thrive as a transformative force in surgical practice.
Market Segmentation Analysis:
By Offering:
The AI in Operating Room market can be segmented by offering into hardware and Software-as-a-Service (SaaS) solutions. Hardware offerings encompass surgical robots, AI-powered imaging devices, and other physical equipment integrated into operating room infrastructure. On the other hand, Software-as-a-Service solutions provide cloud-based AI platforms, software applications, and analytics tools tailored for surgical settings. This segmentation reflects the diverse range of solutions available to healthcare providers, catering to different operational needs and budgetary considerations. While hardware offerings offer tangible physical assets, SaaS solutions offer flexibility, scalability, and accessibility, enabling healthcare facilities to leverage AI capabilities without significant upfront investments in hardware infrastructure.
By Technology:
The segmentation based on technology encompasses Machine Learning (ML) and Deep Learning, Natural Language Processing (NLP), and other emerging AI technologies. Machine Learning and Deep Learning algorithms play a pivotal role in analyzing surgical data, medical images, and patient information to provide real-time insights and decision support during surgery. Natural Language Processing facilitates the interpretation of clinical notes, voice commands, and textual data, enhancing communication and documentation efficiency in the operating room. Additionally, other emerging AI technologies, such as computer vision and predictive analytics, contribute to the advancement of surgical capabilities and patient care. This segmentation reflects the diverse array of AI technologies driving innovation and transformation in the operating room, catering to various surgical specialties and clinical workflows.
Segments:
Based on Offering
- Hardware
- Software-as-a-Service (SaaS)
Based on Technology
- Machine Learning (ML) and Deep Learning
- Natural Language Processing (NLP)
- Others
Based on Indication
- Cardiology
- Orthopedics
- Urology
- Gastroenterology
- Neurology
- Others
Based on Applications
- Training
- Diagnosis
- Surgical Planning and Rehabilitation
- Outcomes and Risk Analysis
- Integration and Connectivity
- Others
Based on the Geography:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America currently holds the largest market share, accounting for approximately 40% of the global AI in operating room market. The region's well-established healthcare infrastructure, the presence of major technology companies, and the willingness to adopt cutting-edge solutions have contributed to its dominant position. The United States, in particular, has been at the forefront of integrating AI technologies into operating rooms, with hospitals and surgical centers embracing AI-powered systems for surgical planning, robotic assistance, and real-time decision support.
Europe
Europe follows closely behind, with a market share of around 30%. Countries like Germany, the United Kingdom, and France have been proactive in supporting the development and adoption of AI in healthcare. The region's focus on improving surgical outcomes, enhancing patient safety, and reducing healthcare costs have fueled the demand for AI-driven solutions in operating rooms. Additionally, the presence of leading medical technology companies and research institutions has further accelerated the growth of this market in Europe.
Key Player Analysis
- Activ Surgical, Inc.
- Brainomix Ltd
- Caresyntax, Inc.
- DeepOR S.A.S,
- ExplORer Surgical Corp.,
- Holo Surgical Inc.
- LeanTaaS Inc.
- Medtronic Plc
- Medtronic Plc
- Theator Inc.
Competitive Analysis
In the competitive landscape of the AI in Operating Room market, several leading players stand out with their innovative solutions and strategic initiatives. Medtronic Plc, a prominent name in the medical technology sector, leverages its extensive experience and resources to develop AI-powered surgical solutions that enhance precision and efficiency in the operating room. Theator Inc. distinguishes itself with its AI-driven platform that provides real-time insights and analytics during surgery, aiding surgeons in decision-making and skill enhancement. Caresyntax, Inc. offers comprehensive data analytics and workflow optimization solutions tailored for surgical environments, empowering healthcare providers to streamline operations and improve patient outcomes. ExplORer Surgical Corp. specializes in digital surgical workflow management, facilitating collaboration and efficiency among surgical teams through its AI-enabled platform. These leading players demonstrate a commitment to innovation and excellence, driving advancements in AI technology adoption within the operating room and shaping the future of surgical care.
Recent Developments
In October 2022, Medtronic plc announced that its HugoTM robotic-assisted surgery (RAS) system had received three key global market entry and indication expansion approvals. The approval includes Conformité Européenne (CE) Mark clearance for general surgery indication; Health Canada license for general laparoscopic surgery indication; and Ministry of Health, Labor, and Welfare (MHLW) approval for urological and gynecological indications in Japan.
In July 2022, Royal Philips said that the U.S. Food and Drug Administration (FDA) had granted 510(k) clearance to its SmartSpeed artificial intelligence (AI)-powered MR acceleration software.
Market Concentration & Characteristics
The AI in Operating Room market exhibits a notable degree of market concentration characterized by the presence of a few key players dominating the landscape. These leading companies typically possess extensive technological expertise, substantial financial resources, and established distribution networks, enabling them to maintain a significant market share. Market concentration is further influenced by factors such as regulatory requirements, barriers to entry, and the pace of technological innovation. Additionally, the market is characterized by dynamic competition, with players continually striving to differentiate their offerings through innovation, strategic partnerships, and mergers and acquisitions. While market concentration may present challenges for smaller players seeking to enter the market, it also fosters an environment of innovation and competition, driving advancements in AI technology and enhancing the quality and efficiency of surgical care delivery in operating room settings.
Report Coverage
The research report offers an in-depth analysis based on Offering, Technology, Indication, Applications, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued Growth: The AI in Operating Room market is poised for sustained expansion, driven by increasing demand for precision surgery and improved patient outcomes.
- Technological Advancements: Ongoing advancements in AI algorithms and machine learning techniques will fuel innovation, enhancing the capabilities of AI-powered surgical systems.
- Expansion of Applications: AI technology will extend its reach into a broader range of surgical specialties, catering to diverse clinical needs and procedures.
- Integration with Robotics: Deeper integration of AI with robotic surgical systems will unlock new possibilities for automation and enhanced surgical precision.
- Enhanced Patient Safety: AI-driven decision support tools will contribute to improved patient safety by minimizing errors and complications during surgery.
- Personalized Medicine: AI algorithms will enable personalized surgical approaches tailored to individual patient characteristics and medical histories.
- Regulatory Frameworks: Robust regulatory frameworks will evolve to ensure the safe and ethical use of AI in surgical settings, fostering trust and confidence among stakeholders.
- Collaboration and Partnerships: Collaborative efforts between healthcare providers, technology developers, and regulatory bodies will drive innovation and adoption of AI in the operating room.
- Addressing Healthcare Disparities: AI technology has the potential to bridge healthcare disparities by improving access to advanced surgical care and expertise in underserved regions.
- Training and Education: Emphasis on standardized training programs and education initiatives will empower healthcare professionals to effectively leverage AI technologies, optimizing their use in the operating room.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Minimally Invasive and Precision Surgeries
Patients and healthcare providers are increasingly favoring minimally invasive procedures due to faster recovery times and reduced complications. AI technologies in the operating room enhance surgical precision and efficiency, directly supporting this trend and driving adoption.
Integration of AI with Robotic-Assisted Surgical Systems
The combination of AI and robotics is revolutionizing surgical procedures by enabling greater dexterity, accuracy, and even partial autonomy in the operating room. This integration is expanding the capabilities of surgical teams and increasing the market share of advanced robotic systems.
Personalized Medicine and Real-Time Decision Support
AI algorithms can analyze vast amounts of patient data, including genetics and medical history, to generate personalized treatment plans and provide real-time intraoperative guidance. This leads to improved patient outcomes and is a key factor in the growing adoption of AI in surgical settings.
Addressing Surgeon Shortages and Enhancing Training
AI-powered surgical assistants and training platforms help mitigate the impact of surgeon shortages, especially in underserved regions. These systems provide real-time feedback, reduce human error, and support less experienced surgeons, making advanced surgical care more accessible.
Advancements in Machine Learning, Deep Learning, and AR
Rapid progress in machine learning, deep learning, and augmented reality is enabling more accurate image analysis, workflow optimization, and intraoperative visualization. These technological advancements are making AI solutions more effective and attractive for operating room integration.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the AI in Operating Room market?
What factors are driving the growth of the AI in Operating Room market?
What are the key segments within the AI in Operating Room market?
What are some challenges faced by the AI in Operating Room market?
Who are the major players in the AI in Operating Room market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Offering
- 1.2.1 Hardware
- 1.2.2 Software-as-a-Service (SaaS)
- 1.3 By Indication
- 1.3.1 Cardiology
- 1.3.2 Orthopedics
- 1.3.3 Urology
- 1.3.4 Gastroenterology
- 1.3.5 Neurology
- 1.3.6 Others
- 1.4 By Technology
- 1.4.1 Machine Learning (ML) and Deep Learning
- 1.4.2 Natural Language Processing (NLP)
- 1.4.3 Others
- 1.5 By Application
- 1.5.1 Training
- 1.5.2 Diagnosis
- 1.5.3 Surgical Planning and Rehabilitation
- 1.5.4 Outcomes and Risk Analysis
- 1.5.5 Integration and Connectivity
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 528.18 million → 2032: USD 4,359.16 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Artificial Intelligence (AI) in Operating Room Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Artificial Intelligence (AI) in Operating Room Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Artificial Intelligence (AI) in Operating Room Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Artificial Intelligence (AI) in Operating Room Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Artificial Intelligence (AI) in Operating Room Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Artificial Intelligence (AI) in Operating Room Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Artificial Intelligence (AI) in Operating Room Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Artificial Intelligence (AI) in Operating Room Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 528.18 million → 2032: USD 4,359.16 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Artificial Intelligence (AI) in Operating Room Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Offering - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hardware
- 12.3.7.2 Software-as-a-Service (SaaS)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Indication - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cardiology
- 12.4.7.2 Orthopedics
- 12.4.7.3 Urology
- 12.4.7.4 Gastroenterology
- 12.4.7.5 Neurology
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Machine Learning (ML) and Deep Learning
- 12.5.7.2 Natural Language Processing (NLP)
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Training
- 12.6.7.2 Diagnosis
- 12.6.7.3 Surgical Planning and Rehabilitation
- 12.6.7.4 Outcomes and Risk Analysis
- 12.6.7.5 Integration and Connectivity
- 12.6.7.6 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Artificial Intelligence (AI) in Operating Room End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Artificial Intelligence (AI) in Operating Room Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Artificial Intelligence (AI) in Operating Room Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Artificial Intelligence (AI) in Operating Room Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Medtronic Plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Intuitive Surgical, Inc.
- 18.4 Stryker Corporation
- 18.5 Brainlab AG
- 18.6 Caresyntax, Inc.
- 18.7 Theator Inc.
- 18.8 ExplORer Surgical Corp.
- 18.9 Activ Surgical, Inc.
- 18.10 Royal Philips
- 18.11 LeanTaaS Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

