
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Roofing Underlayment Market Size 2024 | USD 25,260.47 million |
| Roofing Underlayment Market, CAGR | 5.39% |
| Roofing Underlayment Market Size 2032 | USD 38,431.54 million |
Market Overview
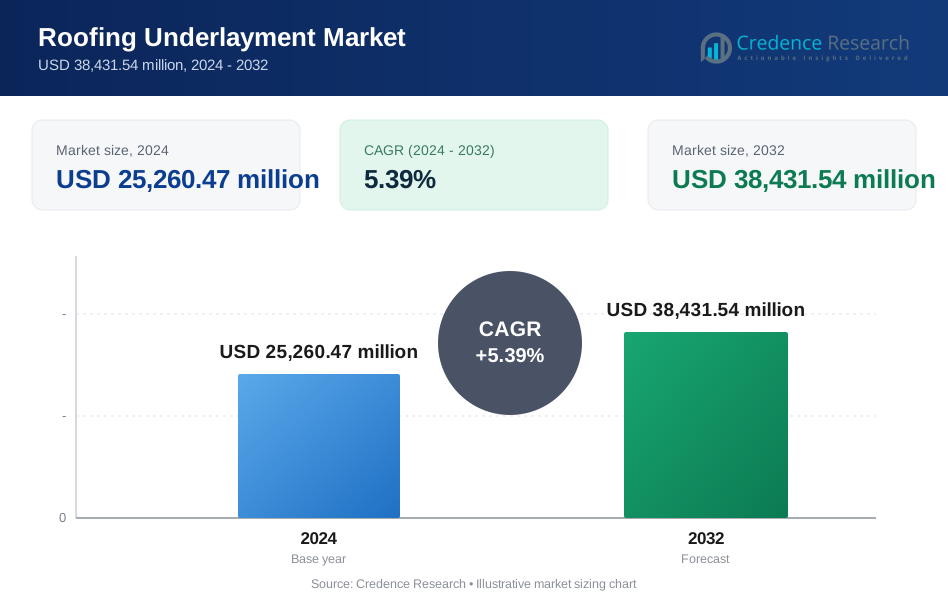
The Global Roofing Underlayment Market is projected to grow from USD 25,260.47 million in 2024 to an estimated USD 38,431.54 million by 2032, registering a compound annual growth rate (CAGR) of 5.39% from 2025 to 2032. Key drivers propelling the roofing underlayment market include the rising need for protection against water infiltration, enhanced durability requirements, and regulatory mandates focused on building safety and sustainability. Technological advancements have led to the development of synthetic underlayments that offer superior performance compared to traditional felt materials. Additionally, trends toward green buildings and energy-efficient roofing systems boost market demand, as underlayments contribute to thermal insulation and moisture control. Increasing preference for roofing materials that reduce maintenance costs also supports market growth. Geographically, North America holds a significant share in the roofing underlayment market, driven by stringent building codes and high adoption of advanced roofing technologies. The Asia Pacific region is expected to witness the fastest growth due to rapid urbanization, rising disposable incomes, and expanding construction sectors in countries such as China and India. Major players leading the market include GAF Materials Corporation, Owens Corning, CertainTeed Corporation, Atlas Roofing Corporation, and TAMKO Building Products. These companies focus on product innovation, strategic partnerships, and expanding distribution networks to strengthen their market presence globally.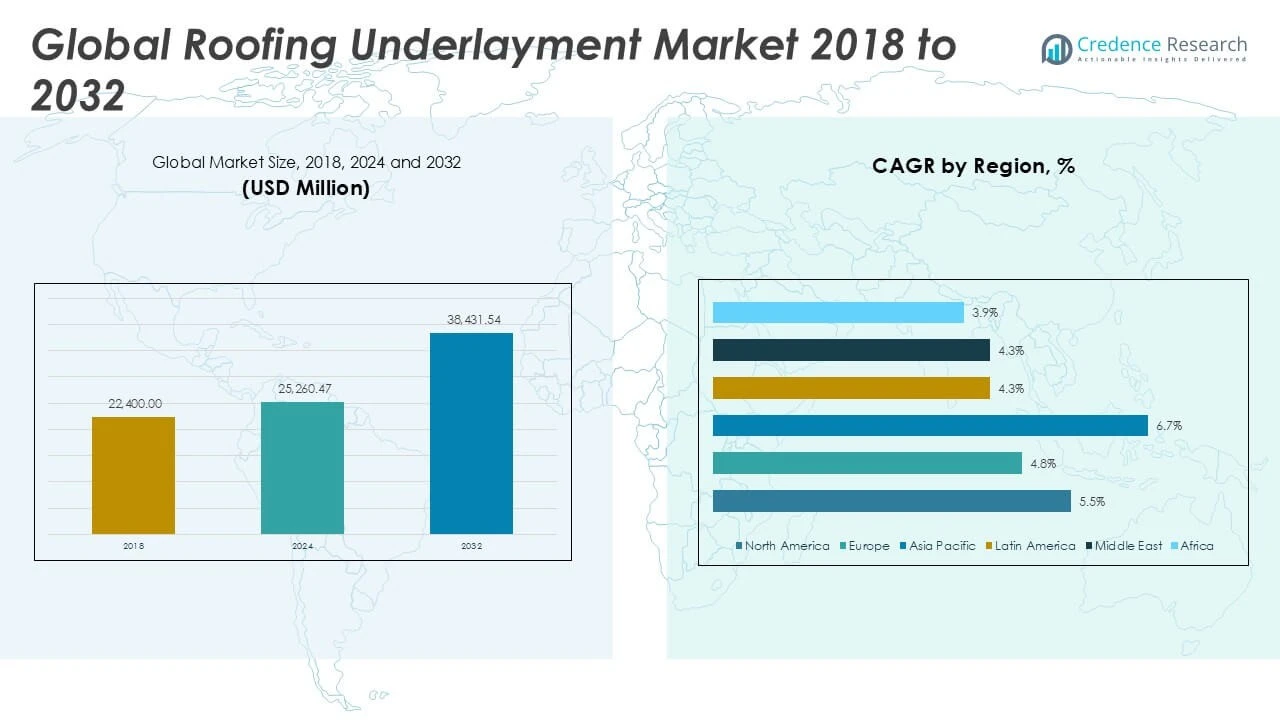
Market Insights
- The market is projected to grow from USD 25,260.47 million in 2024 to USD 38,431.54 million by 2032, exhibiting a CAGR of 5.39% driven by rising construction and infrastructure development.
- Increasing demand for durable, weather-resistant roofing solutions and growing emphasis on energy-efficient building materials act as key growth drivers.
- Technological advancements in synthetic underlayments enhance product performance, installation ease, and longevity, positively impacting market expansion.
- Market restraints include volatility in raw material prices and limited awareness about advanced roofing underlayments in some regions, which may slow adoption.
- North America holds a dominant market share supported by strict building codes and advanced roofing technologies.
- Asia Pacific is expected to register the highest growth rate due to rapid urbanization, increasing disposable income, and expanding residential and commercial construction.
- Market players focus on product innovation, strategic partnerships, and expanding distribution networks to strengthen their global presence and meet evolving customer needs.
Market Drivers
Increasing Construction Activities and Rising Demand for Durable Roofing Solutions
The Global Roofing Underlayment Market benefits significantly from the ongoing expansion in residential and commercial construction worldwide. Growing urbanization and infrastructure development fuel demand for reliable roofing materials that ensure structural integrity and weather resistance. Builders and contractors prioritize roofing underlayments that provide effective moisture barriers and extend roof lifespan. It plays a critical role in protecting roofing systems from water infiltration, wind, and temperature fluctuations. The rising emphasis on constructing energy-efficient buildings also encourages the use of underlayments that contribute to insulation and thermal regulation. This combination of factors drives sustained market growth and innovation.- For instance, government initiatives such as the Pradhan Mantri Awas Yojana (PMAY) and Smart Cities Mission have significantly contributed to the demand for roofing solutions, supporting large-scale infrastructure development in India
Growing Awareness of Building Safety Standards and Regulatory Compliance
Increasing enforcement of stringent building codes and safety regulations boosts the demand for high-quality roofing underlayments globally. Governments and industry bodies mandate roofing materials that comply with fire resistance, waterproofing, and durability standards. It compels manufacturers and construction firms to adopt advanced products, such as synthetic underlayments, that exceed traditional options in performance. The need to meet environmental and safety criteria pushes the market toward sustainable and resilient roofing solutions. Compliance with regulations not only ensures occupant safety but also enhances property value and reduces maintenance costs. These factors strengthen the market’s foundation and support steady adoption.- For instance, a 2024 survey by the Building Engineering Services Association (BESA) found that 88% of industry professionals were aware of the Building Safety Act, reflecting growing compliance with safety regulations.
Technological Advancements Enhancing Roofing Underlayment Performance
Innovations in material science and manufacturing processes improve the quality and functionality of roofing underlayments. The development of synthetic underlayments offers superior strength, lightweight design, and better resistance to tearing and moisture compared to conventional felt. It enables faster installation and reduces labor costs while increasing durability under harsh weather conditions. Enhanced UV resistance and breathability features also contribute to the product’s effectiveness. Manufacturers continuously invest in research to introduce next-generation materials that address evolving customer demands. This technological progress drives product differentiation and market competitiveness.Rising Preference for Sustainable and Energy-Efficient Roofing Solutions
Growing environmental concerns and energy conservation efforts encourage the adoption of roofing materials that minimize carbon footprints. Roofing underlayments contribute to reducing energy consumption by improving thermal insulation and preventing heat loss. It supports green building certifications and aligns with global sustainability goals. Consumers and commercial developers increasingly select products that balance performance with environmental impact. The trend toward eco-friendly construction materials motivates manufacturers to develop recyclable and low-emission underlayments. This shift toward sustainability represents a key driver shaping the market’s future trajectory.Market Trends
Rising Adoption of Synthetic Roofing Underlayments for Enhanced Durability
The Global Roofing Underlayment Market shows a clear shift toward synthetic materials, which offer superior performance compared to traditional felt underlayments. Synthetic underlayments provide increased resistance to moisture, UV exposure, and tearing, improving overall roof protection. It also offers easier installation due to lighter weight and greater flexibility, which reduces labor time and costs. Builders and contractors increasingly favor synthetic options for their reliability in harsh weather conditions. The trend toward synthetic materials supports longer roof lifespans and lower maintenance requirements. This transition drives innovation and expands product portfolios across the market.- For instance, nearly 58% of new residential roofs and 42% of commercial projects now use slip synthetic underlayment due to its superior performance and longevity.
Integration of Roofing Underlayments with Energy-Efficient Building Designs
Energy efficiency plays a growing role in construction, influencing the choice of roofing underlayments in the market. The Global Roofing Underlayment Market responds to demand for materials that contribute to thermal insulation and reduce energy consumption in buildings. It helps maintain indoor temperature stability by preventing heat loss and moisture buildup. Roofing underlayments compatible with green building certifications gain traction among architects and developers. Manufacturers focus on improving product thermal performance to align with sustainability objectives. This trend aligns with increasing regulatory support for energy-efficient construction worldwide.- For instance, Lockheed Martin's AI-driven radar systems enhance target recognition and reduce false positives, allowing for more precise threat identification in complex environments.
Expansion of Smart and Multi-Functional Roofing Underlayment Solutions
Innovation drives the development of smart roofing underlayments that combine multiple protective functions into a single product. The Global Roofing Underlayment Market incorporates features such as enhanced vapor permeability, UV resistance, and antimicrobial properties. It allows roofing systems to perform better under diverse environmental stresses and reduces potential damage over time. Manufacturers increasingly integrate these attributes to meet the rising expectations of end users for durable, efficient, and low-maintenance roofing solutions. This multi-functionality trend elevates product value and broadens market appeal.Growth in Demand from Emerging Economies Fueling Market Expansion
Emerging economies contribute significantly to the Global Roofing Underlayment Market’s growth through rapid urbanization and infrastructure development. Rising disposable incomes and increased construction investments in regions such as Asia Pacific and Latin America drive higher roofing material consumption. It creates opportunities for manufacturers to expand distribution networks and introduce cost-effective underlayment options. Local governments’ focus on improving building safety standards further supports market penetration. The expansion into emerging markets fosters competitive dynamics and stimulates innovation tailored to regional needs.Market Challenges
Challenges in Raw Material Price Volatility and Its Impact on Production Costs
The Global Roofing Underlayment Market faces significant challenges from fluctuations in raw material prices, particularly petroleum-based products used in synthetic underlayments. It increases production costs and affects profit margins for manufacturers. Volatile prices create uncertainty in supply chain planning and can delay product deliveries. Smaller manufacturers may struggle to absorb these cost pressures, limiting their ability to compete effectively. This instability also impacts pricing strategies, forcing companies to balance affordability with quality. Market participants must adopt cost-control measures and explore alternative materials to mitigate these risks.- For instance, the roofing underlayment industry has seen the development of over 45 advanced synthetic underlayment materials designed to improve durability and reduce dependency on petroleum-based products.
Challenges in Limited Awareness and Installation Expertise Affecting Market Penetration
Limited awareness among end users and contractors about the benefits and correct installation of advanced roofing underlayments restricts market growth. It can lead to improper application, reducing product performance and customer satisfaction. The Global Roofing Underlayment Market requires focused efforts to educate stakeholders on product features and installation best practices. Lack of skilled labor in some regions further compounds this issue, slowing adoption rates. Manufacturers and industry bodies need to invest in training programs and awareness campaigns. Overcoming these challenges is crucial to unlocking the full market potential and ensuring long-term growth.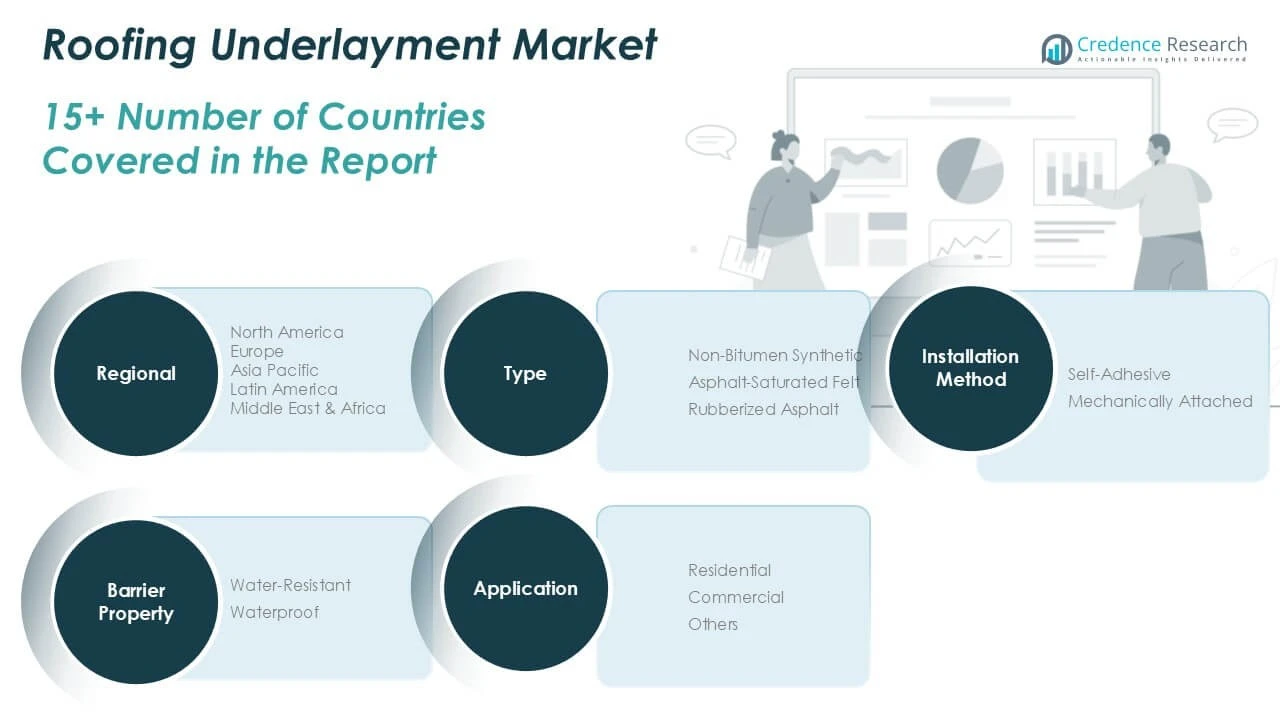
Market Opportunities
Opportunities Arising from Growing Urbanization and Infrastructure Development in Emerging Markets
The Global Roofing Underlayment Market benefits from rapid urbanization and increasing infrastructure investments in emerging economies such as China, India, and Southeast Asia. It creates demand for advanced roofing materials that enhance building safety, durability, and energy efficiency. Expanding residential, commercial, and industrial construction projects offer ample opportunities for market players to introduce cost-effective and high-performance underlayments. Government initiatives supporting sustainable building practices further encourage adoption of innovative roofing solutions. Manufacturers can capitalize on these trends by tailoring products to regional climate conditions and regulatory requirements. Enhanced distribution networks and localized marketing strategies will enable better market penetration and growth.Opportunities Presented by Technological Innovation and Sustainable Building Practices
The growing emphasis on energy conservation and eco-friendly construction opens new avenues in the Global Roofing Underlayment Market. It encourages the development of synthetic and multi-functional underlayments that improve thermal insulation, moisture control, and weather resistance. Investing in research and development to create recyclable and low-emission products aligns with increasing consumer and regulatory demand for sustainability. The shift toward smart and modular construction methods offers further potential to introduce lightweight, easy-to-install roofing underlayments. Collaboration with architects, builders, and regulatory bodies can accelerate product adoption and market expansion. These opportunities position companies to strengthen their competitive advantage and meet evolving industry needs.Market Segmentation Analysis
By Type The Global Roofing Underlayment Market categorizes products primarily into Non-Bitumen Synthetic, Asphalt-Saturated Felt, and Rubberized Asphalt underlayments. Non-Bitumen Synthetic underlayments gain traction due to their superior durability, lightweight nature, and resistance to moisture and tearing. Asphalt-Saturated Felt remains widely used for its cost-effectiveness and traditional application in residential and commercial roofing. Rubberized Asphalt underlayments provide enhanced waterproofing capabilities and self-adhesive properties, making them ideal for critical roof areas prone to water infiltration. The demand for synthetic options grows steadily due to performance advantages and increasing construction standards. By Application Market segmentation by application includes Residential, Commercial, and Others. Residential roofing dominates due to extensive housing developments and renovation activities worldwide. It drives demand for underlayments that offer protection, energy efficiency, and long service life. The commercial segment follows closely, benefiting from large-scale infrastructure projects and stringent safety regulations. Other applications include industrial and institutional buildings, which require specialized underlayments to meet unique operational needs. Each application segment influences product development tailored to performance requirements and budget considerations. By Installation Method Installation methods divide the market into Self-Adhesive and Mechanically Attached underlayments. Self-Adhesive underlayments provide ease of installation and strong adhesion, reducing labor time and minimizing installation errors. They suit areas requiring detailed waterproofing and offer better performance in extreme weather. Mechanically Attached underlayments rely on fasteners for secure placement and allow easier repositioning during installation. This method remains popular for large roofing projects where flexibility and cost control are priorities. The choice depends on project complexity, climate, and budget constraints. By Barrier Property Barrier property segmentation includes Water-Resistant and Waterproof underlayments. Water-Resistant products offer basic protection against moisture penetration and are commonly used in moderate climates or as secondary layers. Waterproof underlayments provide complete protection against water infiltration, suitable for regions with heavy rainfall or snow. It enhances roof durability and reduces maintenance costs. The market sees increased demand for waterproof underlayments due to growing awareness of weather resilience and building longevity. Manufacturers innovate to balance barrier performance with breathability to prevent condensation issues.Segments
Based on Type- Non-Bitumen Synthetic
- Asphalt-Saturated Felt
- Rubberized Asphalt
- Residential
- Commercial
- Others
- Self-Adhesive
- Mechanically Attached
- Water-Resistant
- Waterproof
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Roofing Underlayment Market The North America Roofing Underlayment Market holds the largest regional market share of approximately 35.2%, with a market value of USD 8,888.32 million in 2024, expected to reach USD 13,560.91 million by 2032 at a CAGR of 5.5%. It benefits from stringent building codes, high infrastructure investments, and advanced construction technologies. The United States and Canada lead demand driven by frequent renovations and new construction emphasizing durable and energy-efficient roofing materials. It gains traction from growing awareness of weather-resistant roofing solutions, especially in areas vulnerable to extreme weather. The presence of key manufacturers and well-established distribution networks further supports market expansion. North America remains a critical hub for roofing underlayment innovation. Europe Roofing Underlayment Market Europe holds the second-largest regional market share at approximately 26.5%, with a valuation of USD 6,691.54 million in 2024, expected to rise to USD 9,642.54 million by 2032 at a CAGR of 4.8%. It experiences growth due to strict environmental regulations and sustainability initiatives in countries like Germany, the UK, and France. The region promotes green building standards encouraging energy-efficient roofing systems. Expanding residential and commercial construction and renovation of historic buildings sustain demand. It witnesses steady growth driven by technological advancements and consumer preference for premium materials. Europe’s market combines traditional and innovative roofing derlayment products. Asia Pacific Roofing Underlayment Market The Asia Pacific Roofing Underlayment Market commands about 25.5% regional market share with a market size of USD 6,434.11 million in 2024, expected to reach USD 10,727.78 million by 2032, growing at a CAGR of 6.7%. Rapid urbanization, industrialization, and infrastructure growth in China, India, Japan, and Southeast Asia drive demand. Rising disposable incomes and government initiatives for building safety and energy efficiency accelerate market adoption. Residential and commercial construction projects promote advanced roofing underlayments. It faces strong competition from global and local manufacturers offering cost-effective and durable products. Asia Pacific plays a key role in market expansion due to its large population and evolving construction sector. Latin America Roofing Underlayment Market Latin America accounts for roughly 5.3% of the global market share, with a value of USD 1,337.09 million in 2024, projected to reach USD 1,854.01 million by 2032 at a CAGR of 4.3%. Infrastructure projects and urban housing developments in Brazil, Mexico, and Argentina drive growth. Awareness of building safety and energy-efficient materials supports demand. Economic fluctuations and slower adoption of high-performance products constrain growth in some areas. Government investments and foreign direct investment foster steady development. Manufacturers expand distribution and tailor products to regional climates. Middle East Roofing Underlayment Market The Middle East holds approximately 4.0% of the global market share, valued at USD 1,002.04 million in 2024, forecast to grow to USD 1,390.01 million by 2032 at a CAGR of 4.3%. Construction activities in the UAE, Saudi Arabia, and Qatar fuel demand. Commercial, residential, and large-scale developments benefit from economic diversification. It requires roofing underlayments resistant to extreme heat and sand exposure. Investments in smart, sustainable building materials support expansion. Market players pursue innovation and strategic partnerships to enhance presence. Africa Roofing Underlayment Market Africa represents about 3.6% of the global market share, with a market value of USD 907.37 million in 2024, expected to reach USD 1,256.30 million by 2032 at a CAGR of 3.9%. Infrastructure growth, urbanization, and construction in South Africa, Nigeria, and Kenya increase demand. Affordable and durable roofing materials remain essential. Challenges include limited technical expertise and economic variability. Government infrastructure projects and improved building standards create growth opportunities. Manufacturers focus on cost-effective products and expanded distribution tailored to regional needs.Key players
- GAF Materials Corporation
- Owens Corning
- Johns Manville
- IKO Industries Ltd.
- Roofing Components International
- MFM Building Products Corp.
- Carlisle SynTec Systems
- DuPont de Nemours, Inc.
- 3M
- SOPREMA
- BMI Group
- Atlas Roofing Corporation
- TAMKO Building Products LLC
- Polyglass USA, Inc.
Competitive Analysis
The Roofing Underlayment Market exhibits intense competition among established multinational companies and regional players. It drives continuous innovation in product quality, durability, and installation ease to meet evolving customer demands. Leading companies focus on expanding their product portfolios and geographic reach through strategic partnerships and acquisitions. It experiences pressure to balance cost efficiency with superior performance to maintain market share. Companies differentiate through technological advancements, sustainable product offerings, and compliance with regulatory standards. Competitive pricing, robust distribution networks, and brand reputation further influence buyer preferences. The market’s dynamic nature compels players to invest in research and development, marketing, and customer support to sustain growth and profitability.Recent Developments
- In March 2025, MFM Building Products Corp. introduced a 48-inch self-adhered underlayment at the International Roofing Expo, designed for larger coverage and ease of installation.
- In May 2025, Carlisle SynTec Systems updated its specifications and details for roofing systems, including underlayment products, to enhance performance and compliance with industry standards.
- In May 2025, Owens Corning announced plans to build a new shingle plant in the Southeastern U.S., expected to begin production in 2027, to meet growing demand for roofing materials.
- In May 2025, Johns Manville highlighted its plans for 2025, focusing on expanding its roofing product offerings and enhancing customer support.
- In May 2025, Atlas Roofing Corporation announced plans for expansion, including the development of new roofing underlayment products to meet increasing market demand.
Market Concentration and Characteristics
The Roofing Underlayment Market demonstrates a moderately concentrated structure dominated by several key global players that control a significant portion of the market share. It features a blend of large multinational corporations and smaller regional manufacturers competing on innovation, product quality, and pricing. Market leaders leverage advanced technology, extensive distribution networks, and strong brand recognition to maintain competitive advantages. It experiences ongoing product diversification to address varied climatic conditions, application requirements, and regulatory standards. The market characteristics include high entry barriers due to capital intensity and stringent quality requirements. It also shows increasing emphasis on sustainable and energy-efficient materials. Competitive dynamics drive continuous improvement in performance and cost-effectiveness, benefiting end users through enhanced roofing solutions.Report Coverage
The research report offers an in-depth analysis based on Type, Application, Installation Method, Barrier Property and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook
- The Roofing Underlayment Market will continue growing steadily due to rising global construction activities and infrastructure development. Increasing urbanization and renovation projects drive sustained demand.
- Technological advancements will lead to the introduction of next-generation synthetic underlayments with improved durability and ease of installation. These innovations will enhance roofing system performance.
- Growing awareness of energy-efficient and sustainable building materials will encourage adoption of eco-friendly roofing underlayments. This trend aligns with stricter environmental regulations worldwide.
- Expansion in emerging economies, especially in Asia Pacific and Latin America, will present significant growth opportunities. Rising disposable incomes and government initiatives will accelerate market penetration.
- The demand for waterproof and multi-functional underlayments will increase due to climate change and extreme weather events. Builders will prioritize materials that offer superior protection and longevity.
- Manufacturers will invest more in R\&D to develop advanced materials with enhanced UV resistance, vapor permeability, and thermal insulation properties. This will meet evolving customer requirements.
- The shift toward modular and prefabricated construction will drive demand for lightweight and easy-to-install roofing underlayments. It will reduce labor costs and construction time.
- Digitalization and smart construction technologies will influence the market by enabling better quality control and efficient installation processes. These improvements will reduce errors and rework.
- Strategic collaborations, mergers, and acquisitions among key players will shape the competitive landscape. Companies will focus on expanding their geographic footprint and product offerings.
- Increasing focus on building safety and stringent construction codes will reinforce demand for high-performance roofing underlayments. It will support long-term market stability and growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Construction Activities and Urbanization
Rapid growth in residential and commercial construction, especially in emerging economies, is driving demand for roofing underlayments that provide reliable protection and durability. Urbanization and infrastructure development projects require advanced roofing solutions to ensure building longevity and safety.
Technological Advancements in Synthetic Underlayments
Innovations in material science have led to the development of synthetic underlayments that offer superior moisture resistance, durability, and ease of installation compared to traditional felt. These advancements are encouraging builders and contractors to adopt higher-performing products.
Stringent Building Codes and Regulatory Compliance
Governments and industry bodies are enforcing stricter building codes and safety standards, which mandate the use of high-quality, fire-resistant, and waterproof roofing underlayments. Compliance with these regulations is boosting market adoption of advanced products.
Rising Focus on Energy Efficiency and Sustainability
The trend toward green buildings and energy-efficient construction is increasing the use of roofing underlayments that contribute to thermal insulation and moisture control. Sustainable and recyclable underlayments are gaining traction as environmental concerns and certification requirements grow.
Preference for Low-Maintenance and Long-Lasting Roofing Solutions
Building owners and developers are seeking roofing materials that reduce long-term maintenance costs and extend roof lifespan. Advanced underlayments with enhanced weather resistance and durability are meeting this demand, supporting market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Roofing Underlayment market in 2023 and its expected size by 2032?
What are the key factors driving the growth of the Roofing Underlayment market?
Why is synthetic underlayment gaining popularity in the market?
Which region holds the largest share in the Roofing Underlayment market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Non-Bitumen Synthetic
- 1.2.2 Asphalt-Saturated Felt
- 1.2.3 Rubberized Asphalt
- 1.3 By Application
- 1.3.1 Residential
- 1.3.2 Commercial
- 1.3.3 Others
- 1.4 By Barrier Property
- 1.4.1 Water-Resistant
- 1.4.2 Waterproof
- 1.5 By Installation Method
- 1.5.1 Self-Adhesive
- 1.5.2 Mechanically Attached
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 25,260.47 million → 2032: USD 38,431.54 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Roofing Underlayment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Roofing Underlayment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Roofing Underlayment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Roofing Underlayment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Roofing Underlayment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Roofing Underlayment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Roofing Underlayment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Roofing Underlayment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 25,260.47 million → 2032: USD 38,431.54 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Roofing Underlayment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Non-Bitumen Synthetic
- 12.3.7.2 Asphalt-Saturated Felt
- 12.3.7.3 Rubberized Asphalt
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential
- 12.4.7.2 Commercial
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Barrier Property - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Water-Resistant
- 12.5.7.2 Waterproof
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Installation Method - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Self-Adhesive
- 12.6.7.2 Mechanically Attached
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Roofing Underlayment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Roofing Underlayment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Roofing Underlayment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Roofing Underlayment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 GAF Materials Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Owens Corning
- 18.4 Johns Manville
- 18.5 IKO Industries Ltd.
- 18.6 Atlas Roofing Corporation
- 18.7 TAMKO Building Products LLC
- 18.8 Carlisle SynTec Systems
- 18.9 DuPont de Nemours, Inc.
- 18.10 SOPREMA
- 18.11 Polyglass USA, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

