
Market Overview:
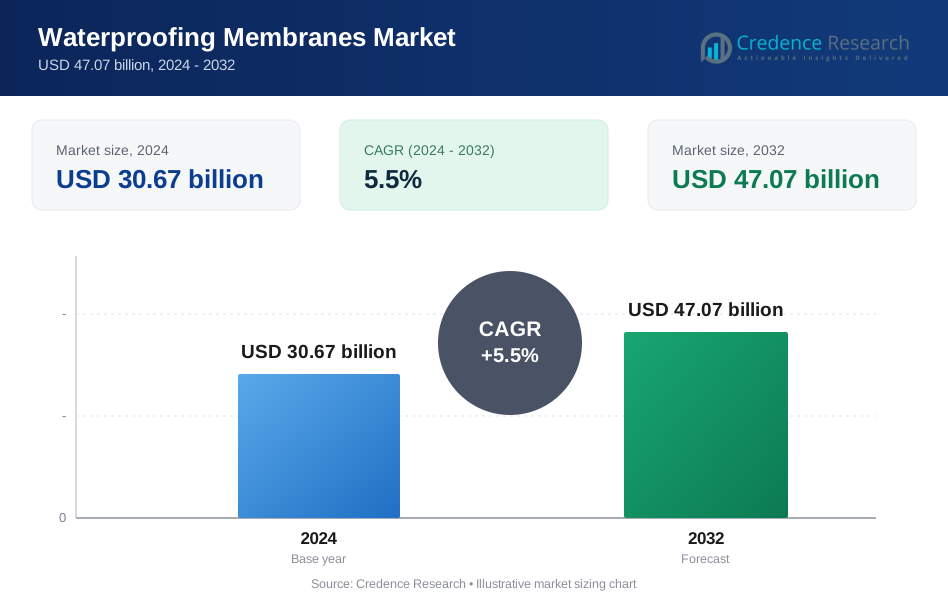
The waterproofing membrane market size was valued at USD 30.67 billion in 2024 and is projected to reach USD 47.07 billion by 2032, growing at a CAGR of 5.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Waterproofing Membranes Market Size 2024 | USD 30.67 billion |
| Waterproofing Membranes Market, CAGR | 5.5% |
| Waterproofing Membranes Market Size 2032 | USD 47.07 billion |
The waterproofing membrane market is highly competitive, with key players including Kemper System, Sika, Pidilite Industries, Xypex Chemical, BASF, Danrae Group, Soprema, Maris Polymers, GAF Materials, Alchimica Building Chemicals, Derbigum International, Asian Paints, Fosroc, Bauder, Saint-Gobain, and Dow driving innovation and market growth. These companies focus on developing advanced polymer, bitumen, and liquid-applied membranes that deliver superior durability, flexibility, and energy efficiency. Asia-Pacific led the market in 2024 with over 30% share, driven by rapid urbanization, infrastructure development, and housing demand in China, India, and Southeast Asia. North America followed with 34% share, supported by strong construction and renovation activities.

Market Insights
- The waterproofing membrane market was valued at USD 30.67 billion in 2024 and is projected to reach USD 47.07 billion by 2032, growing at a CAGR of 5.5% from 2025 to 2032.
- Rising construction activities, infrastructure development, and demand for moisture protection in residential and commercial projects are driving market growth.
- Liquid-applied membranes and polymer-based solutions are trending due to their ease of application, energy efficiency, and suitability for complex structures.
- The market is competitive, with players focusing on product innovation, sustainable solutions, and strategic partnerships to strengthen their global presence.
- North America held 34% share in 2024, followed by Asia-Pacific with over 30%, while bitumen led the material segment with over 40% share, supported by cost-effectiveness and durability for roofing and foundation applications.
Market Segmentation Analysis:
By Material
Bitumen held the largest share of the waterproofing membrane market in 2024, accounting for over 40% share due to its cost-effectiveness, durability, and proven performance in roofing and foundation applications. Its widespread use in torch-applied and self-adhesive membranes makes it a preferred choice for residential and infrastructure projects. Polymers such as PVC and TPO are growing rapidly, supported by demand for lightweight, flexible, and heat-resistant membranes in commercial buildings. Rubber membranes like EPDM are favored in green roofs and large-scale roofing projects. Other materials, including liquid-applied membranes, cater to niche waterproofing needs.
- For instance, Sika AG, a major supplier of specialty chemicals for the construction industry, reported record sales of 11.76 billion Swiss francs in 2024, an increase of 4.7% in Swiss francs over the previous year
By Application
Roofing dominated the market with more than 35% share in 2024, driven by increasing construction of residential and commercial buildings and rising need for durable, weather-resistant solutions. Demand for single-ply polymer membranes is surging due to ease of installation and energy-efficient properties. Basement and foundation applications follow, fueled by urban infrastructure expansion and rising awareness of moisture protection in below-grade structures. Walls and facades are gaining traction with growing use of liquid-applied membranes in high-rise construction. Landfills and tunnels utilize geomembranes for leak prevention, while balconies and other small applications contribute steadily to market growth.
- For instance, in 2024, GAF expanded its production capabilities by starting production at a new TPO manufacturing plant in Valdosta, Georgia, to meet commercial roofing demand. This expansion was initially announced in late 2022 and aimed to increase the supply of its EverGuard™ TPO products. While North American TPO market TPO single-ply roofing membranes was estimated at various figures by different market research firms for 2024, one estimate placed the value at approximately $2.5 billion.
By End Use
Infrastructure projects accounted for the largest share of over 30% in 2024, supported by major investments in roads, bridges, and tunnels requiring robust waterproofing solutions. Residential construction is a significant contributor, driven by rising housing demand and government-backed affordable housing programs. Commercial projects such as office complexes and shopping centers continue to adopt advanced membranes for energy efficiency and long-term durability. Industrial facilities including manufacturing plants and warehouses use waterproofing systems to protect structural integrity, machinery, and stored goods from water damage, supporting steady demand from the industrial segment during the forecast period.
Key Growth Drivers
Rising Construction and Infrastructure Investments
Rapid urbanization and increasing government spending on infrastructure projects are major drivers for waterproofing membranes. Roads, bridges, tunnels, and metro systems require durable waterproofing to enhance service life and minimize maintenance costs. Residential construction is also expanding, supported by housing initiatives in emerging economies. These factors collectively boost demand for bitumen and polymer-based membranes. Growing awareness of moisture-related structural damage further accelerates adoption, making construction and infrastructure spending a critical growth catalyst.
- For instance, Mapei is a major supplier of chemical products for the construction industry and is known for its waterproofing solutions, including polyurethane and polyurea systems. Simultaneously, Autostrade per l'Italia, which operates around 3,000 km of Italy's motorways, has undertaken significant maintenance and sustainability initiatives across its network, including its vast number of bridges and viaducts (over 4,200).
Shift Toward Sustainable and Energy-Efficient Solutions
Rising focus on green building standards and energy-efficient construction is boosting demand for eco-friendly waterproofing membranes. Manufacturers are developing solvent-free, recyclable, and low-VOC membranes that align with LEED and BREEAM certifications. Cool roofing applications using reflective membranes help lower energy consumption in commercial buildings. This sustainability shift is pushing adoption in urban and industrial projects. The trend benefits polymer and liquid-applied membranes, which offer flexibility and reduced environmental impact, strengthening their market penetration globally.
- For instance, in 2024, Soprema introduced a new, Quebec-focused recycling initiative called SOPRALOOP. This program recycles residual materials like paper, cardboard, glassine, and polystyrene into high-performance insulation products. Through this circular economy approach, Soprema recovers nearly 25,000 tonnes of paper, cardboard, and glassine and approximately 10,000 tonnes of polystyrene annually in Quebec, significantly reducing landfill waste. Soprema has a long-standing history of promoting sustainable products and reducing VOC emissions, including for its COLPHENE BSW membrane system
Technological Advancements and Product Innovation
Innovations in manufacturing processes and product formulations are improving the performance of waterproofing membranes. Advanced membranes now offer enhanced UV resistance, chemical stability, and ease of installation, reducing project timelines. Self-adhesive, spray-applied, and pre-formed sheet membranes are gaining popularity for complex structures. Digital tools such as IoT-enabled monitoring systems ensure long-term performance by detecting leaks early. These advancements support higher adoption across commercial, residential, and industrial sectors, making technology and product development a key driver for market expansion.
Key Trends & Opportunities
Growing Adoption of Liquid-Applied Membranes
Liquid-applied membranes are witnessing strong demand due to their seamless application and suitability for irregular surfaces. They minimize the risk of joint failure compared to sheet membranes, offering better long-term protection. The ability to be sprayed or rolled reduces labor requirements, appealing to contractors facing workforce shortages. Their use is expanding in green roofs, podium decks, and retrofitting projects, presenting significant opportunities. Manufacturers are introducing fast-curing, solvent-free formulations to cater to environmentally conscious buyers, further driving this trend globally.
- For instance, Tremco offers the AlphaGuard BIO system, a high-performance, bio-based, two-part polyurethane roof coating. The system, which contains 60% to 70% rapidly renewable bio-based content, can be used for roof restoration, new construction, and vegetative roofs. It cures faster than comparable one-component products and can provide a service life of up to 20 years when installed correctly.
Emerging Opportunities in Asia-Pacific Markets
Asia-Pacific offers significant growth potential due to rapid industrialization, urban development, and infrastructure expansion in China, India, and Southeast Asia. Governments are investing heavily in smart city projects and transportation networks, driving demand for high-performance waterproofing solutions. Rising disposable incomes and housing demand also boost residential construction, creating opportunities for manufacturers. Local production expansion and partnerships with construction firms provide companies with competitive advantages, making this region a focal point for long-term market growth strategies.
- For instance, Carlisle Companies, the parent company of Carlisle Coatings & Waterproofing, is a major supplier of building envelope products. In 2024, the company successfully completed a strategic pivot to focus exclusively on building products. As part of this transition, it divested its Carlisle Interconnect Technologies business for $2.025 billion, with the definitive agreement announced in January 2024 and the sale completed in the second quarter of 2024.
Key Challenges
High Installation and Maintenance Costs
The cost of waterproofing membranes, particularly advanced polymer and liquid-applied types, remains a barrier for adoption in price-sensitive markets. Skilled labor is required for proper installation to avoid future failures, increasing project costs. Inadequate installation can lead to membrane damage and costly repairs, deterring some builders. Price competition from low-quality alternatives further pressures manufacturers to maintain margins while ensuring product performance, posing a significant challenge for market players targeting cost-conscious customers.
Volatility in Raw Material Prices
Waterproofing membrane production relies heavily on petroleum-based materials such as bitumen and polymers. Fluctuations in crude oil prices directly impact raw material costs, leading to pricing instability for end-users. Manufacturers face margin pressure during periods of high input costs, which can delay procurement decisions in large projects. The industry is exploring bio-based and recycled alternatives to reduce dependency on volatile raw materials, but adoption remains gradual, keeping price volatility a key challenge for market stability.
Regional Analysis
North America
North America accounted for around 34% share of the waterproofing membrane market in 2024, supported by strong demand from residential and commercial construction sectors. Growing renovation activities and adoption of energy-efficient roofing systems are key growth contributors. The U.S. leads the region with high consumption of polymer-based membranes in flat roofing and infrastructure projects. Canada is witnessing rising adoption of liquid-applied membranes in green building projects and public infrastructure upgrades. The presence of leading manufacturers and availability of advanced solutions continue to strengthen market penetration, while strict building codes ensure consistent demand for quality waterproofing systems.
Europe
Europe held nearly 28% share of the waterproofing membrane market in 2024, driven by a well-established construction sector and growing emphasis on sustainable building practices. Countries like Germany, France, and the UK are investing in energy-efficient infrastructure, supporting the use of advanced polymer and bitumen membranes. Renovation of aging residential and commercial structures is also fueling demand. EU regulations promoting eco-friendly materials are accelerating the shift toward solvent-free, recyclable membranes. Increased investments in transport infrastructure, including tunnels and bridges, further boost regional consumption, making Europe a mature but steadily growing market with a strong focus on sustainability.
Asia-Pacific
Asia-Pacific dominated the market with over 30% share in 2024, making it the fastest-growing region during the forecast period. Rapid urbanization, infrastructure development, and housing demand in China, India, and Southeast Asia are key drivers. Government investments in smart cities, metro rail projects, and industrial zones are increasing the consumption of waterproofing membranes. Rising awareness about moisture protection in residential construction is also supporting growth. Local manufacturing capacity expansion by global players is improving product availability and reducing costs, positioning Asia-Pacific as a critical growth hub with strong opportunities for both bitumen and polymer membrane adoption.
Latin America
Latin America represented around 5% share of the waterproofing membrane market in 2024, with gradual growth led by Brazil and Mexico. Rising investments in commercial and residential construction projects are fueling demand for cost-effective waterproofing solutions. Infrastructure development projects, including highways and water treatment plants, are adopting durable membranes to extend asset lifespan. Economic recovery and urbanization trends are supporting steady demand for roofing and foundation applications. However, market growth is slightly restrained by fluctuating raw material prices and limited awareness in rural areas, creating opportunities for manufacturers to introduce affordable, easy-to-install solutions.
Middle East & Africa
Middle East & Africa held nearly 3% share of the market in 2024, supported by large-scale infrastructure and real estate developments in GCC countries. Mega projects such as smart cities, airports, and commercial complexes are driving demand for high-performance waterproofing membranes. Hot climate conditions in the region increase the need for heat- and UV-resistant solutions, boosting adoption of polymer and liquid-applied membranes. Africa is witnessing gradual growth, driven by urbanization and government investments in water management infrastructure. Limited skilled labor and cost concerns present challenges, but the market shows strong potential with ongoing construction projects and industrial expansion.
Market Segmentations:
By Material:
- Bitumen
- Polymers
- Rubber
- Others
By Application:
- Roofing
- Basement & foundation
- Walls & facades
- Landfills & tunnels
- Others (balconies etc.)
By End Use:
- Residential
- Commercial
- Industrial
- Infrastructure
By Geography:
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Latin America
- Brazil
- Argentina
- Chile
- Rest of Latin America
- Middle East & Africa
- United Arab Emirates
- South Africa
- Saudi Arabia
- Egypt
- Rest of Middle East & Africa
Competitive Landscape
Kemper System, Sika, Pidilite Industries, Xypex Chemical, BASF, Danrae Group, Soprema, Maris Polymers, GAF Materials, Alchimica Building Chemicals, Derbigum International, Asian Paints, Fosroc, Bauder, Saint-Gobain, and Dow are among the major players shaping the waterproofing membrane market. The competitive landscape is characterized by a focus on product innovation, sustainability, and expansion into emerging markets. Companies are investing in advanced polymer and liquid-applied membranes to enhance flexibility, UV resistance, and ease of installation. Strategic mergers, acquisitions, and partnerships strengthen distribution networks and increase market reach. Emphasis on developing eco-friendly, solvent-free, and recyclable membranes aligns with global green building regulations. Players are also targeting infrastructure and industrial projects, supported by government initiatives for urban development. Continuous investment in R&D and the introduction of energy-efficient solutions are helping companies gain a competitive edge while meeting rising demand from residential, commercial, and infrastructure sectors worldwide.
Key Player Analysis
- Kemper System
- Sika
- Pidilite Industries'[
- Xypex Chemical
- BASF
- Danrae Group
- Soprema
- Maris Polymers
- GAF Materials
- Alchimica Building Chemicals
- Derbigum International
- Asian Paints
- Fosroc
- Bauder
- Saint-Gobain
- Dow
Recent Developments
- In 2025, Sika Corporation introduced new "Hybrid" and modified bitumen roofing solutions to the U.S. market under the SikaShield brand.
- In 2024, Saint-Gobain announced the acquisition of the global construction chemicals player FOSROC, further strengthening its position in the construction chemicals space.
- In 2024, Soprema acquired Mida from TechnoNicol, strengthening its position in the European waterproofing market, expanding its product offerings, and creating opportunities for greater synergy in manufacturing, innovation, and the development of sustainable construction materials
Report Coverage
The research report offers an in-depth analysis based on Material, Application, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to grow steadily, driven by rising global construction activities.
- Demand for polymer-based membranes will increase due to their flexibility and energy efficiency.
- Liquid-applied membranes will gain traction for complex structures and retrofitting applications.
- Infrastructure projects such as tunnels, bridges, and metros will remain key demand drivers.
- Adoption of sustainable and recyclable membranes will rise with green building initiatives.
- Technological innovations will enhance durability, UV resistance, and installation efficiency.
- Asia-Pacific will continue to dominate growth, supported by rapid urbanization and industrialization.
- Renovation and repair activities in developed regions will sustain market demand.
- Smart city and water management projects will create new opportunities.
- Competitive pricing and availability of skilled labor will remain critical to market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Construction and Infrastructure Investments
Rapid urbanization and increased government spending on infrastructure projects such as roads, bridges, and tunnels are fueling demand for waterproofing membranes to ensure durability and minimize maintenance costs.
Shift Toward Sustainable and Energy-Efficient Solutions
Growing emphasis on green building standards and energy efficiency is driving adoption of eco-friendly, solvent-free, and recyclable waterproofing membranes, especially in commercial and urban projects.
Technological Advancements and Product Innovation
Innovations in membrane formulations and application methods, such as self-adhesive and liquid-applied membranes, are improving installation efficiency, UV resistance, and long-term performance, expanding their use in complex and retrofitting projects.
Rising Demand for Moisture Protection in Residential and Commercial Projects
Increasing awareness of moisture-related structural damage and the need for long-lasting protection in both new construction and renovation projects are boosting the uptake of advanced waterproofing solutions.
Expansion in Asia-Pacific Markets
Rapid industrialization, urban development, and government-backed housing and infrastructure initiatives in China, India, and Southeast Asia are creating significant growth opportunities for waterproofing membrane manufacturers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Waterproofing Membranes Market?
At what Compound Annual Growth Rate is the Waterproofing Membrane Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Waterproofing Membrane Market?
Which Waterproofing Membrane Market segment held the largest share in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Residential
- 1.2.2 Commercial
- 1.2.3 Industrial
- 1.2.4 Infrastructure
- 1.3 By Material
- 1.3.1 Bitumen
- 1.3.2 Polymers
- 1.3.3 Rubber
- 1.3.4 Others
- 1.4 By Application
- 1.4.1 Roofing
- 1.4.2 Basement & foundation
- 1.4.3 Walls & facades
- 1.4.4 Landfills & tunnels
- 1.4.5 Others (balconies etc.)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 30.67 billion → 2032: USD 47.07 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Waterproofing Membranes Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Waterproofing Membranes Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Waterproofing Membranes Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Waterproofing Membranes Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Waterproofing Membranes Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Waterproofing Membranes Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Waterproofing Membranes Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Waterproofing Membranes Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 30.67 billion → 2032: USD 47.07 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Waterproofing Membranes Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential
- 12.3.7.2 Commercial
- 12.3.7.3 Industrial
- 12.3.7.4 Infrastructure
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Bitumen
- 12.4.7.2 Polymers
- 12.4.7.3 Rubber
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Roofing
- 12.5.7.2 Basement & foundation
- 12.5.7.3 Walls & facades
- 12.5.7.4 Landfills & tunnels
- 12.5.7.5 Others (balconies etc.)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Waterproofing Membranes End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Waterproofing Membranes Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Waterproofing Membranes Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Waterproofing Membranes Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Sika
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 BASF
- 18.4 Soprema
- 18.5 GAF Materials
- 18.6 Saint-Gobain
- 18.7 Dow
- 18.8 Pidilite Industries
- 18.9 Kemper System
- 18.10 Fosroc
- 18.11 Asian Paints
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

