
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Salad Container Market Size 2023 | USD 2,164.00 million |
| Salad Container Market, CAGR | 3.60% |
| Salad Container Market Size 2032 | USD 2,871.67 million |
Market Overview
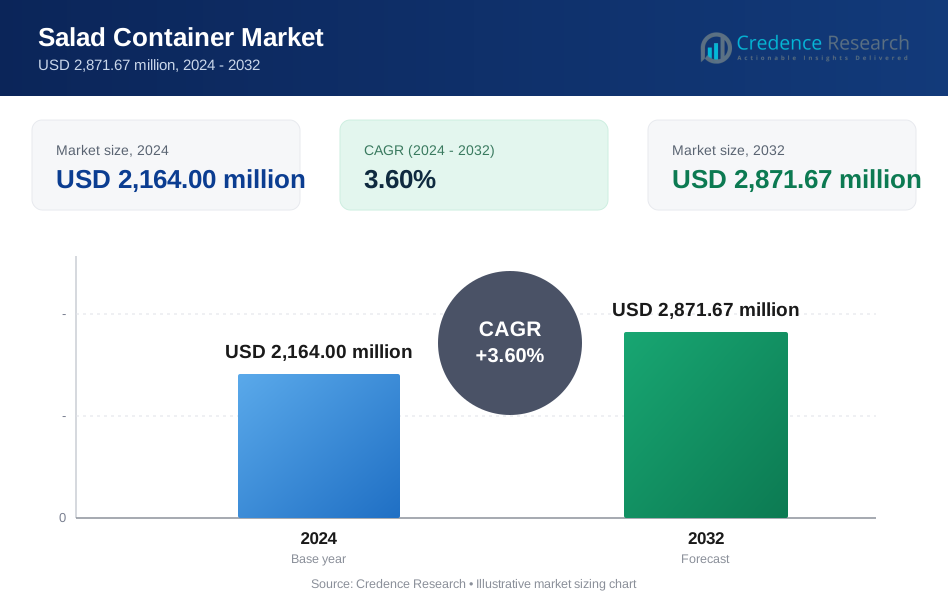
The Salad Container market is projected to grow from USD 2,164.00 million in 2024 to USD 2,871.67 million by 2032, at a compound annual growth rate (CAGR) of 3.60%.
The Salad Container market is driven by a rising consumer focus on healthy eating and the increasing popularity of on-the-go meal options. The demand for durable and eco-friendly salad containers is also accelerating as environmental awareness grows. Innovations in container design that enhance convenience, such as compartments for separate ingredients and improved sealants for freshness, are trending in the market. Additionally, the expansion of online food delivery services is boosting the need for high-quality salad containers, aligning with consumer preferences for convenience and sustainability. These factors collectively foster robust market growth.
The Salad Container market exhibits a strong geographical spread with significant growth in North America and Europe, driven by high consumer demand for convenience foods and sustainable packaging solutions. Asia-Pacific is rapidly emerging as a key market due to increasing urbanization and health consciousness among consumers. Key players such as Dart Container Corporation, Huhtamaki, and Sabert Corporation dominate the market, leveraging extensive distribution networks and innovative product offerings. These companies are instrumental in driving regional market dynamics and responding effectively to the evolving preferences and regulatory standards across different geographies.
Market Drivers
Rising Demand for Convenience Foods
The surge in demand for ready-to-eat and ready-to-cook meals, driven by busy lifestyles and increasing disposable incomes, is significantly boosting the market for salad containers. For instance, revenue in the Ready-to-Eat Meals market amounts to US$0.59tn in 2024. These containers offer a practical packaging solution for pre-packaged salads, aligning with the consumer's need for convenience and quick meal options. As more individuals opt for fast and easy food solutions, the role of durable and user-friendly salad containers becomes increasingly essential, catering to a fast-paced society that values efficiency and quality in food preparation and consumption.
Growing Health and Wellness Consciousness
Health and wellness consciousness among consumers is on the rise, with an increasing number of people seeking nutritious food options. Salads, widely recognized as healthy meal choices, require high-quality containers to maintain their freshness and nutritional value. For instance, 82% of US consumers now consider wellness a top or important priority in their everyday lives, which is similar to what consumers in the United Kingdom and China report (73% and 87% respectively). The demand for salad containers is thus not only driven by the need to preserve quality but also by the desire to support healthy lifestyle choices. As consumers become more health-conscious, the market for reliable and safe salad containers continues to expand, supporting the wellness trends that dominate food consumption habits.
Expanding Foodservice Industry and Innovation in Packaging Technology
The foodservice industry's growth, encompassing restaurants, cafes, and grocery stores, has heightened the need for effective packaging solutions like salad containers. For instance, the foodservice industry is forecast to reach $1 trillion in sales in 2024. These containers are crucial for serving fresh salads in various dining and retail settings, enhancing consumer experiences by ensuring quality and convenience. Additionally, advancements in packaging technology have introduced innovative features in salad containers, such as leak-proof designs, sustainable materials, and extended shelf life, further propelling market growth. Coupled with an increasing vegetarian and vegan population and a growing focus on sustainability, these innovations meet both consumer preferences and regulatory standards for food safety, driving the continuous evolution of the salad container market.
Increasing Urbanization and Nuclear Families
Urbanization and the proliferation of nuclear families have altered dietary habits, particularly among working professionals who demand convenience in their dining choices. Salad containers address this need by providing single-serving solutions that are convenient and tailored to individual use. The shift towards smaller family units and the increase in single-person households amplify the need for compact, practical food packaging, making salad containers an ideal choice for modern urban living.
Market Trends
Evolving Consumer Preferences and Sustainability Initiatives
Consumers are increasingly prioritizing eco-friendly packaging options, driving a shift towards biodegradable, compostable, and recyclable salad containers. This sustainability focus is not only a response to consumer demand but also aligns with global environmental objectives, pushing companies to invest in sustainable materials and green production processes. In parallel, the trend of premiumization is reshaping consumer expectations, where individuals are willing to pay more for high-quality, aesthetically pleasing salad containers. The demand for premium materials such as glass and ceramic is rising, complemented by innovative designs and features that offer product differentiation and add value to the consumer experience. These trends reflect a broader consumer shift towards products that combine sustainability with luxury, emphasizing the importance of environmental responsibility without compromising on design and quality.
Convenience, Customization, and Technological Integration
The increasing trend of on-the-go consumption has spurred the demand for compact, leak-proof containers, suitable for busy lifestyles. Multi-compartment containers that separate dressing and salad ingredients are becoming popular, reflecting the consumers' preference for convenience and functionality. For instance, the multi-compartment tank segment led the Tank Container market with a market share of around 25.09% in 2021. Additionally, lightweight materials are favored for their portability, catering to the needs of consumers who value practicality and ease of transport. Alongside convenience, customization is gaining traction in the market, with consumers seeking personalized packaging experiences. Salad containers offering options for branding and personalization are particularly popular in the foodservice industry, where differentiation is key. Moreover, transparency in packaging where consumers can view contents easily is becoming important, as it assures consumers of the freshness and quality of their food. This trend is further supported by the growth of e-commerce, which demands sturdy, secure packaging for delivery purposes. Together, these trends ranging from advanced sustainability efforts to the integration of smart packaging technologies that provide traceability and freshness indicators underscore a dynamic market environment where consumer preferences and technological advancements drive continuous innovation and market growth.
Market Challenges Analysis
Competition, Consumer Demands, and Supply Chain Vulnerabilities
Intense competition within the salad container industry pressures manufacturers to innovate while managing price competitiveness. Differentiating products and building brand loyalty are crucial for standing out in a crowded market, requiring strategic marketing and continuous product development. For instance, the cost of shipping a 40ft container in March 2023 was around $3,162, around double that when compared to just a year before. Moreover, evolving consumer preferences dictate packaging design and material choices, necessitating a proactive approach to trend analysis and product adaptation. Supply chain disruptions further complicate the landscape, as global issues can lead to material shortages and increased costs, emphasizing the need for resilient supply chains to mitigate risks effectively. Concurrently, the challenge of packaging waste and recycling demands innovative solutions for end-of-life management, aligning with consumer expectations and environmental regulations. Companies must also focus on consumer education to highlight the environmental impact and benefits of different packaging materials, ensuring informed choices and promoting sustainability.
Navigating Cost and Regulatory Landscapes
The salad container market faces significant challenges related to the rising costs of raw materials, especially sustainable options, which can erode profitability. Balancing the consumer demand for eco-friendly packaging with cost-effectiveness remains a persistent challenge, as manufacturers strive to develop affordable yet sustainable solutions. Additionally, regulatory compliance presents another complex hurdle. Adhering to stringent food safety and environmental regulations demands constant vigilance and adaptability to avoid penalties and ensure continuous market access. The evolving nature of these regulations requires companies to remain agile and informed, potentially increasing operational costs but ensuring safety and sustainability in production processes.
Market Segmentation Analysis:
By Material:
The Salad Container market is segmented by materials into plastic, paperboard, and aluminum, each catering to specific consumer needs and sustainability goals. Plastic containers, known for their durability and cost-effectiveness, continue to hold a significant market share. However, increasing environmental concerns are driving the demand for paperboard containers, which offer a biodegradable alternative that aligns with growing consumer preferences for sustainable packaging solutions. Aluminum containers, although less common, are valued for their recyclability and strength, making them suitable for a variety of packaging applications where barrier protection against moisture and light is critical.
By Container Type:
Regarding container types, the market offers a diverse range of products including plates and bowls, trays, clamshells, and cups. Plates and bowls are widely used due to their convenience and versatility, making them a popular choice for both fast casual dining and premium food services. Trays and clamshells are favored for their ability to accommodate complete meals in a compact and secure manner, ideal for takeout and delivery services. Cups are essential for side salads and smaller meal portions, catering to the demand for snack-sized food options. This segmentation allows manufacturers to cater specifically to the varied packaging needs of the food service industry, enhancing user experience and maintaining product integrity.
Segments:
Based on Material:
- Plastic
- Paperboard
- Aluminum
Based on Container Type:
- Plates and Bowls
- Trays
- Clamshell
- Cups
Based on End User:
- Restaurants
- Hotels and Lodgings
- Food Courts
- Online Food Delivery
- Others (hospitals, schools, offices, etc.)
- Households
Based on the Geography:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis
North America
North America dominates the market with a substantial 40% share, primarily due to the region's strong culture of on-the-go eating and increasing health consciousness. For instance, a survey conducted in 2023 revealed that 82% of respondents would be willing to pay more for products in sustainable packaging. The United States leads this segment, benefiting from a well-established quick-service restaurant industry and a growing demand for convenient, healthy meal options. The region's market is characterized by high demand for sustainable and recyclable salad containers, reflecting increasing consumer awareness of environmental issues. Canada follows closely, with a rising trend in plant-based diets contributing to the growth of the salad container market. The North American market also benefits from innovative packaging designs that focus on maintaining freshness, preventing leaks, and enhancing the overall user experience.
Europe
Europe holds the second-largest market share at 30%, with countries like the United Kingdom, Germany, and France at the forefront of salad container adoption. The European market is driven by stringent regulations on single-use plastics, prompting a shift towards eco-friendly packaging materials such as bioplastics and recycled content. The region has seen significant growth in the use of compartmentalized salad containers, catering to consumer preferences for customizable meal options
Key Player Analysis
- Eco-Products
- Huhtamaki
- Pactiv
- Dart Container Corporation
- Novolex
- Vegware
- Genpak
- Sabert Corporation
- Anchor Packaging
- Reynolds Consumer Products
- Be Green Packaging
- Fabri-Kal
- EarthChoice
- WinCup
- BSI Biodegradable Solutions
- World Centric
- BioPak
- StalkMarket
- Southern Champion Tray
- GreenGood
Competitive Analysis
In the competitive Salad Container market, leading players like Dart Container Corporation, Huhtamaki, and Sabert Corporation are setting industry standards with their extensive range of innovative and sustainable packaging solutions. Dart Container excels in providing a diverse array of plastic-based containers, known for their durability and cost-effectiveness. Huhtamaki focuses on eco-friendly paperboard options, catering to the rising consumer demand for sustainable products. Sabert Corporation combines innovation with sustainability, offering containers made from both traditional and compostable materials to meet diverse market needs. These companies maintain their competitive edge through continuous innovation, strategic global distribution networks, and responsive manufacturing practices. They actively engage in research and development to introduce advanced materials and designs that enhance the functionality and environmental friendliness of salad containers, effectively addressing the evolving preferences of consumers and regulatory requirements.
Recent Developments
- In September 2023, Dart Container Corporation invested in Red Leaf, securing exclusive rights to use Red Leaf’s alternative fiber generated from wheat straw residuals for its molded fiber foodservice packaging.
- In April 2024, Apollo Funds completed the acquisition of a majority stake in Reynolds Consumer Products.
- In January 2024, Genpak launched its new, sustainable molded fiber packaging line without intentionally added PFAS.
- In 2023, EarthChoice introduced nearly 80 sustainable packaging products including cups, hinged-lid containers, plates, and straws for disposable food service needs.
- In June 2023, WinCup announced it will transition its core traditional products, including foam cups, food containers, bowls, lids, and polypropylene straws, to its Vio® biodegradable technology platform.
Market Concentration & Characteristics
The Salad Container market is moderately concentrated, characterized by the presence of a few key players alongside numerous smaller companies that cater to niche markets. Leading firms like Dart Container Corporation, Huhtamaki, and Sabert Corporation hold significant market shares, leveraging their broad product portfolios and established distribution networks to exert substantial influence over market trends and pricing strategies. These major players drive innovation and set industry standards, particularly in developing eco-friendly and high-quality packaging solutions. However, the entry of new companies, especially those focusing on sustainable and innovative packaging options, is intensifying competition and gradually diluting market concentration. This dynamic encourages continuous product and technological advancements, ensuring that the market remains vibrant and responsive to evolving consumer demands and environmental regulations.
Report Coverage
The research report offers an in-depth analysis based on Material, Container Type, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increased adoption of biodegradable and compostable materials in response to growing environmental concerns.
- Expansion of product lines to include innovative designs that cater to on-the-go consumers and food delivery services.
- Enhancement of product durability and functionality to maintain freshness and extend shelf life.
- Growth in demand for customized and branded containers as businesses seek to differentiate their offerings.
- Rise in strategic partnerships and acquisitions among key players to expand geographical reach and product capabilities.
- Adoption of advanced manufacturing technologies to increase production efficiency and reduce waste.
- Expansion into emerging markets, particularly in Asia and Africa, driven by urbanization and changing consumer lifestyles.
- Introduction of smart packaging solutions that incorporate technology for freshness monitoring and consumer interaction.
- Increased focus on regulatory compliance and adaptation to global standards for food safety and packaging.
- Development of scalable and flexible supply chains to quickly respond to market changes and consumer demands.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Salad Container Market?
What factors are driving the growth of the Salad Container Market?
What are the key segments within the Salad Container Market?
What are some challenges faced by the Salad Container Market?
Who are the major players in the Salad Container Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Salad Container Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Salad Container Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,164.00 million → 2032: USD 2,871.67 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Salad Container Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Salad Container Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Salad Container Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Salad Container Market Drivers
- 3.3 Salad Container Market Restraints & Challenges
- 3.4 Salad Container Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Salad Container Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Salad Container Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Salad Container category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Salad Container Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Salad Container Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Salad Container market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Salad Container Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Salad Container Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Salad Container Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Salad Container (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Salad Container Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Salad Container Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Salad Container Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Salad Container Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Salad Container Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Salad Container Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Salad Container Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Salad Container Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Salad Container Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
