
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| U.S. Salad Dressing Market Size 2024 | USD 23,781.96 Million |
| U.S. Salad Dressing Market, CAGR | 4.50% |
| U.S. Salad Dressing Market Size 2032 | USD 35,342.26 Million |
Market Overview
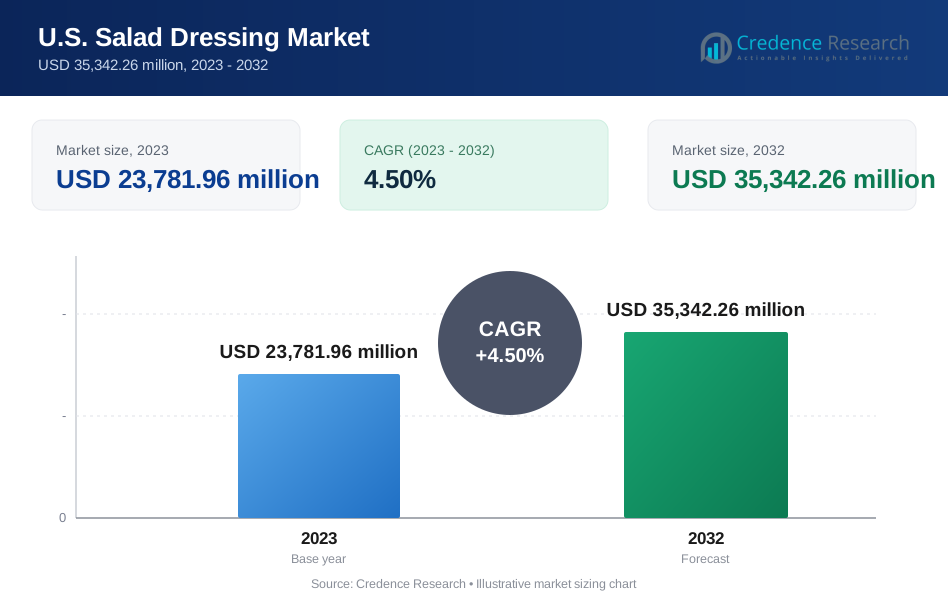
The U.S. Salad Dressing Market is projected to grow from USD 23,781.96 million in 2023 to USD 35,342.26 million by 2032, at a compound annual growth rate (CAGR) of 4.50%.
The U.S. salad dressing market is driven by increasing consumer demand for convenient, healthy, and versatile food options. With a growing focus on plant-based, organic, and clean-label products, consumers are opting for dressings that align with healthier lifestyles. The rise of online grocery shopping and the expanding availability of a wide variety of dressings in supermarkets are further boosting market growth. Additionally, the increasing popularity of international cuisines and flavors has led to a broader range of dressing options, from ethnic-inspired to gourmet varieties. The demand for low-calorie, sugar-free, and gluten-free alternatives is also influencing product innovation, attracting health-conscious consumers. Moreover, the growing trend of meal customization and the increasing adoption of salads as meal replacements are contributing to the market’s expansion. Together, these factors are shaping the future growth trajectory of the U.S. salad dressing market.
The U.S. salad dressing market is highly dynamic, with key players driving innovation and catering to diverse consumer preferences across various regions. Prominent companies such as Unilever PLC, Kraft Heinz, Hidden Valley, and Ken's Foods dominate the landscape, offering a wide range of products from traditional mayonnaise to organic and plant-based dressings. Regional preferences also play a significant role, with the Western U.S. favoring healthier, organic options, while the Southern U.S. leans towards bold and flavorful dressings. Manufacturers like Annie’s Homegrown and DUKE'S MAYONNAISE cater to the growing demand for natural, clean-label products, appealing to health-conscious consumers. Additionally, companies such as McCormick & Company and Hormel Foods Corporation continue to innovate with gourmet, ethnic-inspired dressings. As the market continues to expand, these key players are investing in product innovation and strategic partnerships to meet evolving consumer needs, ensuring a competitive edge in both retail and food service sectors.
Market Insights
- The U.S. salad dressing market was valued at USD 23,781.96 million in 2023 and is projected to reach USD 35,342.26 million by 2032, growing at a CAGR of 4.50%.
- Increasing consumer demand for healthier and clean-label options is driving market growth.
- Rising preference for plant-based and organic salad dressings is reshaping consumer choices.
- Ethnic-inspired and gourmet dressings are gaining traction as consumers seek new flavors.
- Market competition is intense, with major players like Unilever, Kraft Heinz, and Ken's Foods leading the industry.
- Raw material price fluctuations and supply chain challenges are key market restraints.
- The Western U.S. holds the largest market share, with strong demand for organic and plant-based products, while the Midwestern U.S. shows continued preference for traditional creamy dressings.
Market Drivers
Increasing Health Consciousness
A key driver of the U.S. salad dressing market is the growing focus on health and wellness among consumers. With rising awareness about the importance of a balanced diet, consumers are increasingly seeking healthier options, including low-fat, low-sugar, and organic salad dressings. For instance, a survey by the International Food Information Council (IFIC) found that 74% of U.S. consumers are actively trying to limit or avoid sugars in their diet. The shift toward healthier eating habits is encouraging manufacturers to innovate and offer products that cater to these preferences, such as dressings with clean labels, natural ingredients, and fewer preservatives.
Popularity of Plant-Based and Organic Products
The surge in demand for plant-based and organic products is another significant driver for the salad dressing market. As more consumers adopt vegetarian, vegan, and flexitarian diets, the need for plant-based alternatives to traditional dressings is growing. For example, a report by the Plant Based Foods Association (PBFA) highlighted that sales of plant-based foods in the U.S. grew by 27% in 2023. Organic and plant-based salad dressings are gaining popularity as they align with the broader trend toward sustainability and eco-friendly food choices. This shift in consumer preferences is prompting manufacturers to expand their product lines to include plant-based, dairy-free, and gluten-free dressings.
Convenience and Customization
Consumers’ preference for convenience in their food choices is also fueling the growth of the salad dressing market. With busy lifestyles, many individuals are opting for ready-to-use salad dressings that offer ease and quick preparation. Additionally, the trend of meal customization, where consumers can personalize their salads with a variety of dressings, has boosted the demand for a diverse range of options. Salad dressings are increasingly available in convenient packaging such as single-serve pouches and bottles, making it easier for consumers to incorporate them into their meals.
Expansion of Online Retail and Supermarket Availability
The increasing penetration of online grocery shopping and the widespread availability of salad dressings in supermarkets and convenience stores are driving market growth. E-commerce platforms provide consumers with access to a broader variety of dressings, allowing them to explore new flavors and products. The rise in online shopping is complemented by an enhanced presence of salad dressing brands in supermarkets, which are offering a greater assortment of dressings to cater to diverse consumer needs, thus expanding market accessibility and driving sales growth.
Market Trends
Shift Toward Healthier Ingredients
A notable trend in the U.S. salad dressing market is the increasing preference for healthier, cleaner ingredients. As consumers become more health-conscious, there is a growing demand for dressings made from natural, non-GMO, and organic ingredients. Brands are responding by offering dressings free from artificial additives, preservatives, and high fructose corn syrup. For instance, a survey by the International Food Information Council found that a significant number of consumers are actively seeking products with clean labels and natural ingredients. This trend is aligned with the broader clean-label movement, where consumers seek transparency and healthier alternatives in their food choices, driving product innovation in the market.
Rise of Plant-Based and Vegan Options
The rise of plant-based and vegan diets is significantly influencing the U.S. salad dressing market. As more consumers embrace vegan and flexitarian lifestyles, the demand for plant-based salad dressings has surged. These dressings often feature alternatives like avocado, almond, and coconut milk, replacing dairy and egg-based ingredients. Vegan salad dressings are now widely available in supermarkets and are being developed to offer the same rich flavors as traditional options, catering to the growing segment of consumers seeking plant-based food products.
Expansion of Global Flavors and Ethnic-Inspired Dressings
There is a growing trend towards incorporating global flavors and ethnic-inspired dressings into U.S. salad offerings. Consumers are increasingly seeking new taste experiences, driving the popularity of international salad dressings such as tahini, miso, and chimichurri. This trend is not only expanding the flavor variety in the market but also encouraging consumers to explore different cultures through food. The integration of bold, ethnic-inspired ingredients is helping salad dressing brands cater to adventurous eaters and those looking to diversify their meals.
Innovation in Packaging and Portion Control
Innovation in packaging and portion control is another key trend reshaping the U.S. salad dressing market. With consumers seeking convenience and practicality, brands are introducing smaller, single-serve portions, ideal for on-the-go consumption. These portable packages are perfect for busy individuals, meal preppers, and those seeking portion control. Additionally, eco-friendly packaging options, such as recyclable bottles and biodegradable pouches, are becoming increasingly popular, as environmentally conscious consumers prioritize sustainability in their purchasing decisions. This trend reflects a shift towards more sustainable, user-friendly products in the market.
Market Challenges Analysis
Rising Raw Material Costs
One of the primary challenges facing the U.S. salad dressing market is the increasing cost of raw materials. As the prices of key ingredients such as oils, spices, and organic produce rise, manufacturers are faced with higher production costs. This issue has been exacerbated by fluctuations in global supply chains, which affect the availability and pricing of essential components. Consequently, salad dressing brands may struggle to maintain competitive pricing while managing these rising costs. These challenges often lead to price hikes that may impact consumer purchasing behavior, especially among price-sensitive customers. Brands are under pressure to balance cost increases with consumer expectations for affordable and high-quality products.
Intense Market Competition and Consumer Preferences
The U.S. salad dressing market is highly competitive, with a wide array of established brands and new entrants vying for consumer attention. This intense competition has made it difficult for brands to differentiate themselves in the marketplace, as consumers are increasingly looking for innovative, unique, and healthier products. With the shift toward clean-label, organic, and plant-based options, traditional brands may face challenges in adapting their products to meet evolving consumer preferences. Additionally, the increasing demand for customizable food options, such as dressings tailored to specific dietary needs, creates further pressure for companies to innovate and keep up with rapidly changing trends. Brands must continuously invest in research and development to stay relevant, making it a challenge to maintain market share in a saturated landscape.
Market Opportunities
The U.S. salad dressing market presents significant opportunities for growth, particularly in the areas of health-conscious and specialty products. With an increasing number of consumers prioritizing wellness, there is a rising demand for healthier alternatives, such as low-fat, low-sodium, organic, and clean-label dressings. Manufacturers can capitalize on this trend by developing products that cater to dietary preferences like gluten-free, vegan, and allergen-free options. Additionally, the shift toward plant-based eating offers a unique opportunity to expand the plant-based dressing segment. By tapping into these consumer preferences, brands can meet the growing demand for nutritious, eco-friendly, and sustainable options, positioning themselves for long-term success in the market.
Another key opportunity lies in expanding the variety and flavor profiles of salad dressings to cater to evolving consumer tastes. The growing interest in international and ethnic cuisines presents a chance for innovation, with flavors like tahini, miso, and Sriracha becoming more popular among U.S. consumers. Brands can explore new product offerings inspired by global flavors and develop unique, bold dressings that appeal to adventurous eaters. Furthermore, as consumers seek convenience, there is an opportunity to invest in single-serve packaging and portion-controlled options that cater to busy lifestyles. By diversifying product ranges and incorporating these trends, brands can differentiate themselves and capture a larger share of the growing salad dressing market.
Market Segmentation Analysis:
By Type:
The U.S. salad dressing market is segmented by type into mayonnaise, sauce, oil-based dressings, gourmet salt, and others. Mayonnaise is one of the dominant segments, owing to its widespread popularity and versatility in both salads and sandwiches. It is particularly favored for its creamy texture and is commonly used in classic dressings like ranch and potato salad. Sauces are also a significant segment, as they cater to a variety of consumer preferences, ranging from creamy and tangy to spicy and savory options. Oil-based dressings, such as vinaigrettes, continue to grow in popularity due to their association with healthier eating habits, as they typically contain fewer calories and preservatives. Gourmet salt and other dressings, which include specialty options like organic and low-fat alternatives, are gaining traction as consumers look for more unique and health-conscious choices. These segments are increasingly influenced by trends such as clean-label, organic, and plant-based products.
By Distribution Channel:
In terms of distribution, the U.S. salad dressing market is divided into off-trade and on-trade channels. The off-trade segment, which includes retail stores and e-commerce platforms, holds a significant market share. This distribution channel benefits from a wide range of salad dressing products available in supermarkets, grocery stores, and online marketplaces, allowing consumers easy access to a variety of brands and types. E-commerce, in particular, has seen an uptick in popularity due to the convenience of online shopping and home delivery. On the other hand, the on-trade segment, which involves sales through food service providers such as restaurants, cafes, and catering services, also plays a crucial role in driving market demand. As more consumers dine out or opt for takeout meals, the demand for salad dressings in the on-trade sector continues to grow, especially with the rise of customizable salads and meal options. Both distribution channels are essential in meeting the diverse needs of the U.S. salad dressing market.
Segments:
Based on Type:
- Mayonnaise
- Sauce
- Oil-Based Dressings
- Gourmet Salt
- Others
Based on Distribution Channel:
- Off-Trade
- On-Trade
Based on End-User:
- Food Services Sector
- Household
Based on the Geography:
- Western United States
- Midwestern United States
- Southern United States
- Northeastern United States
Regional Analysis
Western United States
Western United States holds the largest market share at approximately 30%, driven by a strong demand for organic, healthy, and plant-based dressing options. Consumers in this region are increasingly health-conscious and environmentally aware, which has led to a shift towards clean-label and organic products. The region also enjoys a significant presence of health-focused food retailers, which contributes to the growth of the salad dressing market. Additionally, the growing popularity of ethnic and gourmet dressings in California and surrounding states adds to the region’s dominance in the market.
Midwestern United States
The Midwestern United States, which accounts for around 25% of the market share, is another key region for salad dressing sales. This region is known for its robust demand for traditional and creamy dressing options, such as ranch and blue cheese, which continue to be popular in Midwestern households. However, there has been a noticeable shift towards healthier alternatives in recent years, with consumers showing increased interest in low-fat and gluten-free dressings. The Midwestern market also benefits from a large number of food service establishments, including quick-service restaurants (QSRs), which serve as key channels for salad dressing consumption.
Southern United States
The Southern United States, contributing around 20% to the overall market share, exhibits a strong preference for flavorful and bold dressings, with regional varieties like honey mustard, barbecue, and vinaigrettes leading the way. As southern cuisine is rich in flavor, the demand for dressings that complement these robust flavors remains high. Health trends are also influencing consumer choices in the South, with more people opting for low-calorie and fat-free alternatives. The presence of major food manufacturers and a significant number of fast-casual dining establishments in the region further propels the market's growth.
Northeastern United States
The Northeastern United States, with a market share of approximately 25%, reflects a diverse consumer base that values both traditional and innovative salad dressings. The region’s strong urban presence, particularly in cities like New York and Boston, has fostered a growing interest in ethnic-inspired dressings and gourmet options. As more consumers in this area lean toward plant-based diets and organic products, there has been a notable increase in demand for vegan and clean-label dressings. Additionally, the Northeastern region benefits from a high density of food service establishments, which continue to drive dressing consumption in both residential and commercial sectors.
Key Player Analysis
- Unilever PLC
- American Garden (GEMCO Ltd)
- Annie’s Homegrown (General Mills)
- Cibona Foods
- DUKE'S MAYONNAISE
- Hidden Valley
- Ken's Foods
- Oetker KG
- Conagra Brands, Inc.
- Hormel Foods Corporation
- Kraft Heinz
- McCormick & Company, Inc.
- Southeastern Mills, Inc.
- Others
Competitive Analysis
The U.S. salad dressing market is highly competitive, with major players like Unilever PLC, Kraft Heinz, Hidden Valley, Ken's Foods, Conagra Brands, Hormel Foods Corporation, McCormick & Company, Annie’s Homegrown, DUKE'S MAYONNAISE, and Dr. Oetker KG. Many players are focusing on diversifying their product portfolios to meet the growing demand for healthier, organic, and plant-based options. This trend has resulted in a surge of clean-label products that appeal to health-conscious consumers. Additionally, brands are introducing ethnic-inspired and gourmet salad dressings to cater to the increasing consumer interest in diverse and unique flavors. With rising competition, companies are also targeting specific consumer segments, such as those seeking low-fat, gluten-free, or allergen-free dressings. The foodservice sector plays a crucial role, with several companies offering dressings tailored to restaurant chains and quick-service providers. Many market players are expanding their distribution networks through both traditional retail and e-commerce platforms to reach a wider customer base.
The competitive landscape also sees significant investments in brand positioning and marketing strategies. As consumer preferences continue to evolve, companies are under constant pressure to adapt quickly by offering innovative solutions that cater to the latest food trends while maintaining product quality and affordability. Thus, staying ahead of consumer demand and maintaining strong brand equity are critical for success in the U.S. salad dressing market.
Recent Developments
- In June 2022, Kewpie has recently redesigned and relaunched its website for the American market, https://www.kewpieshop.com. To promote the launch of the new website, Kewpie has created an "essentials" bundle that includes the two most popular products among consumers. The set includes Kewpie Mayonnaise and Deep Roasted Sesame Dressing.
- In 2022, Hellmann, a division of Unilever, introduced a new gravy mayonnaise that includes gravy-flavored Mayo. Reportedly, the new product is used as a dipping sauce for chips and chicken products.
- In March 2022, Unilever's Hellmann's brand launched a new gravy mayonnaise, including gravy-flavored Mayo. The new condiment is the first of its kind and is part of a new trio of flavors that also includes Coronation and Chilli Charger.The company claims it is the perfect dipping sauce for chicken and chips.
Market Concentration & Characteristics
The U.S. salad dressing market is moderately concentrated, with a few dominant players holding significant market shares. These companies have established strong brand identities and distribution channels that enable them to cater to both retail and foodservice sectors. However, the market is also characterized by a growing number of small and niche players that offer specialized products such as organic, plant-based, and allergen-free dressings. These emerging brands focus on health-conscious consumers, tapping into the increasing demand for clean-label and organic food products. The presence of large, well-established companies ensures a competitive environment, driving continuous innovation in terms of flavor, packaging, and product offerings. The market is highly fragmented when it comes to product types, with a wide variety of options available to cater to diverse consumer preferences. These range from traditional creamy dressings, such as ranch and blue cheese, to oil-based vinaigrettes, ethnic-inspired flavors, and gourmet dressings. This variety, along with the increasing trend towards personalization and healthier alternatives, further contributes to the market's dynamic nature. Additionally, the growing emphasis on sustainability, with many brands adopting eco-friendly packaging and sourcing practices, is influencing the competitive landscape. The market's concentration reflects both the dominance of established players and the rise of innovative, health-focused brands.
Report Coverage
The research report offers an in-depth analysis based on Type, Distribution Channel, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The U.S. salad dressing market is expected to grow steadily, driven by increasing consumer demand for healthier and organic options.
- Plant-based and vegan salad dressings are projected to see significant growth as more consumers adopt plant-based diets.
- Clean-label products with minimal ingredients and no artificial additives will continue to gain popularity.
- Ethnic-inspired flavors and gourmet dressings will see higher demand as consumers seek unique and diverse options.
- The rise of e-commerce and online grocery shopping will play a crucial role in the distribution of salad dressing products.
- Innovative packaging, including eco-friendly and sustainable options, will become a key differentiator for brands.
- Health-conscious consumers will increasingly opt for low-fat, low-sodium, and gluten-free dressings.
- Foodservice channels, including restaurants and quick-service chains, will continue to be an important growth driver.
- Companies are expected to focus on enhancing product quality and flavor to stay competitive in the market.
- The market will witness more collaborations and partnerships, with brands exploring new distribution opportunities and product innovations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Health Consciousness
Consumers are seeking healthier salad dressing options, such as low-fat, low-sugar, organic, and clean-label products, driving manufacturers to innovate and expand their offerings to meet these preferences.
Popularity of Plant-Based and Organic Products
The rise in vegetarian, vegan, and flexitarian diets is fueling demand for plant-based and organic salad dressings, prompting brands to develop dairy-free, gluten-free, and eco-friendly alternatives.
Convenience and Customization
Busy lifestyles and the trend toward meal personalization are boosting demand for ready-to-use dressings in convenient packaging, as well as a wider variety of flavors and portion-controlled options.
Expansion of Online Retail and Supermarket Availability
The growth of e-commerce and broader supermarket assortments are making it easier for consumers to access a diverse range of salad dressings, supporting market expansion and brand discovery.
Innovation in Flavors and Ethnic-Inspired Dressings
Consumer interest in global cuisines and unique taste experiences is driving the introduction of ethnic-inspired and gourmet dressings, expanding the market and attracting adventurous eaters.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Salad Dressing market?
What factors are driving the growth of the U.S. Salad Dressing market?
What are the key segments within the U.S. Salad Dressing market?
What are some challenges faced by the U.S. Salad Dressing market?
Who are the major players in the U.S. Salad Dressing market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Mayonnaise
- 1.2.2 Sauce
- 1.2.3 Oil-Based Dressings
- 1.2.4 Gourmet Salt
- 1.2.5 Others
- 1.3 By End-User
- 1.3.1 Food Services Sector
- 1.3.2 Household
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 23,781.96 million → 2032: USD 35,342.26 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Salad Dressing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Salad Dressing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Salad Dressing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Salad Dressing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Salad Dressing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Salad Dressing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Salad Dressing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Salad Dressing Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 23,781.96 million → 2032: USD 35,342.26 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Salad Dressing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Mayonnaise
- 12.3.7.2 Sauce
- 12.3.7.3 Oil-Based Dressings
- 12.3.7.4 Gourmet Salt
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Food Services Sector
- 12.4.7.2 Household
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Salad Dressing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 U.S. Salad Dressing Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 U.S. Salad Dressing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 U.S. Salad Dressing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Unilever PLC
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Kraft Heinz
- 18.4 Hidden Valley
- 18.5 Ken's Foods
- 18.6 Annie’s Homegrown (General Mills)
- 18.7 DUKE'S MAYONNAISE
- 18.8 McCormick & Company, Inc.
- 18.9 Hormel Foods Corporation
- 18.10 Conagra Brands, Inc.
- 18.11 Dr. Oetker KG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
