
Market Overview
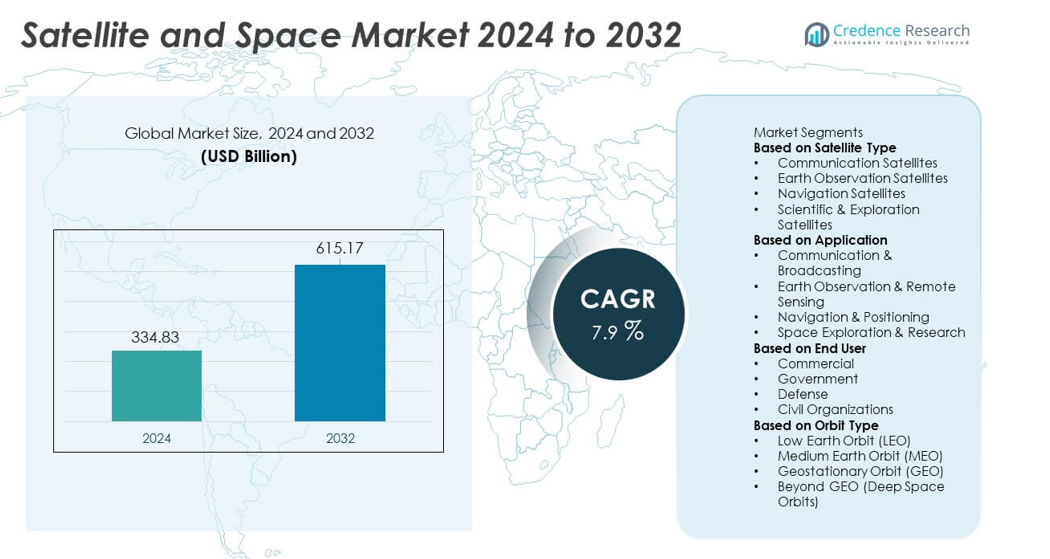
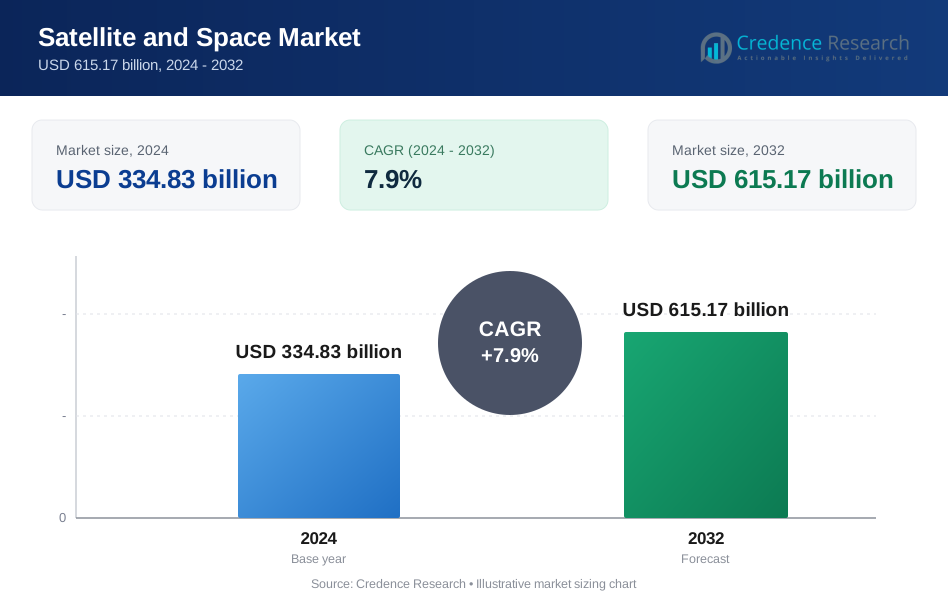
The Satellite and Space market reached USD 334.83 billion in 2024 and is projected to grow to USD 615.17 billion by 2032, reflecting a CAGR of 7.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Satellite and Space market Size 2024 | USD 334.83 billion |
| Satellite and Space market, CAGR | 7.9% |
| Satellite and Space market Size 2032 | USD 615.17 billion |
The satellite and space market is driven by leading players such as SpaceX, Airbus Defence and Space, Lockheed Martin Corporation, Boeing Defense, Space & Security, Northrop Grumman Corporation, Thales Alenia Space, Maxar Technologies, Blue Origin, CASC, and ISRO, all of which expand capabilities through advanced satellite manufacturing, high-throughput communication systems, and reliable launch services. These companies invest in reusable rockets, large satellite constellations, and high-resolution imaging technologies to address rising global demand for broadband, navigation, and Earth observation data. Regionally, North America leads the market with 38% share, supported by strong government programs and private-sector innovation, while Asia Pacific follows with 29% share, driven by expanding national space missions and rapid digital adoption.
Market Insights
- The Satellite and Space market reached USD 334.83 billion in 2024 and will grow at a CAGR of 7.9% through 2032, supported by rising demand for connectivity and advanced satellite systems.
- Key drivers include growing investments in communication satellites, expanding Earth observation needs, and increasing government funding for national security, climate monitoring, and deep-space missions.
- Major trends include rapid growth of LEO mega-constellations, advancements in reusable launch vehicles, and rising commercial participation in satellite manufacturing, broadband services, and space exploration programs.
- Competitive activity intensifies as players such as SpaceX, Airbus, Lockheed Martin, Thales Alenia Space, and Maxar Technologies invest in high-throughput satellites, imaging technologies, and cost-efficient launch solutions.
- Regionally, North America leads with 38% share, followed by Asia Pacific at 29% and Europe at 27%. Segment-wise, communication satellites dominate with 44% share, while communication and broadcasting applications hold 41%, and the commercial end-user segment accounts for 48% across the global market.
Market Segmentation Analysis:
By Satellite Type
Communication satellites lead the segment with 44% share, driven by rising demand for broadband connectivity, growing adoption of IoT networks, and expanding use of high-throughput satellites for commercial and government communication needs. These satellites support data transmission, broadcasting, and real-time communication across remote and underserved regions. Earth observation satellites grow steadily due to increasing applications in agriculture, climate monitoring, and disaster management, while navigation satellites strengthen global positioning services. Scientific and exploration satellites continue to support deep-space missions and research programs. Continuous investment in advanced payloads and low-latency communication systems sustains the dominance of communication satellites.
- For instance, SpaceX boosted satellite capacity through Starlink Gen2, which carries approximately 96 Gbps of bandwidth per V2 Mini satellite and uses advanced phased-array antennas.
By Application
Communication and broadcasting dominate with 41% share, supported by strong demand for satellite TV, broadband services, secure communication networks, and mobility-based connectivity for aviation and maritime sectors. The shift toward high-speed satellite internet and global expansion of direct-to-home services drives steady adoption. Earth observation and remote sensing applications rise due to their use in defense surveillance, environmental monitoring, and commercial analytics. Navigation and positioning remain vital for transportation, autonomous systems, and precision mapping. Space exploration and research gain momentum as agencies and private companies invest in lunar missions and deep-space programs, broadening long-term growth opportunities.
- For instance, Maxar strengthened the remote sensing segment with its WorldView Legion satellites, designed to capture up to 15 revisits per day over key areas using 30 cm-class sensors.
By End User
The commercial segment holds the largest share at 48%, driven by rising demand for satellite broadband, imaging services, navigation support, and data-driven commercial applications. Private companies invest heavily in constellation launches, reusable rockets, and satellite-as-a-service models that expand accessibility. Government agencies remain key users for weather forecasting, public communication, and national space programs. Defense users rely on satellites for surveillance, secure communication, and navigation accuracy, contributing to steady procurement cycles. Civil organizations adopt satellite services for environmental protection, disaster response, and scientific research. Growing public–private partnerships and expanding commercial investments continue to reinforce the leadership of the commercial segment.
Key Growth Driver
Rising Demand for Global Connectivity
Growing demand for high-speed connectivity fuels strong adoption of communication satellites, especially in underserved and remote regions. Broadband expansion, 5G backhaul support, and rising IoT device integration increase the need for reliable satellite networks. Companies invest in high-throughput and low-earth-orbit constellations to enhance data capacity and reduce latency. Aviation, maritime, and mobility sectors depend on satellite communication for continuous coverage. As digital services expand and connectivity becomes essential for economic growth, satellite networks play a central role in bridging infrastructure gaps and meeting global communication needs.
- For instance, SES strengthened global connectivity with its O3b mPOWER constellation, deploying satellites capable of delivering up to 10,000 Mbps per beam.
Expansion of Earth Observation and Data Analytics
Earth observation satellites gain momentum as governments and industries rely on high-resolution imaging for agriculture, environmental monitoring, disaster response, and defense applications. Increased demand for climate intelligence, weather forecasting, and resource mapping drives the deployment of advanced remote-sensing satellites. Commercial users adopt satellite analytics for logistics, energy management, and urban planning. Technological advancements in synthetic aperture radar, hyperspectral imaging, and cloud-based analytics enhance data accuracy and real-time insights. As reliance on space-based intelligence rises, the Earth observation segment becomes a key driver of market growth.
- For instance, Planet Labs expanded monitoring capabilities with more than 200 Dove satellites capturing up to 1.2 million sq km of imagery daily at 3–5 meter resolution.
Growth of Space Exploration and Commercial Launch Services
Space exploration accelerates with growing investments in lunar missions, deep-space research, and spacecraft development. Commercial launch providers expand reusable rocket programs to reduce launch costs and increase mission frequency. Governments collaborate with private companies to advance exploration capabilities and support scientific missions. Rising interest in asteroid mining, space tourism, and long-term space habitats boosts demand for launch services and spacecraft manufacturing. As space becomes more accessible, exploration initiatives create significant opportunities for innovation, partnerships, and market expansion across multiple segments.
Key Trend & Opportunity
Rise of Mega-Constellations and Low-Earth-Orbit Systems
Mega-constellations in low-earth orbit create new opportunities for global broadband coverage, low-latency communication, and large-scale IoT integration. Companies invest in thousands of small satellites to deliver seamless internet access and support digital transformation across industries. These constellations reduce dependency on traditional geostationary systems and enable new commercial services such as autonomous vehicle support and remote industrial monitoring. As deployment costs decline and manufacturing scales, LEO-based networks reshape the competitive landscape and present strong long-term growth opportunities.
- For instance, Amazon’s Project Kuiper advanced constellation deployment by producing satellites using automated lines capable of assembling up to 5 satellites per day at peak capacity, each supporting 100 Gbps bandwidth per optical inter-satellite link.
Increased Commercialization and Private Sector Participation
Commercial players increasingly dominate satellite manufacturing, launch services, and data solutions, driving innovation and reducing operational costs. Private companies introduce flexible satellite platforms, reusable rockets, and satellite-as-a-service models that expand accessibility for businesses and governments. Venture capital investment supports startups developing navigation systems, imaging technologies, and space-based communication solutions. As commercialization accelerates, collaboration between public and private entities creates new opportunities in exploration, defense modernization, and global connectivity services.
- For instance, Rocket Lab improved commercial launch access by flying more than 70 Electron missions with payload capacities reaching 320 kg per launch.
Key Challenge
High Launch Costs and Capital-Intensive Infrastructure
The satellite and space market faces high financial barriers due to expensive launch operations, manufacturing costs, and ground infrastructure requirements. Despite advancements in reusable rockets, many small and emerging players struggle to enter the market. Long development cycles, technical risks, and high insurance costs further elevate operational challenges. These financial pressures limit scalability and slow expansion for companies that lack substantial investment backing. Managing cost efficiency while maintaining performance and reliability remains a core challenge.
Space Debris and Regulatory Constraints
Increasing satellite deployments create rising concerns about space debris, orbital congestion, and collision risks. Regulatory bodies impose strict guidelines for satellite disposal, orbital management, and spectrum allocation, increasing compliance burdens for operators. Coordination across nations remains complex, slowing deployment timelines. Debris-related risks threaten operational continuity and raise long-term sustainability concerns for both commercial and government missions. As space activity accelerates, balancing innovation with regulatory and environmental safeguards becomes a fundamental challenge for the industry.
Regional Analysis
North America
North America holds 38% share of the satellite and space market, driven by strong government funding, advanced space programs, and high commercial participation. The United States leads with extensive investments in satellite communication, national security systems, Earth observation projects, and deep-space exploration missions. Major aerospace companies and launch service providers expand LEO constellations, reusable rockets, and satellite-based broadband networks. Growing demand for defense surveillance, climate monitoring, and high-speed connectivity further strengthens regional dominance. Canada contributes through remote sensing programs and communication satellite development. Strong technological capabilities and space innovation ecosystems maintain North America’s leadership.
Europe
Europe accounts for 27% share, supported by strong institutional programs, collaborative research initiatives, and expanding commercial satellite activities. The European Space Agency (ESA) invests in Earth observation, navigation, and scientific missions that enhance regional technological strength. Countries such as Germany, France, and the United Kingdom lead satellite manufacturing, launch vehicle development, and advanced remote-sensing capabilities. Growing interest in sustainable space operations and regulatory frameworks strengthens regional competitiveness. Commercial players expand services in broadband, imaging, and navigation systems. Europe’s combined public–private investments and focus on strategic autonomy continue to drive stable growth in the satellite and space sector.
Asia Pacific
Asia Pacific holds 29% share, driven by rapid satellite deployment, strong government initiatives, and growing commercial launch activity. China and India lead the region with ambitious space programs, expanding launch capabilities, and large-scale satellite constellations supporting communication, navigation, and imaging. Japan and South Korea contribute through advanced R&D programs and commercial satellite solutions. Rising demand for broadband connectivity, disaster management tools, and agricultural monitoring accelerates adoption. Increasing investment from private companies strengthens innovation and manufacturing capacity. With large populations and fast-growing digital economies, Asia Pacific remains one of the most dynamic regions in the satellite and space market.
Latin America
Latin America captures 4% share, supported by rising demand for satellite broadband, remote sensing, and national security applications. Countries such as Brazil, Argentina, and Mexico expand satellite programs to strengthen communication networks and improve rural connectivity. Governments invest in Earth observation systems for agriculture, environmental monitoring, and climate risk management. Growing partnerships with global space agencies and private companies enhance regional capabilities. Despite budget limitations and slower adoption compared to major regions, increasing digital transformation and infrastructure needs continue to support stable market growth across Latin America.
Middle East & Africa
The Middle East and Africa hold 2% share, driven by growing national space initiatives, rising communication needs, and expanding satellite-based services. Gulf countries such as the UAE and Saudi Arabia invest heavily in satellite manufacturing, space exploration missions, and geospatial intelligence. Africa shows increasing adoption of satellite broadband and Earth observation tools to support agriculture, disaster response, and connectivity in remote areas. Regional governments collaborate with international space agencies to develop local capabilities. Although infrastructure challenges persist, rising digitalization and strategic national programs support long-term market development.
Market Segmentations:
By Satellite Type
- Communication Satellites
- Earth Observation Satellites
- Navigation Satellites
- Scientific & Exploration Satellites
By Application
- Communication & Broadcasting
- Earth Observation & Remote Sensing
- Navigation & Positioning
- Space Exploration & Research
By End User
- Commercial
- Government
- Defense
- Civil Organizations
By Orbit Type
- Low Earth Orbit (LEO)
- Medium Earth Orbit (MEO)
- Geostationary Orbit (GEO)
- Beyond GEO (Deep Space Orbits)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis shows a strong presence of major players such as SpaceX, Airbus Defence and Space, Lockheed Martin Corporation, Boeing Defense, Space & Security, Northrop Grumman Corporation, Thales Alenia Space, Maxar Technologies, Blue Origin, CASC, and ISRO. These organizations strengthen the market through advanced satellite manufacturing, high-frequency launch capabilities, and expanding involvement in Earth observation, communication networks, and space exploration missions. Leading companies invest heavily in reusable launch systems, next-generation satellite constellations, and high-throughput communication payloads to improve performance and reduce operational costs. Public–private partnerships support research, deep-space missions, and strategic national programs. Commercial players increasingly adopt satellite-as-a-service models, offering flexible access to imaging, broadband, and navigation solutions. Governments continue to drive demand through defense modernization, climate monitoring, and secure communication requirements. As competition intensifies, differentiation centers on launch reliability, technology innovation, constellation scaling, and sustainable space operations.
Key Player Analysis
- SpaceX
- Airbus Defence and Space
- Lockheed Martin Corporation
- Boeing Defense, Space & Security
- Northrop Grumman Corporation
- Thales Alenia Space
- Maxar Technologies
- Blue Origin
- China Aerospace Science and Technology Corporation (CASC)
- Indian Space Research Organisation (ISRO)
Recent Developments
- In November 2025, Indian Space Research Organisation (ISRO) launched GSAT‑7R (CMS‑03) - India’s heaviest communication satellite - to boost naval communications.
- In November 2025, ISRO was reported to be in a major expansion phase and had plans for seven launches before the end of the financial year in March 2026.
- In November 2025, Blue Origin unveiled plans for a super-heavy variant of New Glenn, designated New Glenn 9×4, aimed to serve deep-space, lunar and large satellite constellation launches.
Report Coverage
The research report offers an in-depth analysis based on Satellite Type, Application, End User, Orbit Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Satellite constellations in low-earth orbit will expand to support global broadband coverage.
- Reusable launch vehicles will reduce mission costs and increase launch frequency.
- Earth observation services will grow as demand for climate and agricultural data rises.
- Defense agencies will increase investments in surveillance and secure communication satellites.
- Commercial players will drive innovation in small satellites and satellite-as-a-service models.
- Space exploration missions will accelerate with new lunar and deep-space programs.
- Navigation and positioning services will improve accuracy through upgraded satellite networks.
- Green propulsion and sustainable space operations will gain importance to reduce orbital debris.
- Partnerships between governments and private firms will strengthen global space capabilities.
- Advanced imaging and AI-driven satellite analytics will enhance real-time decision-making for multiple industries.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Global Connectivity
The need for high-speed, reliable broadband in remote and underserved regions is driving investments in communication satellites and LEO mega-constellations, enabling global internet access and supporting digital transformation across industries.
Growth in Earth Observation and Data Analytics
Rising demand for high-resolution imaging for agriculture, environmental monitoring, disaster response, and defense is fueling the deployment of advanced Earth observation satellites and analytics platforms, supporting data-driven decision-making.
Commercialization and Private Sector Innovation
Increased participation from private companies is accelerating the development of reusable launch vehicles, flexible satellite platforms, and satellite-as-a-service models, reducing costs and expanding market accessibility for commercial and government users.
Rising Space Exploration and Launch Services
Growing investments in lunar missions, deep-space research, and commercial launch services are expanding the scope of space activities, creating new opportunities for spacecraft manufacturing, launch providers, and scientific research.
Advancements in Satellite Technology and Constellation Scaling
Technological progress in high-throughput satellites, phased-array antennas, and automated satellite manufacturing is enabling the rapid deployment of large-scale constellations, improving data capacity, reducing latency, and supporting new applications such as IoT and autonomous systems.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Satellite and Space market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Satellite and Space market projected to grow between 2025 and 2032?
Which Satellite and Space market segment held the largest share in 2024?
Which are the significant players leveraging the Satellite and Space market growth?
What are the primary factors fueling the growth of the Satellite and Space market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Commercial
- 1.2.2 Government
- 1.2.3 Defense
- 1.2.4 Civil Organizations
- 1.3 By Orbit Type
- 1.3.1 Low Earth Orbit (LEO)
- 1.3.2 Medium Earth Orbit (MEO)
- 1.3.3 Geostationary Orbit (GEO)
- 1.3.4 Beyond GEO (Deep Space Orbits)
- 1.4 By Application
- 1.4.1 Communication & Broadcasting
- 1.4.2 Earth Observation & Remote Sensing
- 1.4.3 Navigation & Positioning
- 1.4.4 Space Exploration & Research
- 1.5 By Satellite Type
- 1.5.1 Communication Satellites
- 1.5.2 Earth Observation Satellites
- 1.5.3 Navigation Satellites
- 1.5.4 Scientific & Exploration Satellites
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 334.83 billion → 2032: USD 615.17 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Satellite and Space Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Satellite and Space Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Satellite and Space Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Satellite and Space Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Satellite and Space Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Satellite and Space Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Satellite and Space Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Satellite and Space Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 334.83 billion → 2032: USD 615.17 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Satellite and Space Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Commercial
- 12.3.7.2 Government
- 12.3.7.3 Defense
- 12.3.7.4 Civil Organizations
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Orbit Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Low Earth Orbit (LEO)
- 12.4.7.2 Medium Earth Orbit (MEO)
- 12.4.7.3 Geostationary Orbit (GEO)
- 12.4.7.4 Beyond GEO (Deep Space Orbits)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Communication & Broadcasting
- 12.5.7.2 Earth Observation & Remote Sensing
- 12.5.7.3 Navigation & Positioning
- 12.5.7.4 Space Exploration & Research
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Satellite Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Communication Satellites
- 12.6.7.2 Earth Observation Satellites
- 12.6.7.3 Navigation Satellites
- 12.6.7.4 Scientific & Exploration Satellites
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Satellite and Space End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Satellite and Space Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Satellite and Space Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Satellite and Space Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 SpaceX
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Airbus Defence and Space
- 18.4 Lockheed Martin Corporation
- 18.5 Boeing Defense, Space & Security
- 18.6 Northrop Grumman Corporation
- 18.7 Thales Alenia Space
- 18.8 Maxar Technologies
- 18.9 Blue Origin
- 18.10 China Aerospace Science and Technology Corporation (CASC)
- 18.11 Indian Space Research Organisation (ISRO)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

