
Market Overview:
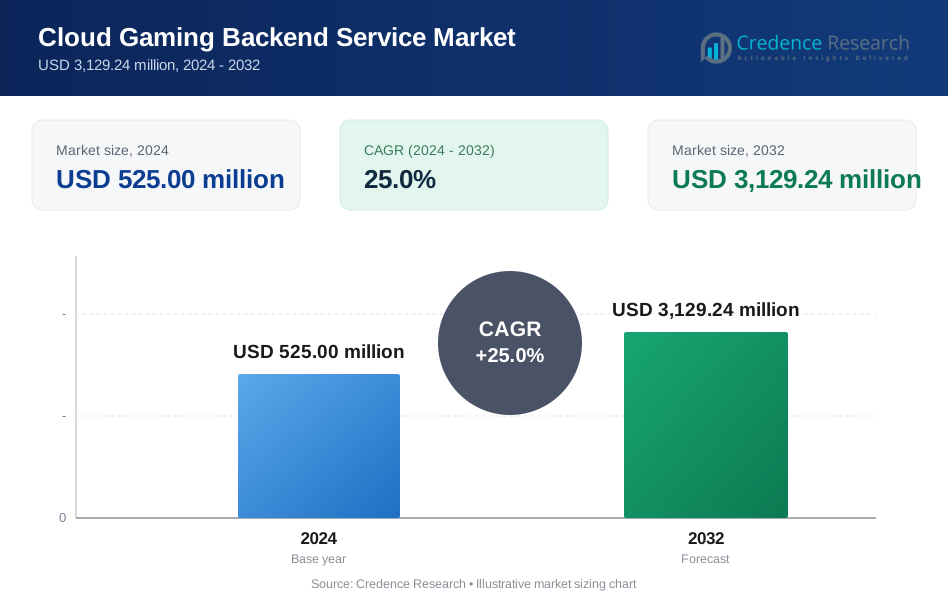
The Global Cloud Gaming Backend Service Market size was valued at USD 93.44 million in 2018 to USD 525.00 million in 2024 and is anticipated to reach USD 3,129.24 million by 2032, at a CAGR of 25.00% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cloud Gaming Backend Service Market Size 2024 | USD 525.00 million |
| Cloud Gaming Backend Service Market , CAGR | 25.00% |
| Cloud Gaming Backend Service Market Size 2032 | USD 3,129.24 million |
The market is gaining traction as gaming companies shift to cloud-based infrastructure to reduce hardware dependence and enhance user accessibility. High-speed internet penetration, widespread adoption of 5G, and rising smartphone usage are fueling growth. Cloud gaming services attract both casual and core gamers by removing upfront hardware costs, while developers benefit from scalable and cost-efficient platforms. Moreover, advancements in AI, real-time rendering, and cross-platform integration are enabling immersive experiences, creating strong momentum for backend service adoption globally.
Regionally, North America leads the market due to its advanced connectivity infrastructure and presence of major technology players driving adoption. Europe is also witnessing strong uptake, supported by government initiatives promoting digital transformation in gaming and entertainment sectors. Meanwhile, Asia-Pacific is emerging as the fastest-growing region, driven by the rapid rise of mobile gaming in countries like China, South Korea, and India. Latin America and the Middle East are showing steady adoption, supported by expanding internet coverage and growing youth gaming communities.

Market Insights:
- The Global Cloud Gaming Backend Service Market was valued at USD 93.44 million in 2018, reached USD 525.00 million in 2024, and is projected to reach USD 3,129.24 million by 2032, expanding at a CAGR of 25.0%.
- Asia Pacific holds the largest share at 48.3%, followed by North America at 27.5% and Europe at 16.7%, driven by advanced infrastructure, high digital penetration, and strong adoption by developers and enterprises.
- Asia Pacific is also the fastest-growing region, supported by rapid mobile gaming adoption, strong 5G expansion, and large consumer bases across China, India, South Korea, and Japan.
- Professional services represented the largest segment in 2024 with an estimated 35% share, supported by strong demand for consulting, deployment, and integration.
- Support and maintenance held nearly 25% share, reflecting steady demand for reliable updates, stability, and operational efficiency across gaming platforms.
Market Drivers:
Increasing Demand for Seamless Gaming Experiences Through Cloud Platforms
The Global Cloud Gaming Backend Service Market is expanding due to growing consumer demand for seamless and device-independent gaming. Players prefer instant access to advanced games without investing in high-end consoles or PCs. High-speed internet and 5G availability support low latency performance, making cloud gaming more attractive. Developers use backend services to manage large player bases with efficient scalability. Publishers reduce distribution costs by shifting to digital models powered by backend solutions. It supports real-time analytics, improving user engagement and personalization. Security and data management are also critical functions enabled through advanced backend systems. Growing acceptance of subscription-based models reinforces market momentum across various demographics.
- For instance, Microsoft confirmed at GDC 2025 that Xbox Cloud Gaming is available across 28 major markets, using automated hardware simulation to test real-world performance and reporting that its “Direct Capture” feature reduced input latency by 7–72 milliseconds per game, with latency improvements applying to nearly its entire game catalog as of 2025.
Rising Adoption of Smartphones and Connected Devices Across User Segments
The popularity of smartphones and smart TVs drives significant growth in the Global Cloud Gaming Backend Service Market. Mobile-first gaming strategies dominate regions with limited access to gaming consoles. Backend platforms offer flexible infrastructure, enabling developers to deliver quality experiences across multiple devices. Affordable internet plans and higher mobile penetration fuel accessibility for casual gamers. It creates opportunities for publishers to expand their audience base with minimal hardware dependency. Emerging markets rely heavily on mobile platforms, making backend scalability essential for consistent performance. Subscription services bundled with telecom plans extend access further, strengthening adoption. This environment positions backend providers at the center of gaming growth worldwide.
Strong Support from Technology Advancements in AI and Real-Time Rendering
The Global Cloud Gaming Backend Service Market benefits from rapid advances in AI and cloud infrastructure. AI-powered algorithms enable predictive performance, supporting stable gameplay under varying conditions. Real-time rendering capabilities reduce latency issues, improving player satisfaction. Backend providers invest in high-performance servers that handle complex graphics and workloads. It improves the feasibility of streaming high-end titles on low-spec devices. Cloud architecture also provides flexibility to developers to scale resources dynamically. Security technologies embedded in backend services safeguard user data and intellectual property. Innovation in graphics processing and AI integration makes the market highly attractive for investors. Continuous technological improvement remains a crucial growth driver.
- For instance, in January 2023, NVIDIA launched GeForce NOW Ultimate tier powered by RTX 4080-class GPUs, streaming at up to 240 frames per second with full ray tracing and DLSS 3, and achieving click-to-pixel latency below 40 milliseconds for cloud gamers.
Growing Popularity of Subscription-Based Gaming Services
The Global Cloud Gaming Backend Service Market gains momentum from the widespread adoption of subscription gaming models. Gamers prefer cost-effective monthly plans over upfront purchases of expensive consoles or games. Backend services handle account management, billing systems, and seamless updates. It ensures users experience uninterrupted access to large libraries without disruptions. Telecom operators and tech giants integrate gaming subscriptions into broader digital bundles, increasing reach. Backend providers offer real-time monitoring tools, enhancing transparency for publishers. This model allows consistent revenue streams for developers and stability for service providers. Growing customer loyalty through subscription frameworks strengthens long-term market potential globally.
Market Trends:
Expansion of Cross-Platform Gaming Experiences Supported by Backend Flexibility
Cross-platform gaming is becoming a dominant trend in the Global Cloud Gaming Backend Service Market. Gamers expect to continue progress seamlessly across mobile, PC, and console. Backend services provide the authentication, storage, and synchronization necessary for unified gameplay. It improves player retention by reducing friction across devices. Cross-platform titles also encourage social engagement, allowing multiplayer across varied hardware. Publishers use backend analytics to monitor patterns and enhance design for cross-device use. This flexibility is essential for developers targeting global audiences with different access points. Continuous focus on interoperability strengthens this trend across multiple regions.
Integration of Blockchain for Ownership and Transaction Transparency
The integration of blockchain drives a transformative trend in the Global Cloud Gaming Backend Service Market. Blockchain provides secure, verifiable ownership of digital assets and in-game purchases. It reduces fraud by offering transparent transaction records managed through backend services. Gamers gain confidence in purchasing unique skins, weapons, or digital property. It enhances trust between developers and players through decentralized platforms. Backend providers integrate smart contracts to automate payments and exchanges. This trend fuels secondary markets, creating new revenue models for developers. Integration with gaming ecosystems makes blockchain-backed backend solutions increasingly appealing.
- For example, Axie Infinity was developed by Sky Mavis, issuing all in-game assets as NFTs on Ethereum and its Ronin sidechain. The game experienced peak popularity in late 2021 and has surpassed $4 billion in lifetime NFT transaction volume.
Development of Cloud-Native Game Design and Distribution Models
Cloud-native game design is a rising trend in the Global Cloud Gaming Backend Service Market. Developers create titles optimized for streaming rather than local installation. Backend services support scalable design, allowing distribution across large user bases instantly. It reduces dependency on physical copies, creating efficiency in delivery. It also enables frequent updates and patches without user intervention. Game developers adopt continuous development cycles supported by backend cloud infrastructure. Cloud-native design broadens accessibility by reducing device requirements. This model positions backend services as indispensable to future gaming ecosystems.
- For example, Ubisoft’s Rainbow Six Siege operates under a continuous “live service” model, delivering global updates and anti-exploit patches programmatically. The publisher documents each deployment through official changelogs and support articles, confirming authentic use of backend infrastructure for real-time scaling and continuous delivery.
Growing Role of E-sports and Interactive Content in Cloud Gaming Adoption
Esports expansion influences the Global Cloud Gaming Backend Service Market with higher demand for real-time interactivity. Gamers expect smooth performance during competitive online events. Backend services provide real-time match data, spectator features, and instant replays. It enhances viewer engagement and monetization opportunities for organizers. Interactive streaming platforms integrate backend solutions for live chats and personalized content. Esports partnerships encourage infrastructure improvements that benefit cloud gaming broadly. Broadcasters use backend analytics to enhance engagement and advertising placement. Growing interest in interactive gaming content fuels backend demand globally.

Market Challenges Analysis:
Infrastructure Limitations and Network Dependency
The Global Cloud Gaming Backend Service Market faces challenges related to network reliability and infrastructure gaps. High-speed internet and 5G availability remain uneven across regions, limiting accessibility. It restricts adoption in developing countries where connectivity remains inconsistent. Latency issues undermine gameplay quality, leading to dissatisfaction among gamers. Backend providers must constantly upgrade servers to meet performance expectations. Costs of infrastructure development increase operational burdens for companies entering new markets. Limited coverage of fiber networks continues to challenge broad adoption. Addressing these network dependencies requires heavy investment and government support.
High Operating Costs and Data Security Concerns
The Global Cloud Gaming Backend Service Market also struggles with operating costs and security risks. Backend providers manage massive amounts of player data and payment information. It raises risks of cyberattacks and breaches, requiring constant monitoring. Security compliance adds costs that increase the financial burden for smaller providers. High server maintenance and energy consumption challenge profitability, especially during scaling. Gamers demand low prices, but service providers must balance cost efficiency with quality. Competition among providers also drives down margins in a demanding market. Sustainability of backend operations remains a pressing challenge for the industry.
Market Opportunities:
Expansion in Emerging Economies with Rising Internet Access
The Global Cloud Gaming Backend Service Market presents strong opportunities in emerging economies. Expanding broadband access and affordable smartphones drive adoption in Asia-Pacific, Latin America, and Africa. It enables millions of new users to access advanced games without costly hardware. Telecom partnerships expand access further through bundled data and gaming services. Backend providers gain long-term growth prospects by addressing these underserved regions. Developers targeting localized content also strengthen engagement among regional audiences. New user bases create sustainable demand for backend platforms globally.
Rising Scope of Cloud-Enabled AR and VR Gaming Applications
The Global Cloud Gaming Backend Service Market benefits from the growing potential of AR and VR. Backend services enable real-time rendering and data synchronization essential for immersive experiences. It allows AR and VR games to function effectively without high-end devices. Advancements in lightweight headsets and 5G networks enhance feasibility. Developers explore cloud-enabled mixed reality experiences for broader consumer segments. Partnerships between cloud providers and gaming studios expand AR and VR adoption. These innovations open lucrative opportunities for backend service growth worldwide.
Market Segmentation Analysis:
By type, the Global Cloud Gaming Backend Service Market by type shows strong growth across professional services, support and maintenance, access and identity management, usage analytics, and others. Professional services dominate with their role in deployment, customization, and consulting for game developers and publishers. Support and maintenance ensure operational efficiency and seamless updates, keeping platforms reliable for users. Access and identity management gain traction with the rising need for secure logins, authentication, and account handling. Usage analytics provides actionable insights on gamer behavior and preferences, allowing publishers to optimize content delivery. Other backend solutions address niche requirements, expanding flexibility and scalability for developers.
- For instance, Game Bear migrated its live gaming operations to Google Cloud, leveraging support services and advanced load balancing. The shift reduced network latency from 400–500 microseconds to 40 microseconds, cut disconnection rates from 5% to 0.5%, and eliminated data loss during peak traffic.
By end-user, the Global Cloud Gaming Backend Service Market reflects varied adoption across small and medium enterprises (SMEs) and large enterprises. SMEs rely on backend services to reduce infrastructure costs while reaching wider audiences through scalable platforms. Large enterprises dominate in revenue share with their ability to invest in advanced backend systems supporting high user volumes. It drives innovation by integrating artificial intelligence, cloud-native architectures, and security frameworks into service delivery. Both segments benefit from real-time monitoring, cross-platform compatibility, and scalable infrastructure. Growing emphasis on personalized gaming experiences ensures both SMEs and large enterprises continue to expand usage, strengthening the overall market.
- For instance, GameStake Technologies, an SME, cut cloud infrastructure costs by 25% and enabled zero-downtime deployments by adopting Kubernetes- and IaC-based backend solutions. This approach allowed the company to scale from 50,000 to millions of users with only a three-person engineering team, as documented in Massdriver's engineering case study.

Segmentation:
By Type
- Professional Services
- Support and Maintenance
- Access and Identity Management
- Usage Analytics
- Others
By End-User
- Small and Medium Enterprises (SMEs)
- Large Enterprises
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Global Cloud Gaming Backend Service Market size was valued at USD 26.00 million in 2018 to USD 143.69 million in 2024 and is anticipated to reach USD 860.23 million by 2032, at a CAGR of 25.1% during the forecast period. North America holds the largest share of the Global Cloud Gaming Backend Service Market, accounting for nearly 27.5% of total revenue. The region benefits from advanced internet infrastructure, high 5G penetration, and the strong presence of technology leaders. It attracts investments from gaming studios and cloud providers due to high consumer spending on digital entertainment. Esports popularity and a growing subscription model culture strengthen backend service adoption. Large enterprises deploy backend solutions at scale, while SMEs leverage them for cost efficiency. Regulatory compliance frameworks also encourage secure and scalable platforms. The market maintains its leadership by integrating AI-driven analytics, identity management, and cross-platform services.
Europe
The Europe Global Cloud Gaming Backend Service Market size was valued at USD 18.05 million in 2018 to USD 96.02 million in 2024 and is anticipated to reach USD 522.26 million by 2032, at a CAGR of 23.6% during the forecast period. Europe contributes nearly 16.7% of the overall Global Cloud Gaming Backend Service Market. Growth is supported by strong adoption in Western Europe, with Germany, the UK, and France leading demand. It benefits from government-backed digitalization programs and rising demand for streaming-based entertainment. Backend providers expand partnerships with telecom operators to integrate cloud gaming into bundled services. SMEs adopt backend services to expand reach, while established enterprises deploy advanced usage analytics. Cross-platform compatibility supports gaming across PCs, consoles, and mobile devices. Consumer demand for secure digital ecosystems boosts adoption of identity management solutions. Continuous investments in esports and online gaming ecosystems reinforce regional market growth.
Asia Pacific
The Asia Pacific Global Cloud Gaming Backend Service Market size was valued at USD 40.85 million in 2018 to USD 238.02 million in 2024 and is anticipated to reach USD 1,505.20 million by 2032, at a CAGR of 25.9% during the forecast period. Asia Pacific dominates with nearly 48.3% of the total Global Cloud Gaming Backend Service Market share. The region experiences strong adoption due to the rising mobile gaming population in China, India, South Korea, and Japan. It benefits from rapid digital infrastructure development and widespread smartphone penetration. Cloud-native gaming platforms thrive due to the low cost of internet services and strong demand for multiplayer games. Large enterprises partner with backend providers to scale immersive experiences quickly. SMEs find backend services critical for reaching wider audiences without hardware investments. Esports growth accelerates demand for secure and high-performance backend systems. The region’s scale and demographic diversity make it the fastest-growing hub for backend services globally.
Latin America
The Latin America Global Cloud Gaming Backend Service Market size was valued at USD 4.40 million in 2018 to USD 24.43 million in 2024 and is anticipated to reach USD 128.85 million by 2032, at a CAGR of 23.1% during the forecast period. Latin America contributes 4.1% of the Global Cloud Gaming Backend Service Market. The region benefits from expanding internet connectivity and increasing demand for mobile-based entertainment. Brazil and Mexico lead adoption with strong youth-driven gaming communities. It gains traction from telecom partnerships that include gaming subscriptions in bundled plans. SMEs use backend services to scale without large upfront investments. Large enterprises focus on building cross-platform ecosystems to attract users. The demand for usage analytics and secure identity management is rising steadily. Despite infrastructure challenges, growing internet access and consumer preference for affordable gaming platforms fuel market growth.
Middle East
The Middle East Global Cloud Gaming Backend Service Market size was valued at USD 2.63 million in 2018 to USD 13.50 million in 2024 and is anticipated to reach USD 67.96 million by 2032, at a CAGR of 22.4% during the forecast period. The Middle East accounts for 2.2% of the Global Cloud Gaming Backend Service Market. Regional growth is driven by rising youth populations, increasing smartphone usage, and expanding internet penetration. Countries like Saudi Arabia, UAE, and Israel are emerging as key adopters. It benefits from government-led initiatives to diversify economies through digital entertainment. Esports events and gaming investments create new opportunities for backend providers. Enterprises adopt backend services to deliver high-quality interactive experiences. SMEs leverage cost-effective platforms for wider regional penetration. Infrastructure expansion supports gradual market maturity across the Middle East.
Africa
The Africa Global Cloud Gaming Backend Service Market size was valued at USD 1.51 million in 2018 to USD 9.34 million in 2024 and is anticipated to reach USD 44.76 million by 2032, at a CAGR of 21.6% during the forecast period. Africa contributes 1.4% of the Global Cloud Gaming Backend Service Market. Growth is supported by improving broadband connectivity and rising smartphone penetration across countries such as South Africa, Nigeria, and Egypt. It remains at an early stage but shows strong future potential as infrastructure improves. SMEs rely on backend platforms for affordable entry into the gaming ecosystem. Large enterprises are beginning to explore backend adoption in markets with stable internet. The demand for mobile-first gaming models supports backend usage. Identity management and security solutions are gaining importance due to growing online transactions. Expansion of telecom partnerships is expected to enhance adoption across Africa.
Key Player Analysis:
- brainCloud
- ChilliConnect
- PlayFab
- Google Cloud
- Amazon Web Services (AWS)
- SpatialOS (Improbable Worlds Ltd.)
- Tavant Technologies
- Microsoft Azure
- IBM Cloud
- NVIDIA
Competitive Analysis:
The Global Cloud Gaming Backend Service Market features strong competition among technology giants and specialized service providers. Leading companies such as Google Cloud, AWS, Microsoft Azure, and IBM Cloud dominate with robust infrastructure and scalable solutions. It leverages their global data centers to deliver low-latency, secure, and high-performance services. Specialized platforms like PlayFab, brainCloud, and ChilliConnect focus on developer-centric tools, usage analytics, and seamless integration for game studios. NVIDIA expands its position through advanced GPU-powered cloud services supporting real-time rendering. SpatialOS strengthens the ecosystem by enabling large-scale multiplayer capabilities. Tavant Technologies supports enterprises with tailored backend frameworks. Competition remains intense as firms invest in AI integration, cross-platform compatibility, and subscription partnerships. Market players pursue mergers, acquisitions, and regional expansions to strengthen portfolios and gain strategic advantage. The balance between global scale and niche expertise defines the evolving competitive landscape.
Recent Developments:
- In March 2025, Xsolla and AWS entered into a key partnership designed to empower game developers with the latest advancements in cloud gaming and LiveOps solutions. The collaboration leverages AWS’s cloud infrastructure and Xsolla’s developer platform to create scalable, flexible backend solutions, further strengthening their positions in the expanding global cloud gaming backend service sector.
- In July 2024, Xsolla announced the acquisition of LF.Group to enhance gaming connectivity and commerce, empower creators, and improve user engagement across multiple platforms. This strategic move aims to give Xsolla a stronger foothold in the global cloud gaming backend service market by integrating LF.Group's technology stack and community features into its existing offerings, driving forward innovation in backend solutions for cloud gaming environments.
Report Coverage:
The research report offers an in-depth analysis based on type and end-user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Global Cloud Gaming Backend Service Market will expand with rising demand for cross-platform experiences.
- Subscription-based gaming models will gain more adoption, strengthening backend service usage worldwide.
- AI integration will enhance predictive analytics, improving personalization and gameplay optimization.
- Real-time rendering will support immersive AR and VR applications powered by backend services.
- Strong partnerships between telecom operators and gaming providers will accelerate regional adoption.
- Security and identity management will remain a top priority, driving innovation in backend solutions.
- Esports growth will create demand for scalable backend services supporting interactive features.
- SMEs will increasingly adopt backend platforms to reduce infrastructure costs and expand reach.
- Large enterprises will continue to invest in cloud-native designs, ensuring sustainable market leadership.
- Emerging markets with rising internet penetration will offer lucrative opportunities for long-term growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Cloud Gaming Backend Service Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Cloud Gaming Backend Service Market projected to grow between 2024 and 2032?
What are the primary factors fueling the growth of the Global Cloud Gaming Backend Service Market?
Who are the leading companies in the Global Cloud Gaming Backend Service Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cloud Gaming Backend Service Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cloud Gaming Backend Service Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 525.00 million → 2032: USD 3,129.24 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cloud Gaming Backend Service Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cloud Gaming Backend Service Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cloud Gaming Backend Service Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cloud Gaming Backend Service Market Drivers
- 3.3 Cloud Gaming Backend Service Market Restraints & Challenges
- 3.4 Cloud Gaming Backend Service Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cloud Gaming Backend Service Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cloud Gaming Backend Service Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cloud Gaming Backend Service category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cloud Gaming Backend Service Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Cloud Gaming Backend Service Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Cloud Gaming Backend Service market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cloud Gaming Backend Service Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cloud Gaming Backend Service Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Cloud Gaming Backend Service Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cloud Gaming Backend Service (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Cloud Gaming Backend Service Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cloud Gaming Backend Service Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Cloud Gaming Backend Service Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cloud Gaming Backend Service Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cloud Gaming Backend Service Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cloud Gaming Backend Service Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cloud Gaming Backend Service Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cloud Gaming Backend Service Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cloud Gaming Backend Service Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
