
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
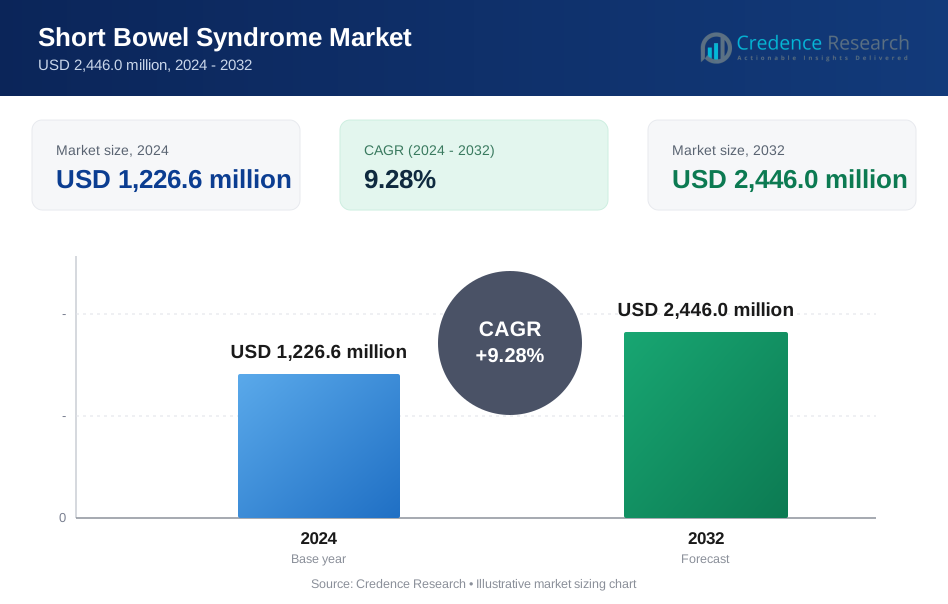
| Short Bowel Syndrome Market Size 2024 | USD 1,226.6million |
| Short Bowel Syndrome Market, CAGR | 9.28% |
| Short Bowel Syndrome Market Size 2032 | USD 2,446.0 million |
Market Overview:
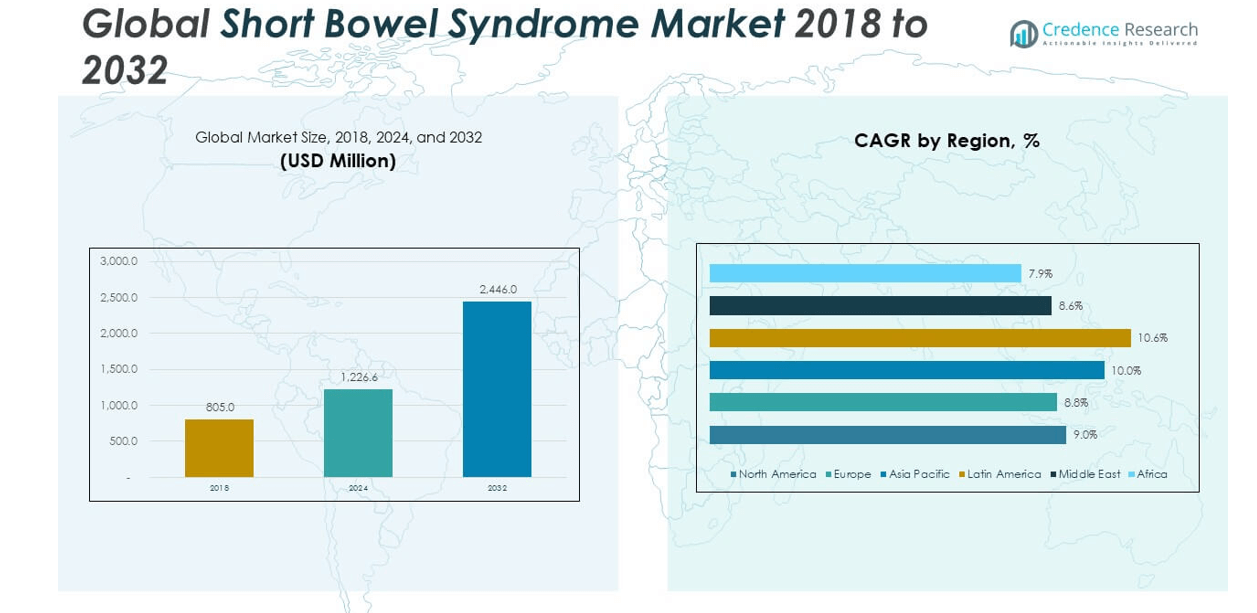
The Short Bowel Syndrome Market size was valued at USD 805.0 million in 2018 to USD 1,226.6million in 2024 and is anticipated to reach USD 2,446.0 million by 2032, at a CAGR of 9.28% during the forecast period.
The growth of the Short Bowel Syndrome (SBS) market is primarily fueled by the rising incidence of gastrointestinal disorders such as Crohn’s disease, mesenteric ischemia, and intestinal cancer, which often necessitate extensive bowel resections leading to SBS. Improved survival rates among patients undergoing such surgeries have further increased the demand for long-term SBS management solutions. In addition, significant advancements in treatment options particularly the introduction of glucagon-like peptide-2 (GLP-2) analogs like Teduglutide have transformed the therapeutic landscape by reducing patients’ dependence on parenteral nutrition. These innovations not only enhance nutrient absorption but also improve patient quality of life. This economic burden has pushed both healthcare systems and patients to seek alternative drug-based therapies. Furthermore, favorable reimbursement policies and regulatory support for orphan and rare disease treatments in key regions have played a pivotal role in accelerating drug development and adoption.
North America dominates the global SBS market, driven by its advanced healthcare infrastructure, early adoption of novel therapies, and robust reimbursement systems. The United States, in particular, holds the largest share due to widespread availability of drugs like Gattex and a growing number of diagnosed patients receiving consistent treatment. Europe follows as the second-largest regional market, supported by rising awareness of rare diseases, improved diagnostic capabilities, and a strong push for innovation through government-funded programs. Countries such as Germany, France, and the U.K. have emerged as key contributors within the region. Meanwhile, the Asia-Pacific region is witnessing the fastest growth, attributed to increasing gastrointestinal surgeries, expanding healthcare access, and growing investment in rare disease research. Latin America and the Middle East & Africa are gradually emerging as potential markets, as countries in these regions work to strengthen healthcare systems and increase access to advanced treatments for rare conditions like SBS.
Market Insights:
- The Short Bowel Syndrome Market grew from USD 805.0 million in 2018 to USD 1,226.6 million in 2024 and is expected to reach USD 2,446.0 million by 2032, reflecting a CAGR of 9.28%.
- Rising cases of Crohn’s disease, intestinal cancer, and mesenteric ischemia are increasing the global SBS patient population.
- GLP-2 analogs like Teduglutide are transforming care by reducing dependence on parenteral nutrition and improving intestinal function.
- The high cost and long-term risks of parenteral nutrition are pushing demand for safer, cost-effective drug-based therapies.
- Orphan drug incentives and faster approvals are accelerating pipeline development, with several promising candidates in late-stage trials.
- North America holds the largest market share, driven by advanced infrastructure and early access to therapies, while Asia-Pacific leads in growth rate.
- Low awareness, diagnostic delays, and unequal access continue to challenge early treatment and global adoption of advanced SBS therapies.
Market Drivers:
Increasing Prevalence of Gastrointestinal Diseases is Expanding the Patient Pool
The growing incidence of gastrointestinal disorders such as Crohn’s disease, intestinal cancer, necrotizing enterocolitis, and mesenteric ischemia has directly contributed to the rising number of patients with short bowel syndrome. These underlying conditions often lead to surgical resection of the small intestine, creating a demand for specialized treatments. The aging population and changing dietary habits have also increased the burden of intestinal diseases worldwide. With more patients requiring complex care following bowel surgeries, healthcare providers are seeking long-term management solutions. The Short Bowel Syndrome Market is benefiting from this increased demand for supportive and targeted therapies. It is also gaining traction due to improved awareness among clinicians about early diagnosis and intervention protocols.
- For example, Takeda Pharmaceuticals indicates that the prevalence of short bowel syndrome (SBS) is rising, with an estimated 15,000–30,000 patients in the United States alone as of 2024, largely due to increased rates of Crohn’s disease and surgical resections for intestinal cancer and necrotizing enterocolitis.
Advancements in GLP-2 Therapy and Hormonal Drugs are Transforming Treatment Pathways
Breakthroughs in pharmacological treatment have shifted the management of short bowel syndrome from parenteral nutrition toward more effective drug-based options. The introduction of GLP-2 analogs such as Teduglutide has shown positive outcomes by enhancing intestinal absorption and reducing the dependency on intravenous feeding. Clinical studies have demonstrated the ability of these drugs to stimulate mucosal growth and increase nutrient uptake. These developments have encouraged healthcare systems to invest in pharmaceutical alternatives that offer sustained benefits and lower complications. The Short Bowel Syndrome Market is increasingly shaped by this trend, with pharmaceutical companies accelerating the development of similar biologics. It continues to evolve in favor of therapies that restore function rather than provide only supportive care.
High Cost and Burden of Long-Term Parenteral Nutrition is Driving Demand for Alternatives
Parenteral nutrition remains a cornerstone of SBS management but imposes significant economic and quality-of-life burdens on patients and health systems. Annual treatment costs can exceed hundreds of thousands of dollars, requiring frequent monitoring and hospital visits. The complications associated with long-term use, including catheter infections, liver damage, and metabolic imbalances, have led to growing dissatisfaction. Hospitals and payers are actively seeking cost-effective alternatives that reduce long-term dependence on intravenous support. The Short Bowel Syndrome Market is experiencing a strong shift toward oral and injectable therapies that reduce reliance on hospital infrastructure. It reflects a broader healthcare movement toward efficiency and long-term sustainability in chronic condition management.
Supportive Regulatory Environment and Orphan Drug Incentives are Accelerating Innovation
Government agencies across North America, Europe, and Asia are increasingly prioritizing rare disease treatment through regulatory incentives and faster approval pathways. The designation of short bowel syndrome therapies as orphan drugs has led to enhanced funding opportunities, extended market exclusivity, and tax credits for developers. These incentives have encouraged pharmaceutical companies to invest in research and development of novel compounds. Several pipeline drugs are currently in late-stage trials, targeting the unmet needs of patients with limited absorption capacity. The Short Bowel Syndrome Market is gaining momentum from these policy-driven initiatives. It is supported by an innovation-friendly ecosystem that lowers entry barriers and promotes rapid clinical translation.
- For instance, Takeda and Zealand Pharma have both benefited from orphan drug designation for their SBS therapies in the US and EU, securing up to 7 years of market exclusivity in the US and 10 years in the EU, as well as tax credits covering up to 25% of qualifying clinical trial costs.
Market Trends:
Expanding Use of Telehealth and Home-Based Monitoring is Changing Patient Care Models
Healthcare systems are increasingly integrating telehealth services and remote monitoring solutions into the care pathways for patients with chronic conditions. For short bowel syndrome, where frequent follow-ups and nutritional adjustments are critical, these tools allow physicians to track progress without repeated hospital visits. Wearable devices and app-based interfaces now support real-time data collection, enabling early intervention and better compliance. Home infusion services have also improved, allowing patients to receive parenteral nutrition and medication without institutional care. The Short Bowel Syndrome Market is responding to this shift with more home-care-compatible therapies and portable delivery systems. It now reflects a trend toward decentralizing care while maintaining clinical oversight.
Growth in Pediatric Treatment Innovations is Broadening the Scope of Clinical Research
A growing number of treatment protocols and studies now target pediatric patients suffering from congenital or early-onset short bowel syndrome. Historically, treatment options for this age group were limited due to safety concerns and lack of clinical data. Today, companies are developing age-appropriate formulations and adjusting dosing strategies to address the specific physiological needs of children. New nutritional supplements, pediatric GLP-2 analogs, and customized parenteral nutrition regimens are under development. The Short Bowel Syndrome Market is witnessing a rise in research focused on improving survival and long-term quality of life for pediatric patients. It is expanding to accommodate distinct clinical pathways for early-life SBS management.
- For example, Gattex® (teduglutide), developed by Zealand Pharma and marketed by Takeda, received FDA approval for use in pediatric patients with short bowel syndrome (SBS) in 2021. This expanded indication covers children aged 1–17 years, based on robust clinical trial data.
Emphasis on Gut Microbiome Modulation is Influencing Future Treatment Strategies
Emerging research highlights the role of the gut microbiome in nutrient absorption, intestinal adaptation, and inflammation control in short bowel syndrome. Companies and academic institutions are increasingly exploring probiotics, synbiotics, and microbiome-targeted therapies to improve intestinal health. These interventions aim to promote beneficial microbial activity, which could complement or enhance existing treatment regimens. Clinical trials investigating fecal microbiota transplants and microbial ecosystem modulators are underway. The Short Bowel Syndrome Market is gradually incorporating microbiome-focused solutions into its development pipeline. It now includes an innovation track driven by the potential of personalized gut-based therapies.
Increased Collaboration Between Industry and Academia is Accelerating Clinical Pipelines
The complexity of short bowel syndrome and its varied presentation have prompted stronger collaboration between pharmaceutical companies, academic research centers, and patient advocacy groups. These partnerships aim to streamline drug development, share real-world evidence, and accelerate clinical trial enrollment. Several multi-center studies are testing next-generation compounds that promote mucosal regeneration or enhance intestinal motility. Joint initiatives also support biomarker discovery to improve diagnosis and monitor treatment response. The Short Bowel Syndrome Market is benefiting from this cross-sector collaboration, which is reducing the time from discovery to regulatory approval. It continues to gain momentum through knowledge-sharing and shared infrastructure investments.
- For example, Eli Lilly and the Mayo Clinic co-lead a multi-center trial of LY3502970, a next-generation GLP-1/GLP-2 dual agonist, with interim results showing statistically significant improvements in intestinal mucosal thickness and a 35% reduction in parenteral nutrition needs in adult SBS patients after 16 weeks.
Market Challenges Analysis:
High Treatment Costs and Access Disparities Are Limiting Patient Reach
The cost of treating short bowel syndrome remains exceptionally high, particularly due to long-term reliance on parenteral nutrition and specialized therapies like GLP-2 analogs. Many healthcare systems struggle to fully reimburse these treatments, leaving patients to bear significant out-of-pocket expenses. In low- and middle-income countries, access to essential drugs and infusion systems is limited, restricting the adoption of advanced therapeutic approaches. Insurance coverage gaps and delayed reimbursement approvals further delay timely intervention. The Short Bowel Syndrome Market faces ongoing challenges in balancing innovation with affordability. It continues to deal with access inequities that limit the benefits of recent medical advancements for broader patient populations.
Clinical Complexity and Limited Awareness Are Hindering Early Diagnosis and Intervention
Short bowel syndrome often presents with nonspecific symptoms that overlap with other gastrointestinal conditions, making diagnosis difficult, especially in primary care settings. Many physicians lack familiarity with the syndrome’s long-term management strategies, leading to delayed referrals and suboptimal treatment plans. Patients frequently experience prolonged diagnostic journeys, which affect outcomes and quality of life. Clinical trial recruitment also remains a challenge due to the small and geographically dispersed patient population. The Short Bowel Syndrome Market is constrained by these diagnostic and educational hurdles. It requires more robust awareness campaigns, diagnostic tools, and specialist training to support early identification and effective treatment planning.
Market Opportunities:
Rising Demand for Novel Therapeutics Creates Space for Biopharmaceutical Innovation
The growing need for more effective and less invasive treatments presents a significant opportunity for biopharmaceutical companies to expand their portfolios. Therapies that promote intestinal adaptation, reduce dependency on parenteral nutrition, and improve nutrient absorption are in high demand. New classes of drugs, including GLP-2 analogs, regenerative biologics, and hormonal modulators, are gaining traction in clinical research. The Short Bowel Syndrome Market offers a promising landscape for firms that can deliver innovative, long-acting, and targeted solutions. It encourages investment in orphan drug pipelines and supports premium pricing due to the rarity of the condition. Market entry barriers remain manageable for companies with differentiated products and clinical expertise.
Emerging Markets and Home-Based Care Models Offer Untapped Growth Potential
Countries in Asia-Pacific, Latin America, and parts of the Middle East are witnessing improved healthcare infrastructure and greater awareness of rare diseases. This shift creates opportunities for companies to introduce cost-effective therapies and expand global access. The rise of home-based care, supported by portable infusion technologies and telemedicine platforms, also supports outpatient management of short bowel syndrome. The Short Bowel Syndrome Market stands to benefit from scalable solutions that align with decentralized care models. It opens the door for device manufacturers and digital health firms to offer supportive technologies. Growth in these segments can help reduce hospital burdens while improving patient outcomes.
Market Segmentation Analysis:
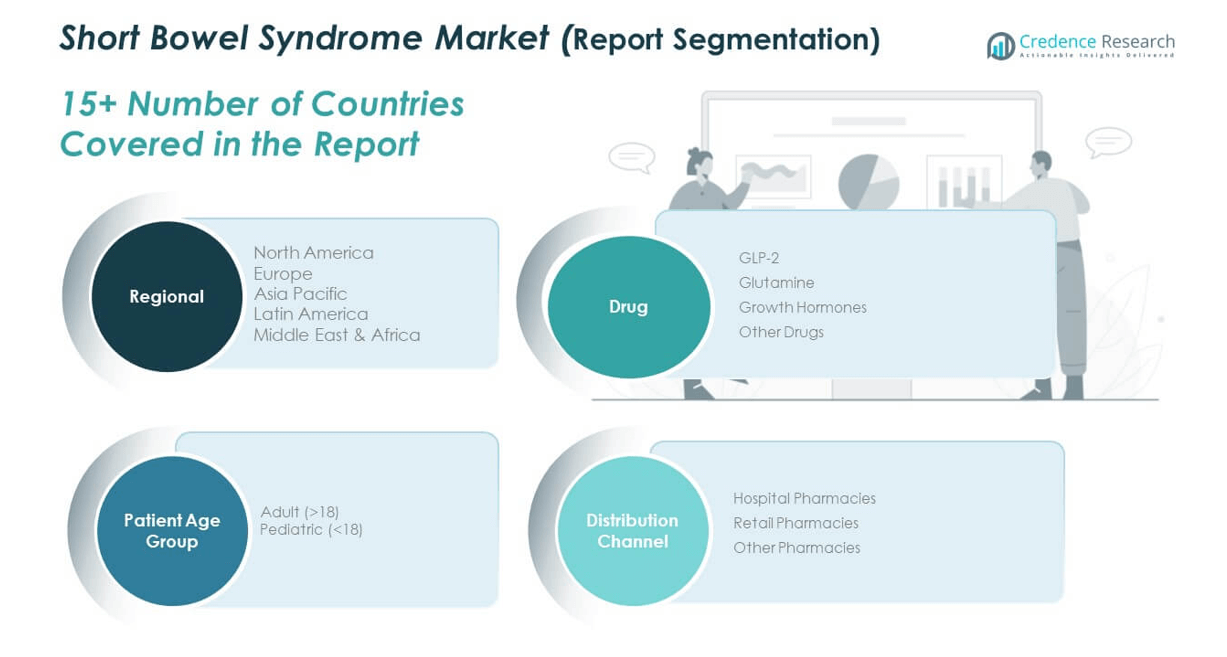
By drug type, patient age group, and distribution channel, each contributing distinctly to overall market dynamics. Among drug segments, GLP-2 analogs hold the largest revenue share due to their proven efficacy in enhancing intestinal absorption and reducing dependence on parenteral nutrition. Glutamine and growth hormones serve as supportive therapies, while the “other drugs” category includes micronutrients and adjunctive treatments that address comorbidities and improve patient outcomes.
- For example, Zorbtive® (somatropin), a recombinant human growth hormone produced by EMD Serono, is FDA-approved for the treatment of short bowel syndrome (SBS) in adult patientsreceiving specialized nutritional support. The approval was based on clinical evidence demonstrating its efficacy in improving intestinal absorption and reducing dependence on parenteral nutrition.
By patient age group, the adult segment dominates the market due to higher prevalence of SBS in this demographic, primarily following surgical resections for Crohn’s disease and intestinal malignancies. The pediatric segment is growing steadily with increasing research on early-onset SBS and tailored formulations for children.
By distribution channel, hospital pharmacies account for the majority of product dispensing, supported by frequent in-patient care requirements. Retail pharmacies are expanding their role, particularly in regions where home-based treatment is gaining traction. The Short Bowel Syndrome Market also includes other pharmacy channels that support specialized and outpatient care programs.
- For example, Gattex is primarily dispensed via hospital-based specialty pharmacies, consistent with Takeda’s distribution model for rare disease therapies that require close clinical management.
Segmentation:
By Drug Segment
- GLP-2
- Glutamine
- Growth Hormones
- Other Drugs
By Patient Age Group
- Adult (>18)
- Pediatric (<18)
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Other Pharmacies
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Short Bowel Syndrome Market size was valued at USD 242.39 million in 2018 to USD 363.49 million in 2024 and is anticipated to reach USD 709.34 million by 2032, at a CAGR of 9.0% during the forecast period. North America holds the largest share of the global market, accounting for nearly 36% of the overall revenue in 2024. The region’s strong dominance is supported by advanced healthcare infrastructure, early adoption of biologic therapies, and robust reimbursement frameworks. The United States contributes the most, with high utilization of GLP-2 analogs and extensive use of home-based parenteral nutrition services. Strong clinical research capabilities and the presence of major pharmaceutical players continue to drive innovation. The Short Bowel Syndrome Market in this region benefits from greater physician awareness, established referral pathways, and government support for rare disease treatment. It maintains a leadership position through continuous therapeutic advancements and high healthcare spending.
Europe
The Europe Short Bowel Syndrome Market size was valued at USD 215.10 million in 2018 to USD 318.70 million in 2024 and is anticipated to reach USD 611.50 million by 2032, at a CAGR of 8.8% during the forecast period. Europe represents nearly 31% of the global market share in 2024, driven by supportive regulatory policies and high diagnosis rates across key countries. Nations such as Germany, France, and the U.K. have adopted national-level programs for rare disease management, which support SBS treatment accessibility. The European Medicines Agency provides orphan drug incentives that encourage continued innovation in this space. Hospital-based treatment remains common, although home infusion services are expanding steadily. The Short Bowel Syndrome Market here benefits from public–private collaborations and ongoing clinical trials across academic centers. It shows steady growth fueled by healthcare equity and increasing physician engagement.
Asia Pacific
The Asia Pacific Short Bowel Syndrome Market size was valued at USD 170.58 million in 2018 to USD 270.22 million in 2024 and is anticipated to reach USD 566.25 million by 2032, at a CAGR of 10.0% during the forecast period. Asia Pacific holds a 27% share of the global market in 2024 and is recognized as the fastest-growing regional segment. China, India, and Japan lead in terms of volume and are investing significantly in rare disease awareness and healthcare digitization. Increasing gastrointestinal surgeries, improved access to biologics, and rising insurance coverage are key factors behind this momentum. Local manufacturers are entering the market with affordable formulations, further driving adoption. The Short Bowel Syndrome Market in this region benefits from urbanization, government initiatives, and improved diagnostic capabilities. It continues to attract investment due to its large patient population and untapped potential.
Latin America
The Latin America Short Bowel Syndrome Market size was valued at USD 84.61 million in 2018 to USD 139.69 million in 2024 and is anticipated to reach USD 307.22 million by 2032, at a CAGR of 10.6% during the forecast period. Latin America accounts for 14% of global market share in 2024 and is experiencing accelerated growth through better healthcare access and rising chronic disease incidence. Brazil and Mexico are key contributors, supported by improved hospital infrastructure and early access to orphan therapies. While out-of-pocket costs remain a concern, public programs are gradually covering rare diseases. Private players are expanding services in urban areas, boosting market reach. The Short Bowel Syndrome Market in this region is evolving through localized manufacturing and distribution efforts. It presents strong opportunities for mid-sized firms offering cost-effective therapeutic options.
Middle East
The Middle East Short Bowel Syndrome Market size was valued at USD 66.17 million in 2018 to USD 97.36 million in 2024 and is anticipated to reach USD 184.92 million by 2032, at a CAGR of 8.6% during the forecast period. The Middle East represents a 10% share of the global SBS market in 2024, with growth led by countries like Saudi Arabia and the UAE. Rising investments in specialty care centers and digital health platforms are driving uptake of SBS treatments. Government-backed insurance coverage and regional procurement programs are expanding patient access. Physician education programs are also helping reduce diagnostic delays. The Short Bowel Syndrome Market in the Middle East benefits from increasing demand for advanced biologics and enteral nutrition solutions. It continues to strengthen through cross-border healthcare partnerships and infrastructure development.
Africa
The Africa Short Bowel Syndrome Market size was valued at USD 26.16 million in 2018 to USD 37.13 million in 2024 and is anticipated to reach USD 66.78 million by 2032, at a CAGR of 7.9% during the forecast period. Africa accounts for just under 4% of the global market in 2024, but shows gradual growth supported by expanding healthcare coverage and donor-funded rare disease programs. Countries such as South Africa, Kenya, and Nigeria are improving access through public-private collaboration. Market penetration remains limited due to high costs and underdeveloped distribution networks. Local initiatives to train medical staff and invest in diagnostic tools are beginning to show results. The Short Bowel Syndrome Market in Africa remains in the early stage but holds long-term potential. It offers opportunities for low-cost treatment models and regional partnerships to scale access.
Key Player Analysis:
- Takeda Pharmaceutical Co. Ltd.
- Merck KGaA
- Ironwood Pharmaceuticals
- OxThera AB
- Nutrinia Ltd.
- Nestlé Health Science
- Hanmi Pharmaceutical
- Zealand Pharma A/S
- Shire plc
- Sancilio & Company, Inc.
- Naia Pharmaceuticals, Inc.
- Other Key Players
Competitive Analysis:
The Short Bowel Syndrome Market is highly consolidated, with a few key players holding a dominant share through patented therapies and strong distribution networks. Companies such as Takeda Pharmaceutical, Zealand Pharma, VectivBio, and OxThera lead the landscape with their specialized drug portfolios targeting intestinal adaptation and nutrient absorption. Takeda’s GLP-2 analog, Gattex/Revestive, remains the market leader due to its proven efficacy and global availability. Emerging firms are focusing on pipeline innovation, with several candidates in late-stage clinical trials. Strategic collaborations, orphan drug designations, and regulatory exclusivity are shaping competition and protecting market positions. The Short Bowel Syndrome Market continues to attract investment from biotech firms and specialty pharma companies aiming to expand therapeutic options. It reflects a competitive environment driven by innovation, niche expertise, and patient-centric approaches in rare disease treatment.
Recent Developments:
- In July 2025, OPKO Health and Entera Bio announced selection of their first‑in‑class oral GLP‑2 analog for presentation at the ESPEN Congress. This tablet program targets SBS patients who currently require injectable GLP‑2 therapy like Gattex.
- In May 2023, Ironwood Pharmaceuticals entered into a definitive agreement to acquire VectivBio, a clinical-stage biotech company pioneering treatments for severe rare gastrointestinal diseases. This acquisition is particularly significant for the Short Bowel Syndrome market, as it brings apraglutide—a lead investigational asset for SBS—into Ironwood’s portfolio.
Market Concentration & Characteristics:
The Short Bowel Syndrome Market exhibits high concentration, with a limited number of companies driving the majority of global revenue through patented therapies and niche expertise. It is characterized by significant barriers to entry, including high development costs, regulatory complexity, and the need for extensive clinical validation. Orphan drug incentives and exclusivity agreements further reinforce the dominance of established players. The market focuses heavily on innovation, with emphasis on biologics, hormone analogs, and targeted therapies that reduce reliance on parenteral nutrition. It caters to a small but medically complex patient population, requiring specialized care protocols and long-term treatment strategies. The Short Bowel Syndrome Market reflects a high-value, low-volume model with strong pricing power and steady demand for advanced therapeutic solutions.
Report Coverage:
The research report offers an in-depth analysis based on Drug, Patient Age Group and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing global prevalence of gastrointestinal diseases will continue to expand the short bowel syndrome patient population.
- Advancements in regenerative medicine and tissue engineering are expected to create new treatment pathways.
- Wider adoption of GLP-2 analogs and hormonal therapies will reduce reliance on parenteral nutrition.
- Growth in pediatric-focused formulations will improve outcomes in early-onset SBS cases.
- Rising healthcare investments in emerging markets will drive product accessibility and regional expansion.
- Strategic partnerships between biotech firms and academic institutions will accelerate drug development.
- Expansion of telehealth and home infusion services will support decentralized care models.
- Orphan drug designations and extended exclusivity will encourage innovation and market entry.
- Improved diagnostic tools and clinician training will enhance early detection and treatment planning.
- Digital health integration will enable real-time monitoring and personalized treatment adjustments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Short Bowel Syndrome Market?
What factors are driving the growth of the Short Bowel Syndrome Market?
What are the key segments within the Short Bowel Syndrome Market?
Who are the major players in this market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Short Bowel Syndrome Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Short Bowel Syndrome Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,226.6 million → 2032: USD 2,446.0 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Short Bowel Syndrome Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Short Bowel Syndrome Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Short Bowel Syndrome Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Short Bowel Syndrome Market Drivers
- 3.3 Short Bowel Syndrome Market Restraints & Challenges
- 3.4 Short Bowel Syndrome Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Short Bowel Syndrome Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Short Bowel Syndrome Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Short Bowel Syndrome category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Short Bowel Syndrome Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Short Bowel Syndrome Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Short Bowel Syndrome market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Short Bowel Syndrome Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Short Bowel Syndrome Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Short Bowel Syndrome Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Short Bowel Syndrome (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Short Bowel Syndrome Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Short Bowel Syndrome Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Short Bowel Syndrome Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Short Bowel Syndrome Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Short Bowel Syndrome Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Short Bowel Syndrome Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Short Bowel Syndrome Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Short Bowel Syndrome Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Short Bowel Syndrome Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
