
Market Overview:
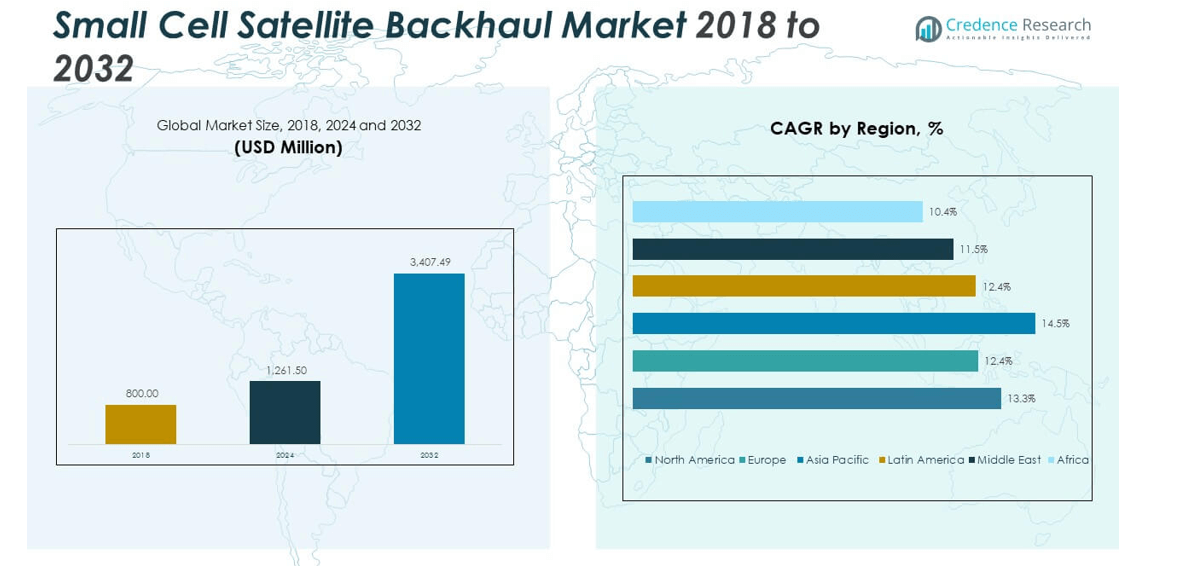
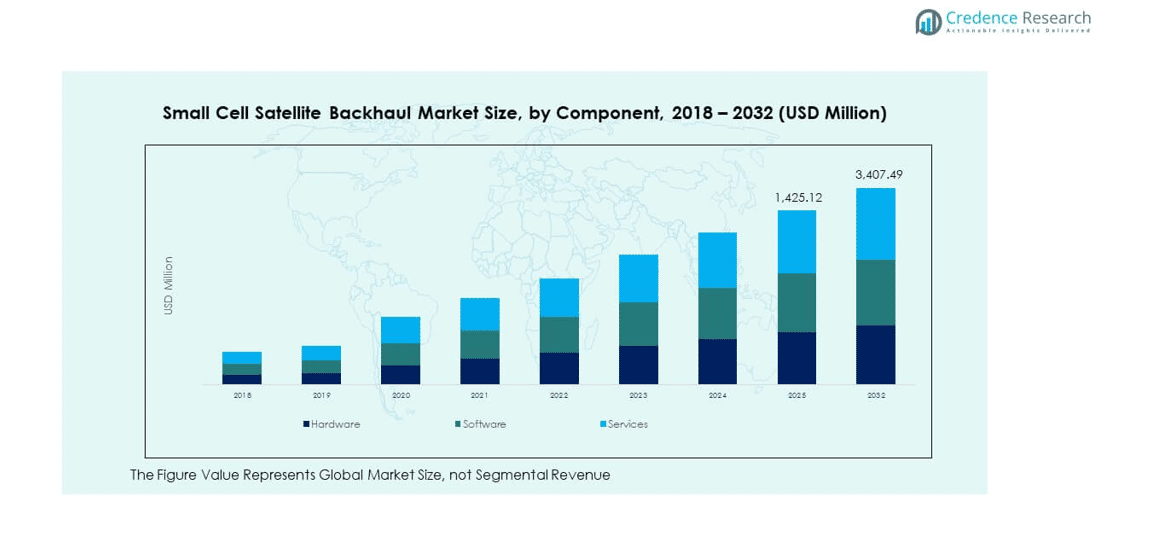
The Global Small Cell Satellite Backhaul Market size was valued at USD 800.00 million in 2018 to USD 1,261.50 million in 2024 and is anticipated to reach USD 3,407.49 million by 2032, at a CAGR of 13.26% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Small Cell Satellite Backhaul Market Size 2024 | USD 1,261.50 million |
| Small Cell Satellite Backhaul Market, CAGR | 13.26% |
| Small Cell Satellite Backhaul Market Size 2032 | USD 3,407.49 million |
The market is driven by the rising need for reliable mobile connectivity in remote and underserved regions. Growing mobile data consumption and rapid 5G network expansion are increasing the demand for small cell satellite backhaul solutions. Network operators are using these systems to enhance capacity, reduce latency, and ensure seamless communication where terrestrial infrastructure is limited or costly to deploy.
Geographically, North America and Europe lead due to strong adoption of advanced telecom networks and major satellite service providers. Asia-Pacific is emerging quickly, supported by growing rural connectivity programs and expanding mobile penetration in countries like India and China. The Middle East and Africa also show potential growth, driven by infrastructure upgrades and government initiatives to bridge the digital divide.
Market Insights:
- The Global Small Cell Satellite Backhaul Market was valued at USD 800.00 million in 2018, grew to USD 1,261.50 million in 2024, and is projected to reach USD 3,407.49 million by 2032, expanding at a CAGR of 13.26% during the forecast period.
- North America (28%), Asia Pacific (26%), and Europe (23%) represent the top three regional markets due to advanced telecom infrastructure, strong satellite investments, and early 5G adoption. These regions benefit from high connectivity demand and the presence of leading satellite operators.
- Asia Pacific is the fastest-growing region, supported by government-led broadband programs, rural connectivity expansion, and rapid deployment of 5G networks across major economies such as China, India, and Japan.
- Hardware contributes the largest segment share of around 45%, driven by the demand for antennas, modems, and signal amplifiers supporting data backhaul across diverse terrains.
- Software and services collectively account for about 55%, reflecting growing emphasis on network automation, cloud-based management, and satellite performance optimization for global operators.
Market Drivers:
Growing Demand for High-Speed Connectivity in Remote and Rural Areas
The Global Small Cell Satellite Backhaul Market is expanding due to the rising demand for broadband connectivity in remote and underserved areas. Many regions still lack terrestrial infrastructure, making satellite-based backhaul the most viable solution. Governments and telecom operators are investing in small cell satellite networks to close connectivity gaps. These systems provide faster deployment compared to fiber networks, enabling efficient mobile coverage. Increasing digitalization in education, healthcare, and agriculture fuels demand for reliable internet. It enhances service delivery and promotes economic growth in rural regions. The technology ensures consistent coverage in geographically challenging locations. The continued support from government initiatives further accelerates the adoption rate.
- For instance, under the Federal Communications Commission’s Rural Digital Opportunity Fund (RDOF) program, winning carriers including Viasat have committed to deploying high-speed broadband-meeting speeds of at least 100 Mbps download and 20 Mbps upload-to over 5.2 million rural homes and businesses across the United States, supported by $9.2 billion in federal investment.
Rapid 5G Network Expansion and Need for Efficient Backhaul Solutions
The ongoing 5G rollout is a key growth driver for the Global Small Cell Satellite Backhaul Market. Mobile operators require scalable and cost-effective backhaul options to support high data throughput. Satellite backhaul plays a vital role in connecting 5G small cells in hard-to-reach regions. It ensures low latency, high bandwidth, and consistent performance for next-generation networks. The demand for flexible connectivity solutions is pushing companies to integrate satellite backhaul with terrestrial infrastructure. The approach increases resilience and capacity during network congestion. It also supports high-demand applications such as IoT, smart cities, and connected vehicles. This trend is making satellite backhaul essential for future 5G network expansion.
- For instance, SES’s O3b mPOWER constellation, developed in partnership with Boeing, delivers multiple gigabits per second throughput with predictable 150 ms latency, enabling telecom partners like Microsoft Azure and Vodafone Cook Islands to provide robust 5G and broadband services in remote environments.
Advancements in Low Earth Orbit (LEO) Satellite Technology
Technological advancements in LEO satellites are transforming the Global Small Cell Satellite Backhaul Market. LEO constellations offer reduced latency and higher data transmission speeds than traditional geostationary systems. These capabilities are critical for real-time communication and 5G integration. Companies are launching new LEO networks to deliver affordable, low-latency connectivity worldwide. The growing number of satellites enhances network redundancy and minimizes signal interruptions. It enables better connectivity in remote regions and maritime or aviation sectors. The expansion of LEO satellite infrastructure also lowers operational costs for telecom operators. Continuous innovation in payload design and antenna systems further boosts performance efficiency.
Rising Mobile Data Traffic and Network Congestion Management
The exponential rise in global mobile data usage is driving the Global Small Cell Satellite Backhaul Market. Increasing smartphone penetration and streaming services require stronger backhaul capacity. Telecom networks are deploying small cells to manage rising data loads efficiently. Satellite-based solutions offer flexible bandwidth allocation for high-traffic zones. They support offloading data during peak usage and maintaining stable performance. It ensures better user experience and prevents network slowdowns. This adaptability makes satellite backhaul crucial for future-ready communication networks. The trend is expected to strengthen with the growing adoption of cloud-based and edge computing applications.
Market Trends:
Integration of Hybrid Satellite-Terrestrial Networks for Seamless Connectivity
A key trend shaping the Global Small Cell Satellite Backhaul Market is the integration of hybrid satellite-terrestrial networks. Telecom operators are combining satellite and ground-based infrastructure for improved efficiency. This hybrid model provides continuous service even when one system faces disruption. It enhances reliability, reduces downtime, and optimizes bandwidth allocation. Operators are using advanced software-defined networking for dynamic traffic management. The hybrid approach supports load balancing and faster content delivery. It strengthens the backbone for 5G and IoT-based services. The shift toward hybrid connectivity demonstrates a focus on network resilience and scalability.
- For instance, AT&T and OneWeb announced their collaboration in September 2021 to combine terrestrial and low Earth orbit satellite coverage, enabling hybrid service delivery to businesses and government customers in Alaska and rural continental U.S. regions with significantly reduced latency.
Rising Adoption of Software-Defined Networking (SDN) and Network Function Virtualization (NFV)
The adoption of SDN and NFV is increasing across the Global Small Cell Satellite Backhaul Market. These technologies help network operators manage complex satellite infrastructures efficiently. They enable flexible control, automation, and real-time optimization of resources. SDN and NFV allow operators to adjust network parameters remotely, improving responsiveness. It reduces operational costs and enhances service scalability. The integration of SDN simplifies traffic routing between satellite and terrestrial systems. The technology also supports faster deployment of new services and reduces hardware dependency. This transformation marks a shift toward more programmable and adaptive backhaul networks.
- For instance, in July 2025, Intelsat and Kratos Defense successfully demonstrated 5G non-terrestrial networking over geostationary orbit using SDN orchestration, boosting real-time efficiency and dynamic bandwidth management in satellite backhaul configurations.
Growing Use of AI and Automation in Network Optimization
Artificial intelligence is emerging as a major trend in the Global Small Cell Satellite Backhaul Market. AI-driven algorithms are being applied to optimize network performance and predict failures. Automated systems improve bandwidth utilization and minimize downtime. Machine learning tools analyze large datasets to detect latency or interference issues. These systems enable predictive maintenance and reduce manual intervention. It enhances service quality and ensures uninterrupted connectivity. Telecom operators are investing in AI-powered analytics platforms for smarter decision-making. The trend is reshaping network management and boosting operational efficiency.
Expansion of Satellite Constellations by Private Space Companies
Private players are investing heavily in satellite constellations to expand the Global Small Cell Satellite Backhaul Market. Companies are focusing on deploying large-scale networks to meet increasing global data needs. This competition is improving service quality and lowering bandwidth costs. The growing involvement of commercial entities accelerates innovation in satellite manufacturing. It drives the miniaturization of hardware and boosts launch frequency. Private partnerships with telecom operators are also expanding coverage in rural and maritime regions. It creates a diverse supply ecosystem supporting rapid network deployment. These developments are reshaping the satellite backhaul landscape worldwide.
Market Challenges Analysis:
High Deployment Costs and Infrastructure Limitations in Developing Regions
The Global Small Cell Satellite Backhaul Market faces challenges due to high deployment and maintenance costs. Building and operating satellite networks demand large capital investments. Developing regions often struggle with funding and access to supporting infrastructure. The cost of ground equipment, spectrum licensing, and data integration adds financial pressure. Telecom operators must balance between service quality and affordability. It slows network rollout in low-income and geographically remote markets. Limited power availability and environmental barriers further restrict expansion. The issue is more critical in areas with weak regulatory frameworks and minimal government support.
Spectrum Management, Latency, and Regulatory Constraints
Spectrum allocation remains a complex challenge in the Global Small Cell Satellite Backhaul Market. Frequency interference between terrestrial and satellite systems creates performance issues. Managing latency and maintaining data integrity are ongoing technical hurdles. It affects service quality and reliability during high-demand periods. Regulatory inconsistencies across countries also delay cross-border operations. The absence of harmonized global policies complicates licensing and coordination. Many operators face delays in approvals and spectrum allocation. Addressing these regulatory barriers is essential to accelerate global adoption.
Market Opportunities:
Rural Connectivity Projects and Government Digitalization Initiatives
Expanding government-led rural broadband programs presents strong opportunities for the Global Small Cell Satellite Backhaul Market. Many countries are investing in national connectivity projects to improve internet access. These initiatives aim to reduce the digital divide by leveraging satellite technology. Public-private partnerships are promoting deployment in remote areas and islands. The growing need for digital inclusion enhances satellite backhaul adoption. It also opens new revenue channels for telecom operators and satellite providers. The increased focus on education, telemedicine, and e-governance drives long-term demand. Satellite networks will play a key role in supporting inclusive digital transformation.
Rising Role of 5G and Emerging IoT Ecosystems
The integration of 5G and IoT systems creates new opportunities for the Global Small Cell Satellite Backhaul Market. Telecom operators are exploring satellite backhaul to connect sensors, vehicles, and smart devices in hard-to-reach zones. It supports real-time data transmission and network scalability for diverse applications. The demand for seamless IoT communication across industries is increasing. It strengthens collaboration between satellite operators and 5G service providers. Future opportunities will focus on edge computing, maritime IoT, and autonomous systems. These advancements will expand market reach and create sustainable growth prospects.
Market Segmentation Analysis:
By Component
The Global Small Cell Satellite Backhaul Market is categorized into hardware, software, and services. Hardware dominates due to rising deployment of antennas, modems, and transceivers supporting high-capacity data links. Software solutions are expanding as operators adopt advanced network management tools and automation platforms. Services are gaining traction with growing demand for installation, maintenance, and managed network operations. The integration of software-defined networking enhances scalability and flexibility across diverse applications.
- For instance, Hughes Network Systems’ JUPITER 3 satellite, launched in 2023, supports over 500 Gbps total capacity, with its HT3000W modem series providing up to 100 Mbps connectivity per terminal for backhaul applications across North and South America.
By Application
The market includes 4G LTE backhaul, 5G small-cell backhaul, IoT/M2M backhaul, rural and remote connectivity, and temporary events or disaster recovery. 5G small-cell backhaul leads due to the rapid global rollout of 5G networks. IoT/M2M applications are increasing with growing smart infrastructure and industrial automation. Rural connectivity remains vital in addressing digital inclusion initiatives across developing regions. Temporary communication networks support disaster management and event-based data coverage.
- For instance, during the May 2024 floods in Brazil, SpaceX’s Starlink donated 1,000 emergency-use terminals that restored internet services for authorities and first responders in under 48 hours, demonstrating satellite backhaul’s critical role in emergency and disaster communication.
By End-User
Key end users include mobile network operators, neutral host providers, government and defense agencies, enterprises in sectors such as oil, gas, mining, and transport, and fixed wireless ISPs. Mobile network operators account for the largest share due to network expansion in remote areas. Enterprises and defense organizations are adopting satellite backhaul for secure and reliable communication. Neutral host providers are emerging with shared infrastructure models to lower deployment costs.
By Deployment and Satellite Type
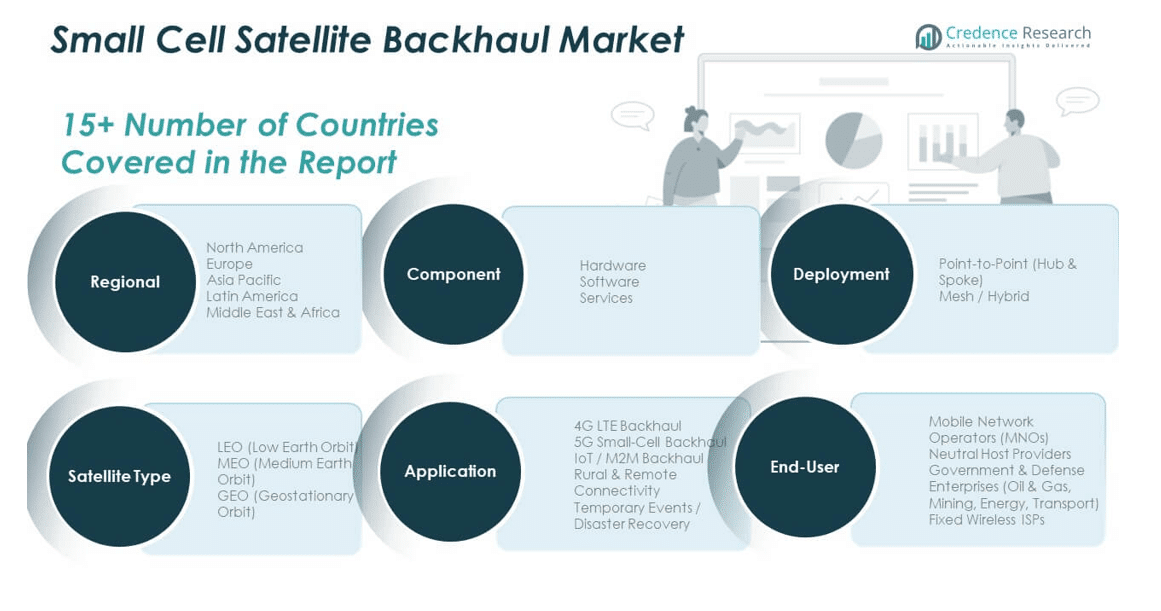
Deployment types include point-to-point (hub and spoke) and mesh or hybrid configurations. Point-to-point systems dominate for their simplicity and cost efficiency, while mesh setups improve redundancy and reliability. By satellite type, LEO satellites hold a growing share due to low latency and fast data delivery. MEO and GEO satellites continue to support high-capacity and long-duration communication needs. Regionally, North America and Europe lead adoption, while Asia Pacific and Africa show rapid growth in connectivity expansion.
Segmentation:
By Component
- Hardware
- Software
- Services
By Application
- 4G LTE Backhaul
- 5G Small-Cell Backhaul
- IoT / M2M Backhaul
- Rural & Remote Connectivity
- Temporary Events / Disaster Recovery
By End-User
- Mobile Network Operators (MNOs)
- Neutral Host Providers
- Government & Defense
- Enterprises (Oil & Gas, Mining, Energy, Transport)
- Fixed Wireless ISPs
By Deployment
- Point-to-Point (Hub & Spoke)
- Mesh / Hybrid
By Satellite Type
- LEO (Low Earth Orbit)
- MEO (Medium Earth Orbit)
- GEO (Geostationary Orbit)
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Global Small Cell Satellite Backhaul Market size was valued at USD 278.40 million in 2018 to USD 433.44 million in 2024 and is anticipated to reach USD 1,169.12 million by 2032, at a CAGR of 13.3% during the forecast period. North America holds the largest market share of 28% driven by the strong presence of satellite operators, advanced communication infrastructure, and early 5G deployment. The U.S. dominates the region with continuous investments in small-cell integration and LEO satellite expansion by companies such as SpaceX, Viasat, and Hughes Network Systems. Canada contributes through government-supported broadband projects targeting remote areas. It benefits from hybrid backhaul deployment combining terrestrial fiber and satellite solutions for enhanced reliability. Demand for secure communication in defense and energy sectors is also growing. The region maintains its leadership with steady technological innovation and high consumer data demand.
Europe
The Europe Global Small Cell Satellite Backhaul Market size was valued at USD 202.56 million in 2018 to USD 306.51 million in 2024 and is anticipated to reach USD 780.15 million by 2032, at a CAGR of 12.4% during the forecast period. Europe accounts for a 23% market share supported by strong policy frameworks promoting rural connectivity. Countries like the UK, France, and Germany lead adoption through public-private initiatives under programs such as the “Digital Europe” agenda. The region’s leading operators, including Eutelsat, SES, and Intelsat, are expanding LEO and MEO constellations to improve latency and bandwidth. It benefits from increased investments in smart city projects and IoT connectivity. Eastern Europe is witnessing new opportunities with growing digital infrastructure funding. Demand from transportation and maritime communication continues to strengthen the European backhaul market.
Asia Pacific
The Asia Pacific Global Small Cell Satellite Backhaul Market size was valued at USD 220.24 million in 2018 to USD 360.97 million in 2024 and is anticipated to reach USD 1,065.18 million by 2032, at a CAGR of 14.5% during the forecast period. Asia Pacific holds a 26% market share and is the fastest-growing region. It is driven by large-scale rural connectivity programs and high mobile penetration in China, India, Japan, and South Korea. The region experiences strong demand for 5G backhaul and IoT applications across manufacturing and transportation. Governments are investing in national broadband initiatives supported by satellite infrastructure. Japan and South Korea lead technological adoption, while India and Southeast Asia show growing potential due to rising internet demand. It benefits from expanding LEO satellite deployments enhancing low-latency services. Strong investments from regional telecoms and international satellite operators accelerate market growth.
Latin America
The Latin America Global Small Cell Satellite Backhaul Market size was valued at USD 57.60 million in 2018 to USD 90.06 million in 2024 and is anticipated to reach USD 227.86 million by 2032, at a CAGR of 12.4% during the forecast period. Latin America holds a 10% market share supported by expanding telecom coverage and infrastructure modernization. Brazil and Mexico are the leading contributors, focusing on remote area connectivity and disaster recovery communication. The adoption of hybrid satellite networks is growing to bridge gaps in underserved regions. Government initiatives and private partnerships are improving digital inclusion. It benefits from the integration of small-cell technology with LEO satellite systems. The region’s growing enterprise and transportation sectors further fuel data traffic demand. Continuous regulatory reforms and international collaboration strengthen its market growth outlook.
Middle East
The Middle East Global Small Cell Satellite Backhaul Market size was valued at USD 25.92 million in 2018 to USD 37.84 million in 2024 and is anticipated to reach USD 90.32 million by 2032, at a CAGR of 11.5% during the forecast period. The region commands a 7% market share and is growing steadily with increasing investments in telecommunication and defense communication systems. GCC countries lead adoption supported by smart city initiatives and large infrastructure projects. Satellite operators are collaborating with regional telecoms to enhance broadband access in remote and desert areas. It benefits from high demand for secure and reliable backhaul connectivity for oil, gas, and maritime industries. The expansion of LEO satellite networks improves data speed and network flexibility. Israel and Turkey are emerging hubs for technology innovation in the sector.
Africa
The Africa Global Small Cell Satellite Backhaul Market size was valued at USD 15.28 million in 2018 to USD 32.68 million in 2024 and is anticipated to reach USD 74.86 million by 2032, at a CAGR of 10.4% during the forecast period. Africa holds a 6% market share, driven by the growing need for rural broadband and digital inclusion initiatives. The market is expanding as governments and international organizations prioritize connectivity for remote communities. South Africa and Egypt lead adoption through national broadband strategies. It benefits from partnerships with global satellite companies providing low-cost internet access. The deployment of small-cell networks complements satellite coverage in rural zones. Rising demand from education, healthcare, and financial services strengthens long-term growth. Continuous efforts to lower equipment costs and improve regulatory alignment will shape Africa’s digital transformation.
Key Player Analysis:
- SpaceX (Starlink)
- Eutelsat OneWeb
- Viasat (including Inmarsat)
- SES S.A.
- Intelsat
- Telesat
- Iridium Communications
- Globalstar
- AST SpaceMobile
- Gilat Satellite Networks
- Hughes Network Systems (EchoStar)
- Comtech Telecommunications
- Ceragon Networks
- Ericsson
- CommScope
Competitive Analysis:
The Global Small Cell Satellite Backhaul Market is highly competitive, with companies focusing on innovation, cost efficiency, and global network expansion. It is dominated by players such as SpaceX (Starlink), Eutelsat OneWeb, Viasat, SES S.A., and Intelsat. These firms compete through the deployment of low Earth orbit constellations, advanced transceiver technologies, and hybrid backhaul solutions. Collaboration with telecom operators and governments enhances their regional presence. Continuous R&D investment strengthens performance, scalability, and bandwidth efficiency. The market exhibits steady consolidation, with partnerships and mergers creating integrated service ecosystems.
Recent Developments:
- In August 2025, Eutelsat OneWeb entered into a strategic partnership with Tata Group–owned Nelco Limited to launch low Earth orbit (LEO) satellite services in India. The collaboration aimed to provide secure, high-speed connectivity across India’s land, maritime, and aviation sectors. This agreement emphasized supporting the nation’s digital transformation and national security initiatives by offering long-range LEO-based backhaul and broadband networks.
- In September 2025, Viasat announced plans for the late-October launch of its second ViaSat-3 satellite (F2) aboard a United Launch Alliance Atlas V rocket from Florida’s Cape Canaveral Space Force Station. This ultra-high-capacity satellite will provide over one terabit per second (Tbps) of throughput and represents a crucial expansion of Viasat’s multi-orbit broadband network serving commercial and mobility customers worldwide.
- On July 17, 2025, SES S.A. formally completed its $3.1 billion acquisition of Intelsat, creating one of the world’s most significant multi-orbit operators with over 120 active satellites across geostationary (GEO) and medium earth orbit (MEO) configurations. This merger greatly enhanced the combined company’s ability to deliver resilient global backhaul and enterprise network solutions, especially for mobility and government clients. SES also launched O3b mPOWER satellites 9 and 10 in July to expand its global network capacity.
- In March 2025, Telesat entered into a multi-year partnership with Orange Wholesale International to provide non-terrestrial connectivity services via the Telesat Lightspeed LEO constellation. A Lightspeed landing station was established at Orange’s Bercenay-en-Othe teleport in France, with planned integration into Orange’s global business connectivity offerings to enhance mobile backhaul performance in remote areas.
Report Coverage:
The research report offers an in-depth analysis based on component, application, end-user, deployment, and satellite type segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing use of LEO constellations will redefine low-latency connectivity across remote regions.
- Integration of hybrid terrestrial-satellite systems will enhance network resilience and performance.
- Growth in 5G backhaul demand will expand satellite bandwidth utilization worldwide.
- Advancements in antenna and modem technologies will reduce operational costs.
- Partnerships between telecom operators and satellite providers will strengthen service portfolios.
- AI-driven automation will optimize bandwidth allocation and predictive maintenance.
- Rising demand from government and defense sectors will support long-term contracts.
- Emerging markets in Asia-Pacific and Africa will drive substantial connectivity growth.
- Expansion of IoT and M2M networks will increase reliance on small-cell backhaul systems.
- Sustainability efforts will lead to energy-efficient satellite network designs and operations.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of 5G Networks and Need for Efficient Backhaul
The rapid global rollout of 5G networks is driving demand for scalable, high-capacity backhaul solutions, especially in areas where terrestrial infrastructure is limited or costly. Small cell satellite backhaul enables operators to extend 5G coverage to remote and underserved regions, ensuring low latency and high bandwidth for next-generation applications.
Rural Connectivity and Government Digital Inclusion Initiatives
Many governments and telecom operators are investing in satellite-based backhaul to bridge the digital divide in rural and remote areas. These initiatives enable faster deployment of broadband services, supporting economic development and digital transformation in locations lacking terrestrial connectivity.
Advancements in LEO Satellite Technology
The emergence of low Earth orbit (LEO) satellite constellations is transforming the market by offering lower latency, higher data speeds, and improved network redundancy compared to traditional geostationary satellites. This technological progress makes satellite backhaul more viable for real-time and high-throughput applications.
Rising Mobile Data Traffic and Network Congestion Management
The exponential growth in mobile data consumption, driven by increased smartphone usage and streaming services, is pushing operators to deploy small cells and satellite backhaul to manage network congestion. Satellite solutions provide flexible bandwidth allocation and reliable performance during peak demand periods.
Integration of Hybrid Satellite-Terrestrial Networks
Telecom operators are increasingly adopting hybrid models that combine satellite and terrestrial infrastructure, enhancing network resilience and optimizing bandwidth. This integration ensures continuous service delivery, even in challenging environments or during terrestrial network outages.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Small Cell Satellite Backhaul Market?
At what Compound Annual Growth Rate is the Global Small Cell Satellite Backhaul Market projected to grow between 2025 and 2032?
What factors are driving the growth of the Small Cell Satellite Backhaul Market?
What are some challenges faced by the Small Cell Satellite Backhaul Market?
Who are the major players in the Small Cell Satellite Backhaul Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Mobile Network Operators (MNOs)
- 1.2.2 Neutral Host Providers
- 1.2.3 Government & Defense
- 1.2.4 Enterprises (Oil & Gas, Mining, Energy, Transport)
- 1.2.5 Fixed Wireless ISPs
- 1.3 By Component
- 1.3.1 Hardware
- 1.3.2 Software
- 1.3.3 Services
- 1.4 By Application
- 1.4.1 4G LTE Backhaul
- 1.4.2 5G Small-Cell Backhaul
- 1.4.3 IoT / M2M Backhaul
- 1.4.4 Rural & Remote Connectivity
- 1.4.5 Temporary Events / Disaster Recovery
- 1.5 By Satellite Type
- 1.5.1 LEO (Low Earth Orbit)
- 1.5.2 MEO (Medium Earth Orbit)
- 1.5.3 GEO (Geostationary Orbit)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 800.00 million → 2032: USD 3,407.49 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Small Cell Satellite Backhaul Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Small Cell Satellite Backhaul Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Small Cell Satellite Backhaul Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Small Cell Satellite Backhaul Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Small Cell Satellite Backhaul Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Small Cell Satellite Backhaul Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Small Cell Satellite Backhaul Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Small Cell Satellite Backhaul Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 800.00 million → 2032: USD 3,407.49 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Small Cell Satellite Backhaul Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Mobile Network Operators (MNOs)
- 12.3.7.2 Neutral Host Providers
- 12.3.7.3 Government & Defense
- 12.3.7.4 Enterprises (Oil & Gas, Mining, Energy, Transport)
- 12.3.7.5 Fixed Wireless ISPs
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Software
- 12.4.7.3 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 4G LTE Backhaul
- 12.5.7.2 5G Small-Cell Backhaul
- 12.5.7.3 IoT / M2M Backhaul
- 12.5.7.4 Rural & Remote Connectivity
- 12.5.7.5 Temporary Events / Disaster Recovery
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Satellite Type - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Volume Forecast, 2018-2032
- 12.6.5 Base-Year Market Share, 2018
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 LEO (Low Earth Orbit)
- 12.6.7.2 MEO (Medium Earth Orbit)
- 12.6.7.3 GEO (Geostationary Orbit)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Small Cell Satellite Backhaul End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Small Cell Satellite Backhaul Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Small Cell Satellite Backhaul Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Small Cell Satellite Backhaul Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 SpaceX (Starlink)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Eutelsat OneWeb
- 18.4 Viasat (including Inmarsat)
- 18.5 SES S.A.
- 18.6 Intelsat
- 18.7 Telesat
- 18.8 Iridium Communications
- 18.9 Hughes Network Systems (EchoStar)
- 18.10 Gilat Satellite Networks
- 18.11 Comtech Telecommunications
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

