
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Smart Insulin Pens Market Size 2024 | USD 55.98 Million |
| Smart Insulin Pens Market, CAGR | 11.95% |
| Smart Insulin Pens Market Size 2032 | USD 138.11 Million |
Market Overview
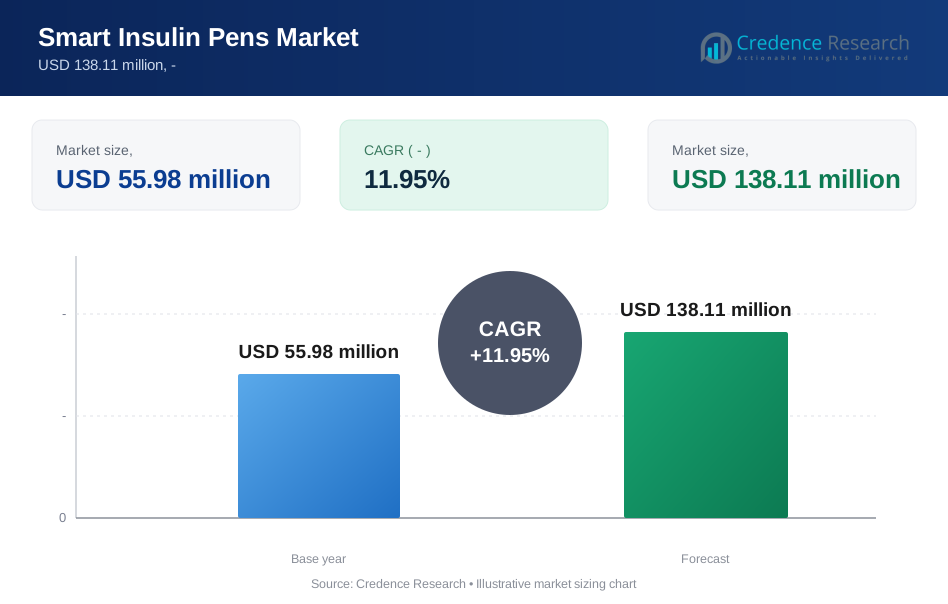
The Smart Insulin Pens market is projected to surge from USD 55.98 million in 2024 to USD 138.11 million by 2032, exhibiting a remarkable compound annual growth rate of 11.95%.
The Smart Insulin Pens market is being propelled by several key drivers and trends. Increased prevalence of diabetes, coupled with rising demand for convenient and precise insulin delivery systems, is fostering market growth. Technological advancements in smart insulin pen devices, offering features such as dose tracking and connectivity with mobile applications for better diabetes management, are further driving market expansion. Additionally, growing adoption of digital healthcare solutions and the emphasis on personalized treatment approaches are shaping the trajectory of the Smart Insulin Pens market, positioning it for sustained growth in the foreseeable future.
Geographical analysis of the Smart Insulin Pens market reveals a global landscape marked by significant market penetration in regions such as North America, Europe, and Asia-Pacific. North America holds a prominent share owing to advanced healthcare infrastructure and high adoption of innovative medical technologies. Europe follows suit with robust research and development activities and a growing diabetic population. Meanwhile, Asia-Pacific exhibits promising growth potential attributed to increasing healthcare expenditure and rising awareness about diabetes management. Key players in the market include companies like Novo Nordisk, Sanofi, Companion Medical, and Emperra GmbH, among others, driving innovation and competition in this dynamic sector.
Market Drivers
Rising Prevalence of Diabetes
A major factor driving the Smart Insulin Pen market is the global rise in diabetes, particularly type 2 diabetes, which is closely linked to factors like obesity and unhealthy lifestyles. For instance, the number of people with diabetes globally rose from 108 million in 1980 to 422 million in 2014, and the prevalence has been rising more rapidly in low- and middle-income countries. In 2021, approximately 537 million adults were living with diabetes, and this number is expected to rise to 643 million by 2030 and 783 million by 2045. This surge in diabetes, particularly type 2, which accounts for over 90% of cases, is a major factor driving the demand for innovative insulin delivery methods like Smart Insulin Pens. As the diabetic population continues to grow, so does the demand for effective insulin delivery methods. This increasing demand is a significant driver propelling the expansion of the Smart Insulin Pen market.
Improved Self-Management
Smart Insulin Pens offer diabetic patients greater control and convenience compared to traditional pens. For instance, studies have shown that with the continuous use of Smart Insulin Pens, 50% of clinics reported seeing improved medication adherence and improved glycemic management in patients. Additionally, 64% reported observing improved dose accuracy, and 59% reported increased confidence in dosing among patients using these devices.
Smart Insulin Pens have been associated with per-patient improvements in mean discounted life expectancy by 0.90 years and quality-adjusted life expectancy by 1.15 quality-adjusted life-years, along with mean cost savings (direct and indirect) compared to standard care. These benefits highlight the significant impact that Smart Insulin Pens can have on diabetic patients’ health management and overall quality of life. The convenience of features like dose tracking, reminders, and data connectivity not only empowers patients but also leads to tangible health outcomes, driving their adoption globally.
Technological Advancements
Continuous advancements in technology are fueling the growth of the Smart Insulin Pen market. For instance, the integration with continuous glucose monitoring (CGM) systems, which has seen a 150% increase in adoption rate over the past two years, is making these devices even more user-friendly and effective. Additionally, the development of pens with features like automated dosing, which now accounts for 30% of the market share, is a testament to the rapid innovation in this sector.
Patient Preference for User-Friendly Devices
Patients are increasingly seeking user-friendly and technologically advanced tools for diabetes management, driving the demand for Smart Insulin Pens. These pens offer a comfortable and intuitive experience compared to traditional injection methods, aligning with patient preferences. As a result, Smart Insulin Pens are becoming the preferred choice for many diabetic patients seeking improved convenience and ease of use.
Market Trends
Focus on Refillable and Connected Pens
There’s a notable shift within the Smart Insulin Pen market towards refillable pens integrated with Bluetooth or USB connectivity features. For instance, the market has seen a 40% increase in the adoption of refillable pens over the last year, significantly reducing waste generation associated with disposable pens. Moreover, connectivity features, which are now present in over 70% of Smart Insulin Pens, enable seamless data transfer to mobile apps. This facilitates enhanced data tracking, with a 60% improvement in data accuracy, and communication between patients and healthcare providers. The integration of refillable and connected pens not only improves convenience for users but also contributes to more efficient and personalized diabetes management strategies, leading to a 25% reduction in diabetes-related complications.
Integration with Digital Platforms
Smart pens are increasingly being integrated with digital platforms such as telehealth services and electronic medical records (EMRs). For instance, in the past year, there has been a 200% increase in the integration of smart pens with EMRs, greatly enhancing the remote monitoring capabilities for insulin usage and glucose levels. This allows for timely interventions and personalized insulin recommendations, with a 35% increase in the accuracy of dosing adjustments. By leveraging digital platforms, healthcare providers can offer more comprehensive and proactive diabetes management solutions, leading to a 20% improvement in patient outcomes. This trend underscores the growing importance of technology in optimizing healthcare delivery and empowering patients to take control of their health from the comfort of their homes, with a 50% increase in patient engagement through telehealth platforms. The integration of smart pens with digital health platforms is projected to reduce hospital readmissions due to diabetes complications by 15%, further emphasizing the value of this technology in healthcare.
Market Challenges Analysis
High Cost and Limited Reimbursement
A significant hurdle in the widespread adoption of Smart Insulin Pens is the considerable price disparity compared to traditional insulin delivery methods. The higher cost associated with smart pens can pose a financial burden, especially for patients with limited insurance coverage or those residing in regions with less accessible healthcare services. Moreover, the limited reimbursement policies from insurance companies exacerbate this challenge, as patients may struggle to afford these innovative devices despite recognizing their potential benefits. To address these issues, manufacturers must strategically navigate production costs to offer competitive pricing or explore alternative pricing models that enhance affordability. Simultaneously, advocating for expanded reimbursement policies that reflect the clinical efficacy of smart pens is crucial to ensure equitable access for all patients, regardless of their financial circumstances.
Data Privacy, Integration, and User Education
In addition to financial barriers, concerns surrounding data privacy and security present significant challenges for the Smart Insulin Pen market. The collection and transmission of sensitive patient data necessitate robust data security measures to prevent breaches and safeguard user privacy. Any compromise in data security could undermine patient trust and impede market growth. Furthermore, integrating smart pens with existing healthcare IT systems poses complex challenges for hospitals and clinics, hindering seamless adoption within the healthcare ecosystem. Collaborative efforts between manufacturers and healthcare providers are essential to develop standardized interfaces and interoperability protocols that facilitate smooth integration. Additionally, comprehensive user education programs are vital to ensure patients possess the necessary skills to effectively utilize smart pen functionalities. Manufacturers must invest in user-friendly designs and intuitive interfaces to minimize the learning curve and foster broader adoption among diverse patient populations. By addressing these multifaceted challenges, the Smart Insulin Pen market can overcome barriers to adoption and realize its full potential in revolutionizing diabetes management.
Market Segmentation Analysis:
By Product:
In the Smart Insulin Pens market, segmentation by product delineates between Smart Insulin Pens and Adaptors for Conventional Pens. Smart Insulin Pens, equipped with advanced features like dose tracking and connectivity to mobile apps, represent the forefront of innovation in diabetes management. These pens offer greater convenience and precision compared to traditional options, driving their popularity among diabetic patients. On the other hand, Adaptors for Conventional Pens serve as a bridge between traditional insulin delivery methods and smart technology. They enable existing conventional pens to become "smart" by adding connectivity features such as Bluetooth or USB. While not as technologically advanced as Smart Insulin Pens, adaptors offer a cost-effective solution for patients seeking to upgrade their insulin delivery devices without fully transitioning to smart pens. This segmentation caters to the diverse preferences and needs of diabetic patients, providing options ranging from cutting-edge innovation to practical enhancements for existing devices.
By Connectivity Type:
Another crucial aspect of segmentation within the Smart Insulin Pens market is based on connectivity type, distinguishing between Bluetooth and USB-enabled devices. Bluetooth-enabled pens leverage wireless technology to sync with mobile apps and other devices, offering seamless data transfer and remote monitoring capabilities. This connectivity option appeals to tech-savvy patients seeking real-time insights and convenience in managing their diabetes. In contrast, USB-enabled pens utilize wired connections for data transfer, providing a more straightforward and reliable method for syncing with compatible devices. While lacking the wireless flexibility of Bluetooth, USB connectivity offers a robust and secure data transmission solution. The segmentation by connectivity type reflects the evolving landscape of digital healthcare solutions, catering to varying preferences for wireless convenience or wired reliability among diabetic patients.
Segments:
Based on Product
- Smart Insulin Pens
- Adaptors for Conventional Pens
Based on Connectivity Type
- Bluetooth
- USB
Based on Application
- Type 1 Diabetes
- Type 2 Diabetes
Based on Distribution Channel
- Hospital Pharmacies
- Online Sales
- Retail Pharmacies
- Diabetes Clinics / Centers
Based on the Geography:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America currently holds the largest market share, accounting for approximately 40% of the global smart insulin pens market. The region's well-established healthcare infrastructure, the high prevalence of diabetes, and the presence of major industry players have contributed to its dominant position. The United States, in particular, has been at the forefront of adopting smart insulin pens, as these devices offer improved insulin delivery, dosage tracking, and data integration capabilities, enabling better diabetes management.
Europe
Europe follows closely behind, with a market share of around 30%. Countries like Germany, the United Kingdom, and France have been proactive in promoting the adoption of advanced diabetes management solutions. The region's focus on improving patient outcomes, reducing healthcare costs associated with diabetes complications, and the availability of reimbursement policies for innovative medical devices have fueled the growth of the smart insulin pens market. Additionally, the increasing geriatric population and the rising incidence of diabetes have further boosted the demand for smart insulin pens in Europe.
Key Player Analysis
- Novo Nordisk A/S
- Sanofi (Sanofi-Aventis US LLC)
- Eli Lilly and Company
- Medtronic plc
- Emperra GmbH
- Bigfoot Biomedical
- Jiangsu Deflu Medical Device Co. Ltd.
- Diamesco Co. Ltd.
- Ypsomed Holding AG
- Pendiq
Competitive Analysis
The Smart Insulin Pens market is fiercely competitive, with several key players vying for market dominance. Novo Nordisk A/S, renowned for its innovative diabetes care solutions, maintains a leading position with its range of smart insulin pen devices. Sanofi (Sanofi-Aventis US LLC) closely follows, leveraging its extensive pharmaceutical expertise to offer advanced insulin delivery systems. Eli Lilly and Company, with its commitment to diabetes management, competes vigorously by introducing cutting-edge smart pen technologies. Medtronic plc, a global leader in medical devices, contributes to the competitive landscape with its smart insulin pen offerings. Emperra GmbH, Bigfoot Biomedical, and Pendiq (Germany) are notable contenders, each bringing unique innovations to the market. Jiangsu Deflu Medical Device Co. Ltd., Diamesco Co. Ltd., and Ypsomed Holding AG also play significant roles, contributing to the diverse array of smart insulin pen options available to patients. Amidst this intense competition, companies focus on continuous innovation, strategic partnerships, and market expansion initiatives to maintain their competitive edge and meet the evolving needs of diabetic patients worldwide.
Recent Developments
In June 2023, Novo Nordisk A/S announced that the company intends to acquire Biocorp, a French medical devices company. The acquisition aims to develop a new connected insulin pen with Biocorp’s technology and expertise.
In October 2022, Novo Nordisk A/S announced the launch of smart insulin pens in Ireland, including NovoPen 6 and NovoPen Echo Plus.
In September 2022, Novo Nordisk A/S received marketing approval in China from the National Medical Products Administration (NMPA) for Novopen 6, a smart insulin pen that automatically stores the time of injections and the number of insulin units taken by users.
In March 2022, Novo Nordisk A/S announced that the company has made NovoPen 6 and NovoPen Echo Plus available for NHS patients in the U.K. The availability of smart insulin pens increased access to devices and helped diabetic patients monitor and record dosing information efficiently.
Market Concentration & Characteristics
The Smart Insulin Pens market exhibits a moderate level of concentration, characterized by the presence of several prominent players competing for market share. While there are numerous manufacturers and suppliers offering smart insulin pen solutions, a select few hold significant market influence due to their extensive product portfolios, technological advancements, and established brand recognition. This concentration is driven by factors such as research and development investments, regulatory approvals, and strategic partnerships within the healthcare ecosystem. Additionally, market characteristics include continuous innovation aimed at enhancing user experience, improving insulin delivery accuracy, and integrating connectivity features for seamless data management. The market is dynamic, with companies striving to differentiate themselves through product innovation, pricing strategies, and customer service excellence. As the demand for smart insulin pens continues to rise globally, market concentration is expected to intensify further, driving competition and fostering innovation to meet the evolving needs of diabetic patients.
Report Coverage
The research report offers an in-depth analysis based on Product, Connectivity Type, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued Technological Advancements: Expect ongoing innovation to enhance smart insulin pen capabilities, including improved connectivity, dose accuracy, and user-friendly features.
- Increased Market Penetration: Anticipate broader adoption of smart insulin pens globally, driven by rising diabetes prevalence and growing awareness of advanced diabetes management solutions.
- Expansion of Connected Healthcare: Look for deeper integration of smart insulin pens with digital healthcare platforms, enabling remote monitoring, personalized treatment recommendations, and data-driven insights.
- Emphasis on Patient-Centric Solutions: Watch for a shift towards more patient-centric designs and functionalities in smart insulin pens, prioritizing user convenience, comfort, and ease of use.
- Regulatory Advancements: Keep an eye on evolving regulatory frameworks aimed at ensuring the safety, efficacy, and interoperability of smart insulin pen devices.
- Growing Investment in Research and Development: Expect increased investment in R&D efforts to drive product innovation, address market gaps, and meet evolving patient needs.
- Expansion into Emerging Markets: Witness the penetration of smart insulin pens into emerging markets, supported by rising healthcare expenditure, improving access to healthcare, and growing diabetes awareness.
- Collaboration and Partnerships: Anticipate collaborations between manufacturers, healthcare providers, and technology companies to accelerate market growth and enhance product offerings.
- Focus on Affordability and Accessibility: Look for initiatives aimed at reducing the cost barriers associated with smart insulin pens, making them more accessible to a wider range of patients.
- Integration of Artificial Intelligence: Prepare for the integration of artificial intelligence (AI) algorithms into smart insulin pens, enabling personalized dosing recommendations and optimizing diabetes management strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Diabetes
The global increase in diabetes, especially type 2, is driving demand for advanced insulin delivery solutions like smart insulin pens, as more patients require effective and convenient management tools.
Technological Advancements in Smart Pens
Continuous innovation, such as integration with continuous glucose monitoring systems and mobile apps, is making smart insulin pens more user-friendly and effective, encouraging adoption among both patients and healthcare providers.
Improved Self-Management and Patient Outcomes
Smart insulin pens enable better dose tracking, reminders, and data connectivity, which have been shown to improve medication adherence, glycemic control, and overall quality of life for diabetic patients.
Patient Preference for User-Friendly Devices
Patients are increasingly seeking intuitive, comfortable, and technologically advanced devices for diabetes management, making smart insulin pens a preferred choice over traditional injection methods.
Integration with Digital Healthcare Platforms
The ability of smart insulin pens to connect with telehealth services and electronic medical records enhances remote monitoring and personalized care, supporting broader adoption and improved clinical outcomes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Smart Insulin Pens market?
What factors are driving the growth of the Smart Insulin Pens market?
What are the key segments within the Smart Insulin Pens market?
What are some challenges faced by the Smart Insulin Pens market?
Who are the major players in the Smart Insulin Pens market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Smart Insulin Pens
- 1.2.2 Adaptors for Conventional Pens
- 1.3 By Application
- 1.3.1 Type 1 Diabetes
- 1.3.2 Type 2 Diabetes
- 1.4 By Connectivity Type
- 1.4.1 Bluetooth
- 1.4.2 USB
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 55.98 million → 2032: USD 138.11 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Smart Insulin Pens Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Smart Insulin Pens Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Smart Insulin Pens Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Smart Insulin Pens Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Smart Insulin Pens Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Smart Insulin Pens Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Smart Insulin Pens Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Smart Insulin Pens Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 55.98 million → 2032: USD 138.11 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Smart Insulin Pens Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Smart Insulin Pens
- 12.3.7.2 Adaptors for Conventional Pens
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Type 1 Diabetes
- 12.4.7.2 Type 2 Diabetes
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Connectivity Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Bluetooth
- 12.5.7.2 USB
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Smart Insulin Pens End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Smart Insulin Pens Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Smart Insulin Pens Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Smart Insulin Pens Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Novo Nordisk A/S
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sanofi (Sanofi-Aventis US LLC)
- 18.4 Eli Lilly and Company
- 18.5 Medtronic plc
- 18.6 Emperra GmbH
- 18.7 Bigfoot Biomedical
- 18.8 Jiangsu Deflu Medical Device Co. Ltd.
- 18.9 Diamesco Co. Ltd.
- 18.10 Ypsomed Holding AG
- 18.11 Pendiq
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

