
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Soft Magnetic Materials Market Size 2023 | USD 34,419.13 Million |
| Soft Magnetic Materials Market, CAGR | 6.58% |
| Soft Magnetic Materials Market Size 2032 | USD 63,657.49 Million |
Market Overview:
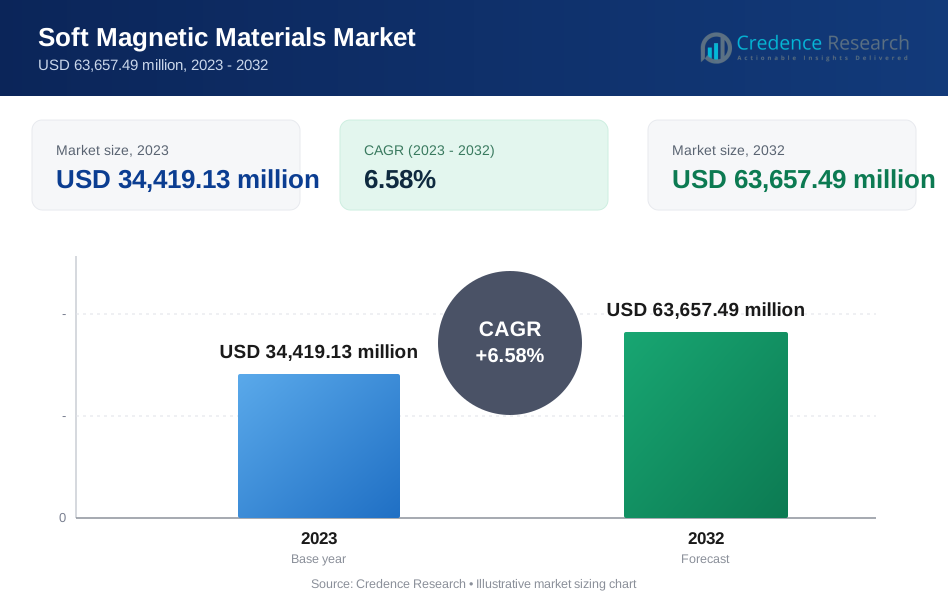
The market for soft magnetic materials (SMMs) is poised for substantial growth, with a projected compound annual growth rate (CAGR) of 6.58%, from USD 34,419.13 million in 2023 to USD 63,657.49 million by 2032. This significant expansion is underpinned by various key factors driving technological advancements worldwide. One pivotal driver is the rising demand for energy efficiency, where SMMs play a critical role in the development of energy-saving transformers, motors, and generators. As global energy consumption continues to escalate, the utilization of SMMs in energy-efficient technologies is expected to soar, fostering market growth.
The electronics industry represents another major avenue for the expansion of the SMM market. With the ongoing miniaturization and increasing functionality of electronic devices, SMMs find extensive use in components like transformers, inductors, and electromagnetic interference (EMI) shielding. This trend is anticipated to drive substantial demand for SMMs within the electronics sector. Additionally, the burgeoning electric vehicle (EV) market presents a significant growth opportunity. As EV adoption accelerates globally, driven by environmental concerns and government initiatives, the demand for SMMs in electric motors and transformers is expected to surge, further propelling market growth.
Furthermore, advancements in material science are fostering the development of new and improved SMMs with superior properties such as higher permeability and lower core losses. These advancements aim to enhance operational efficiency across various applications. Geographically, the Asia-Pacific region, particularly countries like China, Japan, and South Korea, is expected to emerge as a dominant player in the SMM market. This prominence is attributed to the presence of major electronics and automotive manufacturing hubs in the region, coupled with growing urbanization and increasing disposable income. Such regional developments are poised to significantly contribute to the expansion of the global SMM market in the coming years.
Segmentation Analysis:
By Product
Soft magnetic materials encompass various types, each serving distinct purposes within different industries. Electrical steel, made of a silicon-iron alloy, dominates the market due to its exceptional magnetic properties, affordability, and widespread applicability in transformers, motors, and generators. Conversely, soft ferrites, known for their high resistivity and low eddy current losses, are anticipated to witness significant growth, particularly in high-frequency applications such as power electronics and filters. Cobalt-iron alloys offer superior magnetic characteristics suitable for high-performance applications like magnetic recording heads and aerospace components, albeit at a higher cost, potentially limiting their widespread adoption. Emerging materials like soft magnetic composites and amorphous metals exhibit unique properties such as being lightweight, having near-net shape capabilities, and having low core losses, hinting at increased market penetration as advancements continue and costs decrease.
By end-user industries
Across various end-user industries, soft magnetic materials play vital roles. In the automotive sector, especially in electric and hybrid vehicles, these materials are essential for high-efficiency motors and transformers. The electronics industry utilizes soft magnetic materials in components like transformers, inductors, and filters found in consumer electronics, power supplies, and telecommunication equipment. The energy sector's increasing reliance on renewable sources like wind and solar power drives demand for soft magnetic materials in transformers and generators for efficient power transmission and distribution. In industrial machinery, including manufacturing processes and automation equipment, soft magnetic materials are crucial components in motors, generators, and transformers. Additionally, specialized applications in the medical field (MRI machines) and aerospace industry (aircraft components) also rely on soft magnetic materials for specific requirements.
Segments:
- By Application
- Motors
- Transformers
- Alternators
- Others
- By Product
- Electrical Steel
- Ferrite
- Permalloys
- Others
- By Regional
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- Italy
- Turkey
- Asia Pacific
- China
- Japan
- South Korea
- Central and South America
- Brazil
- The Middle East and Africa
- North America
Market Drivers:
Rise of Electric Vehicles (EVs) and Hybrid Electric Vehicles (HEVs):
In addition to the global sales, the adoption of EVs and HEVs is also increasing at a national level. In Norway, over 75% of new cars sold in 2023 were electric. This is largely due to the country’s comprehensive policies promoting electric mobility, such as tax incentives and subsidies. Furthermore, several major automakers have announced plans to transition to electric vehicles. For example, General Motors plans to sell only zero-emission vehicles by 2035. These trends indicate a growing market for soft magnetic materials in the automotive sector.
Expanding the Renewable Energy Sector:
In terms of renewable energy, countries like China and the United States are leading the way. For instance, in 2023, China added 120 GW of solar power capacity, while the United States added 15 GW of wind power capacity. Moreover, the cost of renewable energy technologies is decreasing. The cost of solar photovoltaic (PV) modules has fallen by 89% since 2010, for instance. This makes renewable energy a more affordable and attractive option, which is likely to drive further growth in the sector and, consequently, increase the demand for soft magnetic materials.
Automation and industrialization:
The ongoing trend towards automation and industrialization across diverse sectors is fueling the demand for soft magnetic materials. These materials serve as essential components in various industrial automation equipment, robots, and control systems. As industries strive for heightened efficiency and automation to optimize their operations, there is a corresponding need for high-performance soft magnetic materials. This trend is anticipated to drive sustained growth in the market as automation becomes increasingly prevalent across industries.
Advancements in Material Science and Technology:
Continuous advancements in material science and technology are leading to the development of new and improved soft magnetic materials with enhanced properties. These advancements focus on key aspects such as reduced core losses, higher permeability, and miniaturization. Lowering energy losses within the material enhances the efficiency of transformers and motors, while enhanced permeability allows for better magnetic flux transmission, resulting in improved performance across various applications. Additionally, the development of soft magnetic materials suitable for miniaturization enables the creation of more compact and efficient electronic devices, further contributing to market growth.
Growing Focus on Energy Efficiency:
The global emphasis on energy conservation and environmental sustainability is a driving force behind the growing demand for energy-efficient technologies, including soft magnetic materials. The properties of soft magnetic materials directly impact the efficiency of transformers, motors, and other electrical equipment. As regulations and consumer preferences increasingly prioritize energy efficiency, there is a corresponding rise in demand for high-performance soft magnetic materials capable of meeting stringent efficiency standards. This focus on energy efficiency is expected to drive significant growth in the market as industries seek sustainable solutions to reduce energy consumption and environmental impact.
Infrastructure Development and Upgrades:
Investments in infrastructure development and upgrades across various sectors, including power grids, transportation systems, and communication networks, are creating a demand for reliable and efficient electrical components, including soft magnetic materials. Soft magnetic materials play a vital role in these applications, ensuring the efficient operation of transformers, motors, and other electrical equipment essential for infrastructure projects. With ongoing infrastructure development initiatives globally, the demand for soft magnetic materials is projected to continue rising, presenting lucrative opportunities for market players.
Market Trends:
Surge in Demand for Energy-Efficient Technologies:
Growing environmental concerns and a focus on energy conservation are driving the demand for energy-efficient technologies across various sectors. Soft magnetic materials play a crucial role in these technologies by minimizing energy losses in transformers, motors, and generators. For instance, in the automotive industry, advancements in electric vehicle technology necessitate the use of high-performance soft magnetic materials for efficient motor operation. This surge in the electric vehicle market is a testament to the increasing demand for energy-efficient technologies. Another instance can be seen in the renewable energy sector, where energy-efficient wind turbines and solar panels are increasingly being adopted. These technologies also rely on soft magnetic materials for optimal performance.
Rise of Automation and Industrialization:
The increasing adoption of automation and robotics in various industries, including manufacturing and healthcare, is propelling the demand for soft magnetic materials. These materials are essential components in motors, actuators, and transformers used in automated equipment, contributing to improved efficiency and precision in industrial processes. For instance, the market was negatively impacted due to COVID-19, but it recovered and increased at a significant rate. The demand for soft magnetic materials is increasing due to their usage in major industries such as electronics, automotive, and energy, with the rising adoption of electric vehicles, renewable energy systems, and smart devices. The electric car market, in particular, is experiencing remarkable growth, with sales exceeding 10 million in 2022. The Asia-Pacific region dominated the market globally, with the largest consumption coming from countries like China, India, and Japan. The robust industrialization across Asia-Pacific countries, coupled with geographical advantages such as the presence of iron mines in India and China, is the driving force behind the soft magnetic materials market in this region.
Focus on Miniaturization and Performance Enhancement:
The trend towards miniaturization of electronic devices demands high-performance soft magnetic materials with exceptional properties like high permeability and low core losses. This allows for the development of compact and efficient electronic components used in consumer electronics, power electronics, and telecommunication infrastructure.
Expansion into New Applications:
Soft magnetic materials are finding applications beyond traditional sectors like motors and transformers. They are increasingly being used in emerging technologies like magnetic resonance imaging (MRI) equipment, wind turbines, and energy storage solutions. This diversification in application areas opens new avenues for market growth.
Geographical Growth in Emerging Economies:
Rising disposable income and rapid industrialization in developing economies like China, India, and Southeast Asia are creating a significant demand for soft magnetic materials. These regions are experiencing a surge in infrastructure development, automotive production, and consumer electronics consumption, all of which rely on these materials.
Market Restraints and Challenges:
Fluctuating Raw Material Prices and Supply Chain Disruptions:
The soft magnetic materials market is susceptible to fluctuations in raw material prices, particularly for critical components like grain-oriented silicon steel (GOES), non-grain-oriented silicon steel (NGOES), and amorphous metals. The cost and availability of these materials directly impact production costs, leading to price volatility in the market. Moreover, geopolitical tensions, trade wars, and unforeseen events can disrupt the global supply chain, causing delays in raw material procurement and production slowdowns. Reliance on specific geographic regions for crucial raw materials further exposes manufacturers to risks associated with supply chain disruptions, necessitating strategic planning to mitigate such challenges.
Stringent Environmental Regulations and Sustainability Concerns:
Manufacturers of soft magnetic materials face increasing pressure from environmental regulations regarding the mining, processing, and disposal of raw materials. Energy consumption during the production process is another area of scrutiny, prompting the need for cleaner production technologies. To comply with regulations and meet sustainability goals, manufacturers are compelled to invest in environmentally friendly practices, such as adopting cleaner production processes and exploring the use of recycled materials. However, these sustainability initiatives may entail additional costs, impact production expenses, and potentially influence market dynamics.
Competition from Alternative Materials and Technologies:
The soft magnetic materials market encounters competition from alternative materials like ferrites and advanced composites in specific applications. Furthermore, advancements in permanent magnet technologies and alternative motor designs pose a potential threat by reducing the demand for soft magnetic materials in certain sectors. To maintain a competitive edge, manufacturers must continuously innovate and enhance the performance characteristics of soft magnetic materials. This entails improving efficiency, power density, and other essential properties to meet evolving market demands and stay ahead of competitors.
High initial investment and technological expertise are required.
The establishment of production facilities for soft magnetic materials demands significant upfront investment in specialized equipment and processes. This substantial initial investment can pose a barrier for new entrants and smaller players in the market, limiting their ability to compete effectively. Additionally, continuous research and development (R&D) efforts are essential for developing new and improved soft magnetic materials. However, these R&D activities entail additional costs, further adding to the operational expenses for manufacturers and highlighting the importance of financial resources and technological expertise in the industry.
Limited Skilled Workforce and Knowledge Transfer:
The soft magnetic materials industry relies on a skilled workforce proficient in material science, processing techniques, and characterization methods. However, an aging workforce coupled with limited knowledge transfer to younger generations poses a challenge to maintaining a skilled labor pool. This skill gap could hinder innovation and production efficiency within the industry. To address this issue, companies need to prioritize knowledge transfer initiatives, invest in training programs, and collaborate with educational institutions to ensure the availability of a competent workforce capable of driving innovation and sustaining industry growth.
Key player:
- Arnold Magnetic Technologies
- Hitachi Metals Group
- JFE Steel Group
- Mahindra CIE
- MATE CO., LTD.
- Meyer Sintermetall AG
- Sintered Specialties, LLC
- Steward Advanced Materials, LLC
- VACUUMSCHMELZE GmbH & Co. KG
- GKN Sinter Metals Engineering GmbH
Recent Developments:
- In January 2022, Daido Steel Co., Ltd. introduced a new product called STARPAS-50PC2S permalloy foil, which is designed to effectively suppress EMC noise, particularly magnetic noise, at low frequencies below approximately 100 kHz. This noise is usually caused by higher frequencies in communication and IoT devices, as well as electric automobiles. This product launch is expected to boost the soft magnetic material market.
- In January 2022, JFE Steel Corporation also launched Denjiro, which is an insulation-coated pure iron powder for soft magnetic composites. This product is ideally suited to axial gap motors and has been added to their broad lineup of soft magnetic materials.
Regional Analysis:
Asia Pacific
Asia Pacific dominates the global soft magnetic materials market, accounting for a substantial share of around 45%. The region's prominence can be attributed to the presence of major manufacturing hubs and the rapidly growing electrical and electronics industries, which are significant consumers of soft magnetic materials.Within Asia Pacific, China holds the largest market share, driven by its expansive manufacturing sector and the increasing demand for electrical appliances, automotive components, and renewable energy solutions. Other significant contributors to the region's market share include Japan, South Korea, and India, which have well-established electronics, automotive, and energy sectors.
North America
North America represents the second-largest regional market for soft magnetic materials, capturing a market share of approximately 30%. The United States leads the way in this region, fueled by its robust automotive industry, electrical and electronics manufacturing, and the growing adoption of renewable energy technologies, all of which necessitate the use of soft magnetic materials.
Europe
Europe accounts for a market share of around 20% in the global soft magnetic materials market. The region's well-developed automotive, electrical, and electronics industries, along with its commitment to sustainable energy solutions, drive the demand for soft magnetic materials. Germany, France, and the United Kingdom are among the major contributors to the European market.
Latin America, the Middle East, and Africa
The remaining 5% market share is distributed across other regions, including Latin America, the Middle East, and Africa, where the demand for soft magnetic materials is steadily increasing, driven by industrialization, infrastructure development, and the adoption of renewable energy technologies.
Future Outlook:
- The increasing adoption of EVs and HEVs will significantly drive the demand for soft magnetic materials used in electric motors, generators, and transformers.
- Growing emphasis on energy conservation will propel the use of soft magnetic materials in transformers and power distribution equipment, leading to lower energy losses.
- Continuous advancements in material science are expected to lead to the development of new soft magnetic materials with improved properties like higher permeability, lower core losses, and better machinability.
- The burgeoning renewable energy sector, particularly wind power generation, will create a significant demand for soft magnetic materials used in wind turbines.
- Increasing automation across various industries will fuel the demand for soft magnetic materials in motors and actuators used in automated systems and robots.
- The Asia Pacific region, driven by rapid industrialization and government initiatives promoting renewable energy and electric vehicles, is expected to be a major growth market for soft magnetic materials.
- The growing demand for lightweight vehicles and portable electronic devices will encourage the development and adoption of lightweight, soft magnetic materials.
- Growing environmental concerns will lead to a focus on the development and utilization of recycled soft magnetic materials, promoting a circular economy approach.
- Stringent government regulations mandating the use of energy-efficient materials will further propel the demand for high-performance soft magnetic materials.
- As the market matures, mergers and acquisitions between key players are expected to occur, leading to industry consolidation and the emergence of stronger market leaders.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth of Electric Vehicles (EVs) and Hybrid Electric Vehicles (HEVs)
The rapid adoption of EVs and HEVs globally, supported by government incentives and automaker commitments to electrification, is significantly increasing the demand for soft magnetic materials in high-efficiency motors and transformers used in these vehicles.
Expansion of Renewable Energy Sector
The surge in renewable energy installations, such as wind turbines and solar power systems, requires efficient transformers and generators that rely on soft magnetic materials, driving market growth as countries invest in sustainable energy infrastructure.
Advancements in Material Science and Technology
Continuous R&D is leading to the development of soft magnetic materials with improved properties like higher permeability and lower core losses, enabling more efficient and compact electrical devices and expanding their application scope.
Rising Automation and Industrialization
The increasing implementation of automation and robotics in manufacturing and industrial processes is boosting the need for high-performance soft magnetic materials in motors, actuators, and control systems, supporting greater operational efficiency.
Focus on Energy Efficiency and Regulatory Standards
Stricter energy efficiency regulations and a global emphasis on reducing energy consumption are compelling manufacturers to adopt advanced soft magnetic materials in transformers, motors, and other electrical equipment to meet stringent performance standards.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the soft magnetic materials market from 2023 to 2032?
What factors are driving the growth of the soft magnetic materials market?
Who are the major players in the soft magnetic materials market?
How is the soft magnetic materials market expected to evolve geographically?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Electrical Steel
- 1.2.2 Ferrite
- 1.2.3 Permalloys
- 1.2.4 Others
- 1.3 By Application
- 1.3.1 Motors
- 1.3.2 Transformers
- 1.3.3 Alternators
- 1.3.4 Others
- 1.4 By End-User Industry
- 1.4.1 Automotive
- 1.4.2 Electronics
- 1.4.3 Energy
- 1.4.4 Industrial Machinery
- 1.4.5 Medical & Aerospace
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 34,419.13 million → 2032: USD 63,657.49 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Soft Magnetic Materials Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Soft Magnetic Materials Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Soft Magnetic Materials Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Soft Magnetic Materials Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Soft Magnetic Materials Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Soft Magnetic Materials Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Soft Magnetic Materials Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Soft Magnetic Materials Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 34,419.13 million → 2032: USD 63,657.49 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Soft Magnetic Materials Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Electrical Steel
- 12.3.7.2 Ferrite
- 12.3.7.3 Permalloys
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Motors
- 12.4.7.2 Transformers
- 12.4.7.3 Alternators
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-User Industry - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automotive
- 12.5.7.2 Electronics
- 12.5.7.3 Energy
- 12.5.7.4 Industrial Machinery
- 12.5.7.5 Medical & Aerospace
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Soft Magnetic Materials End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Soft Magnetic Materials Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Soft Magnetic Materials Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Soft Magnetic Materials Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Arnold Magnetic Technologies
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Hitachi Metals Group
- 18.4 JFE Steel Group
- 18.5 Mahindra CIE
- 18.6 MATE CO., LTD.
- 18.7 Meyer Sintermetall AG
- 18.8 Sintered Specialties, LLC
- 18.9 Steward Advanced Materials, LLC
- 18.10 VACUUMSCHMELZE GmbH & Co. KG
- 18.11 GKN Sinter Metals Engineering GmbH
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

