
Market Overview:
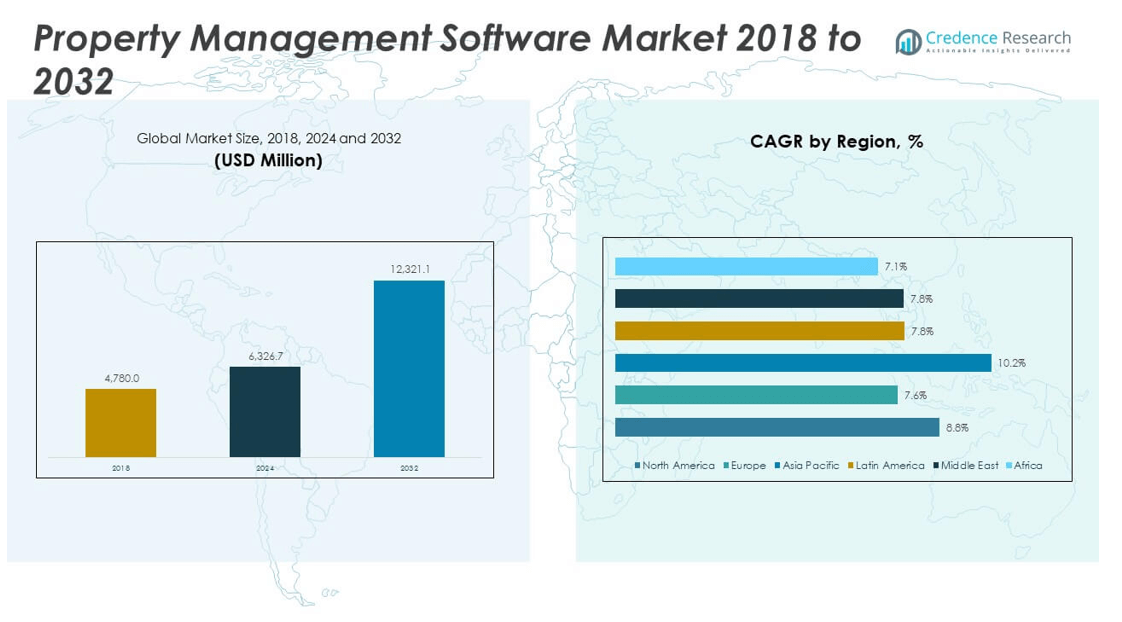
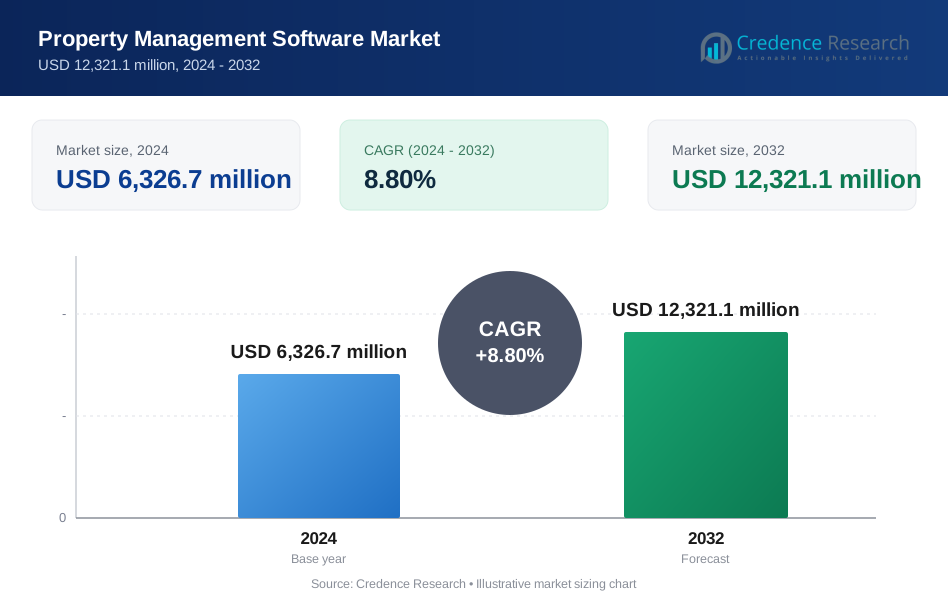
The Property Management Software Market size was valued at USD 4,780.0 million in 2018 to USD 6,326.7 million in 2024 and is anticipated to reach USD 12,321.1 million by 2032, at a CAGR of 8.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Property Management Software Market Size 2024 | USD 6,326.7 million |
| Property Management Software Market, CAGR | 8.8% |
| Property Management Software Market Size 2032 | USD 12,321.1 million |
The market growth is driven by the increasing adoption of digital solutions in real estate operations, as property owners and managers seek efficiency in rent collection, tenant communication, and maintenance tracking. Cloud-based platforms are gaining traction for offering scalability and remote accessibility, while integration with IoT, AI, and data analytics enhances decision-making and predictive management. Rising urbanization, the growing demand for rental housing, and the shift toward automation in facility management further accelerate the adoption of property management software across commercial and residential segments.
Geographically, North America leads the property management software market due to advanced digital infrastructure, widespread adoption of SaaS-based solutions, and the presence of established providers. Europe follows closely, with strong demand from the commercial real estate sector and regulatory compliance needs driving adoption. Meanwhile, Asia-Pacific emerges as the fastest-growing region, fueled by rapid urbanization, rising investments in smart city projects, and growing awareness of digital solutions in property management. Emerging economies in Latin America and the Middle East are also beginning to adopt such platforms to modernize real estate operations.
Market Insights:
- The Property Management Software Market was valued at USD 4,780.0 million in 2018, reached USD 6,326.7 million in 2024, and is projected to reach USD 12,321.1 million by 2032, growing at a CAGR of 8.8% during the forecast period.
- North America held the largest share at 44.8% in 2024, supported by strong SaaS adoption and a mature real estate sector, followed by Asia Pacific with 23.2% driven by urbanization, and Europe with 17.3% led by compliance-focused property operations.
- Asia Pacific represents the fastest-growing region with 23.2% share, fueled by smart city investments, expanding rental demand, and rising digital infrastructure across China, India, and Southeast Asia.
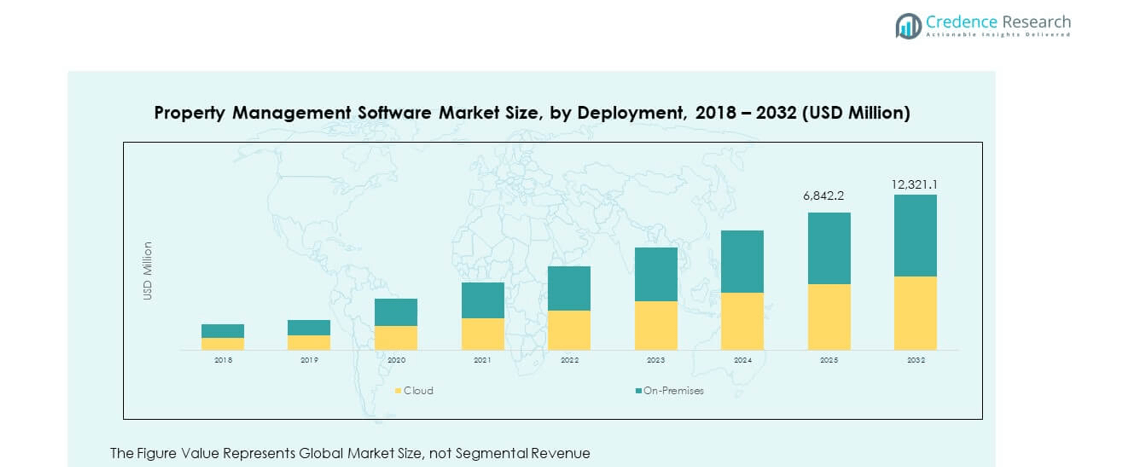
- In 2024, cloud deployment accounted for 63.5% of the Property Management Software Market, reflecting its dominance due to scalability, lower costs, and remote access advantages.
- On-premises solutions represented 36.5% of the Property Management Software Market in 2024, retaining presence among organizations prioritizing security, customization, and direct IT control.
Market Drivers:
Rising Digital Transformation in Real Estate Operations
The Property Management Software Market experiences strong growth due to increasing digital adoption in the real estate sector. Organizations seek efficient platforms that streamline tenant communication, rent collection, and facility maintenance. It reduces administrative workload by automating repetitive tasks and providing centralized control. Cloud deployment gains traction because it enhances remote accessibility and scalability. Integration with AI-driven analytics allows property managers to forecast tenant behavior and optimize resource allocation. The push for operational efficiency across residential and commercial properties supports rapid software adoption. Growing demand for rental housing and urban infrastructure projects strengthens reliance on property management tools.
- For instance, in June 2024, Yardi announced new AI-driven identification verification and maintenance labor tracking in its Breeze Premier software, with over 200 customers piloting the feature in the U.S. and Canada according to its official product update.
Growing Demand for Cloud-Based and Mobile-First Platforms
Property managers and owners increasingly prefer cloud solutions that provide flexibility, scalability, and secure access from any location. It ensures real-time data synchronization, which improves decision-making and operational transparency. Mobile-first platforms support tenants and landlords with seamless interaction through apps and digital dashboards. Rising use of mobile technology among property owners and residents enhances demand for mobile-enabled features. Automated billing, instant notifications, and on-the-go management become critical expectations. The Property Management Software Market benefits from these factors by witnessing strong growth across residential and commercial segments. Cloud platforms also reduce upfront costs, making adoption accessible to smaller property firms.
Integration of Emerging Technologies for Predictive Management
The Property Management Software Market advances as companies integrate IoT, AI, and machine learning features. Smart sensors improve monitoring of energy usage, water supply, and facility maintenance. It empowers property managers to adopt predictive approaches instead of reactive solutions. AI-driven analytics optimize tenant experience by predicting service needs and offering personalized engagement. Machine learning models enhance fraud detection and secure financial transactions. Digital twins and automation tools help simulate property performance and identify potential risks. Increased reliance on advanced technology boosts adoption across urban developments and smart city projects. This creates new efficiencies and supports long-term sustainability in operations.
- For example, Augury provides an AI-powered machine learning platform that monitors equipment such as HVAC systems to detect early signs of failure. Its predictive analytics help facility managers take proactive maintenance actions, reducing the risk of unplanned downtime and costly emergency repairs.
Rising Urbanization and Expanding Rental Housing Needs
The surge in global urban populations drives significant demand for rental housing and multi-family property solutions. It encourages property managers to invest in software platforms that centralize multiple property operations. Expanding infrastructure projects and real estate development intensify the need for efficient asset utilization. Urbanization accelerates challenges like high tenant turnover, which digital platforms can address effectively. The Property Management Software Market benefits from the growing reliance on automated tenant management systems. Integration of compliance features also ensures adherence to local housing regulations. Increasing property portfolios across metropolitan areas require scalable digital tools to maintain profitability and reduce manual errors.
Market Trends:
Increasing Emphasis on Data-Driven Decision Making
The Property Management Software Market is witnessing a major trend where property owners and managers prioritize data-driven insights. It leverages analytics to track tenant patterns, optimize rent structures, and identify inefficiencies. Real-time reporting tools enable managers to assess financial performance across multiple units. Automated dashboards support transparency and allow faster business decisions. The use of predictive analytics helps companies maximize occupancy rates and reduce maintenance downtime. More organizations adopt integrated reporting to align with investor expectations. Demand for business intelligence tools embedded within property software continues to expand across global markets.
Rise of Smart Building and Sustainability Solutions
Smart building technologies are transforming how properties are managed and maintained. It integrates energy monitoring, HVAC control, and lighting systems with software platforms. Growing environmental concerns push landlords to adopt sustainable solutions that reduce carbon footprint. The Property Management Software Market aligns with green building regulations and sustainability certifications. Tenants increasingly demand eco-friendly spaces supported by real-time energy tracking tools. Digital platforms empower managers to lower utility costs through automated efficiency controls. Sustainability features also strengthen property value in competitive rental markets. Integration of renewable energy management modules further elevates adoption.
- For instance, MRI Software offers an Energy Management Suite within its property solutions that helps clients collect utility data, monitor usage, detect anomalies, and manage tenant billing through dashboards and analytics.
Expansion of End-to-End Platforms and Ecosystem Integration
Companies demand unified solutions that cover leasing, accounting, communication, and compliance in a single interface. It allows property managers to avoid fragmented systems and enhance operational efficiency. Vendors in the Property Management Software Market expand their platforms by offering API integrations with financial, CRM, and payment systems. Ecosystem-based models attract enterprises seeking seamless workflows across multiple functions. Unified platforms also reduce training costs for staff by offering simplified user experiences. End-to-end systems enable faster tenant onboarding and streamlined lease management. Growing interest in comprehensive ecosystems pushes providers to invest heavily in platform expansion.
- For instance, In 2024, AppFolio expanded its AppFolio Stack Integration Marketplace by adding new certified partners such as Amazon Hub, AvidXchange, Birdeye, and Tenant Turner, strengthening its ecosystem of third-party integrations to enhance leasing, payments, and resident services.
Strong Focus on Tenant Experience and Customization Features
Tenant satisfaction becomes a critical priority for property owners aiming to reduce churn. It drives demand for software solutions that enhance communication, payment convenience, and personalized services. The Property Management Software Market reflects this shift by emphasizing tenant portals and self-service features. Customizable dashboards allow landlords to tailor services for diverse tenant groups. Integration of loyalty programs and digital engagement tools increases tenant retention. Personalized rental reminders, service updates, and virtual assistance further improve experience. Software providers increasingly differentiate their offerings by investing in tenant-focused innovations. This shift positions tenant engagement as a central factor for competitive advantage.
Market Challenges Analysis:
High Implementation Costs and Integration Complexity
The Property Management Software Market faces barriers due to significant upfront costs and integration challenges. Many small and mid-sized property owners hesitate to invest in advanced platforms because of limited budgets. It becomes difficult for them to align digital adoption with financial constraints. Integration with legacy systems creates technical bottlenecks that slow down implementation. Lack of skilled staff to operate complex software further limits adoption. Customization requirements add to project timelines and increase overall expenditure. Smaller property firms often rely on manual processes, delaying digital adoption. High costs and complexity continue to remain major challenges in scaling software penetration.
Concerns Over Data Security and Regulatory Compliance
Data privacy remains a major challenge for property managers adopting digital platforms. The Property Management Software Market must address rising risks of cyberattacks and tenant data breaches. It becomes critical for vendors to comply with regional regulations such as GDPR and other housing laws. Inconsistent compliance frameworks across countries create additional burdens for international players. Concerns about financial fraud during digital rent collection slow adoption in some markets. Vendors must ensure high-level encryption and secure payment gateways to retain trust. Lack of awareness about compliance standards among property managers further complicates the scenario. Security and regulatory risks continue to pose obstacles for broader software adoption.
Market Opportunities:
Expansion into Emerging Markets with Rising Urban Demand
Emerging economies present significant opportunities due to rapid urbanization and rising housing demands. The Property Management Software Market can capture growth by targeting cities with expanding rental populations. It supports landlords in managing large property portfolios where manual methods fail. Growing investments in smart city infrastructure create demand for digital solutions. It enables property managers to adopt scalable platforms that address local needs. Rising smartphone penetration further supports adoption of mobile-based property tools. Vendors focusing on customized solutions for emerging regions are likely to strengthen market presence.
Development of AI-Powered Personalization and Predictive Tools
Artificial intelligence offers strong opportunities to enhance tenant engagement and operational efficiency. The Property Management Software Market benefits from AI-driven chatbots, predictive analytics, and virtual assistants. It supports managers in forecasting tenant preferences, rent cycles, and service needs. Personalization features improve tenant loyalty and reduce vacancy risks. Predictive tools optimize maintenance schedules and extend asset lifecycle. Vendors that integrate advanced AI features differentiate their platforms in competitive markets. Growing interest in automation and personalized services positions AI-driven tools as a major opportunity for future expansion.
Market Segmentation Analysis:
The Property Management Software Market is segmented
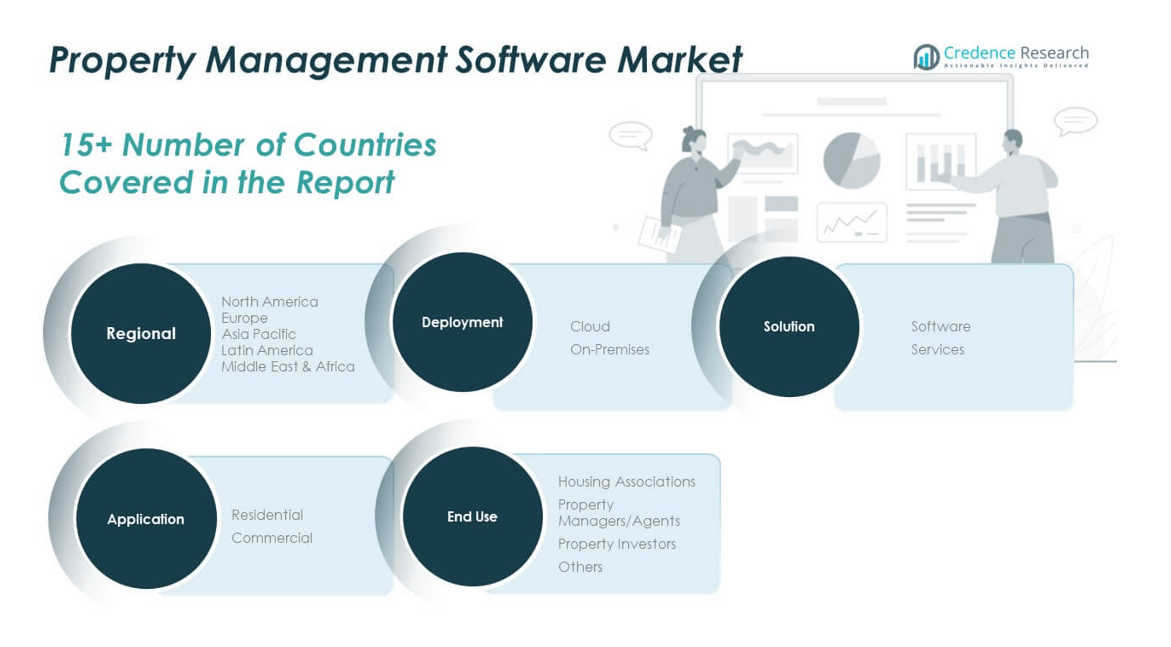
By deployment into cloud and on-premises solutions. Cloud deployment holds a dominant position due to its scalability, lower upfront costs, and remote accessibility, making it highly attractive for property owners with diverse portfolios. On-premises solutions maintain relevance among organizations that prioritize full control, data security, and customization within internal IT environments.
By solution, the market divides into software and services, with software generating the largest revenue share through platforms that streamline lease management, accounting, and tenant engagement, while services provide implementation, support, and integration assistance to maximize efficiency.
- For example, AppFolio deploys dedicated onboarding and customer success teams that guide clients through data migration and training, helping property management firms adopt its platform effectively and maximize long-term utilization.
By application, the market separates into residential and commercial segments. Residential adoption grows rapidly, driven by the demand for digital tenant communication, automated rent collection, and efficient maintenance scheduling in multi-family housing. Commercial applications expand steadily, supported by enterprises managing office spaces, retail facilities, and industrial properties that require sophisticated compliance and financial management tools.
- For example, Buildium delivers a cloud-based, all-in-one platform tailored for community association and property management. It streamlines accounting, resident portals, maintenance workflows, and board communications to support housing associations and small-to-mid-sized management firms efficiently.
By end use, the market covers housing associations, property managers or agents, property investors, and others. Housing associations adopt digital platforms to manage tenant relations and compliance across large housing communities. Property managers and agents leverage software for operational efficiency and tenant retention, while investors rely on data-driven platforms to maximize returns across property portfolios. It also includes other users such as independent landlords and small agencies that increasingly turn to simplified, mobile-enabled solutions to remain competitive in evolving rental markets.
Segmentation:
By Deployment
- Cloud
- On-Premises
By Solution
- Software
- Services
By Application
- Residential
- Commercial
By End Use
- Housing Associations
- Property Managers/Agents
- Property Investors
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Property Management Software Market size was valued at USD 2,166.3 million in 2018 to USD 2,839.4 million in 2024 and is anticipated to reach USD 5,522.6 million by 2032, at a CAGR of 8.8% during the forecast period. North America accounts for 44.8% market share in 2024. The region leads the global market due to advanced digital infrastructure and widespread adoption of SaaS-based platforms. Strong demand from both residential and commercial property managers drives rapid adoption. It benefits from a mature real estate industry with increasing reliance on automation and cloud-based services. Regulatory compliance and integration with financial systems further enhance uptake across housing associations and property management firms. Investment in smart city projects and growing rental housing needs accelerate demand. Established vendors and new entrants compete aggressively, creating a dynamic and innovative ecosystem.
Europe
The Europe Property Management Software Market size was valued at USD 875.7 million in 2018 to USD 1,094.4 million in 2024 and is anticipated to reach USD 1,958.5 million by 2032, at a CAGR of 7.6% during the forecast period. Europe holds 17.3% market share in 2024. Strong adoption in Germany, the UK, and France drives regional growth. It benefits from robust demand for compliance management and digital lease handling in the commercial sector. Residential housing associations increasingly rely on digital solutions to streamline tenant engagement and maintenance. Data security and adherence to GDPR play a critical role in vendor strategies. Growth is steady across southern Europe with rising modernization of property operations. Investments in smart housing projects strengthen adoption. European vendors also compete with global players, creating a balanced and diverse market environment.
Asia Pacific
The Asia Pacific Property Management Software Market size was valued at USD 1,056.4 million in 2018 to USD 1,466.8 million in 2024 and is anticipated to reach USD 3,171.8 million by 2032, at a CAGR of 10.2% during the forecast period. Asia Pacific represents 23.2% market share in 2024. The region experiences the fastest growth globally, driven by urbanization, infrastructure expansion, and rising rental housing demand. It gains momentum from investments in smart cities and digitization of property operations across China, India, and Southeast Asia. Growing middle-class populations demand efficient rental solutions, fueling software adoption. It benefits from rising smartphone penetration and demand for mobile-first property management platforms. Japan and South Korea emphasize advanced technologies including AI and IoT integration. Australia sees strong adoption among property managers handling large residential and commercial portfolios. Vendors increasingly target regional customization to capture local market opportunities.
Latin America
The Latin America Property Management Software Market size was valued at USD 311.7 million in 2018 to USD 408.6 million in 2024 and is anticipated to reach USD 740.2 million by 2032, at a CAGR of 7.8% during the forecast period. Latin America captures 6.4% market share in 2024. Growth is supported by expanding urban populations and rising demand for organized housing management solutions. Brazil leads the region, followed by Argentina and Mexico, where property managers seek cost-effective digital tools. It benefits from increasing adoption of cloud deployment due to reduced infrastructure costs. Financial institutions and housing associations drive steady demand through compliance-focused platforms. Market expansion is gradual, with challenges in affordability and awareness among small property firms. Regional vendors face competition from international providers offering tailored solutions. Adoption strengthens as governments push for modernization in real estate sectors.
Middle East
The Middle East Property Management Software Market size was valued at USD 233.7 million in 2018 to USD 294.2 million in 2024 and is anticipated to reach USD 529.9 million by 2032, at a CAGR of 7.7% during the forecast period. The region holds 4.7% market share in 2024. It shows steady growth fueled by infrastructure development and expanding commercial real estate sectors. GCC countries, particularly the UAE and Saudi Arabia, lead adoption with strong investments in digital property solutions. Housing demand from expatriate populations drives residential adoption. It benefits from government initiatives encouraging smart building and urban modernization. Israel and Turkey display emerging adoption patterns with increasing focus on compliance management. Cloud-based solutions gain preference in regional markets with large-scale commercial properties. Vendors expand through partnerships with local firms to strengthen their presence.
Africa
The Africa Property Management Software Market size was valued at USD 136.2 million in 2018 to USD 223.4 million in 2024 and is anticipated to reach USD 398.0 million by 2032, at a CAGR of 7.3% during the forecast period. Africa accounts for 3.5% market share in 2024. The region is at an early stage of adoption but demonstrates strong potential in urban hubs. South Africa leads with significant uptake in residential and commercial properties. It faces challenges in digital infrastructure and affordability, slowing broader adoption. Egypt and Nigeria emerge as promising markets with rising real estate investments. Cloud-based solutions attract property managers seeking low-cost, scalable platforms. It benefits from growing awareness of tenant engagement and automated rent management. Vendors that offer simplified, mobile-based platforms find opportunities among small landlords and property agents.
Key Player Analysis:
- Yardi Systems
- CoreLogic
- MRI Software
- Buildium
- RealPage, Inc.
- CoStar
- ResMan
- Rentec Direct
- Propertyware
- TenantCloud
- Hemlane
- SimplifyEm
- Cozy (now part of Apartments.com)
- Innago
Competitive Analysis:
The Property Management Software Market is characterized by strong competition among global and regional players offering diverse solutions for residential and commercial properties. Leading companies such as Yardi Systems, MRI Software, RealPage, CoreLogic, and Buildium dominate with comprehensive platforms that integrate accounting, tenant engagement, and compliance tools. It witnesses increasing competition from emerging providers like TenantCloud, Hemlane, and Innago that focus on affordability and mobile-first solutions. Strategic mergers, product launches, and geographic expansions define competitive positioning. Vendors emphasize AI-driven analytics, cloud deployment, and integrated ecosystems to strengthen market presence. Service quality, customization capabilities, and scalability remain key differentiators for enterprises and SMEs.
Recent Developments:
- In August 2025, Deckard Technologies, a leading provider of short-term rental management software, entered a new phase of growth by acquiring AllTheRooms, a Wilmington, DE-based analytics and data group. This acquisition consolidates Deckard Technologies’ position in the short-term rental management and tax compliance sector, expanding its software coverage to new markets in the United States and internationally.
- In May 2025, Yardi Systems launched Yardi Acquisition Manager to automate real estate deal workflows, offering centralized documentation, real-time insights, and fully integrated underwriting that improves investment ROI and accelerates execution.
- In January 2025, Volaris Group, an international technology company, completed the acquisition of agentOS Proptech Group, a provider of property management software solutions based in the UK. The acquisition aims to further support the long-term growth of agentOS in the property management vertical, while leveraging Volaris Group’s technology expertise and global resources.
Market Concentration & Characteristics:
The Property Management Software Market demonstrates moderate concentration with a few global leaders controlling significant revenue shares. It reflects high fragmentation due to the presence of multiple niche providers catering to regional demands. The market shows strong growth potential, fueled by cloud adoption, digital transformation, and smart city investments. Vendors compete on pricing, integration capabilities, and value-added services to attract property managers and housing associations. It exhibits characteristics of rapid technological innovation, recurring revenue from subscription models, and growing demand across residential and commercial applications.
Report Coverage:
The research report offers an in-depth analysis based on Deployment, Solution, Application and End Use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Property Management Software Market will expand through wider adoption of AI-driven predictive analytics for tenant behavior and maintenance planning.
- Cloud-based deployment will strengthen its position as property managers prioritize scalability and remote accessibility.
- Integration with IoT devices will enable smarter building management and energy efficiency monitoring.
- Mobile-first platforms will gain momentum as tenants and landlords demand on-the-go accessibility.
- Vendor strategies will emphasize end-to-end solutions that unify accounting, communication, and compliance in single platforms.
- Rising urbanization and demand for rental housing will accelerate software adoption in both developed and emerging economies.
- Sustainability modules will become integral as property managers align with green building standards and environmental regulations.
- Data security and compliance capabilities will remain a priority amid tightening privacy laws.
- Partnerships with financial and real estate institutions will expand software reach across diverse end users.
- The market will witness stronger growth in emerging regions where smart city initiatives and digital infrastructure investments are rising
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Digital Transformation in Real Estate Operations
Property owners and managers are increasingly adopting digital platforms to streamline rent collection, tenant communication, and maintenance tracking, reducing administrative workload and improving operational efficiency.
Growing Demand for Cloud-Based and Mobile-First Platforms
Cloud deployment offers scalability, lower upfront costs, and remote access, making it attractive for property managers, while mobile-first solutions enhance tenant and landlord engagement through real-time apps and dashboards.
Integration of Emerging Technologies for Predictive Management
The adoption of IoT, AI, and data analytics enables predictive maintenance, smarter resource allocation, and enhanced tenant experience, driving the need for advanced property management software.
Rising Urbanization and Expanding Rental Housing Needs
Rapid urbanization and the growth of rental housing markets, especially in emerging economies, are increasing the need for scalable, automated property management solutions to handle larger and more complex property portfolios.
Emphasis on Data Security and Regulatory Compliance
With increasing concerns over data privacy and evolving regulatory requirements, property management software that offers robust security features and compliance tools is seeing higher adoption among property managers and housing associations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size for property management software?
What are the key drivers of market growth?
Which region is expected to experience the fastest growth?
What challenges does the market face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Housing Associations
- 1.2.2 Property Managers/Agents
- 1.2.3 Property Investors
- 1.2.4 Others
- 1.3 By Solution
- 1.3.1 Software
- 1.3.2 Services
- 1.4 By Deployment
- 1.4.1 Cloud
- 1.4.2 On-Premises
- 1.5 By Application
- 1.5.1 Residential
- 1.5.2 Commercial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,326.7 million → 2032: USD 12,321.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Property Management Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Property Management Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Property Management Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Property Management Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Property Management Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Property Management Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Property Management Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Property Management Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,326.7 million → 2032: USD 12,321.1 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Property Management Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Housing Associations
- 12.3.6.2 Property Managers/Agents
- 12.3.6.3 Property Investors
- 12.3.6.4 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Solution - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Software
- 12.4.6.2 Services
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Cloud
- 12.5.6.2 On-Premises
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Residential
- 12.6.6.2 Commercial
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Property Management Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Property Management Software Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Property Management Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Property Management Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Yardi Systems
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 CoreLogic
- 18.4 MRI Software
- 18.5 Buildium
- 18.6 RealPage, Inc.
- 18.7 CoStar
- 18.8 ResMan
- 18.9 Propertyware
- 18.10 TenantCloud
- 18.11 AppFolio
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

