
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
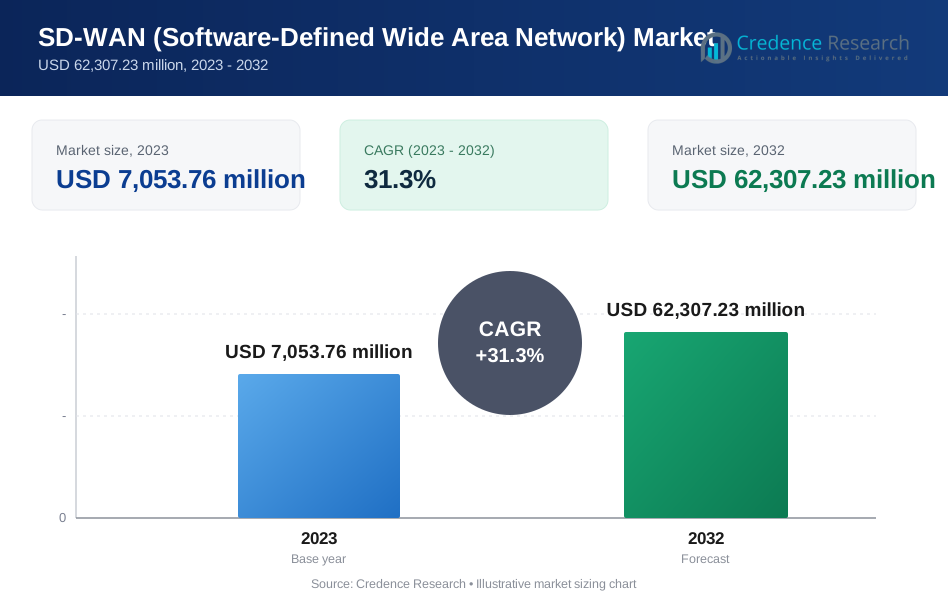
| Software Defined Wide Area Network (SD-WAN) market Size 2023 | USD 7,053.76 million |
| Software Defined Wide Area Network (SD-WAN) market, CAGR | 31.3% |
| Software Defined Wide Area Network (SD-WAN) market Size 2032 | USD 62,307.23 million |
Market Overview
The Software Defined Wide Area Network (SD-WAN) market is projected to grow from USD 7,053.76 million in 2023 to an estimated USD 62,307.23 million by 2032, reflecting a remarkable compound annual growth rate (CAGR) of 31.3% from 2024 to 2032. This exponential growth is driven by the increasing adoption of cloud-based services, the rising demand for enhanced network agility and scalability, and the need for cost-effective solutions in wide area networking.
The growth of the SD-WAN market is fueled by key drivers such as the accelerating digital transformation of businesses, increased reliance on cloud and SaaS applications, and the need for secure, reliable, and high-performing connectivity. Furthermore, trends such as the integration of artificial intelligence (AI) and machine learning (ML) capabilities into SD-WAN for better network automation and analytics, coupled with the adoption of hybrid and multi-cloud strategies, are contributing to the rapid evolution and adoption of SD-WAN solutions.
Geographically, North America holds a significant share of the SD-WAN market, driven by the presence of major technology providers, early adoption of digital innovations, and robust IT infrastructure. Meanwhile, the Asia-Pacific region is anticipated to witness the fastest growth due to rising digitalization, expanding enterprise networks, and government initiatives supporting advanced network solutions. Key players in the SD-WAN market include Cisco Systems, VMware Inc., Silver Peak (acquired by Aruba Networks), Fortinet, and Palo Alto Networks, among others, driving innovation and competition in the market.
Market Drivers
Growing Demand for Cost-Effective Networking Solutions
Enterprises across the globe are under increasing pressure to manage their wide area networks (WAN) with greater cost efficiency while ensuring high performance. Traditional WAN architectures, primarily based on Multiprotocol Label Switching (MPLS), often come with significant overhead costs, including hardware, dedicated network links, and maintenance expenses. SD-WAN addresses these challenges by allowing organizations to leverage more affordable public internet connections alongside private MPLS links, optimizing cost and performance through centralized management and intelligent path selection. With SD-WAN solutions, businesses can achieve lower total cost of ownership (TCO) while maintaining high levels of application performance and reliability, making it an attractive choice for enterprises seeking cost-effective networking solutions. For instance, a global retail company with 500 stores across 20 countries implemented SD-WAN and reduced their WAN costs by millions of dollars annually while improving application performance for their cloud-based inventory management system. This demand continues to drive the SD-WAN market's expansion.
Increased Adoption of Cloud-Based Applications and Services
The rapid shift towards cloud computing and Software-as-a-Service (SaaS) applications has reshaped the way organizations manage their network infrastructure. More businesses are embracing cloud services such as Microsoft 365, Salesforce, and Google Workspace, which require highly reliable and scalable connectivity to ensure seamless user experiences. Traditional WAN architectures often struggle to cope with the performance demands of cloud-based applications due to their reliance on backhauling traffic through data centers, leading to latency and bottlenecks. SD-WAN, on the other hand, offers direct cloud access at branch offices, optimizing traffic routing, reducing latency, and improving application performance. As more companies prioritize cloud-first strategies, the demand for SD-WAN solutions continues to rise, serving as a key market driver.
Need for Enhanced Network Agility and Flexibility
As organizations grow and evolve, they require greater network agility and flexibility to quickly adapt to changing business needs. Traditional WANs often involve complex and time-consuming processes for deployment, configuration, and management. SD-WAN offers centralized network management, enabling IT teams to deploy and configure network services in a matter of hours instead of weeks. This flexibility extends to adding or modifying branch locations, scaling bandwidth, and deploying new applications, making SD-WAN an ideal solution for businesses that need to keep pace with digital transformation and changing user demands. Moreover, SD-WAN solutions can be quickly and easily integrated with existing network infrastructures, minimizing disruptions and ensuring seamless transitions. As another example, a multinational financial services firm deployed SD-WAN across 1000 branch offices, resulting in a significant reduction in network downtime and enabling them to provision new services in days rather than weeks, further driving its adoption across diverse industries.
Growing Focus on Network Security and Cyber Threats
As businesses continue to expand their digital footprints, they are increasingly targeted by sophisticated cyber threats. Traditional WAN architectures often lack the built-in security features needed to address modern security challenges, making enterprises vulnerable to attacks, data breaches, and disruptions. SD-WAN solutions are designed with security in mind, providing integrated security features such as encryption, secure direct internet access, network segmentation, and next-generation firewalls. These security capabilities enable organizations to protect their data and applications more effectively while maintaining optimal network performance. Additionally, SD-WAN solutions are often integrated with Secure Access Service Edge (SASE) frameworks, further enhancing security by combining networking and security functions into a unified cloud-native service. This growing focus on robust network security is driving widespread adoption of SD-WAN, particularly in industries where data protection and compliance are critical.
Market Trends
Integration of SD-WAN with Secure Access Service Edge (SASE) Solutions
A prominent trend in the SD-WAN market is its integration with Secure Access Service Edge (SASE) frameworks, combining networking and security functions into a unified cloud-native service. This evolution addresses the increasing demand for comprehensive network security while maintaining optimal performance across distributed enterprise networks. By integrating SD-WAN with SASE, businesses can benefit from consistent security policies, robust access controls, threat prevention measures, and optimized connectivity for remote and branch users. The adoption of hybrid work models and the surge in remote access requirements due to the COVID-19 pandemic have further accelerated this trend, as organizations seek secure and seamless ways to connect distributed workforces. This convergence of networking and security capabilities in SASE-driven SD-WAN solutions ensures holistic protection, simplified management, and improved user experiences, making it a key market trend shaping future network strategies.
Adoption of AI and Machine Learning for Network Automation and Optimization
Another major trend in the SD-WAN market is the increasing adoption of artificial intelligence (AI) and machine learning (ML) to enhance network automation, performance monitoring, and optimization. AI-driven SD-WAN solutions leverage predictive analytics, real-time data insights, and automated decision-making to optimize network traffic, reduce latency, and improve overall user experiences. By automating complex tasks such as path selection, application prioritization, and fault detection, organizations can significantly reduce manual interventions, lower operational costs, and minimize network downtime. AI and ML capabilities also enable proactive network management, allowing enterprises to anticipate issues before they escalate and swiftly adapt to dynamic network conditions. For instance, a major telecommunications company reported that their AI-powered SD-WAN solution reduced network outages by 35% and improved application performance by 40% for their enterprise customers. Additionally, a global retail chain implemented an AI-driven SD-WAN platform, resulting in a 50% reduction in WAN costs and a 60% decrease in network configuration time across their 1,000+ store locations. This trend reflects a growing demand for intelligent network solutions that deliver faster, more agile, and self-optimizing connectivity for today's data-intensive applications and cloud-centric environments. As a result, vendors are increasingly incorporating AI/ML-driven capabilities into their SD-WAN offerings to provide competitive differentiation and maximize customer value.
Market Restraints and Challenges
Complexity in Integration with Existing Network Infrastructure
One of the primary challenges facing the SD-WAN market is the complexity of integrating SD-WAN solutions with existing network infrastructures, especially for large enterprises with complex, multi-layered networks. While SD-WAN solutions offer centralized control, automation, and flexibility, the process of transitioning from traditional WAN architectures, such as MPLS-based systems, can be challenging. Organizations often face compatibility issues with legacy hardware, network protocols, and security policies during implementation. The integration process may require significant planning, configuration, and re-engineering of existing network architectures, leading to potential disruptions and increased costs. This complexity can deter some enterprises from adopting SD-WAN or prolong deployment timelines, particularly for organizations with limited IT resources or expertise. Ensuring a smooth transition and effective integration of SD-WAN solutions remains a critical challenge for vendors and end-users alike.
Concerns Related to Security and Data Privacy
While SD-WAN solutions often come with built-in security features, enterprises remain cautious about security risks and data privacy concerns, especially in highly regulated industries. The distributed nature of SD-WAN, with direct-to-cloud connectivity and multiple branch locations, can increase the potential attack surface, making it more susceptible to cyber threats such as Distributed Denial-of-Service (DDoS) attacks, unauthorized access, and data breaches. Furthermore, ensuring compliance with stringent industry-specific regulations (e.g., healthcare, finance) can pose significant challenges for organizations deploying SD-WAN solutions. As cyber threats become more sophisticated, maintaining robust security measures, continuous monitoring, and regulatory compliance while leveraging the advantages of SD-WAN remains a major concern. This challenge underscores the need for effective security integrations, user education, and consistent enforcement of security policies to protect data and network integrity.
Market Segmentation Analysis
By Component
The SD-WAN market can be segmented by component into solutions and services. The solutions segment includes software, which dominates due to its ability to provide centralized network management, enhanced security, and optimized data traffic control across distributed networks. This demand is further fueled by the widespread adoption of cloud services that require flexible, reliable connectivity. SD-WAN appliances, comprising hardware devices deployed at branch offices and data centers, complement software by enabling high-performance connectivity and supporting hybrid approaches for transitioning enterprises. On the services side, consulting plays a critical role in developing tailored SD-WAN strategies and ensuring successful adoption, while implementation services handle the deployment, integration, and configuration of solutions within existing infrastructures. Finally, training and support services provide continuous assistance to optimize network operations, address security concerns, and manage updates, ensuring effective use of SD-WAN solutions.
By Deployment Mode
The SD-WAN market offers two primary deployment modes: cloud-based and on-premises. Cloud-based deployment is gaining significant traction as organizations increasingly embrace cloud services and hybrid/multi-cloud strategies due to its agility, scalability, and centralized control, making it well-suited for geographically distributed offices and remote workforces. This mode supports faster deployments, reduced capital expenditure, and on-demand scalability, driving demand for cloud-native solutions. On the other hand, on-premises deployment is favored by organizations that require greater control over their network infrastructure, particularly those in industries with strict data privacy and security regulations. Offering full customization and enhanced data security, on-premises SD-WAN remains a relevant option for enterprises managing complex and sensitive data environments while emphasizing robust control and compliance capabilities.
Segments
Based on Component
- Solution
- Software
- Appliances
- Services
- Consulting
- Implementation
- Training and support
Based on Deployment Mode
- Cloud
- On-premises
Based on Organization Size
- SMEs
- Large Enterprises
Based on End User
- Service Providers
- Verticals
- Banking, Financial Services, and Insurance
- Manufacturing
- Retail
- Healthcare
- Government
- Transport and Logistics
- Energy and Utilities
- Other Verticals
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (35%)
North America holds the largest share of the global SD-WAN market, accounting for approximately 35% of the market in 2023. This dominance is attributed to the region's early adoption of advanced networking solutions and its well-established IT infrastructure. Enterprises across the United States and Canada are increasingly transitioning to SD-WAN solutions to optimize network performance, support hybrid work models, and enhance security across distributed networks. Key drivers include the rapid adoption of cloud-based applications, increasing cybersecurity concerns, and the strong presence of major SD-WAN vendors such as Cisco Systems, VMware, and Fortinet. Government initiatives to promote digital transformation and network modernization further fuel market growth in this region.
Europe (25%)
Europe represents a significant portion of the SD-WAN market, capturing approximately 25% of the market share. The demand for SD-WAN solutions in the region is driven by the increasing adoption of cloud services, the rise of IoT-enabled devices, and the need for robust connectivity and security in hybrid and remote work environments. Countries such as the UK, Germany, France, and the Netherlands are leading in SD-WAN adoption due to a strong focus on digital innovation and the expansion of enterprise networks. Additionally, stringent data privacy regulations, such as the General Data Protection Regulation (GDPR), drive the adoption of secure SD-WAN solutions to ensure compliance.
Key players
- Cisco (US)
- Oracle (US)
- Hewlett Packard Enterprise (US)
- Nokia (Finland)
- VMware (US)
- Huawei (China)
- Juniper Networks (US)
- Fortinet (US)
- Citrix (US)
- Ciena (US)
- Epsilon Telecommunications (Singapore)
- Palo Alto Networks (US)
- Riverbed Technology (US)
- Ericsson (Sweden)
- BT (UK)
- Colt Technology Services (UK)
- NEC Corporation (Japan)
- Tata Communications (India)
- Extreme Networks (US)
- Martello Technologies (Canada)
- Arelion (Sweden)
- Aryaka (US)
- Flexiwan (Israel)
- Cato Networks (Israel)
- Nour Global (UAE)
- Sencinet (Brazil)
- MCM Telecom (Mexico)
- InterNexa (Colombia)
- FatPipe Networks (US)
- Bigleaf Networks (US)
- Lavelle Networks (India)
Competitive Analysis
The SD-WAN market is highly competitive, with major players like Cisco, VMware, and Fortinet dominating through comprehensive solutions and robust market penetration. These companies leverage their extensive portfolios and strong customer bases to drive innovation and market share. Regional players, such as Tata Communications (India) and Epsilon Telecommunications (Singapore), offer localized and tailored solutions, adding competitive diversity. Vendors like Cato Networks and Aryaka provide cloud-native SD-WAN services, emphasizing scalability and security for global enterprises. The competitive landscape is shaped by the need for performance optimization, security integration, and cost reduction, compelling players to focus on partnerships, technological advancements, and customer-centric offerings to gain a competitive edge.
Recent Developments
- In February 2024, Cisco launched AI-enriched networking solutions at Cisco Live 2024, designed to enhance SD-WAN with AI-driven security, observability, and operational insights.
- In February 2024, VMware (now part of Broadcom) announced new developments in its SD-WAN and SASE portfolio at Mobile World Congress 2024. This included the introduction of VMware VeloCloud SASE, secured by Symantec.
- In September 2024, Huawei and CypressTel launched an SD-WAN joint innovation lab at Huawei Connect 2024 to focus on R&D and innovative applications of SD-WAN technologies.
- In June 2024, Juniper Networks unveiled new AI-powered enhancements for its SD-WAN solutions, including Marvis Minis, which improves network operations by diagnosing issues and running proactive speed tests.
- In September 2023, BT launched its Agile Connect SD-WAN service to help large organizations drive digital transformation with enhanced control over traffic flows and reduced network complexity.
- In December 2023, Tata Communications partnered with Jaguar Land Rover (JLR) to deploy a cloud-first SD-WAN solution connecting JLR’s global sites, supporting Industry 4.0 standards and AI-powered automation.
- In April 2024, Extreme Networks introduced ExtremeCloud SD-WAN as part of its unified cloud-managed environment after integrating technology from its acquisition of Ipanema in 2021.
- In January 2024, Aryaka launched new managed SD-WAN offerings including SmartConnect EZ, which leverages a new L3 private core for cost-effective deployments.
Market Concentration and Characteristics
The Software Defined Wide Area Network (SD-WAN) market exhibits a moderate-to-high level of market concentration, with several key players, such as Cisco, VMware, Fortinet, and Palo Alto Networks, holding a significant share due to their comprehensive solution portfolios, established customer bases, and global reach. The market is characterized by intense competition, innovation-driven offerings, and a focus on scalability, security, and cost efficiency. Smaller and regional players contribute to market diversity by offering specialized or localized solutions, often targeting niche markets or providing cloud-native, agile offerings tailored to specific customer needs. The market’s growth is fueled by rapid digital transformation, cloud adoption, and a strong emphasis on network security, which drives differentiation and strategic partnerships among market participants.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment Mode, Organization Size, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The SD-WAN market will continue its rapid expansion, driven by the rising demand for flexible, cost-effective networking solutions that optimize performance across distributed enterprises.
- Organizations will increasingly deploy SD-WAN solutions to enhance connectivity and performance for their cloud-based applications and services, supporting hybrid and multi-cloud strategies.
- SD-WAN solutions will further integrate advanced security features, including Secure Access Service Edge (SASE) frameworks, to address evolving cybersecurity threats and regulatory compliance requirements.
- Artificial intelligence and machine learning capabilities will become more prevalent, enhancing network automation, real-time traffic optimization, and predictive analytics for self-optimizing networks.
- The continued growth of hybrid and remote work will drive organizations to adopt SD-WAN to provide reliable, secure, and efficient connectivity for geographically dispersed workforces.
- SD-WAN will increasingly be integrated with edge computing to support low-latency applications and improve data processing efficiency, particularly in IoT-driven and real-time applications.
- The Asia-Pacific, Latin America, and Middle East & Africa regions will experience significant growth due to rising digital transformation initiatives and increasing internet penetration.
- Vendors will offer tailored SD-WAN solutions to meet the unique requirements of industries such as healthcare, finance, and retail, enhancing market competitiveness.
- The SD-WAN market will see a shift toward flexible, subscription-based pricing models, enabling businesses to adopt scalable solutions with reduced capital expenditure.
- Strategic partnerships among SD-WAN vendors, cloud service providers, and security firms will shape the market, offering end-to-end solutions that meet diverse enterprise networking needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand for Cost-Effective Networking Solutions
Enterprises are seeking to reduce the high costs associated with traditional WAN architectures by adopting SD-WAN, which enables the use of affordable public internet connections alongside private links, optimizing both cost and performance through centralized management.
Increased Adoption of Cloud-Based Applications and Services
The shift to cloud computing and SaaS applications requires reliable, scalable, and direct connectivity, which SD-WAN provides by optimizing traffic routing and reducing latency, thus supporting seamless cloud access for distributed enterprises.
Need for Enhanced Network Agility and Flexibility
SD-WAN enables rapid deployment, centralized management, and easy scaling of network resources, allowing organizations to quickly adapt to changing business needs, add new locations, and support digital transformation initiatives.
Growing Focus on Network Security and Cyber Threats
With the rise in cyber threats and regulatory requirements, SD-WAN solutions are increasingly adopted for their integrated security features, such as encryption, segmentation, and next-generation firewalls, often combined with SASE frameworks for comprehensive protection.
Integration of AI and Machine Learning for Network Optimization
Vendors are embedding AI and ML capabilities into SD-WAN solutions to automate network management, optimize traffic in real time, and proactively address issues, reducing downtime and operational costs while improving application performance.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the SD-WAN market in 2023 and 2032, and what is the expected CAGR?
What are the key drivers fueling the growth of the SD-WAN market?
Why is North America a major region for the SD-WAN market?
What role does AI and ML play in the SD-WAN market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Service Providers
- 1.2.2 Banking, Financial Services, and Insurance
- 1.2.3 Manufacturing
- 1.2.4 Retail
- 1.2.5 Healthcare
- 1.2.6 Government
- 1.2.7 Transport and Logistics
- 1.2.8 Energy and Utilities
- 1.2.9 Other Verticals
- 1.3 By Component
- 1.3.1 Solution (Software)
- 1.3.2 Solution (Appliances)
- 1.3.3 Services (Consulting)
- 1.3.4 Services (Implementation)
- 1.3.5 Services (Training and Support)
- 1.4 By Deployment Mode
- 1.4.1 Cloud
- 1.4.2 On-premises
- 1.5 By Organization Size
- 1.5.1 SMEs
- 1.5.2 Large Enterprises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 7,053.76 million → 2032: USD 62,307.23 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global SD-WAN (Software-Defined Wide Area Network) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global SD-WAN (Software-Defined Wide Area Network) Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global SD-WAN (Software-Defined Wide Area Network) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global SD-WAN (Software-Defined Wide Area Network) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global SD-WAN (Software-Defined Wide Area Network) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global SD-WAN (Software-Defined Wide Area Network) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global SD-WAN (Software-Defined Wide Area Network) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global SD-WAN (Software-Defined Wide Area Network) Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 7,053.76 million → 2032: USD 62,307.23 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global SD-WAN (Software-Defined Wide Area Network) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Base-Year Market Share, 2023
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Service Providers
- 12.3.6.2 Banking, Financial Services, and Insurance
- 12.3.6.3 Manufacturing
- 12.3.6.4 Retail
- 12.3.6.5 Healthcare
- 12.3.6.6 Government
- 12.3.6.7 Transport and Logistics
- 12.3.6.8 Energy and Utilities
- 12.3.6.9 Other Verticals
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Base-Year Market Share, 2023
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Solution (Software)
- 12.4.6.2 Solution (Appliances)
- 12.4.6.3 Services (Consulting)
- 12.4.6.4 Services (Implementation)
- 12.4.6.5 Services (Training and Support)
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment Mode - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Base-Year Market Share, 2023
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Cloud
- 12.5.6.2 On-premises
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Organization Size - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Base-Year Market Share, 2023
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 SMEs
- 12.6.6.2 Large Enterprises
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global SD-WAN (Software-Defined Wide Area Network) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global SD-WAN (Software-Defined Wide Area Network) Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global SD-WAN (Software-Defined Wide Area Network) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global SD-WAN (Software-Defined Wide Area Network) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Cisco Systems
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 VMware (Broadcom)
- 18.4 Fortinet
- 18.5 Palo Alto Networks
- 18.6 Juniper Networks
- 18.7 Huawei
- 18.8 Aryaka
- 18.9 Tata Communications
- 18.10 BT
- 18.11 Cato Networks
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

