
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Network Outsourcing Market Size 2023 | USD 20505 million |
| Network Outsourcing Market , CAGR | 9.4% |
| Network Outsourcing Marke Size 2032 | USD 42072.5 million |
Market Overview:
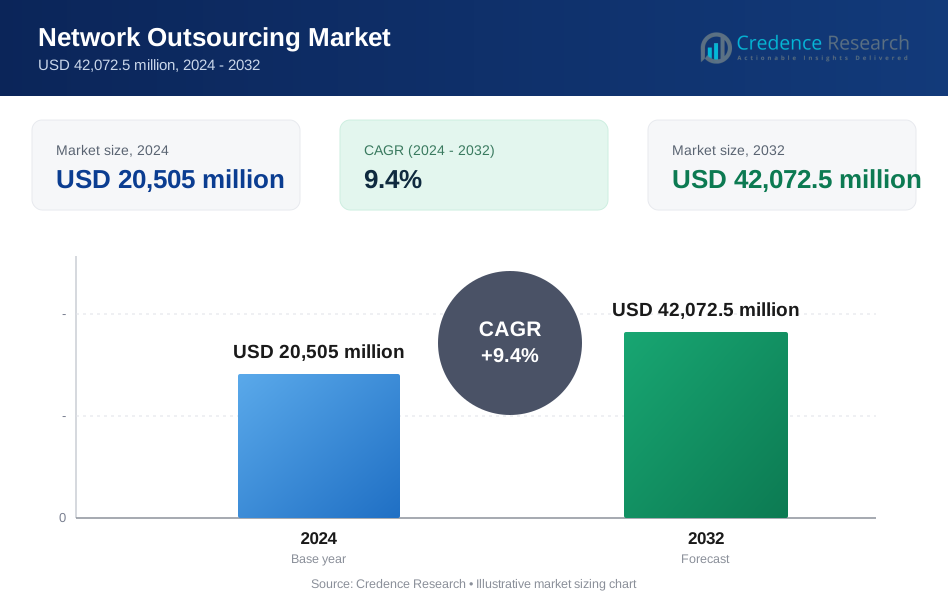
The Network Outsourcing Market is projected to grow from USD 20505 million in 2024 to an estimated USD 42072.5 million by 2032, with a compound annual growth rate (CAGR) of 9.4% from 2024 to 2032.
The Network Outsourcing Market Key drivers include the rising complexity of enterprise networks, increasing adoption of new network architectures such as SD-WAN, and the demand for cost-effective network management. Many enterprises seek to manage network infrastructure and security through outsourcing, allowing them to reduce costs and ensure reliable, up-to-date solutions with reduced internal resource requirements. Additionally, the shortage of skilled IT professionals and the growing need for efficient network management amid increasing cyber threats are driving businesses to partner with network outsourcing providers. The integration of artificial intelligence (AI) and machine learning (ML) into network management solutions further enhances the appeal of outsourcing, enabling providers to offer predictive maintenance and advanced monitoring capabilities.
Regionally, North America leads the Network Outsourcing Market due to the region's large presence of technology companies, high investment in IT infrastructure, and strong demand for managed services. Europe follows closely, driven by high adoption rates of cloud technologies and outsourcing in industries such as telecommunications and finance. In Asia-Pacific, rapid digital transformation in countries like China, India, and Japan has created new growth opportunities, with small and medium-sized enterprises increasingly looking toward network outsourcing to maintain competitive edge. The Middle East and Africa are also witnessing steady growth due to rising investments in telecom infrastructure, especially within smart cities initiatives, signaling potential for increased market expansion.
Market Drivers:
Rising Complexity of Network Infrastructure and Demand for Cost Optimization:
The growing complexity of network infrastructure across enterprises is a major factor driving the demand for network outsourcing services. As businesses expand and adopt more advanced technologies, their network structures become more intricate and challenging to manage. Outsourcing allows organizations to streamline these complex networks while ensuring cost efficiency, as providers handle maintenance, upgrades, and troubleshooting. For instance, Deloitte's Global Outsourcing Survey highlights that organizations can achieve significant cost savings and operational efficiencies through outsourcing. Network outsourcing reduces the need for in-house IT teams to focus on day-to-day network operations, freeing them to concentrate on core functions that drive business growth. Furthermore, outsourcing helps companies reduce capital expenditure and optimize operational costs, creating a strong case for adopting outsourced network management solutions.
Shortage of Skilled IT Professionals and the Need for Specialized Expertise:
The shortage of skilled IT professionals has become an increasingly prominent issue in the digital era, and the network outsourcing market benefits from this trend. Many companies face difficulties finding and retaining qualified professionals to manage their complex networks. Outsourcing providers bridge this talent gap by offering specialized expertise in network management, cybersecurity, and cloud integration. Outsourcing also allows businesses to access a vast pool of knowledge and expertise, ensuring that they remain up-to-date with the latest industry trends and technological advancements. The need for specialized skills in rapidly evolving fields such as software-defined networking (SDN), artificial intelligence (AI), and machine learning (ML) further emphasizes the value of outsourcing for network management.
Increasing Adoption of Advanced Network Architectures and Digital Transformation:
The growing adoption of advanced network architectures, such as Software-Defined Wide Area Networking (SD-WAN), is significantly driving the network outsourcing market. As businesses move toward digital transformation, they require robust, scalable network infrastructures to support cloud-based applications, big data, and Internet of Things (IoT) connectivity. SD-WAN and other modern network architectures demand advanced technical skills for configuration, monitoring, and optimization. By outsourcing, companies can leverage the expertise of service providers who are skilled in deploying and managing these advanced architectures. This trend is particularly strong in sectors undergoing rapid digital transformation, including healthcare, finance, and retail, where reliable and efficient networks are critical for operational success.
Rising Cybersecurity Threats and the Shift Towards Managed Security Services:
With cyber threats becoming increasingly sophisticated, businesses are prioritizing network security as part of their outsourcing strategies. Network outsourcing providers offer managed security services, enabling companies to protect their infrastructure and data through advanced security measures like real-time threat monitoring, vulnerability assessments, and incident response management. Outsourced providers are often more equipped to handle cybersecurity challenges with dedicated resources and industry-specific knowledge, which is particularly advantageous for small and medium-sized enterprises that may lack the resources for a full in-house security team. As organizations recognize the importance of safeguarding against cyber threats, the demand for secure and reliable outsourced network solutions is rising, propelling growth in the network outsourcing market.
Market Trends:
Growing Demand for Cloud-Based Network Solutions:
The increasing adoption of cloud computing across industries has greatly influenced the network outsourcing market. Organizations are moving toward cloud-based network solutions to support remote workforces, enhance flexibility, and achieve cost-effective scalability. Cloud-based network outsourcing services allow businesses to manage and optimize their networks through virtualized platforms, reducing the need for extensive physical infrastructure. As cloud solutions become more advanced, providers are offering tailored services to support hybrid and multi-cloud environments, a trend that is set to accelerate further as enterprises seek seamless connectivity and simplified network management in their digital transformation journeys.
Integration of Artificial Intelligence and Machine Learning in Network Management:
Artificial Intelligence (AI) and Machine Learning (ML) are increasingly being integrated into network management solutions to enhance efficiency and predictive capabilities. These technologies enable network outsourcing providers to offer advanced features such as anomaly detection, predictive maintenance, and self-healing networks. With AI and ML, network performance can be continuously monitored, and potential issues can be identified and resolved before they impact operations. This proactive approach to network management minimizes downtime, optimizes resource allocation, and enhances user experience. As companies recognize the benefits of AI-driven network solutions, the adoption of AI and ML in network outsourcing is expected to grow, reflecting a major trend in the market.
Shift Towards Software-Defined Networking (SDN) and Network Function Virtualization (NFV):
Another significant trend in the network outsourcing market is the adoption of Software-Defined Networking (SDN) and Network Function Virtualization (NFV). SDN and NFV technologies allow for more agile and flexible network architectures by decoupling network management from physical devices. This shift is particularly advantageous for enterprises looking to scale their network capabilities quickly in response to business demands. For instance, Cisco reports that SDN has seen wide adoption across data centers (64%), WANs (58%), and access networks (40%). By leveraging SDN and NFV through outsourcing, companies can gain enhanced control over their network infrastructure while reducing dependency on expensive hardware. This trend supports the rising demand for dynamic, customizable network solutions, especially in industries that require high-speed connectivity and low latency, such as telecommunications and media.
Emphasis on Cybersecurity and Compliance:
As cyber threats grow more sophisticated, network outsourcing providers are increasingly prioritizing cybersecurity and compliance as integral parts of their services. Outsourcing partners are now offering comprehensive managed security services that include continuous monitoring, threat detection, and rapid response to security incidents. Additionally, they are integrating regulatory compliance features to support industries such as finance, healthcare, and government, which operate under strict data protection laws. For example, Deloitte's Global Outsourcing Survey indicates that cybersecurity and data analytics are top outsourcing priorities for many organizations. The focus on cybersecurity and compliance is driven by the necessity for businesses to protect sensitive data and mitigate cyber risks. This trend is expected to continue, as organizations seek to fortify their networks against security breaches and ensure compliance with evolving regulatory standards, further fueling growth in the network outsourcing market.
Market Restraints and Challenges:
Data Security and Privacy Concerns:
Data security and privacy remain significant challenges in the network outsourcing market. By outsourcing network management, companies often grant third-party providers access to sensitive data and critical infrastructure. This access heightens the risk of data breaches, unauthorized access, and potential misuse of information. Even with strict security protocols, companies may struggle to maintain full control over data security when relying on external vendors. Concerns around compliance with data protection regulations, particularly in highly regulated industries such as healthcare and finance, also pose barriers to wider adoption of outsourcing.
Loss of Control Over Network Operations:
Another key challenge is the perceived loss of control over network operations. When network management is outsourced, companies may feel they lack real-time insights and direct influence over their network’s functionality and responsiveness. This detachment can be concerning, particularly in situations where network performance directly impacts customer experience or operational efficiency. Companies that prioritize real-time monitoring and hands-on management often hesitate to adopt full network outsourcing, fearing that it may delay troubleshooting or reduce customization in network configurations.
Dependence on Third-Party Expertise and Reliability:
Network outsourcing creates a dependency on third-party providers, which can be a risk if the provider fails to deliver expected levels of service. Issues such as service outages, provider insolvency, or inadequate technical support can severely impact a company’s operations, potentially leading to financial losses and reputational damage. Furthermore, as technology evolves rapidly, organizations must ensure that their providers keep pace with the latest advancements. For instance, Deloitte's report on outsourcing trends emphasizes the importance of managing third-party risks, as businesses increasingly depend on external providers for mission-critical services. Without this alignment, businesses may find their outsourced solutions lagging behind in terms of innovation and competitiveness.
High Initial Costs and Complexity of Transition:
While network outsourcing can reduce operational costs in the long term, the initial transition often involves high setup costs and complexity. Transitioning from an in-house network to an outsourced model requires detailed planning, restructuring of existing processes, and often a temporary increase in workload and expenses. These factors may deter organizations, particularly small and medium-sized enterprises, from pursuing network outsourcing despite its potential benefits.
Market Segmentation Analysis:
By service types, managed services dominate, offering organizations comprehensive network management and maintenance solutions. Professional services are also crucial, as they provide consulting, assessment, and implementation support, while cloud services are rising rapidly due to increased demand for cloud-based solutions that enhance scalability and flexibility.
By deployment type, on-premises solutions remain popular among companies with stringent data control needs, such as those in regulated industries. However, cloud-based deployment is gaining traction, particularly with the rise of remote work and digital transformation initiatives, allowing companies to access network services from virtually anywhere with optimized costs.
By industry verticals, the telecommunications sector leads the market due to its reliance on robust network infrastructure. The banking and financial services sector also demonstrates significant demand due to its requirements for secure, compliant network management. Healthcare, retail, and manufacturing industries are increasingly turning to network outsourcing to support growing IT infrastructure needs and ensure reliable connectivity and data security.
By processes, including network monitoring, data management, security management, and help desk support. Security management is particularly critical due to rising cybersecurity threats, while network monitoring and help desk support are essential for maintaining network uptime and addressing issues proactively.
By customer size, large enterprises lead adoption, although small and medium enterprises increasingly leverage outsourcing for cost-effective access to advanced network services, reflecting a strong growth trend across all segments.
Segmentation:
By Service
- Managed Services
- Professional Services
- Cloud Services
By Deployment Type
- On-Premises
- Cloud-Based
By Industry Verticals
- Telecommunications
- Banking and Financial Services
- Healthcare
- Retail
- Manufacturing
By Processes
- Network Monitoring
- Data Management
- Security Management
- Help Desk Support
By Customer Size
- Small Enterprises
- Medium Enterprises
- Large Enterprises Source
By Regional
- North America U.S. Canada Mexico Europe Germany France U.K. Italy Spain Rest of Europe Asia Pacific China Japan India South Korea South-east Asia Rest of Asia Pacific Latin America Brazil Argentina Rest of Latin America Middle East & Africa GCC Countries South Africa Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share in the global network outsourcing market, accounting for approximately 35% of the market in 2023. This dominance is driven by the high concentration of technology companies, strong IT infrastructure, and significant investment in network security and management solutions. The United States leads the region, with major sectors like telecommunications, finance, and healthcare heavily adopting network outsourcing to reduce operational costs and improve network efficiency. The shift toward cloud-based services and the integration of advanced technologies like AI and machine learning further bolster North America’s market position. Additionally, the region’s proactive approach to cybersecurity, supported by stringent regulations, increases demand for managed security services, which is a vital component of network outsourcing.
Europe
Europe follows North America, with a market share of around 25%. The region shows strong growth in network outsourcing, particularly in the United Kingdom, Germany, and France, as businesses increasingly focus on digital transformation. The European Union’s General Data Protection Regulation (GDPR) and other data protection standards drive companies to outsource network management to ensure compliance. In addition, industries such as finance, healthcare, and retail are relying on outsourcing for improved data management and cybersecurity, especially in light of the increasing regulatory pressure. The European market benefits from the presence of numerous local and international service providers, making network outsourcing services more accessible and competitive.
Asia-Pacific
The Asia-Pacific region represents about 20% of the global market and is projected to be the fastest-growing region in the network outsourcing market. Countries like China, India, and Japan are experiencing rapid growth in digital transformation, cloud adoption, and network outsourcing. The region’s robust manufacturing and retail sectors are increasingly adopting network outsourcing to support their expanding IT needs and improve operational efficiency. Additionally, the rise of small and medium-sized enterprises (SMEs) in this region, along with favorable government policies promoting digitalization, is contributing to the growing demand for outsourced network services. The increasing need for affordable yet reliable network management solutions makes the Asia-Pacific region a key growth market for outsourcing providers.
Latin America
Latin America accounts for about 10% of the market, with steady growth driven primarily by Brazil, Mexico, and Argentina. Companies in Latin America are gradually adopting network outsourcing to optimize costs and enhance network management capabilities. The region is increasingly investing in IT infrastructure to support the adoption of cloud and managed services, although economic constraints and limited technological infrastructure in some areas may limit faster growth. However, as digital transformation initiatives expand, particularly within industries such as telecommunications and finance, the demand for network outsourcing in Latin America is expected to rise.
Middle East and Africa
The Middle East and Africa collectively hold around 10% of the network outsourcing market. The growth in this region is largely fueled by the development of smart city projects and increased investments in telecommunications infrastructure, especially in the United Arab Emirates and Saudi Arabia. As organizations in these regions work to improve network resilience and scalability, network outsourcing presents an attractive solution. While the market here is relatively nascent, the increasing focus on digital transformation and improved cybersecurity measures is anticipated to support gradual market expansion in the coming years.
Key Player Analysis:
- Accenture PLC
- Amadeus IT Group
- Andela Inc
- ATOS SE
- Capgemini SE
- Cognizant Technology Solutions Corporation
- DXC Technologies
- HCL Technologies Ltd
- IBM Corporation
- Infosys Limited
- Pointwest Technologies
- Specialist Computer Centres (SCC)
- Tata Consultancy Services
- Wipro Limited
- WNS Global Services
Competitive Analysis:
The Network Outsourcing Market is highly competitive, with several global and regional players vying for market share. Leading companies, such as IBM, Cisco, Ericsson, and Accenture, dominate through comprehensive service offerings and extensive global reach. These players leverage their technological expertise and established brand presence to secure major contracts with enterprises across diverse industries, from telecommunications to finance and healthcare. Additionally, they focus on integrating advanced technologies like AI, machine learning, and cybersecurity to enhance their network management services. Regional players and specialized providers offer strong competition by delivering tailored solutions and competitive pricing, particularly for small and medium-sized enterprises. Companies like Huawei and Tata Communications play a significant role in the Asia-Pacific market, addressing local demand for flexible, scalable network solutions. The intense competition in this market drives constant innovation, encouraging providers to enhance their service quality, security features, and customization to meet evolving client needs.
Market Concentration & Characteristics:
The Network Outsourcing Market is moderately concentrated, with a mix of large multinational corporations and regional players competing for market share. Prominent players like IBM, Cisco, Ericsson, and Accenture dominate the market due to their extensive service portfolios, technological expertise, and global presence. These companies hold a significant share, catering to large enterprises with complex network requirements and a focus on advanced technologies like AI and cybersecurity. Despite this concentration among top providers, the market also includes numerous regional players and niche providers, which offer specialized and cost-effective solutions tailored to small and medium-sized enterprises. This dynamic creates a competitive landscape where both scalability and specialization are valued. Market characteristics include high demand for managed services, growing adoption of cloud-based solutions, and a strong emphasis on data security. The combination of large players and specialized firms fosters a balance of innovation and customization across the industry.
Report Coverage:
The research report offers an in-depth analysis based on By Service, By Deployment Type, By Industry Verticals, By Processes and By Customer Size. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increased adoption of AI-driven solutions will enable predictive maintenance and automated network management.
- Expansion of 5G networks will drive demand for outsourced solutions to handle complex network requirements.
- Cloud-based network outsourcing will grow as remote work and hybrid environments remain prevalent.
- Enhanced cybersecurity measures will be crucial as cyber threats become more sophisticated.
- Small and medium enterprises will increasingly seek outsourcing for cost-effective network management.
- Advancements in SDN and NFV will push companies toward flexible, scalable outsourced network solutions.
- Growing digital transformation initiatives across industries will continue to fuel market demand.
- Providers will integrate multi-cloud management services to support diverse cloud ecosystems.
- Rising regulatory compliance needs will encourage outsourcing to ensure data protection and privacy.
- Emerging markets, especially in Asia-Pacific and Latin America, will experience accelerated adoption of network outsourcing solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Complexity of Network Infrastructure
As enterprise networks become more intricate with the adoption of advanced technologies and digital transformation, organizations increasingly turn to outsourcing providers to manage, maintain, and optimize these complex environments efficiently.
Shortage of Skilled IT Professionals
The global deficit of qualified IT and network management professionals drives companies to outsource network operations, enabling access to specialized expertise and up-to-date technical skills that are difficult to maintain in-house.
Adoption of Advanced Network Architectures
The shift toward SD-WAN, SDN, and other modern network architectures requires advanced technical capabilities, prompting businesses to leverage outsourcing partners for deployment, monitoring, and optimization of these solutions.
Escalating Cybersecurity Threats
With cyber threats growing in sophistication, organizations are outsourcing network security management to providers with dedicated resources and expertise, ensuring robust protection and compliance with regulatory standards.
Cost Optimization and Operational Efficiency
Outsourcing network management allows enterprises to reduce capital and operational expenditures, streamline processes, and focus internal resources on core business activities, making it an attractive strategy for cost-conscious organizations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Network Outsourcing Market?
What are the main drivers of this market's growth?
Which region leads the Network Outsourcing Market?
What are common challenges in the Network Outsourcing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service
- 1.2.1 Managed Services
- 1.2.2 Professional Services
- 1.2.3 Cloud Services
- 1.3 By Customer Size
- 1.3.1 Small Enterprises
- 1.3.2 Medium Enterprises
- 1.3.3 Large Enterprises
- 1.4 By Deployment Type
- 1.4.1 On-Premises
- 1.4.2 Cloud-Based
- 1.5 By Industry Verticals
- 1.5.1 Telecommunications
- 1.5.2 Banking and Financial Services
- 1.5.3 Healthcare
- 1.5.4 Retail
- 1.5.5 Manufacturing
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 20,505 million → 2032: USD 42,072.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Network Outsourcing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Network Outsourcing Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Network Outsourcing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Network Outsourcing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Network Outsourcing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Network Outsourcing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Network Outsourcing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Network Outsourcing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 20,505 million → 2032: USD 42,072.5 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Network Outsourcing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Managed Services
- 12.3.6.2 Professional Services
- 12.3.6.3 Cloud Services
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Customer Size - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Small Enterprises
- 12.4.6.2 Medium Enterprises
- 12.4.6.3 Large Enterprises
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 On-Premises
- 12.5.6.2 Cloud-Based
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Industry Verticals - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Telecommunications
- 12.6.6.2 Banking and Financial Services
- 12.6.6.3 Healthcare
- 12.6.6.4 Retail
- 12.6.6.5 Manufacturing
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Network Outsourcing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Network Outsourcing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Network Outsourcing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Network Outsourcing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 IBM Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Accenture PLC
- 18.4 Capgemini SE
- 18.5 Cognizant Technology Solutions Corporation
- 18.6 HCL Technologies Ltd
- 18.7 Tata Consultancy Services
- 18.8 Wipro Limited
- 18.9 DXC Technology
- 18.10 Infosys Limited
- 18.11 ATOS SE
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

