
Market Overview:
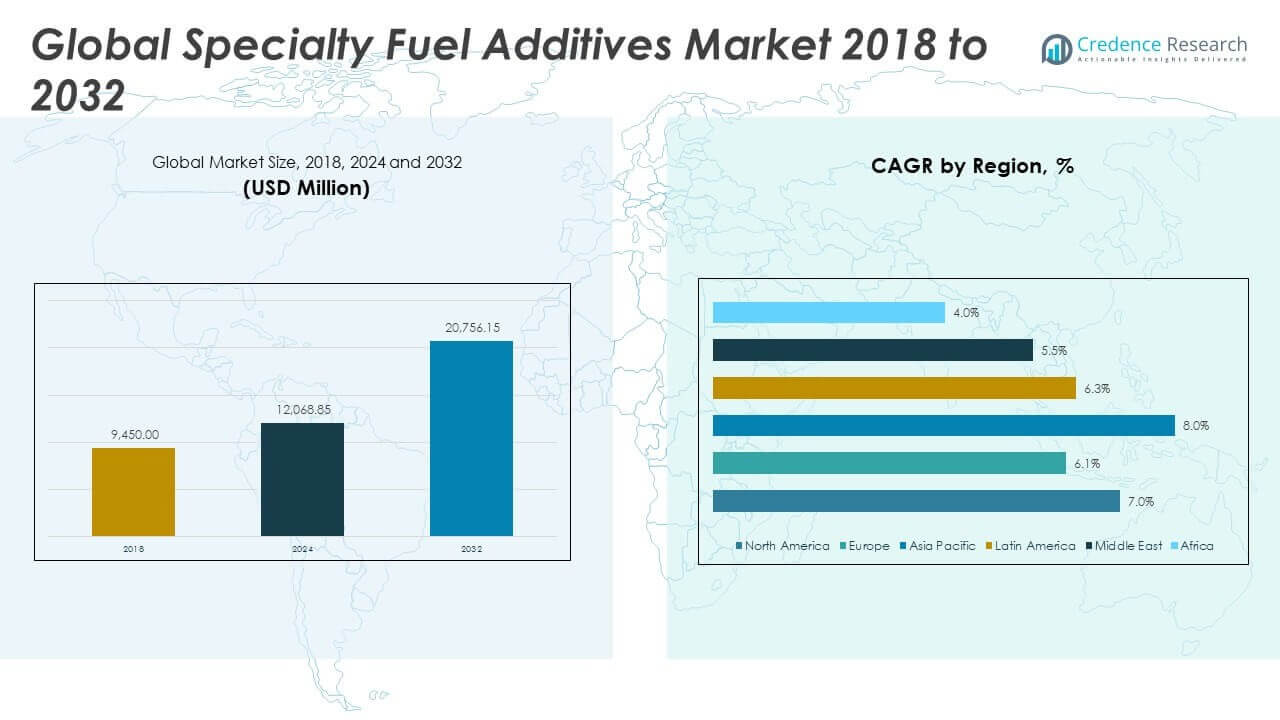
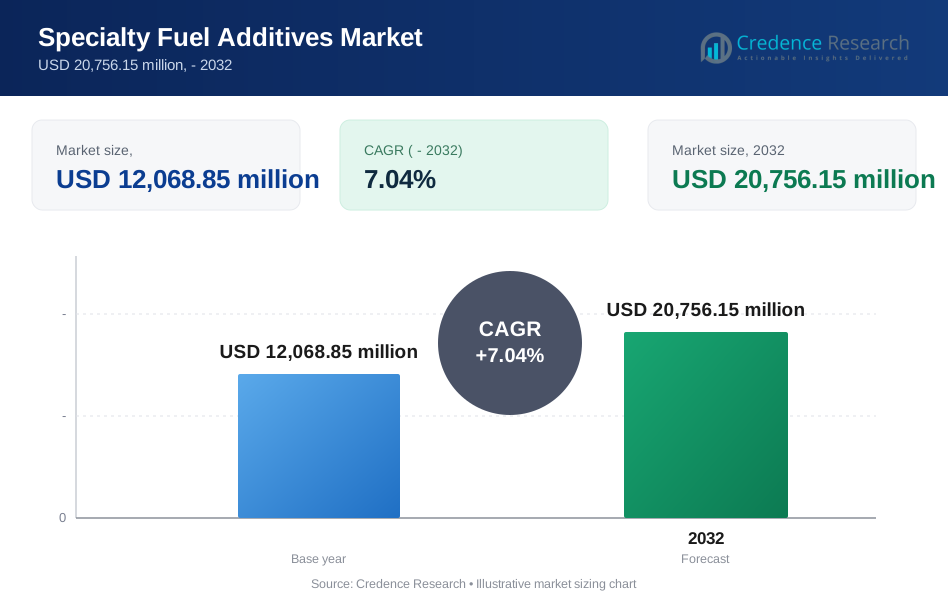
The Global Specialty Fuel Additives Market size was valued at USD 9,450.00 million in 2018 to USD 12,068.85 million in 2024 and is anticipated to reach USD 20,756.15 million by 2032, at a CAGR of 7.04% during the forecast period.| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Specialty Fuel Additives Market Size 2024 | USD 12,068.85 Million |
| Specialty Fuel Additives Market, CAGR | 7.04% |
| Specialty Fuel Additives Market Size 2032 | USD 20,756.15 Million |
Market Insights:
- The Global Specialty Fuel Additives Market size was valued at USD 9,450.00 million in 2018, reached USD 12,068.85 million in 2024, and is anticipated to reach USD
- 20,756.15 million by 2032, at a CAGR of 7.04%.
- Stricter emission regulations such as Euro VI and U.S. EPA Tier 3 are key drivers, prompting demand for additives that reduce particulate matter and nitrogen oxide emissions across major fuel markets.
- Widespread adoption of ultra-low sulfur diesel (ULSD), which lacks natural lubricity, is increasing the use of additives like lubricity improvers, stabilizers, and corrosion inhibitors to protect engine components and maintain performance.
- Rising fuel prices and aging vehicle fleets are encouraging the use of additives that improve fuel economy, clean injectors, enhance ignition quality, and reduce carbon deposits in both on-road and off-road vehicles.
- The market is witnessing growth in bio-based and environmentally friendly additive formulations as manufacturers align with global sustainability goals and respond to green fuel policies.
- Asia-Pacific leads the Global Specialty Fuel Additives Market, driven by rapid industrialization and rising automotive output in China, India, and Southeast Asia, followed by North America and Europe with strong demand from the U.S., Germany, UK, and France.
- The industry faces pressure from volatile raw material prices, logistics disruptions, and regulatory inconsistencies across regions, which slow innovation and increase operational costs, especially for new market entrants.
Market Drivers:
Stringent Emissions Regulations Are Forcing Compliance through Advanced Fuel Additive Technologies: Tightening global emissions standards are one of the most significant growth drivers for the Global Specialty Fuel Additives Market. Governments in North America, Europe, and parts of Asia are enforcing regulations that limit particulate matter, nitrogen oxides, and unburned hydrocarbons from internal combustion engines. Fuel suppliers must integrate additives that enable compliance with Euro VI, EPA Tier 3, and equivalent regional norms. These additives enhance combustion efficiency, reduce soot formation, and lower greenhouse gas emissions. It is critical for refiners and fuel distributors to adopt customized additive packages to meet regulatory benchmarks without compromising engine performance. These legislative measures continue to create a favorable environment for innovation and investment in emission-control additives.- For instance, BASF’s Keropur® fuel additive technology has been adopted by several European fuel suppliers to meet Euro VI emission standards, with documented reductions of up to 20 mg/km in particulate matter and significant decreases in nitrogen oxide emissions in certified engine tests during 2023.
- Innospec has developed multi-functional lubricity improvers, such as the Octamar LI-5 and OLI-9000 series, specifically for ultra-low sulfur diesel (ULSD). These additives restore lubricity lost during sulfur removal processes, preventing excessive wear of fuel pumps and injectors.
Market Trends:
Growing Shift Toward Bio-Based and Renewable Additive Formulations Is Shaping Product Portfolios: The increasing focus on sustainability is pushing manufacturers to develop bio-based and renewable specialty fuel additives. Traditional petroleum-derived additives face scrutiny due to their environmental impact, prompting a shift toward plant-based or biodegradable alternatives. The Global Specialty Fuel Additives Market is seeing an uptick in investment in eco-friendly formulations, especially for use in markets with strong green mandates. It supports carbon reduction goals and aligns with global decarbonization policies. Fuel producers and additive suppliers are prioritizing raw materials with lower environmental footprints while maintaining performance standards. This trend is encouraging innovation across supply chains, from raw material sourcing to end-product development.- For instance, Clariant launched its Vita 100% bio-based surfactant and fuel additive range in 2024. These products are made from renewable feedstocks with at least a 98% Renewable Carbon Index and can help save up to 85% of CO₂ emissions per ton compared to fossil-based alternatives.
- For instance, Dorf Ketal commissioned over 200 automated additive dosing systems in refineries and fuel terminals worldwide in 2024, each capable of real-time adjustment with a dosing accuracy of ±0.1%, ensuring compliance with fuel quality and regulatory standards.
Market Challenges Analysis:
Volatility in Raw Material Prices and Supply Chain Disruptions Are Pressuring Profit Margins: The specialty fuel additives industry depends heavily on petrochemical derivatives, specialty chemicals, and performance intermediates whose prices fluctuate with crude oil and global commodity cycles. Sudden shifts in raw material availability, logistics bottlenecks, and geopolitical instability have disrupted supply chains, forcing manufacturers to adjust pricing strategies or absorb increased costs. The Global Specialty Fuel Additives Market faces profitability risks when procurement volatility limits production flexibility. Long-term supply agreements can mitigate some challenges, but rising freight costs and sourcing constraints continue to strain operational efficiency. Smaller players struggle more with price fluctuations, which may lead to market consolidation. Manufacturers must balance cost management with the need for consistent quality and regulatory compliance. Regulatory Uncertainty and Regional Variability Are Slowing Product Innovation and Market Entry: Diverse regulatory frameworks across countries make it difficult for manufacturers to standardize product formulations and streamline global distribution. The Global Specialty Fuel Additives Market encounters inconsistent approval processes, varying performance benchmarks, and fragmented compliance criteria in North America, Europe, and Asia. These inconsistencies slow down time-to-market for new products and increase R&D costs due to required regional customization. It also affects long-term planning, especially for companies aiming to expand into emerging markets with evolving or unclear fuel standards. Navigating this complexity requires substantial investment in regulatory affairs and localized expertise. This challenge restricts the scalability of innovations and complicates international growth strategies for fuel additive suppliers.Market Opportunities:
Expanding Demand in Emerging Economies Is Creating Long-Term Growth Potential for Additive Manufacturers: Rapid industrialization, urbanization, and rising vehicle ownership in emerging markets are creating strong demand for high-efficiency fuels. Countries in Asia-Pacific, Latin America, and Africa are increasing investments in transportation infrastructure and tightening fuel quality regulations. The Global Specialty Fuel Additives Market has an opportunity to supply cost-effective, multifunctional additives tailored for low-to-mid grade fuel systems in these regions. It can address challenges like inconsistent fuel quality, poor combustion, and rising emissions. Local partnerships, regional manufacturing hubs, and tailored formulations will help companies tap into this growing customer base. Early market entry and localized compliance strategies offer a competitive advantage. Development of Next-Generation Additives for Alternative Fuels Can Support Sustainability Goals: The global energy transition is accelerating the use of alternative fuels such as biodiesel, ethanol blends, and synthetic fuels. These fuels often present storage, stability, and compatibility challenges that specialty additives can solve. The Global Specialty Fuel Additives Market has a significant opportunity to lead innovation in additive systems that support low-emission and renewable fuel platforms. It can help extend shelf life, improve cold weather performance, and ensure clean combustion in diverse applications. Engine and fuel system OEMs are increasingly seeking collaborative partners to co-develop additives that align with next-generation powertrain requirements. This shift opens a pathway for long-term product differentiation and regulatory alignment.Market Segmentation Analysis:
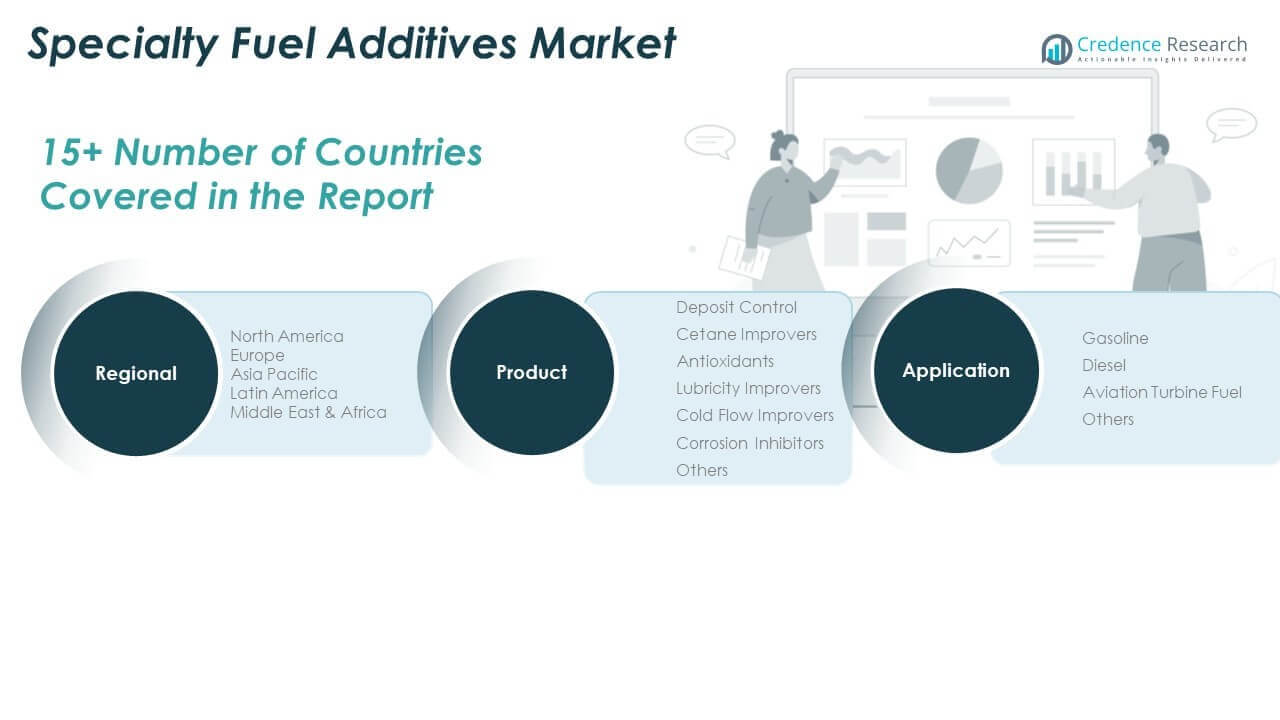
By Product The Global Specialty Fuel Additives Market is segmented into deposit control additives, cetane improvers, antioxidants, lubricity improvers, cold flow improvers, corrosion inhibitors, and others. Deposit control additives account for the largest revenue share due to their effectiveness in maintaining injector cleanliness and engine efficiency. Cetane improvers are widely used in diesel applications to enhance ignition quality and reduce engine noise. Antioxidants help prevent fuel degradation during storage and transport, especially in unstable or blended fuels. Lubricity improvers are critical in ultra-low sulfur diesel to protect fuel system components from excessive wear. Cold flow improvers enable reliable fuel performance in cold climates by minimizing wax crystal formation. Corrosion inhibitors prevent rust and metal damage, particularly in pipelines and storage tanks. Other additives cater to niche performance requirements in various fuel blends.- For instance, Afton Chemical’s HiTEC® series, such as HiTEC® 46600 are used in both diesel and gasoline applications. These additives deliver rapid clean-up of injectors, improved fuel economy, and superior corrosion control, with proven effectiveness in industry-standard tests and real-world fleet trials.
- For instance, Lubrizol supplies specialty additives for a wide range of fuels, including aviation turbine fuel and industrial applications.
Segmentation:
By Product- Deposit Control
- Cetane Improvers
- Antioxidants
- Lubricity Improvers
- Cold Flow Improvers
- Corrosion Inhibitors
- Others
- Gasoline
- Diesel
- Aviation Turbine Fuel
- Others
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America The North America Specialty Fuel Additives Market size was valued at USD 2,630.88 million in 2018 to USD 3,306.79 million in 2024 and is anticipated to reach USD 5,676.84 million by 2032, at a CAGR of 7.0% during the forecast period. North America holds a substantial 27.4% share of the Global Specialty Fuel Additives Market. The region benefits from stringent environmental regulations, widespread adoption of ultra-low sulfur diesel (ULSD), and strong demand for fuel-efficient technologies. The U.S. leads in consumption due to its extensive automotive, aviation, and industrial base. It continues to invest in clean fuel technologies and infrastructure modernization. Canada and Mexico contribute to growth with increased transportation activity and rising adoption of performance additives. The market remains competitive, with a strong presence of global and regional additive manufacturers. Europe The Europe Specialty Fuel Additives Market size was valued at USD 2,037.42 million in 2018 to USD 2,478.61 million in 2024 and is anticipated to reach USD 3,971.74 million by 2032, at a CAGR of 6.1% during the forecast period. Europe accounts for 20.5% of the Global Specialty Fuel Additives Market. Strict Euro VI and upcoming Euro VII emission norms are driving demand for advanced fuel additives. Countries like Germany, France, and the UK lead in the adoption of clean fuels and additive technologies. Diesel and aviation sectors rely heavily on additive solutions to ensure regulatory compliance and fuel system longevity. The shift toward alternative fuels and electric vehicles affects long-term demand but encourages innovation in hybrid-compatible additives. Regional players continue to focus on sustainability and compliance-driven formulations. Asia Pacific The Asia Pacific Specialty Fuel Additives Market size was valued at USD 3,475.71 million in 2018 to USD 4,569.82 million in 2024 and is anticipated to reach USD 8,432.93 million by 2032, at a CAGR of 8.0% during the forecast period. Asia Pacific leads the Global Specialty Fuel Additives Market with a dominant 37.9% share. China and India are major growth engines due to expanding automotive production, industrialization, and urban development. Emission mandates in China and fuel quality improvements across Southeast Asia support increased additive adoption. Japan and South Korea contribute with high-performance requirements in transportation and aviation. It is a key manufacturing hub for global additive suppliers, enhancing local access and cost efficiency. Growing demand for premium fuels and cold-weather additives in northern regions further drives product diversification. Latin America The Latin America Specialty Fuel Additives Market size was valued at USD 765.45 million in 2018 to USD 970.21 million in 2024 and is anticipated to reach USD 1,574.77 million by 2032, at a CAGR of 6.3% during the forecast period. Latin America holds a 8.0% share of the Global Specialty Fuel Additives Market. Brazil leads in consumption, driven by its large transportation sector and ethanol-blended fuel usage. Diesel additives dominate due to demand from freight and agricultural machinery. Argentina and other countries are adopting cleaner fuel policies, supporting moderate market expansion. Economic fluctuations and inconsistent regulatory frameworks pose challenges to uniform growth. It offers long-term opportunities in infrastructure, energy, and transport sectors with growing emphasis on efficiency and environmental compliance. Middle East The Middle East Specialty Fuel Additives Market size was valued at USD 326.03 million in 2018 to USD 387.33 million in 2024 and is anticipated to reach USD 593.74 million by 2032, at a CAGR of 5.5% during the forecast period. The Middle East represents 3.2% of the Global Specialty Fuel Additives Market. Rising investment in refining capacity, logistics, and aviation supports additive consumption. Gulf countries are improving fuel quality standards, leading to wider adoption of cetane improvers and corrosion inhibitors. The region's dependency on diesel and jet fuels creates steady demand across transportation and industrial sectors. Fuel exports and aviation hubs like the UAE also contribute to additive usage. Domestic production and import dependency shape pricing and supply stability. Africa The Africa Specialty Fuel Additives Market size was valued at USD 214.52 million in 2018 to USD 356.08 million in 2024 and is anticipated to reach USD 506.12 million by 2032, at a CAGR of 4.0% during the forecast period. Africa accounts for 2.9% of the Global Specialty Fuel Additives Market. South Africa remains the key market, supported by a relatively developed refining and transport network. Diesel additives dominate, especially in mining, construction, and off-road applications. Other countries are gradually upgrading fuel standards, opening opportunities for additive suppliers. Infrastructure limitations and inconsistent policy enforcement slow broader adoption. It offers untapped potential as governments prioritize emissions control and fuel efficiency over the next decade.Key Player Analysis:
- NewMarket Corporation
- Innospec
- BASF
- Infineum International Limited
- Albemarle Corporation
- Baker Hughes Company
- Dow
- Chevron Oronite Company LLC
- The Lubrizol Corporation
- TotalEnergies
- Dorf Ketal
- Clariant
- Eurenco
- NALCO Champion
- Evonik Industries AG
Competitive Analysis:
The Global Specialty Fuel Additives Market is highly competitive, with key players focusing on product innovation, regulatory compliance, and strategic partnerships. Leading companies such as NewMarket Corporation, Innospec, BASF, Infineum International Limited, and The Lubrizol Corporation dominate the market through diversified portfolios and strong global distribution networks. It features ongoing R&D to develop multifunctional, bio-based, and region-specific formulations that meet evolving fuel standards. Players are also expanding production capacities and investing in emerging markets to capture regional growth. Competitive intensity remains high, especially in diesel and aviation fuel segments, where performance and emissions compliance are critical. Price volatility in raw materials and varying regulatory landscapes across regions challenge both global and regional suppliers. Companies that align innovation with compliance and customer-specific performance requirements are likely to maintain leadership in this evolving landscape. Strategic mergers, acquisitions, and technology collaborations will continue shaping the competitive positioning across key application areas.Recent Developments:
- In June 2025, Dow announced an agreement to sell its 50% interest in the DowAksa Advanced Composites joint venture to Aksa Akrilik Kimya Sanayii A.Ş., with the transaction expected to close in the third quarter of 2025. This move aligns with Dow’s strategy to focus on core, high-value downstream businesses.Additionally, in August 2024, Dow extended its partnership with Richard Childress Racing to advance science-based innovation in automotive applications for the 2025 NASCAR season.
- In April 2025, Albemarle Corporation reported record energy storage lithium salt production and double-digit volume growth in its Specialties segment. The company maintained its 2025 outlook, citing exemptions from new tariffs and continued global demand for essential minerals. Albemarle also achieved approximately 90% of its cost and productivity improvement targets through April 2025.
- In April 2025, BASF launched three new natural-based ingredients for personal care at the in-cosmetics Global event in Amsterdam. These products-Verdessence® Maize, Lamesoft® OP Plus, and Dehyton® PK45 GA/RA-are designed to provide sustainable alternatives to traditional ingredients, supporting BASF’s commitment to biodegradable and eco-friendly solutions.In January 2025, BASF also introduced a new concept of climate-adaptive, eco-conscious formulations at Cosmet’Agora in Paris, focusing on hydration, UV protection, and sustainable beauty routines.
- In February 2025, Innospec entered a strategic partnership with UNESCO’s International Institute for Higher Education in Latin America and the Caribbean (IESALC) to launch a STEM education initiative for indigenous students in Brazil. The program, developed in collaboration with the Federal University of Minas Gerais, aims to train 40 indigenous students directly and benefit 200 more, reflecting Innospec’s commitment to sustainable development and social responsibility.
Market Concentration & Characteristics:
The Global Specialty Fuel Additives Market is moderately concentrated, with a mix of global leaders and regional players competing across application segments. It is characterized by high entry barriers due to regulatory requirements, formulation complexity, and the need for technical validation. Established companies dominate through proprietary technologies, long-term client contracts, and integrated supply chains. The market exhibits a strong focus on innovation, with continuous development of customized, multifunctional, and environmentally compliant additives. Demand varies by fuel type and regional standards, influencing product differentiation strategies. Suppliers prioritize reliability, fuel compatibility, and compliance with emissions norms to secure long-term partnerships with refineries and OEMs. Competitive dynamics remain stable, but pressure from raw material costs and emerging bio-based alternatives continues to shape market behavior.Report Coverage:
The research report offers an in-depth analysis based on product and application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook:
- Demand for multifunctional additives will rise as users seek cost-effective, high-performance fuel solutions.
- Bio-based and renewable additive development will accelerate to meet global sustainability targets.
- Diesel and aviation segments will remain dominant due to ongoing reliance in commercial transport and logistics.
- Growth in emerging economies will create new opportunities through fuel quality upgrades and industrial expansion.
- Regulatory tightening across regions will continue to drive innovation in emissions-reducing additive technologies.
- Cold flow and lubricity improvers will see higher demand in colder regions and ULSD markets.
- OEM collaborations will increase to align additive performance with evolving engine technologies.
- Digital dosing and monitoring systems will gain traction for improved additive management and fuel optimization.
- Price volatility in petrochemical feedstocks may influence supply chain strategies and margin pressures.
- Market consolidation may intensify as major players seek scale and geographic diversification through acquisitions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Emissions Regulations
Global adoption of stricter emission standards such as Euro VI and U.S. EPA Tier 3 is compelling fuel suppliers to use advanced additives that reduce particulate matter and nitrogen oxide emissions, driving demand for specialty fuel additives.
Widespread Adoption of Ultra-Low Sulfur Diesel (ULSD)
The shift to ULSD, which lacks natural lubricity, has increased the need for lubricity improvers, stabilizers, and corrosion inhibitors to maintain engine performance and longevity, boosting additive consumption across commercial fleets and industrial engines.
Rising Focus on Fuel Economy and Engine Protection
With volatile fuel prices and aging vehicle fleets, end users are increasingly adopting additives that improve fuel economy, clean injectors, and reduce carbon deposits, supporting both cost savings and reduced maintenance.
Growth in Vehicle Fleets and Industrial Engines
Expanding automotive, industrial, and aviation sectors - especially in emerging markets - are increasing the consumption of both diesel and gasoline, thereby raising the demand for specialty fuel additives to ensure optimal engine performance and compliance.
Innovation in Bio-Based and Environmentally Friendly Additives
Manufacturers are developing bio-based and eco-friendly additive formulations to align with global sustainability goals and green fuel policies, opening new market opportunities and supporting regulatory compliance.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Specialty Fuel Additives Market?
What factors are driving the growth of the Global Specialty Fuel Additives Market?
What are the key segments within the Global Specialty Fuel Additives Market?
What are some challenges faced by the Global Specialty Fuel Additives Market?
Who are the major players in the Global Specialty Fuel Additives Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Deposit Control Additives
- 1.2.2 Cetane Improvers
- 1.2.3 Antioxidants
- 1.2.4 Lubricity Improvers
- 1.2.5 Cold Flow Improvers
- 1.2.6 Corrosion Inhibitors
- 1.2.7 Others
- 1.3 By Application
- 1.3.1 Gasoline
- 1.3.2 Diesel
- 1.3.3 Aviation Turbine Fuel
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 12,068.85 million → 2032: USD 20,756.15 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Specialty Fuel Additives Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Specialty Fuel Additives Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Specialty Fuel Additives Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Specialty Fuel Additives Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Specialty Fuel Additives Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Specialty Fuel Additives Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Specialty Fuel Additives Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Specialty Fuel Additives Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 12,068.85 million → 2032: USD 20,756.15 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Specialty Fuel Additives Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Deposit Control Additives
- 12.3.7.2 Cetane Improvers
- 12.3.7.3 Antioxidants
- 12.3.7.4 Lubricity Improvers
- 12.3.7.5 Cold Flow Improvers
- 12.3.7.6 Corrosion Inhibitors
- 12.3.7.7 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Gasoline
- 12.4.7.2 Diesel
- 12.4.7.3 Aviation Turbine Fuel
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Specialty Fuel Additives End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Specialty Fuel Additives Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Specialty Fuel Additives Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Specialty Fuel Additives Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 NewMarket Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Innospec
- 18.4 BASF
- 18.5 Infineum International Limited
- 18.6 Albemarle Corporation
- 18.7 Baker Hughes Company
- 18.8 Dow
- 18.9 Chevron Oronite Company LLC
- 18.10 The Lubrizol Corporation
- 18.11 Clariant
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

