
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Starch-Based Plastics Market Size 2024 | USD 1914 million |
| Starch-Based Plastics Market, CAGR | 9.43% |
| Starch-Based Plastics Market Size 2032 | USD 3935.8 million |
Market Overview:
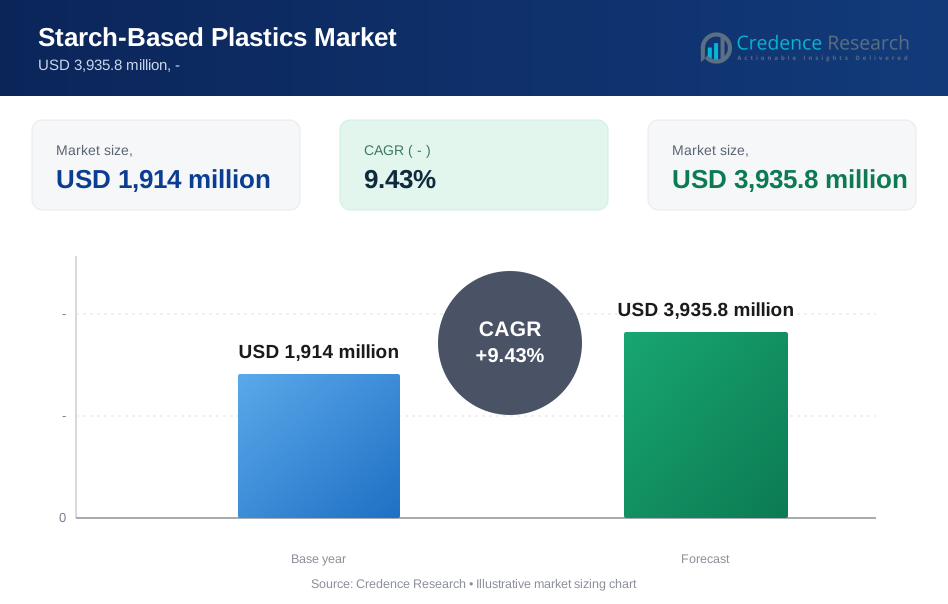
The Starch-based Plastics Market is projected to grow from USD 1914 million in 2024 to an estimated USD 3935.8 million by 2032, with a compound annual growth rate (CAGR) of 9.43% from 2024 to 2032.
Several factors drive the demand for starch-based plastics, primarily the shift towards sustainable packaging solutions and increased regulatory restrictions on traditional plastic usage. Growing awareness among consumers and manufacturers about the environmental impacts of plastic waste has catalyzed the adoption of biodegradable plastics, of which starch-based types are among the most prominent. These materials are renewable, compostable, and reduce reliance on petroleum-based resources, making them highly desirable for single-use packaging applications, particularly in the food and beverage sector. Furthermore, advancements in starch processing and blending technologies have improved the performance and durability of starch-based plastics, allowing them to compete more effectively with conventional plastics. This increasing performance versatility has also encouraged their use in various sectors, including agriculture, where they help reduce plastic contamination in soils.
Regionally, Europe holds a leading share in the starch-based plastics market, supported by strict regulations on plastic waste, high environmental awareness, and established infrastructure for compostable materials. North America follows, with significant demand from industries aiming to improve their sustainability profiles, particularly in the U.S. The Asia-Pacific region, especially countries like China, Japan, and India, is expected to see the fastest growth due to rising consumer awareness and governmental efforts to curb plastic pollution. Latin America and the Middle East are also emerging markets, driven by growing environmental awareness and gradual adoption of biodegradable plastics across multiple industries. This regional diversity underscores the global appeal of starch-based plastics as a versatile, eco-friendly solution aligned with sustainable development goals.
Market Drivers:
Increasing Demand for Sustainable Packaging Solutions:
One of the primary drivers in the starch-based plastics market is the rising demand for sustainable packaging solutions. As consumer preferences shift towards eco-friendly products, manufacturers are increasingly seeking alternatives to traditional petroleum-based plastics. Starch-based plastics, derived from renewable resources like corn, potatoes, and tapioca, offer a biodegradable and compostable solution, making them particularly attractive for packaging applications. Single-use packaging, especially in the food and beverage sector, benefits significantly from starch-based plastics as they fulfill sustainability goals without compromising quality. This trend is reinforced by businesses aiming to align with consumer expectations and meet corporate social responsibility standards through environmentally friendly packaging.
Regulatory Support and Restrictions on Conventional Plastics:
Stricter regulations and policies against single-use plastics globally are a major catalyst driving the growth of starch-based plastics. Governments and environmental agencies in regions such as Europe and North America have enacted policies that limit or ban the use of non-biodegradable plastics to reduce plastic waste and its harmful impact on the environment. These regulations encourage businesses to seek alternative materials, propelling the adoption of starch-based plastics, which comply with biodegradable packaging standards. Europe, for instance, has stringent waste management laws that promote compostable plastics, creating favorable conditions for starch-based alternatives. Such regulatory support is a powerful force driving market expansion, with other regions gradually following suit as global awareness around plastic waste increases.
Advancements in Material Properties and Processing Technologies:
Technological advancements in the production and formulation of starch-based plastics have significantly improved their durability, flexibility, and resistance to moisture, making them more suitable for diverse applications. Innovations in blending starch with other biopolymers or additives have enhanced performance characteristics, allowing starch-based plastics to compete with conventional plastics in terms of strength and shelf life. For instance, Green Dot Bioplastics has developed Terratek SC, a proprietary blend of wheat starch and polypropylene made up of 65% renewable material. These developments have broadened the scope of starch-based plastics beyond packaging into sectors like agriculture, where they can be used for mulch films and plant pots, as well as consumer goods. The improvement in material properties makes starch-based plastics viable for products that demand higher durability, expanding their market potential and driving industry growth as manufacturers explore new applications.
Rising Awareness and Commitment to Carbon Reduction:
Growing awareness of climate change and the environmental impact of fossil fuels have encouraged companies and consumers alike to seek carbon-reducing alternatives, including starch-based plastics. Since these plastics are derived from renewable resources and decompose naturally, they contribute to lower greenhouse gas emissions across their lifecycle compared to traditional plastics. This characteristic aligns with the sustainability goals of companies that are increasingly committing to carbon reduction initiatives. For instance, Plantic Technologies has created innovative packaging made predominantly from starch and recycled materials. By replacing petroleum-based plastics with starch-based options, companies can achieve lower environmental footprints, which appeals to environmentally conscious consumers and complies with green certifications. This alignment with sustainability goals acts as a powerful driver in expanding the starch-based plastics market, supporting both corporate and consumer objectives in reducing environmental impact.
Market Trends:
Growing Preference for Biodegradable Materials in Packaging:
A significant trend in the starch-based plastics market is the increasing preference for biodegradable materials in packaging applications. As consumers and companies become more environmentally conscious, the demand for sustainable packaging solutions has grown, leading to a shift away from conventional, non-degradable plastics. Starch-based plastics, which are compostable and reduce landfill waste, are well-suited for single-use packaging such as food containers, cutlery, and shopping bags. For instance, NatureWorks LLC, a major producer of bioplastics derived from plant resources like cornstarch, has seen growing demand for its Ingeo biopolymer products used in food packaging, serviceware, and other applications. This trend is particularly strong in regions where there are established composting facilities and consumer interest in eco-friendly packaging, pushing manufacturers to adopt starch-based alternatives that align with sustainability goals.
Rise in Bio-Based Product Innovations:
The starch-based plastics market is experiencing a wave of innovations aimed at enhancing the properties of bio-based products. Research and development efforts are focused on improving the mechanical strength, moisture resistance, and flexibility of starch-based plastics to expand their application scope beyond packaging. Blending starch with other biopolymers, such as polylactic acid (PLA) or polyhydroxyalkanoates (PHA), has allowed manufacturers to create materials that can withstand more demanding applications in agriculture, medical, and industrial sectors. These product innovations not only improve usability but also make starch-based plastics a competitive alternative to petroleum-based plastics in terms of performance, which is expanding their market reach.
Expansion of Compostable Product Regulations:
Regulatory frameworks worldwide are increasingly mandating the use of compostable materials, particularly in packaging, which is propelling growth in the starch-based plastics market. In Europe, for instance, the EU’s single-use plastics directive encourages member states to restrict non-biodegradable plastic usage and adopt compostable alternatives. Such regulatory measures create strong incentives for companies to shift to starch-based plastics, which comply with compostability standards, and align with these eco-friendly policies. North America and Asia are following similar regulatory trends, particularly in cities and states where plastic bans are gaining traction. This expansion of compostable product regulations encourages the development and use of starch-based materials, which fulfill these environmental guidelines, further fueling market growth.
Increased Adoption in Emerging Markets:
Emerging markets, especially in Asia-Pacific and Latin America, are witnessing increased adoption of starch-based plastics, driven by rising awareness of environmental sustainability and economic development. With urbanization and changing consumer preferences, demand for eco-friendly products is on the rise in countries such as China, India, and Brazil. Governments in these regions are gradually introducing initiatives to curb plastic pollution, making starch-based plastics a viable alternative for local manufacturers. As infrastructure for waste management and composting grows in these areas, starch-based plastics are gaining traction as a sustainable solution that reduces plastic waste. This trend toward green alternatives in emerging markets opens up new opportunities for starch-based plastic manufacturers and diversifies the market’s global footprint.
Market Restraints and Challenges:
High Production Costs and Limited Scale of Production:
One of the primary restraints in the starch-based plastics market is the high cost associated with production. Compared to traditional petroleum-based plastics, starch-based plastics involve more complex manufacturing processes, often requiring specialized equipment and raw materials, which raises overall costs. Additionally, the limited scale of production means that starch-based plastics are not yet produced at levels that would allow economies of scale, keeping prices high and limiting accessibility, particularly in price-sensitive markets. These cost factors make starch-based plastics less competitive with conventional plastics, especially in sectors where budget constraints are critical.
Performance Limitations in Certain Applications:
Despite improvements, starch-based plastics still face performance limitations that hinder their use in certain applications. Compared to conventional plastics, starch-based alternatives are generally less durable and may have lower resistance to moisture and heat. These properties restrict their usage in high-performance applications, such as in automotive or heavy industrial sectors, where materials are required to withstand harsh conditions. While advancements in blending starch with other biodegradable polymers have improved durability, performance gaps remain a challenge, limiting the potential applications of starch-based plastics across industries.
Regulatory and Infrastructure Challenges in Emerging Markets:
The lack of regulatory support and infrastructure for biodegradable plastics in some emerging markets poses challenges to the starch-based plastics market. Although awareness around plastic pollution is growing, many regions lack the necessary waste management and composting infrastructure to handle biodegradable plastics efficiently. This limits the potential benefits of starch-based plastics, as they require specific conditions to decompose effectively. Furthermore, inconsistent regulatory frameworks across regions can create challenges for manufacturers seeking to expand globally, as compliance requirements may vary significantly, leading to increased costs and logistical complexities.
Competition from Other Biodegradable Alternatives:
Starch-based plastics face competition from other biodegradable materials such as polylactic acid (PLA), polyhydroxyalkanoates (PHA), and cellulose-based plastics. Each of these materials has unique properties and advantages, allowing them to cater to specific market needs. For instance, PLA has gained popularity in packaging due to its relative durability and cost-effectiveness, making it a strong competitor to starch-based plastics. As companies seek versatile and high-performance alternatives, this competition adds pressure on starch-based plastics to innovate continuously to maintain their market share.
Market Segmentation Analysis:
By Type, the market is primarily divided into Thermoplastic Starch and Starch Polymer Blends. Thermoplastic starch (TPS) dominates the market due to its biodegradability, versatility, and competitive pricing. As the most basic form of starch-based plastic, TPS is increasingly used in packaging and agriculture applications where environmental sustainability is prioritized. Starch polymer blends, on the other hand, offer enhanced durability and flexibility by combining starch with other polymers, making them suitable for applications requiring greater resilience, such as automotive components and consumer goods. This segment's growth is driven by innovation in blending techniques, aiming to improve the material’s functional properties while maintaining biodegradability.
By End-User, starch-based plastics find applications across sectors like Automotive and Transportation, Agriculture, Packaging, Consumer Goods, and Others. The packaging segment holds the largest share, leveraging starch-based plastics for disposable items such as bags, wrappers, and containers. In agriculture, starch-based plastics are utilized for mulching films and biodegradable pots, aiding in sustainable farming practices. The automotive and transportation sector uses starch polymer blends in specific interior components, driven by industry goals to reduce carbon footprints. Consumer goods also benefit, as companies increasingly adopt eco-friendly materials for items like cutlery, containers, and small appliances. Collectively, these segments drive the starch-based plastics market, with a focus on reducing environmental impact across industries.
Segmentation:
By Type
- Thermoplastic Starch
- Starch Polymer Blends
By End-User
- Automotive and Transportation
- Agriculture
- Packaging
- Consumer Goods
- Others
By Geographic
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The starch-based plastics market demonstrates varied growth patterns and potential across key regions, with regional differences shaped by environmental policies, consumer preferences, and production capabilities. The primary regions include North America, Europe, Asia-Pacific, Latin America, and the Middle East and Africa, each contributing uniquely to market dynamics and shaping the global landscape.
In North America, starch-based plastics have garnered significant interest due to increasing awareness of environmental sustainability and stringent government regulations on single-use plastics. The United States and Canada are the main contributors in this region, collectively holding approximately 25% of the global market share. Growing environmental awareness, coupled with consumer preference for eco-friendly products, continues to drive demand. However, relatively high production costs limit mass adoption across all sectors.
Europe remains a dominant player in the starch-based plastics market, holding nearly 35% of the global market share. Strict regulations on plastic usage, coupled with progressive sustainability initiatives by the European Union, have accelerated the adoption of starch-based alternatives in countries like Germany, France, and the United Kingdom. Europe's high market share is further bolstered by a robust research and development infrastructure that supports innovation and the scalability of biodegradable plastics. As a result, the region witnesses high demand across the packaging, agriculture, and consumer goods sectors.
Asia-Pacific is an emerging leader, holding around 20% of the market share and showcasing substantial growth potential. Countries like China, India, and Japan are increasingly investing in biodegradable plastic alternatives due to mounting environmental concerns and a surge in demand from various industries. The region’s large population base, coupled with growing urbanization, provides a vast consumer market that encourages expansion. However, challenges remain with infrastructure and cost competitiveness, which could hinder faster adoption.
Latin America and the Middle East & Africa regions jointly contribute to about 10% of the global market share. In Latin America, Brazil and Mexico are driving adoption, motivated by rising awareness of eco-friendly packaging and agricultural applications. Meanwhile, the Middle East & Africa region, while still nascent in adoption, shows promising growth due to increasing government focus on sustainable development. However, limited technological infrastructure and high costs pose challenges to rapid expansion.
Key Player Analysis:
- AGRANA BETEILIGUNGS AG
- BioLogiQ Inc
- Biome Bioplastics Limited
- BIOTEC GmbH & Co
- Cardia Bioplastics
- Corbion N.V
- FuturaMatSOLANYL BP
- Grabio Greentech
- Green Dot
- Kuraray Co. Ltd
- Multibax Public Company Limited
- Nihon Cornstarch Corporation
- Novamont S.p.A
- NUREL
- Rodenburg Biopolymers
- Sunar NP
- Toray Industries Inc
- Wittenburg Group
Competitive Analysis:
The starch-based plastics market is moderately competitive, with a mix of established players and emerging companies focused on expanding eco-friendly product portfolios. Key companies, such as Novamont, BASF, and Biome Bioplastics, lead the market due to their robust research and development capabilities and established distribution networks. These companies have made substantial investments in improving the performance of starch-based plastics, making them viable alternatives for various packaging and consumer applications. Smaller players and startups are also entering the market, aiming to tap into niche applications and regional demand, particularly in emerging markets where interest in biodegradable solutions is growing. To strengthen their market position, companies are pursuing strategies such as product innovation, strategic partnerships, and mergers to broaden their offerings and enhance production capacity. Overall, the market’s competitive landscape is characterized by continuous innovation and a growing focus on sustainable solutions that cater to an environmentally conscious consumer base.
Recent Developments:
- In January 2023, Kuraray announced a price increase for its GENESTARTM heat-resistant polyamide resin, effective February 1, 2023, for both domestic and international shipments. GENESTARTM is an engineering-grade polyamide plastic derived from a specialized monomer, widely used across applications ranging from automotive parts to electrical and electronic components.
- In November 2022, Kuraray Co., Ltd. introduced a new addition to its MAGIC TAPE™ lineup of polyester hook-and-loop fasteners, developed using recycled raw materials. This product was launched to provide apparel and other manufacturers with a sustainable material, supporting efforts toward a circular economy.
Market Concentration & Characteristics:
The starch-based plastics market displays a moderate level of concentration, with a few large players holding significant market shares alongside numerous smaller, specialized firms. Key companies like Novamont, BASF, and NatureWorks lead the industry due to their advanced research capabilities, extensive product portfolios, and well-established distribution channels. These major players benefit from economies of scale and substantial investments in R&D, allowing them to develop high-performance starch-based plastics tailored to diverse applications. The market is characterized by a strong focus on sustainability, as starch-based plastics align with growing environmental regulations and consumer demand for biodegradable alternatives. Innovation is a defining characteristic, with continuous advancements aimed at enhancing the material’s durability, moisture resistance, and applicability across industries. The market also features regional diversity, as smaller companies in Asia-Pacific and Latin America target niche applications and capitalize on rising demand in local markets, contributing to the market’s dynamic nature.
Report Coverage:
The research report offers an in-depth analysis based on By Type and By End-User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for eco-friendly packaging will drive significant growth in starch-based plastics across consumer goods.
- Advances in blending technologies are expected to improve durability and expand application areas for starch-based plastics.
- Increasing regulatory support for biodegradable materials will boost adoption, particularly in regions with strict plastic bans.
- Growth in composting infrastructure will enhance the viability of starch-based plastics, aiding waste management initiatives.
- High production costs may decrease as manufacturing scales up, making starch-based options more cost-competitive.
- Emerging markets, especially in Asia-Pacific and Latin America, will contribute to market expansion through rising environmental awareness.
- Ongoing R&D investments will enhance performance, enabling starch-based plastics to compete with conventional plastics.
- Expansion beyond packaging into agriculture and medical sectors will diversify market applications.
- Strategic partnerships and mergers will drive innovation and broaden the product portfolios of leading companies.
- Increasing consumer preference for sustainable products will maintain long-term demand and market momentum.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate for the starch-based plastics market?
What drives the demand for starch-based plastics?
Which region leads the starch-based plastics market?
What are the main challenges for the starch-based plastics market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Starch-Based Plastics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Starch-Based Plastics Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 1,914 million → forecast year: USD 3,935.8 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Starch-Based Plastics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Starch-Based Plastics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Starch-Based Plastics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Starch-Based Plastics Market Drivers
- 3.3 Starch-Based Plastics Market Restraints & Challenges
- 3.4 Starch-Based Plastics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Starch-Based Plastics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Starch-Based Plastics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Starch-Based Plastics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Starch-Based Plastics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Starch-Based Plastics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Starch-Based Plastics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Starch-Based Plastics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Starch-Based Plastics Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Starch-Based Plastics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Starch-Based Plastics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Starch-Based Plastics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Starch-Based Plastics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Starch-Based Plastics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Starch-Based Plastics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Starch-Based Plastics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Starch-Based Plastics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Starch-Based Plastics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Starch-Based Plastics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Starch-Based Plastics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
