
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Tax Management Market Size 2024 | USD 22,589.91 million |
| Tax Management Market, CAGR | 6.34% |
| Tax Management Market Size 2032 | USD 36,756.61 million |
Market Overview:
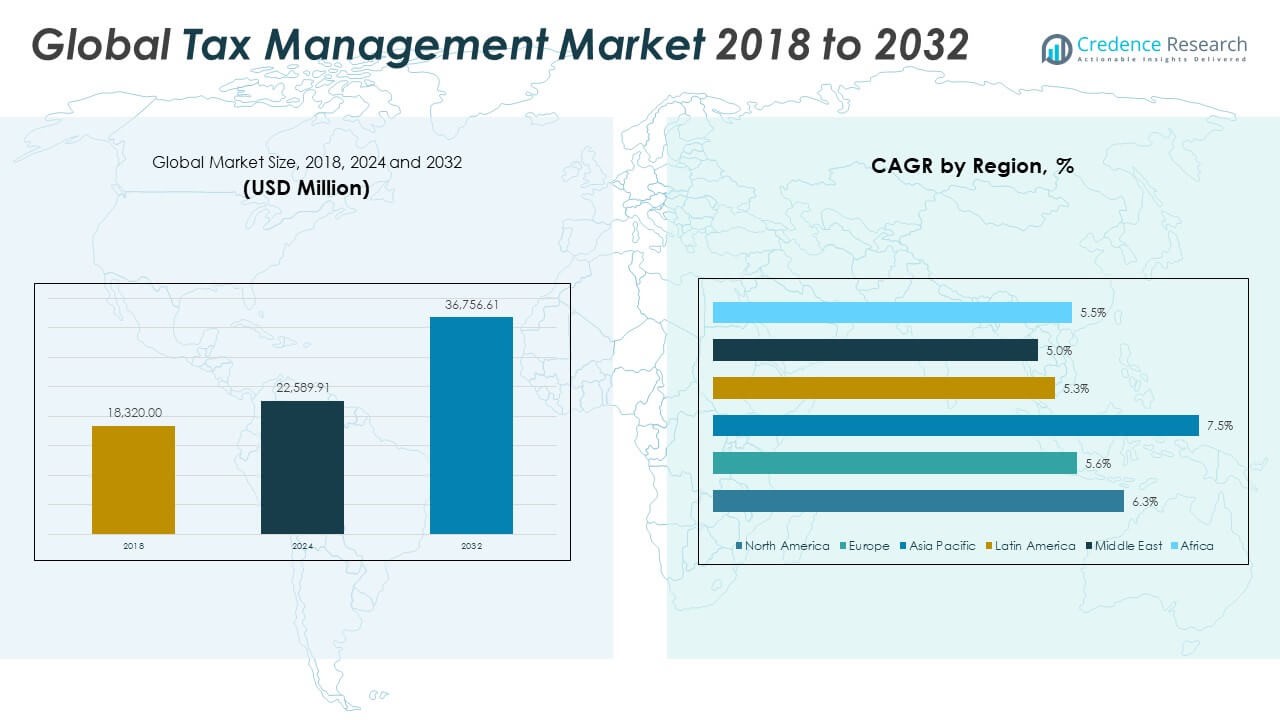
The Tax Management Market size was valued at USD 18,320.00 million in 2018 to USD 22,589.91 million in 2024 and is anticipated to reach USD 36,756.61 million by 2032, at a CAGR of 6.34% during the forecast period.
The market is witnessing strong growth due to rising regulatory complexity and the demand for real-time tax reporting solutions. Businesses are increasingly adopting advanced tax management software to reduce compliance risks and streamline operations. The rise of cross-border transactions and digital business models is also contributing to the demand for intelligent tax automation platforms. Governments are tightening tax reporting standards, further encouraging companies to invest in integrated tax solutions that can adapt quickly to regulatory updates and ensure accurate, timely filings.
Regionally, North America leads the Tax Management Market due to the presence of large multinational corporations, sophisticated tax regulations, and early adoption of cloud-based tax technologies. Europe follows closely, driven by stringent VAT regulations and digital compliance mandates across the EU. Asia Pacific is emerging as a high-growth region, propelled by digital transformation in countries like India, China, and Southeast Asia. Increasing government emphasis on transparency and e-invoicing systems is pushing enterprises in these markets to implement scalable tax management solutions.
Market Insights:
- The Tax Management Market size was valued at USD 18,320.00 million in 2018 and reached USD 22,589.91 million in 2024; it is projected to attain USD 36,756.61 million by 2032, growing at a CAGR of 6.34% during the forecast period.
- Demand for real-time tax reporting and automation is accelerating due to complex and evolving regulatory frameworks across multiple jurisdictions.
- Rising digital transformation in enterprises is driving the integration of AI-enabled tax engines for accurate compliance and risk reduction.
- High implementation costs, especially for SMEs, remain a major barrier to widespread adoption of enterprise-grade tax platforms.
- Constant updates to local tax laws and global reporting standards create operational pressure and demand ongoing software upgrades.
- North America leads the market due to advanced regulatory systems and early adoption of cloud tax technologies, followed by Europe.
- Asia Pacific is emerging rapidly, supported by digital tax reforms and growing e-invoicing mandates across India, China, and Southeast Asia.
Market Drivers:
Rising Global Regulatory Complexity Requires Advanced Compliance Tools
Governments are continuously revising tax regulations, increasing complexity for businesses operating across borders. Tax authorities now demand greater transparency and real-time reporting, prompting companies to adopt sophisticated compliance solutions. Manual methods are insufficient to manage evolving regulatory landscapes, driving demand for intelligent tax engines. Enterprises seek to minimize audit risks and penalties through automated calculation, classification, and submission tools. The Tax Management Market benefits from this shift toward proactive compliance management. It supports streamlined reporting in line with regional and international standards. Tax departments need systems that can adjust quickly to changing legal frameworks. This complexity acts as a primary force behind market expansion.
- For example, Vertex enhanced its tax engine with dynamic rule applications that automatically apply jurisdiction-specific tax rates and rules at the point of calculation. This update supports accurate transactional compliance for e-commerce and marketplace transactions across more than 19,000 U.S. and international jurisdictions.
Digitalization of Tax Processes Promotes System Integration and Automation
Governments are embracing digital tax platforms, making electronic invoicing and digital filings mandatory in many regions. Businesses are responding by integrating tax software with enterprise systems to automate compliance workflows. Digital transformation in finance functions encourages adoption of tax technology aligned with broader IT modernization strategies. Automated tax determination and real-time updates are becoming essential to operational efficiency. The Tax Management Market is expanding as companies aim to create seamless, data-driven environments. It drives value through improved accuracy and time savings. Legacy systems struggle to meet these evolving demands, accelerating migration to cloud-based tax solutions. Organizations increasingly prioritize scalable platforms that adapt to future digital mandates.
- For example, Bloomberg Tax & Accounting introduced an AI Expression Generator within its Workpapers application. The tool enables tax professionals to input plain‑language prompts and instantly receive auto‑generated formulas, greatly reducing manual errors and enhancing efficiency.
Surging Volume of Cross-Border Transactions Fuels Adoption of Global Tax Tools
Cross-border e-commerce, global supply chains, and multinational operations have created tax obligations in multiple jurisdictions. Each country has unique rules for indirect taxes, transfer pricing, and reporting, intensifying compliance challenges. Businesses must implement global tax solutions that ensure accuracy and transparency across locations. The Tax Management Market supports international operations by enabling centralized visibility into tax positions. It helps prevent double taxation and ensures adherence to treaty requirements. Real-time transaction data must be processed quickly to manage VAT, GST, and digital service taxes. The market responds to growing demand for harmonized tools capable of multi-jurisdictional compliance. Scalability and localization are now critical factors for selection.
Focus on Risk Management and Audit Readiness Drives Strategic Investment
Tax departments are increasingly held accountable for governance and risk mitigation, influencing enterprise-level investment decisions. Executives prioritize platforms that offer audit trails, version controls, and user-based access rights. These capabilities strengthen internal controls and reduce exposure to financial risk. The Tax Management Market is growing as organizations seek to proactively manage disputes and audits. It supports consistent documentation and timely responses to tax authority queries. Strategic use of analytics enhances visibility into liabilities and potential red flags. Companies value solutions that ensure accuracy, improve stakeholder confidence, and reduce the burden of audits. Investments in these systems reflect a broader push for tax function maturity.
Market Trends:
Emergence of AI and Machine Learning in Tax Automation Tools
Artificial intelligence and machine learning are transforming how companies approach tax compliance and planning. These technologies enable predictive analytics, anomaly detection, and intelligent workflow automation. AI helps classify transactions, detect risks, and recommend optimal tax treatments with minimal manual intervention. Machine learning improves system performance by adapting to new patterns in financial data. The Tax Management Market is evolving with solutions that incorporate AI-powered engines for smarter decision-making. It allows tax professionals to focus on strategic advisory rather than routine processing. These tools also enhance audit readiness by flagging inconsistencies proactively. Innovation in AI is setting a new standard in tax operations.
- For example, Sovos officially launched Sovos Intelligence in July 2025, introducing AI-powered capabilities like real-time anomaly detection and natural-language analytics, built on its Tax Compliance Cloud and powered by the Sovi™ AI The platform unifies tax, e-invoicing, and reporting data into a single, real-time model.
Rise of Cloud-Native Tax Platforms and Subscription Models
Cloud-native tax platforms are replacing on premise systems due to their scalability, cost-efficiency, and integration capabilities. Companies prefer Software-as-a-Service (SaaS) models that offer faster updates, lower maintenance, and predictable costs. Cloud environments allow centralized control across distributed business units. The Tax Management Market is responding with platforms designed for seamless cloud deployment and real-time collaboration. It enables continuous access to regulatory updates and performance monitoring. Cloud architecture supports integration with ERP, CRM, and procurement systems. Organizations value the ability to scale solutions across regions and business lines. Cloud-native models are redefining delivery and support standards in tax compliance technology.
Integration of Real-Time Data Analytics for Decision Support
Real-time tax analytics are gaining prominence as businesses seek actionable insights for planning and compliance. Embedded analytics provide dashboards, alerts, and visualization tools that inform strategic decisions. Real-time capabilities support transaction-level tracking and scenario modeling, essential in dynamic tax environments. The Tax Management Market now includes platforms that combine compliance with advanced data tools. It enables CFOs and tax leaders to monitor liabilities, reconcile discrepancies, and forecast outcomes. Access to live data enhances transparency and strengthens decision-making. Tax functions are becoming more analytical, requiring tools that provide depth and agility. This trend reinforces the role of tax in corporate performance strategy.
- For example, Avalara’s real-time data tools allow businesses to predict VAT and other tax obligations based on live transaction feeds, enhancing cash flow management and reducing the risk of unexpected tax exposures
Growing Use of Blockchain for Secure and Transparent Tax Records
Blockchain is emerging as a solution for secure and tamper-proof tax documentation and reporting. Distributed ledger technology enhances transparency in financial records and transaction validation. Governments and corporations are exploring blockchain to improve indirect tax collection and prevent fraud. The Tax Management Market is witnessing initial integration of blockchain into e-invoicing and VAT reconciliation systems. It creates immutable records that support audit integrity and data security. Blockchain also facilitates cross-border compliance by enabling traceable and standardized documentation. Adoption remains at an early stage but holds significant potential. It signals a shift toward more decentralized and trusted tax ecosystems.
Market Challenges Analysis:
High Implementation Costs and Integration Complexity Limit Adoption
Despite the advantages of advanced tax platforms, implementation remains expensive and resource-intensive. Organizations must invest in infrastructure, training, and customization to align systems with their tax structures. Integration with existing ERP, billing, and accounting systems adds further complexity. Smaller businesses often lack the budget and technical expertise required for enterprise-grade platforms. The Tax Management Market faces barriers in reaching cost-sensitive segments. It requires vendors to offer flexible pricing models and modular adoption paths. Limited internal IT support can slow deployment timelines. These challenges restrict access to technology for mid-sized companies and emerging markets.
Rapidly Evolving Tax Regulations Create Pressure on System Adaptability
Tax laws are subject to frequent changes across jurisdictions, requiring systems to adapt quickly. Delays in software updates can result in compliance failures and financial penalties. Businesses must monitor tax rule changes in real time, especially in countries with aggressive tax reform agendas. The Tax Management Market must deliver timely and accurate updates across its platforms. It places pressure on vendors to maintain robust regulatory intelligence networks. Misinterpretation or delayed updates undermine user confidence. Complexity increases in organizations operating in diverse regulatory environments. Continuous system calibration becomes essential to maintain compliance and operational continuity.
Market Opportunities:
Expansion into Emerging Markets with Digital Tax Infrastructure Growth
Emerging economies are modernizing their tax systems with digital invoicing and electronic filing mandates. This shift opens opportunities for solution providers to enter high-growth markets. The Tax Management Market can expand its footprint by offering localized tools tailored to regional compliance needs. It benefits from rising demand in Asia, Latin America, and the Middle East. Vendors that adapt platforms to local languages and rules gain competitive advantage. Governments in these regions promote formalization and transparency, driving investment in automation. It sets the stage for broader adoption among local enterprises and SMEs.
Demand for End-to-End Tax Platforms from Multinational Corporations
Global businesses seek centralized platforms that support compliance across multiple jurisdictions. They require unified dashboards, audit capabilities, and local rule engines in a single interface. The Tax Management Market is well-positioned to address this need through comprehensive, cross-border solutions. It can grow by aligning with multinational digital transformation strategies. Scalable and secure platforms gain traction among firms seeking control and efficiency. This demand supports long-term growth and innovation within the market.
Market Segmentation Analysis:
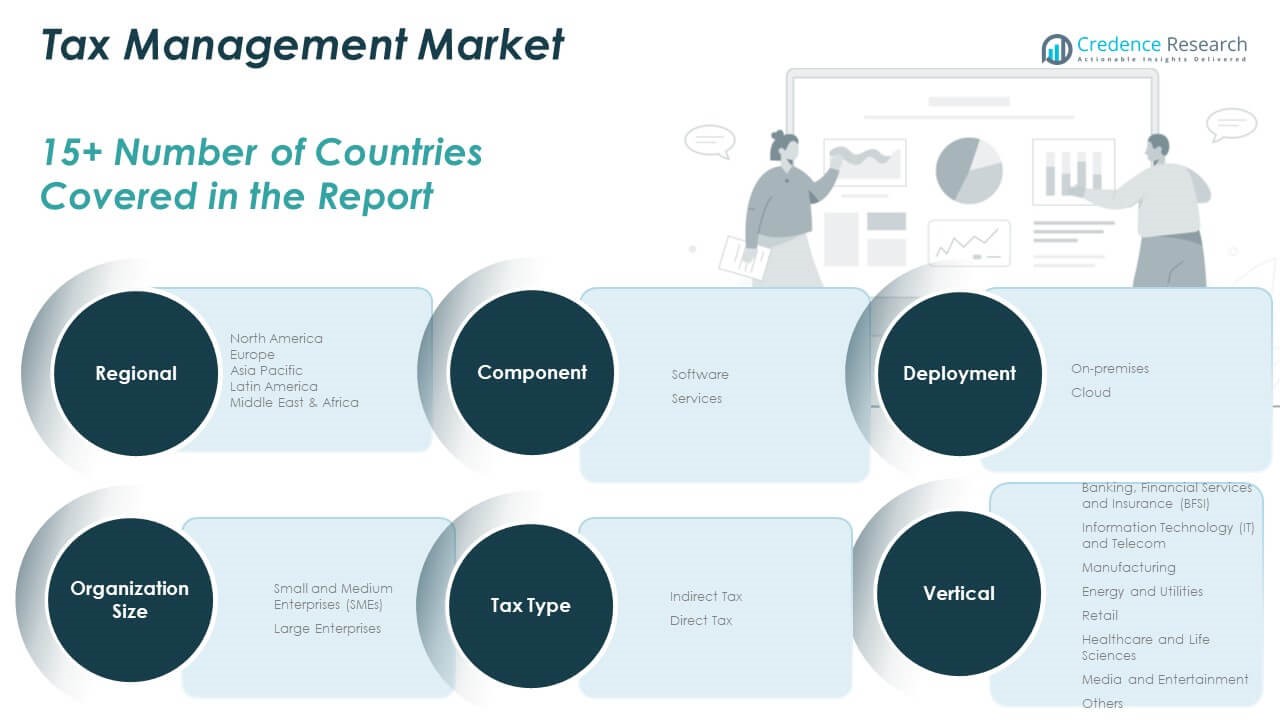
The Tax Management Market is segmented
By component into software and services. Software accounts for a larger share due to rising demand for automation, real-time reporting, and integration with enterprise systems. Services support implementation, consulting, and maintenance, gaining traction among SMEs lacking internal IT resources.
- For example, Ryan, a global tax services and software provider, announced a partnership with Alteryx, Inc. to deliver advanced tax function automation.
By tax type, indirect tax dominates owing to the complexity of VAT, GST, and digital sales tax across jurisdictions. Direct tax solutions are also expanding due to growing compliance scrutiny in corporate income tax reporting.
By vertical, BFSI leads the market due to the sector’s high regulatory exposure and complex transactional nature. IT and telecom follow closely, with strong adoption of cloud tax solutions. Manufacturing, energy, and utilities segments show steady growth due to increasing digital transformation and global supply chain compliance needs. Retail and healthcare demand scalable solutions for multi-jurisdictional reporting, while media and entertainment require tools for digital service taxes.
By Deployment-wise, cloud-based solutions are growing rapidly, favored for their scalability, updates, and remote accessibility. On-premises platforms retain relevance in highly regulated sectors requiring data residency. Hybrid models serve enterprises balancing flexibility with internal control.
- For example, cloud-based solutions such as Avalara, Vertex, and TaxCloud dominate due to rapid updates, global scalability, and easy integration with ERP/CRM systems. Companies reduce go-live times from months to just weeks, lower IT infrastructure costs, and ensure continuous access to regulatory updates.
By organization size, large enterprises hold a dominant share due to broader operations and cross-border tax obligations. SMEs are increasingly investing in modular, cloud-first platforms to streamline compliance within budget constraints. The Tax Management Market supports diverse use cases through flexible configurations tailored to evolving business environments.
Segmentation:
By Component
- Software
- Services
By Tax Type
- Indirect Tax
- Direct Tax
By Vertical
- Banking, Financial Services and Insurance (BFSI)
- Information Technology (IT) and Telecom
- Manufacturing
- Energy and Utilities
- Retail
- Healthcare and Life Sciences
- Media and Entertainment
- Others
By Deployment
- On-premises
- Cloud
- Hybrid
By Organization Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Regional Analysis:
North America
The North America Tax Management Market size was valued at USD 6,826.03 million in 2018 to USD 8,317.47 million in 2024 and is anticipated to reach USD 13,489.31 million by 2032, at a CAGR of 6.3% during the forecast period. North America accounted for 36.82% of the global market in 2024. It maintains its leadership position due to a mature regulatory environment and early adoption of digital tax technologies. The U.S. dominates the region with strong enterprise demand for integrated tax compliance platforms. Increasing complexity in federal and state-level tax codes pushes companies to invest in scalable solutions. Cloud-native platforms and AI-powered compliance tools are gaining traction across large corporations. The region also witnesses a shift toward predictive analytics and real-time tax visibility. Strong presence of key tax technology vendors supports innovation and competitive pricing. North America continues to serve as the benchmark for tax modernization initiatives worldwide.
Europe
The Europe Tax Management Market size was valued at USD 4,851.14 million in 2018 to USD 5,750.77 million in 2024 and is anticipated to reach USD 8,841.90 million by 2032, at a CAGR of 5.6% during the forecast period. Europe represented 25.47% of the global market in 2024. The region benefits from stringent VAT compliance laws and growing e-invoicing mandates across EU member states. Countries such as Germany, France, and the UK are leading adoption of automated tax filing systems. Enterprises seek platforms that can address frequent updates in VAT, SAF-T, and other digital reporting obligations. It drives investment in multi-country compliance tools that support audit-readiness and data harmonization. The market also shows rising demand for secure, GDPR-compliant cloud platforms. Regulatory pressure is a key catalyst in pushing digital transformation across tax functions. Europe remains a highly structured market focused on control, transparency, and compliance assurance.
Asia Pacific
The Asia Pacific Tax Management Market size was valued at USD 4,638.62 million in 2018 to USD 5,964.77 million in 2024 and is anticipated to reach USD 10,590.27 million by 2032, at a CAGR of 7.5% during the forecast period. Asia Pacific held a 26.40% share of the global market in 2024. Rapid economic development and digitization in China, India, and Southeast Asia are driving growth. Governments in the region are introducing e-filing and e-invoicing frameworks to improve compliance and revenue collection. Businesses are adopting modern tax platforms to manage multi-layered GST, VAT, and service tax structures. It supports automation in a region marked by high transaction volumes and diverse regulatory landscapes. SMEs and large enterprises alike are seeking cloud-based, mobile-accessible tax solutions. Domestic and multinational companies are investing in tools that localize tax rules while offering global scalability. The region presents high potential for vendors offering adaptable and affordable solutions.
Latin America
The Latin America Tax Management Market size was valued at USD 1,044.24 million in 2018 to USD 1,273.84 million in 2024 and is anticipated to reach USD 1,906.56 million by 2032, at a CAGR of 5.3% during the forecast period. Latin America captured 5.64% of the global market share in 2024. The region is experiencing steady digital transformation in tax compliance driven by government mandates. Brazil and Mexico are at the forefront with compulsory electronic invoicing and digital bookkeeping regulations. Businesses require tax engines capable of adapting to frequent tax rule modifications and real-time reporting. The Tax Management Market supports this evolution by offering tools that simplify documentation, reconciliation, and audit preparation. Growth remains concentrated among mid-sized companies and multinational firms operating in complex tax regimes. Local regulatory volatility increases demand for flexible platforms that respond to shifting compliance environments. Vendor partnerships with local service providers enhance implementation success.
Middle East
The Middle East Tax Management Market size was valued at USD 696.16 million in 2018 to USD 804.05 million in 2024 and is anticipated to reach USD 1,180.09 million by 2032, at a CAGR of 5.0% during the forecast period. The Middle East accounted for 3.56% of the global market share in 2024. Introduction of VAT across Gulf Cooperation Council (GCC) countries has reshaped the tax compliance landscape. Enterprises are now required to maintain electronic records, file digital returns, and manage periodic audits. The Tax Management Market in the region is expanding as businesses adapt to newly enforced reporting obligations. Demand is rising for ERP-integrated platforms that offer localized compliance features. UAE and Saudi Arabia are driving the most significant adoption, supported by government-backed digital transformation agendas.
Africa
The Africa Tax Management Market size was valued at USD 263.81 million in 2018 to USD 479.00 million in 2024 and is anticipated to reach USD 748.48 million by 2032, at a CAGR of 5.5% during the forecast period. Africa contributed 2.12% to the global market in 2024. The region is in the early stages of tax digitization, with several countries initiating electronic filing and invoice digitization projects. South Africa, Nigeria, and Kenya are leading efforts to modernize tax collection and reduce evasion. Businesses face challenges related to infrastructure and system interoperability, prompting demand for flexible, cloud-hosted tax solutions. The Tax Management Market is gradually gaining momentum with increasing awareness and regulatory support. It is driven by a need for transparency and accountability in public finance systems. Multinational corporations and development finance-backed initiatives are helping drive technology adoption. Growth potential is high, though market maturity remains uneven across countries.
Key Player Analysis:
- Aldrich Services LLP
- Anrok, Inc.
- Asure Software, Inc.
- Avalara, Inc.
- Avantax, Inc.
- Canopy Tax, Inc.
- Crowe LLP
- Drake Software, LLC
- Ernst & Young Global Limited
- Global Tax Management, Inc.
- HRB Digital LLC
- Intuit, Inc.
- Jackson Hewitt Tax Service Inc.
- JPMorgan Chase & Co.
- KPMG International Limited
- PricewaterhouseCoopers LLP (PwC)
- Quaderno
- Sage Group PLC
- SAP SE
- Tax Management Associates, Inc.
- Taxback International
- TaxCloud (The Federal Tax Authority, LLC)
- TaxSlayer LLC
- Thomson Reuters Corporation
- Vertex, Inc.
Competitive Analysis:
The Tax Management Market features a moderately concentrated competitive landscape dominated by global players such as Thomson Reuters, Wolters Kluwer, SAP, Oracle, and Intuit. These companies maintain strong portfolios through continuous software innovation, regulatory content integration, and global reach. They compete on scalability, automation, and compliance adaptability across diverse tax jurisdictions. Regional players and niche providers offer customized solutions targeting SMEs and local markets. The market favors vendors that can deliver seamless ERP integration and cloud-based architecture. Strategic partnerships, acquisitions, and product enhancements define competitive positioning. It rewards firms that invest in AI-driven tax intelligence and real-time analytics. Competitive intensity is rising as businesses prioritize digitized and unified tax solutions.
Recent Developments:
- In May 2025, IRIS Software Group made a strategic minority investment in Instead, an AI-powered tax platform. The collaboration supports Instead’s mission to automate over 90% of tax preparation workflows and enhance strategic advisory delivery. IRIS will work closely with Instead to accelerate product development and extend sales and marketing capabilities across the U.S.
- In June 2025, RSM US, one of the top five U.S. accounting firms, launched its in-house AI-driven tax platform, myRSM Tax. It integrates generative AI into core tax workflows to automate tasks, improve compliance, and empower professionals with real-time insights and secure portals. The platform reflects RSM’s $1 billion multi-year AI investment strategy.
Market Concentration & Characteristics:
The Tax Management Market demonstrates moderate to high concentration with a mix of multinational software providers and emerging regional vendors. It exhibits characteristics such as high compliance dependency, rapid regulatory adaptation, and demand for seamless system interoperability. It emphasizes accuracy, audit-readiness, and scalability across varied tax regimes. Cloud deployment and subscription pricing models are reshaping solution delivery. Market players differentiate through user interface design, localization capabilities, and support services. Integration with ERP and finance ecosystems is a key buying criterion. Innovation in automation, AI, and real-time data handling continues to shape the market’s competitive and functional landscape
Report Coverage:
The research report offers an in-depth analysis based on Component, Tax Type, Vertical, Deployment and Organization Size. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- AI-driven tax platforms will enhance predictive compliance and minimize human intervention.
- Cloud-based solutions will dominate deployments due to scalability and regulatory agility.
- Real-time tax analytics will become central to strategic financial planning.
- Integration with ERP, CRM, and procurement systems will drive platform interoperability.
- Emerging economies will witness rapid adoption fueled by tax digitization reforms.
- Cross-border e-commerce growth will increase demand for multi-jurisdictional compliance tools.
- Blockchain will gain traction in ensuring secure and tamper-proof tax documentation.
- Demand for SaaS-based offerings will rise among mid-sized and decentralized enterprises.
- Vendors will focus on delivering modular, localized solutions for diverse regulatory needs.
- Regulatory pressure and transparency mandates will continue to reshape market dynamics.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Regulatory Complexity
Frequent changes and increasing complexity in tax regulations across jurisdictions are compelling businesses to adopt advanced tax management solutions that can automate compliance, minimize audit risks, and ensure timely filings.
Digitalization of Tax Processes
Government mandates for electronic invoicing and digital tax filings are driving enterprises to integrate tax management software with core business systems, enabling automation, real-time reporting, and improved operational efficiency.
Growth in Cross-Border Transactions
The surge in international trade, e-commerce, and global supply chains is increasing the need for tax management platforms that can handle multi-jurisdictional compliance, VAT/GST management, and prevent double taxation.
Focus on Risk Management and Audit Readiness
Organizations are investing in tax management platforms that provide audit trails, version controls, and analytics to strengthen internal controls, reduce compliance risk, and streamline responses to tax authority queries.
Adoption of Cloud and AI-Driven Solutions
The shift toward cloud-based and AI-enabled tax platforms is enabling businesses to scale quickly, access real-time regulatory updates, and leverage predictive analytics for smarter, more agile tax compliance.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Tax Management Market?
What factors are driving the growth of the Tax Management Market?
What are the key segments within the Tax Management Market?
What are some challenges faced by the Tax Management Market?
Who are the major players in the Tax Management Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Tax Type
- 1.2.1 Indirect Tax
- 1.2.2 Direct Tax
- 1.3 By Vertical
- 1.3.1 Banking, Financial Services and Insurance (BFSI)
- 1.3.2 Information Technology (IT) and Telecom
- 1.3.3 Manufacturing
- 1.3.4 Retail
- 1.3.5 Healthcare and Life Sciences
- 1.4 By Component
- 1.4.1 Software
- 1.4.2 Services
- 1.5 By Deployment
- 1.5.1 Cloud
- 1.5.2 On-premises
- 1.5.3 Hybrid
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 18,320.00 million → 2032: USD 36,756.61 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Tax Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Tax Management Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Tax Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Tax Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Tax Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Tax Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Tax Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Tax Management Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 18,320.00 million → 2032: USD 36,756.61 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Tax Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Tax Type - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Base-Year Market Share, 2018
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Indirect Tax
- 12.3.6.2 Direct Tax
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Vertical - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Base-Year Market Share, 2018
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Banking, Financial Services and Insurance (BFSI)
- 12.4.6.2 Information Technology (IT) and Telecom
- 12.4.6.3 Manufacturing
- 12.4.6.4 Retail
- 12.4.6.5 Healthcare and Life Sciences
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Component - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Base-Year Market Share, 2018
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Software
- 12.5.6.2 Services
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Deployment - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Base-Year Market Share, 2018
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Cloud
- 12.6.6.2 On-premises
- 12.6.6.3 Hybrid
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Tax Management End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Tax Management Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Tax Management Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2018-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Tax Management Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Thomson Reuters Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 SAP SE
- 18.4 Intuit, Inc.
- 18.5 Avalara, Inc.
- 18.6 Vertex, Inc.
- 18.7 KPMG International Limited
- 18.8 PricewaterhouseCoopers LLP (PwC)
- 18.9 Wolters Kluwer N.V.
- 18.10 TaxCloud (The Federal Tax Authority, LLC)
- 18.11 Ernst & Young Global Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

