
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Vaginal Slings Market Size 2024 | USD 1,969.34 million |
| Vaginal Slings Market, CAGR | 5.10% |
| Vaginal Slings Market Size 2032 | USD 2,926.78 million |
Market Overview
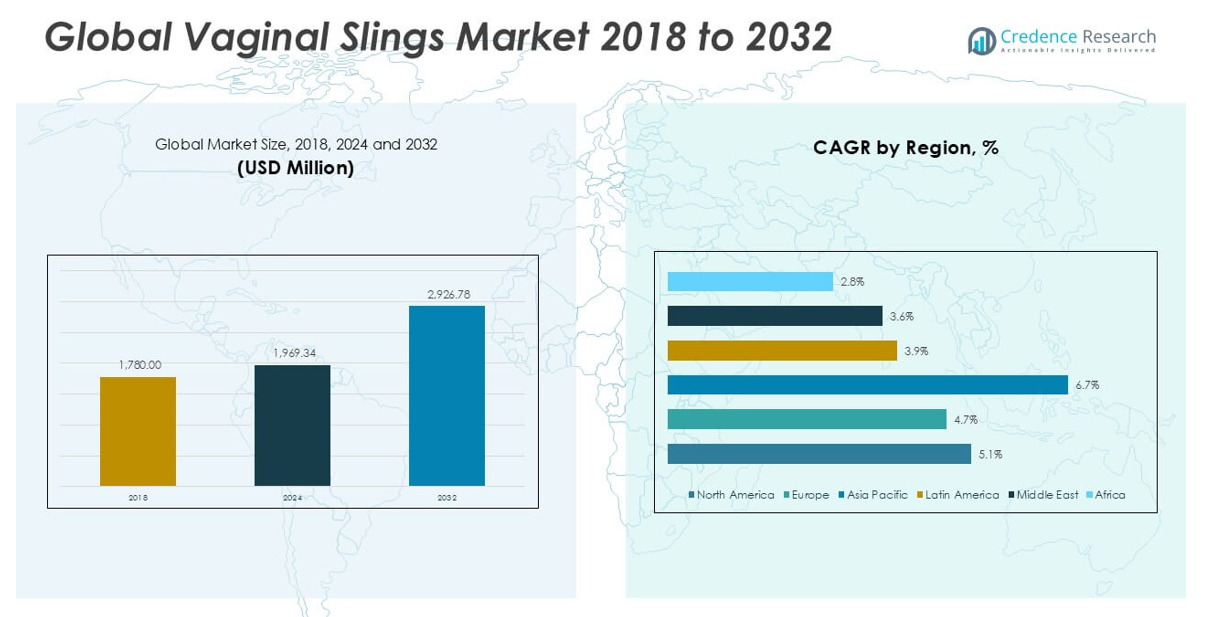
The Vaginal Slings market size was valued at USD 1,780.00 million in 2018, reached USD 1,969.34 million in 2024, and is anticipated to reach USD 2,926.78 million by 2032, at a CAGR of 5.10% during the forecast period.
The vaginal slings market is led by prominent players such as Boston Scientific Corporation, Coloplast Corp, Johnson & Johnson Services, Inc., Promedon S.A., and A.M.I. GmbH, who collectively drive innovation and expansion through advanced product development and strategic partnerships. These companies focus on enhancing sling efficacy and patient safety while expanding their global footprint. Regionally, Europe commands the largest market share at approximately 45.2%, supported by advanced healthcare infrastructure and high adoption rates. North America follows with a 25.4% share, benefiting from favorable reimbursement policies and strong clinical adoption. Asia Pacific is emerging rapidly, holding around 18.7% of the market, fueled by increasing healthcare investments and growing awareness. Together, these regions represent the majority of the global vaginal slings market, reflecting both mature and high-growth opportunities for leading manufacturers.
Market Insights
- The vaginal slings market was valued at USD 1,969.34 million in 2024 and is projected to reach USD 2,926.78 million by 2032, growing at a CAGR of 5.10%.
- Rising prevalence of stress urinary incontinence among women and advancements in minimally invasive sling procedures are driving market growth globally.
- Increasing adoption of tension-free vaginal tape slings and midurethral slings, which together hold the majority market share, reflects the trend toward safer and more effective treatments.
- Competitive landscape is dominated by key players like Boston Scientific, Coloplast, and Johnson & Johnson, who focus on innovation and expanding their regional presence, especially in North America and Europe.
- Market growth is restrained by post-surgical complications concerns and regulatory challenges, particularly affecting adoption rates in emerging regions like Africa and the Middle East, where market shares remain comparatively lower.
Market Segmentation Analysis:
By Product:
In the vaginal slings market, the Tension-Free Vaginal Tape (TVT) Slings segment holds the dominant share, accounting for approximately 45-50% of the market in 2024. This dominance is driven by their high success rates, minimally invasive procedure, and shorter recovery times compared to other options. TVT slings are widely preferred by healthcare providers due to their proven long-term efficacy in treating stress urinary incontinence. Additionally, the increasing adoption of tension-free techniques by surgeons and the growing awareness among patients about the benefits of these slings contribute significantly to the segment’s growth.
- For instance, Boston Scientific’s TVT Exact system has reported a 90% success rate at 5 years post-operation in clinical studies involving over 600 patients worldwide.
By Type
The Midurethral Sling segment leads the market, capturing around 60-65% of the market share in 2024. This dominance is attributed to its status as the gold standard in surgical treatment for female stress urinary incontinence, offering high effectiveness and low complication rates. The growing number of minimally invasive procedures and increasing clinical recommendations for midurethral slings further support this segment’s expansion. The preference for these slings is also influenced by their reduced operative time, faster patient recovery, and widespread availability, which continue to drive steady demand in hospitals and outpatient surgical centers.
- For instance, Coloplast’s SPARC midurethral sling has been utilized in over 400,000 procedures globally, with a reported mean operative time under 20 minutes and complication rates below 5% in post-market surveillance data.
By End Use
Among end users, Hospitals dominate the vaginal slings market, holding approximately 50-55% of the market share in 2024. The leading position of hospitals is primarily driven by the availability of skilled surgeons, advanced surgical infrastructure, and comprehensive post-operative care. Hospitals are typically the first choice for complex or inpatient procedures, which supports the segment’s growth. Additionally, increasing hospital admissions for pelvic floor disorders and the rising number of gynecological surgeries contribute to the growing demand for vaginal slings in hospital settings, reinforcing their market leadership.
Market Overview
Increasing Prevalence of Stress Urinary Incontinence
The rising global prevalence of stress urinary incontinence (SUI), particularly among aging women, is a major driver for the vaginal slings market. Factors such as obesity, childbirth, and menopause significantly contribute to the increasing incidence of pelvic floor disorders. This growing patient pool creates consistent demand for effective and minimally invasive treatments like vaginal slings. As awareness regarding urinary incontinence management improves, more women are seeking medical solutions, thereby boosting the adoption of sling procedures across hospitals, clinics, and ambulatory surgical centers worldwide.
- For instance, Johnson & Johnson’s Ethicon unit has expanded its pelvic health division to perform over 50,000 sling procedures annually, reflecting rising clinical demand linked to SUI prevalence.
Advancements in Minimally Invasive Surgical Techniques
Technological advancements in minimally invasive procedures have significantly accelerated the adoption of vaginal slings. Modern sling systems now offer improved biocompatibility, reduced operative times, and faster patient recovery. Surgeons increasingly prefer tension-free vaginal tape (TVT) and midurethral slings due to their proven safety and efficacy. Additionally, advancements in materials and surgical tools enable better procedural outcomes with lower complication rates. This technological progression not only enhances patient satisfaction but also encourages healthcare providers to adopt sling procedures as a primary solution for urinary incontinence.
- For instance, A.M.I. GmbH introduced the DynaMesh® SIS sling made from ultra-lightweight polypropylene mesh with a pore size of 2.2 mm, reducing post-operative inflammation by 35% compared to conventional mesh in clinical trials involving 150 patients.
Growing Geriatric Population
The expanding global geriatric population is a crucial growth driver for the vaginal slings market. Elderly individuals are more prone to stress urinary incontinence due to weakened pelvic muscles and age-related changes. As life expectancy rises, particularly in developed regions, the demand for effective long-term solutions like vaginal slings continues to grow. Healthcare systems are increasingly focusing on elderly care, driving investments in urinary incontinence treatments. This demographic trend ensures sustained demand for vaginal slings, positioning the market for steady long-term growth.
Key Trends & Opportunities
Rising Preference for Ambulatory Surgical Centers
A notable trend in the vaginal slings market is the growing preference for ambulatory surgical centers (ASCs) for sling procedures. ASCs offer benefits such as reduced costs, faster patient turnover, and shorter waiting times compared to hospitals. Patients increasingly opt for these centers due to the minimally invasive nature of sling surgeries, which often require same-day discharge. This shift is creating opportunities for device manufacturers to develop sling systems specifically tailored for outpatient settings, enhancing the accessibility and affordability of treatment.
- For instance, Promedon S.A. has developed the Monarc® transobturator sling designed for outpatient use, with an average surgery duration of 15 minutes and discharge rates exceeding 90% within 4 hours post-operation.
Increasing Focus on Patient-Centric Innovations
Manufacturers are actively focusing on developing patient-centric sling systems with enhanced comfort, adjustability, and long-term durability. The demand for personalized medical devices that cater to individual anatomical variations is gaining traction, presenting new opportunities for product innovation. Companies are exploring lightweight, biocompatible materials and customizable sling designs to improve patient outcomes and reduce post-operative complications. This trend not only differentiates brands but also aligns with the broader movement toward precision medicine, offering a competitive edge in the growing market.
- For instance, Caldera Medical’s AdjustaTight® sling features an adjustable mechanism allowing intraoperative tension customization, used in over 5,000 cases with documented reductions in reoperation rates by 20% compared to fixed-tension slings.
Key Challenges
Concerns Regarding Post-Surgical Complications
Despite advancements, the vaginal slings market faces significant challenges related to post-surgical complications, including mesh erosion, pain, and infection. These concerns have led to regulatory scrutiny and cautious adoption among some healthcare providers and patients. Negative publicity surrounding mesh-related lawsuits in the past has also impacted patient confidence. Addressing these safety concerns requires stringent quality controls, enhanced physician training, and the development of safer sling materials, which can add to manufacturing costs and lengthen approval timelines.
Regulatory Barriers and Product Recalls
Stringent regulatory frameworks governing the approval of vaginal sling devices present a major hurdle for market participants. Regulatory authorities in the U.S. and Europe have imposed strict guidelines to ensure patient safety, which can delay product launches and limit market entry for smaller players. Additionally, historical product recalls due to safety issues have increased compliance pressures on manufacturers. These barriers can constrain market growth by reducing the speed at which new and innovative sling systems reach the market.
Limited Access in Low-Income Regions
The adoption of vaginal sling procedures remains limited in low- and middle-income countries due to factors such as lack of awareness, high procedural costs, and limited access to trained specialists. In many developing regions, urinary incontinence is underdiagnosed and often untreated due to social stigma and poor healthcare infrastructure. This restricted accessibility poses a considerable challenge for manufacturers seeking to expand their presence globally. Overcoming this issue will require targeted awareness programs and cost-effective solutions tailored for emerging markets.
Regional Analysis
North America
North America accounted for a significant portion of the vaginal slings market, valued at USD 452.12 million in 2018, representing approximately 25.4% market share. The market is projected to grow steadily, reaching USD 491.54 million in 2024 and USD 729.07 million by 2032, with a CAGR of 5.1%. Growth is driven by rising awareness of stress urinary incontinence, increasing healthcare infrastructure, and widespread adoption of minimally invasive procedures. The presence of leading manufacturers and favorable reimbursement policies further support market expansion across the United States and Canada.
Europe
Europe held the largest share in 2018, valued at USD 804.56 million, accounting for about 45.2% of the global vaginal slings market. The region is expected to grow moderately, reaching USD 870 million in 2024 and USD 1,251.94 million by 2032, at a CAGR of 4.7%. Growth is driven by increasing prevalence of pelvic floor disorders, technological advancements in sling devices, and improved healthcare access in Western Europe. Regulatory support and rising geriatric populations across key countries such as Germany, France, and the UK also contribute to sustained demand.
Asia Pacific
Asia Pacific showed strong growth potential with a market size of USD 333.75 million in 2018, holding roughly 18.7% of the global market. The market is anticipated to expand to USD 390.61 million by 2024 and USD 657.94 million by 2032, growing at the highest CAGR of 6.7%. Increasing healthcare investments, improving awareness about urinary incontinence, and expanding geriatric populations in China, India, and Japan drive growth. Additionally, expanding medical infrastructure and rising affordability of surgical procedures fuel the region’s dynamic market development.
Latin America
Latin America’s vaginal slings market was valued at USD 88.64 million in 2018, representing about 5% of the global market share. It is expected to grow gradually to USD 96.87 million in 2024 and USD 130.74 million by 2032, at a CAGR of 3.9%. Growth is supported by improving healthcare infrastructure, growing female population awareness, and increasing urbanization in countries like Brazil and Mexico. However, cost sensitivity and limited access to advanced healthcare services moderate the market expansion pace.
Middle East
The Middle East market was valued at USD 61.41 million in 2018, accounting for roughly 3.5% of the global vaginal slings market. It is projected to grow to USD 63.20 million in 2024 and USD 83.72 million by 2032, with a CAGR of 3.6%. Market growth is driven by increasing healthcare investments, rising awareness of pelvic floor health, and improved access to surgical treatments in GCC countries. However, geopolitical tensions and variable healthcare infrastructure across countries present challenges to faster adoption.
Africa
Africa’s vaginal slings market was valued at USD 39.52 million in 2018, representing approximately 2.2% of the global market share. The region is expected to reach USD 57.12 million in 2024 and USD 73.37 million by 2032, growing at a CAGR of 2.8%. Growth is constrained by limited healthcare infrastructure, low awareness, and affordability challenges. However, increasing government focus on women’s health and expanding medical facilities in countries such as South Africa and Nigeria offer growth opportunities, albeit at a slower pace compared to other regions.
Market Segmentations:
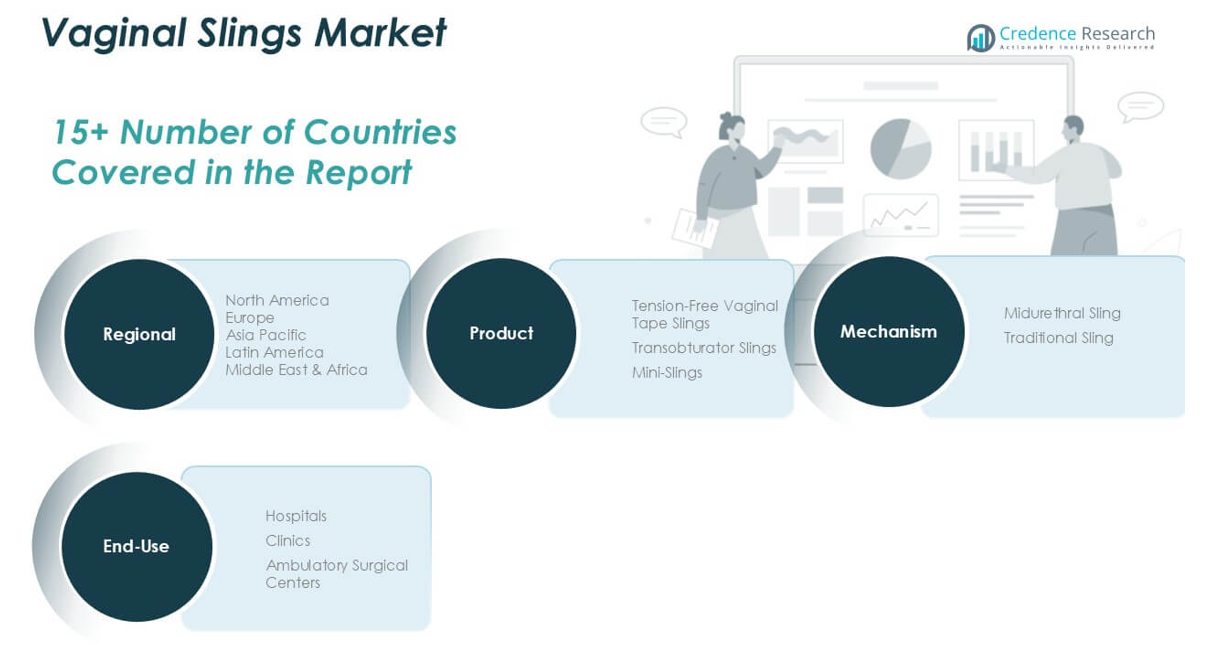
By Product
- Tension-Free Vaginal Tape Slings
- Transobturator Slings
- Mini-Slings
By Type
- Midurethral Sling
- Traditional Sling
By End Use
- Hospitals
- Clinics
- Ambulatory Surgical Centers
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the vaginal slings market is marked by the presence of several leading global and regional players focusing on innovation, strategic partnerships, and geographic expansion to strengthen their market positions. Key companies such as Boston Scientific Corporation, Coloplast Corp, and Johnson & Johnson Services, Inc. dominate through robust product portfolios, continuous R&D investment, and extensive distribution networks. These players emphasize developing advanced sling materials and minimally invasive technologies to enhance patient outcomes and safety. Additionally, mid-sized and emerging companies like Promedon S.A. and A.M.I. GmbH are actively expanding their market share by targeting niche segments and emerging economies. Competitive strategies also include mergers, acquisitions, and collaborations with healthcare providers to improve product accessibility and broaden clinical applications. The increasing emphasis on regulatory compliance and post-market surveillance further drives companies to innovate responsibly while addressing safety concerns. Overall, the market remains highly competitive with ongoing efforts to meet evolving clinical needs and improve patient-centric solutions.
Key Player Analysis
- Boston Scientific Corporation
- Coloplast Corp
- Promedon S.A.
- A.M.I. GmbH
- Johnson & Johnson Services, Inc.
- Betatech Medica
- Caldera Medical
- Neomedic International
- Cousin Surgery
- Lotus Surgicals
- UroCure
Recent Developments
- In March 2024, the FDA approved Y2ni.Fit Bladder Support, a vaginal insert for adult patients with stress urinary incontinence (SUI).
- In January 2024, UroCure and LiNA Medical U.S. launched two new surgical solutions for female stress urinary incontinence nationwide. This product launch may enable the company to improve its product portfolio and industry position in the country.
- In May 2023, Caldera Medical, a company of PlantTec Medical, introduced polysaccharide-based product 4DRYFIELD to effectively stop bleeding and prevent postoperative tissue adhesions in surgeries including vaginal sling procedures.
- In February 2022, Agency for Medical Innovation (AMI) was purchased by Evoco, a biotechnology business with US headquarters, for an unknown sum. Evoco collaborates closely with the present management team and is looking to maximize value creation potential with this acquisition. Manufacturer of vaginal slings Agency for Medical Innovation is situated in Austria.
Market Concentration & Characteristics
The Vaginal Slings Market exhibits a moderately concentrated structure, dominated by a few leading global players who hold significant market shares. Companies such as Boston Scientific Corporation, Coloplast Corp, and Johnson & Johnson Services, Inc. drive innovation through continuous investment in research and development, focusing on enhancing product safety, efficacy, and minimally invasive technologies. The market features high entry barriers due to stringent regulatory requirements, complex clinical validation processes, and the need for specialized manufacturing capabilities. It operates in a competitive environment where product differentiation relies heavily on material innovation, surgical outcomes, and physician preference. Regional disparities exist, with North America and Europe commanding the largest shares due to advanced healthcare infrastructure, higher patient awareness, and well-established reimbursement systems. Emerging markets in Asia Pacific, Latin America, and the Middle East show increasing adoption rates fueled by expanding healthcare access and rising awareness of urinary incontinence treatments. However, these regions face challenges such as limited infrastructure and cost sensitivity. The market also contends with safety concerns related to post-operative complications, influencing product development and regulatory scrutiny. Overall, the Vaginal Slings Market balances technological advancement and regulatory compliance while expanding into new geographies, maintaining steady growth driven by evolving patient needs and clinical practice trends.
Report Coverage
The research report offers an in-depth analysis based on Product, Type, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The vaginal slings market will continue to grow steadily driven by rising prevalence of stress urinary incontinence worldwide.
- Increasing adoption of minimally invasive surgical techniques will boost demand for advanced sling products.
- Technological innovations in sling materials will enhance patient comfort and reduce complication rates.
- Expansion of healthcare infrastructure in emerging economies will create new market opportunities.
- Growing awareness and diagnosis of pelvic floor disorders will increase the number of treated cases.
- Regulatory agencies will enforce stricter safety standards, prompting product improvements.
- Ambulatory surgical centers will become preferred settings for sling procedures due to cost efficiency.
- Manufacturers will focus on developing customizable sling solutions tailored to individual patient needs.
- Rising geriatric population will significantly contribute to market growth globally.
- Collaborations between device makers and healthcare providers will improve market penetration and patient outcomes.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Stress Urinary Incontinence
The increasing incidence of stress urinary incontinence, particularly among aging women and those affected by obesity, childbirth, and menopause, is driving demand for effective and minimally invasive treatments like vaginal slings.
Advancements in Minimally Invasive Surgical Techniques
Technological improvements in sling materials and surgical procedures have led to safer, faster, and more effective treatments, encouraging both surgeons and patients to prefer vaginal sling procedures over traditional methods.
Growing Geriatric Population
As the global population ages, the prevalence of pelvic floor disorders rises, resulting in sustained demand for long-term solutions such as vaginal slings, especially in developed regions with higher life expectancy.
Expansion of Healthcare Infrastructure in Emerging Markets
Increasing investments in healthcare facilities and rising awareness about urinary incontinence in Asia Pacific and Latin America are expanding access to sling procedures, fueling market growth in these high-potential regions.
Shift Toward Ambulatory Surgical Centers
The trend toward performing sling procedures in ambulatory surgical centers, which offer cost efficiency and faster patient turnover, is increasing the accessibility and affordability of these treatments, further boosting market adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Vaginal Slings Market?
What are the key segments within the Vaginal Slings Market?
What are some challenges faced by the Vaginal Slings Market?
Who are the major players in the Vaginal Slings Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Midurethral Sling
- 1.2.2 Traditional Sling
- 1.3 By End Use
- 1.3.1 Hospitals
- 1.3.2 Clinics
- 1.3.3 Ambulatory Surgical Centers
- 1.4 By Product
- 1.4.1 Tension-Free Vaginal Tape Slings
- 1.4.2 Transobturator Slings
- 1.4.3 Mini-Slings
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,969.34 million → 2032: USD 2,926.78 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Vaginal Slings Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Vaginal Slings Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Vaginal Slings Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Vaginal Slings Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Vaginal Slings Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Vaginal Slings Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Vaginal Slings Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Vaginal Slings Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,969.34 million → 2032: USD 2,926.78 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Vaginal Slings Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Midurethral Sling
- 12.3.7.2 Traditional Sling
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Clinics
- 12.4.7.3 Ambulatory Surgical Centers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Tension-Free Vaginal Tape Slings
- 12.5.7.2 Transobturator Slings
- 12.5.7.3 Mini-Slings
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Vaginal Slings End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Vaginal Slings Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Vaginal Slings Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Vaginal Slings Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Boston Scientific Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Coloplast Corp
- 18.4 Johnson & Johnson Services, Inc.
- 18.5 Promedon S.A.
- 18.6 A.M.I. GmbH
- 18.7 Caldera Medical
- 18.8 Neomedic International
- 18.9 Cousin Surgery
- 18.10 Lotus Surgicals
- 18.11 UroCure
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

