
Market Overview:
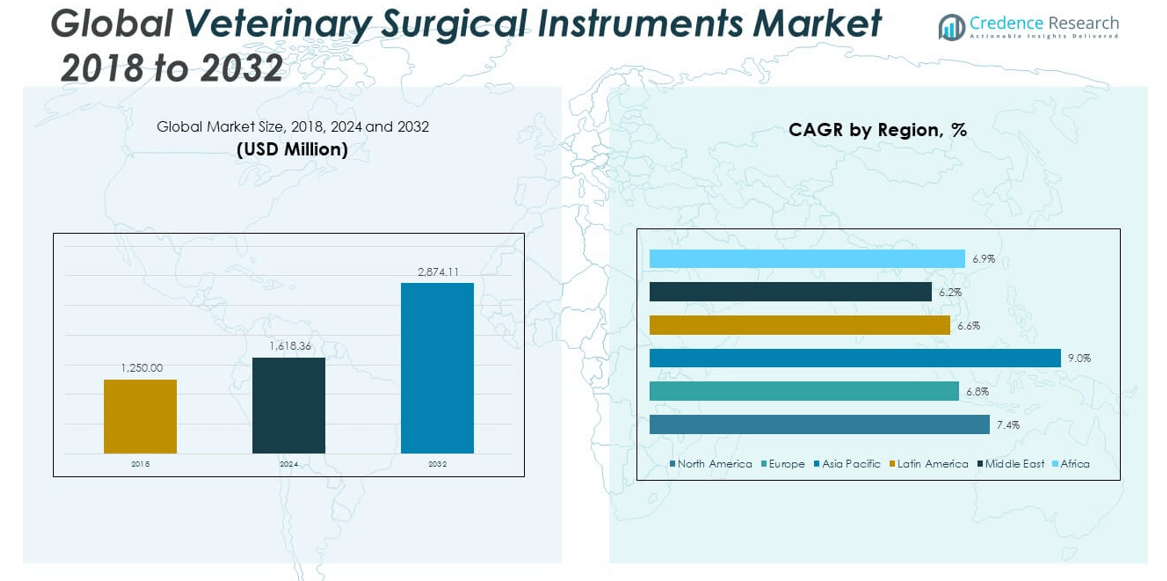
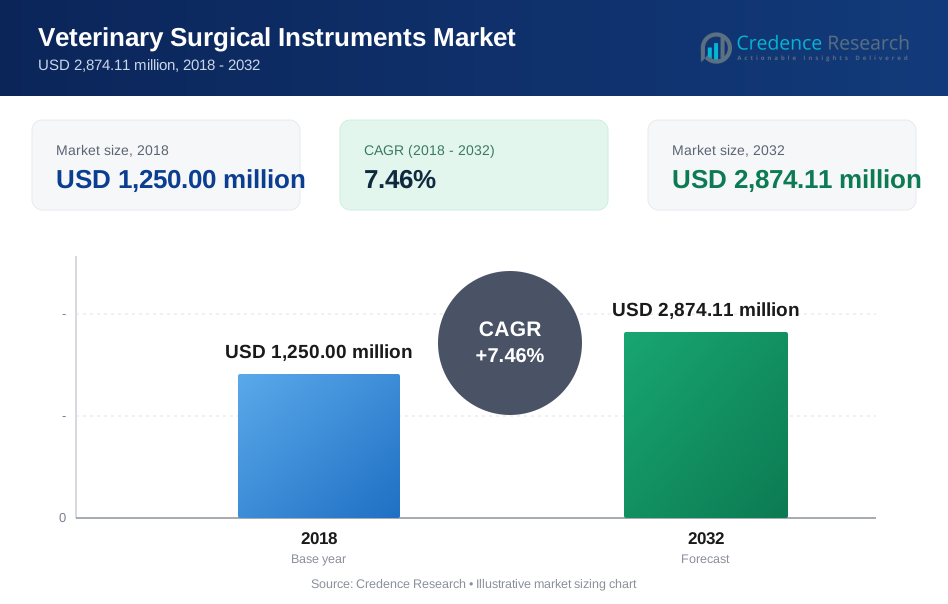
The Veterinary Surgical Instruments Market size was valued at USD 1,250.00 million in 2018 to USD 1,618.36 million in 2024 and is anticipated to reach USD 2,874.11 million by 2032, at a CAGR of 7.46% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Veterinary Surgical Instruments Market Size 2024 | USD 1,618.36 million |
| Veterinary Surgical Instruments Market, CAGR | 7.46% |
| Veterinary Surgical Instruments Market Size 2032 | USD 2,874.11 million |
The market is experiencing sustained growth due to increasing pet ownership, heightened awareness of animal health, and a rise in veterinary surgeries for both companion and livestock animals. Technological advancements in surgical procedures and the growing adoption of minimally invasive techniques have fueled demand for precision instruments. Furthermore, the increasing prevalence of chronic diseases in animals and the rising focus on veterinary infrastructure development are driving consistent investment in advanced surgical equipment across veterinary clinics and hospitals.
North America leads the veterinary surgical instruments market due to a well-established veterinary care infrastructure, high pet adoption rates, and strong expenditure on animal health. Europe follows closely, supported by growing animal welfare initiatives and veterinary regulations. Meanwhile, the Asia-Pacific region is emerging as a high-growth market, driven by the expanding livestock industry, increasing pet ownership in urban centers, and rising disposable incomes in countries such as China, India, and Australia. These dynamics are encouraging market players to invest in product availability, training, and localized manufacturing across emerging regions.
Market Insights:
- The Veterinary Surgical Instruments Market was valued at USD 1,250.00 million in 2018, reached USD 1,618.36 million in 2024, and is projected to grow to USD 2,874.11 million by 2032, at a CAGR of 7.46%.
- Increasing pet ownership and growing awareness of animal healthcare are accelerating demand for surgical interventions in both companion and livestock animals.
- Technological advancements in surgical tools, including electrosurgery and ergonomic handheld instruments, are driving precision and efficiency in veterinary procedures.
- High cost of advanced surgical instruments and limited infrastructure in rural or developing regions are restraining broader adoption.
- North America leads the market due to high veterinary spending and widespread access to specialized care, accounting for nearly 39.76% of global revenue in 2024.
- Asia Pacific is the fastest-growing region, fueled by rising pet adoption, growing livestock sector, and veterinary infrastructure development.
- Regulatory disparities and lack of uniform training standards pose challenges to consistent usage of high-end instruments across global markets.
Market Drivers
Rising Companion Animal Population and Growing Expenditure on Veterinary Care
The growing global pet population directly fuels demand in the Veterinary Surgical Instruments Market. Increasing awareness of pet health among owners is prompting more frequent veterinary visits and surgical procedures. Pet humanization trends are encouraging owners to pursue advanced medical care for animals. This shift is creating a favorable environment for high-quality surgical instruments. It benefits from rising disposable incomes and greater pet insurance penetration in developed regions. Veterinary hospitals are expanding services to accommodate complex surgeries. This development further supports consistent investment in specialized tools. Regulatory improvements in animal care also drive surgical standardization and tool adoption.
Expansion of Veterinary Clinics and Availability of Skilled Professionals
The Veterinary Surgical Instruments Market benefits from the rapid establishment of veterinary clinics and diagnostic centers. A steady increase in the number of trained veterinary professionals is expanding the capacity to conduct surgeries. With better access to qualified veterinarians, more pet owners seek surgical solutions. It experiences strong momentum from institutional support and industry-backed training programs. Countries are investing in veterinary education and surgical skill development. These investments contribute to the widespread use of advanced tools. Urbanization and access to pet care facilities are increasing globally. Rising surgical case volumes demand more efficient and precise instruments across facilities.
- For example, Mars Veterinary Health(operator of VCA, BluePearl, and Banfield hospitals) announced in 2024 that it now operates over 3,000 veterinary hospitals globally, with 250 new clinics opened in the U.S. in the past two years.
Rise in Zoonotic Diseases and Need for Preventive Surgical Interventions
The Veterinary Surgical Instruments Market gains traction from the global focus on controlling zoonotic diseases. Governments are promoting animal sterilization, wound management, and disease-control surgeries. Veterinary professionals conduct more preventive procedures to minimize transmission risks. It grows stronger as public health frameworks encourage structured veterinary care. Regions with high livestock populations are investing in surgical tools to support herd health. Technological improvements make surgeries safer and faster, encouraging adoption in rural settings. This development enhances productivity and disease containment. Efforts to integrate veterinary services into public health systems also increase instrument demand.
- For example, World Health Organization (WHO) 2024 Zoonoses reportdocuments 2,100 zoonotic disease outbreaks globally in 2023, a 25% increase from 2019.
Growing Adoption of Minimally Invasive and Laser-Assisted Surgical Techniques
The Veterinary Surgical Instruments Market is seeing an increase in demand due to the shift toward minimally invasive and precision-guided surgeries. These techniques reduce recovery time and improve outcomes in animal patients. Clinics prefer high-performance instruments that support micro-level accuracy. It gains strength from innovations in endoscopy and laparoscopy. Manufacturers are tailoring tools for compact and multi-functional use. Smaller incisions lead to better healing and lower postoperative care needs. This trend supports demand for customized and ergonomic surgical tools. The appeal of these procedures among pet owners supports long-term market expansion.
Market Trends
Integration of Smart Surgical Devices and Connectivity for Real-Time Monitoring
The Veterinary Surgical Instruments Market is incorporating smart instruments with integrated sensors and wireless data tracking. These tools provide surgeons with real-time feedback during operations. Enhanced visualization tools and digital diagnostics improve surgical decision-making. It benefits from advancements in IoT and wearable devices tailored for animal use. Clinics are adopting systems that sync surgical instruments with patient records. Real-time monitoring enables precision and reduces surgical errors. These trends create a pathway for hybrid tools that combine cutting, cauterization, and monitoring. Software-linked tools are helping streamline surgical workflow in veterinary hospitals.
- For example, Bionet’s VEMO system offers real-time ECG, heart rate (HR), and respiratory rate (RR) monitoring for veterinary applications. It leverages Bluetooth connectivity to an iOS tablet, enabling veterinary caregivers to patch up and monitor an animal continuously for up to 72hr with real-time data tracings.
Customization of Instruments for Species-Specific Surgical Applications
Veterinary practices are increasingly demanding instruments designed for specific animal types and procedures. The Veterinary Surgical Instruments Market is responding with specialized tools for small animals, equines, and exotic pets. It supports veterinarians performing complex procedures on species with unique anatomical structures. Manufacturers are segmenting offerings based on pet type and veterinary specialties. This trend addresses the limitations of one-size-fits-all instruments. Veterinarians benefit from better outcomes and easier procedural handling. These developments are influencing procurement standards in both clinics and academic institutions. Market players are expanding portfolios to cover diverse animal healthcare needs.
- For example, GerVetUSA manufactures surgical instruments using German medical-grade stainless steel, delivering personalized instrument sizing tailored to individual surgeon requirements especially for small animals, exotics, and species with distinct anatomical structures.
Eco-Friendly and Reusable Surgical Instruments Gaining Acceptance
There is a growing preference for sustainable and reusable instruments in the Veterinary Surgical Instruments Market. Healthcare providers are reducing reliance on disposable tools to cut costs and waste. It aligns with global sustainability initiatives across the medical and veterinary sectors. Sterilizable, durable instruments offer long-term cost efficiency. Clinics are revising purchasing models to favor environmentally compliant vendors. This trend is particularly strong in regions with strict waste regulations. Technological advances in materials allow reuse without compromising sterility or performance. Reusable options also appeal to mobile and rural veterinary services with limited supply chains.
Digital Procurement Platforms and E-Commerce Expansion in Equipment Supply
Digital transformation is influencing the distribution and procurement landscape of veterinary surgical instruments. The Veterinary Surgical Instruments Market is seeing increased activity through online platforms and B2B portals. It enables clinics to access global catalogs and pricing transparency. Distributors are using AI-based systems to manage inventory and fulfill custom orders. Small practices gain access to high-grade tools without large-scale contracts. E-commerce supports faster delivery and reduces dependency on regional stockists. This development enhances competitive pricing and supply consistency. Digitally-enabled buying also improves equipment traceability and after-sales service.
Market Challenges Analysis
High Cost of Advanced Surgical Instruments and Budget Limitations in Small Practices
The Veterinary Surgical Instruments Market faces resistance from budget constraints in small and mid-sized veterinary clinics. Many advanced instruments are cost-prohibitive for independent practitioners. It becomes challenging for clinics in developing regions to upgrade to modern surgical tools. Limited reimbursement options for veterinary surgeries exacerbate cost concerns. Procurement delays and inconsistent equipment maintenance raise operational risks. High upfront costs deter frequent upgrades, leading to longer instrument lifecycles. Dependence on imports can inflate prices in countries with weaker currency or higher tariffs. Clinics may opt for substandard alternatives to control costs, impacting patient outcomes. These economic hurdles affect uniform market growth and tool accessibility.
Inconsistent Regulatory Standards and Lack of Uniform Quality Control
The Veterinary Surgical Instruments Market struggles with regulatory fragmentation across regions. Different countries follow varied guidelines for veterinary surgical equipment. It complicates global distribution and compliance for manufacturers. The absence of standardized certifications limits adoption of newer tools. Veterinary associations often lack the authority to enforce uniform quality checks. Disparities in veterinary education also influence how tools are used and maintained. Inadequate training on advanced instruments leads to underutilization or misuse. These gaps create liability issues and slow the pace of innovation adoption. Harmonizing standards across countries remains a persistent challenge.
Market Opportunities
Expansion of Animal Health Infrastructure in Developing Economies
The Veterinary Surgical Instruments Market has strong growth potential in emerging economies. Governments are investing in veterinary hospitals, mobile clinics, and livestock care programs. It supports instrument demand through public tenders and international funding. Rural veterinary outreach programs create recurring needs for surgical kits. NGOs and animal welfare groups promote sterilization and vaccination, increasing surgical volume. Local manufacturing initiatives can reduce import dependency and lower prices. Market players are forming partnerships with regional distributors. The rise in pet ownership in urban centers further strengthens instrument adoption.
Increased Focus on Pet Insurance and Owner Willingness to Opt for Surgery
Growing pet insurance penetration is enabling more owners to consider surgical care for their animals. The Veterinary Surgical Instruments Market stands to benefit from this expanding financial support system. It makes surgeries more affordable and predictable in cost. Insurance providers are aligning with clinics to promote surgical treatment packages. This shift promotes demand for advanced instruments that ensure reliable outcomes. Rising trust in veterinary care contributes to higher acceptance of invasive procedures. Clinics with insured clientele are more likely to invest in high-end equipment. This trend favors long-term demand stability.
Market Segmentation Analysis:
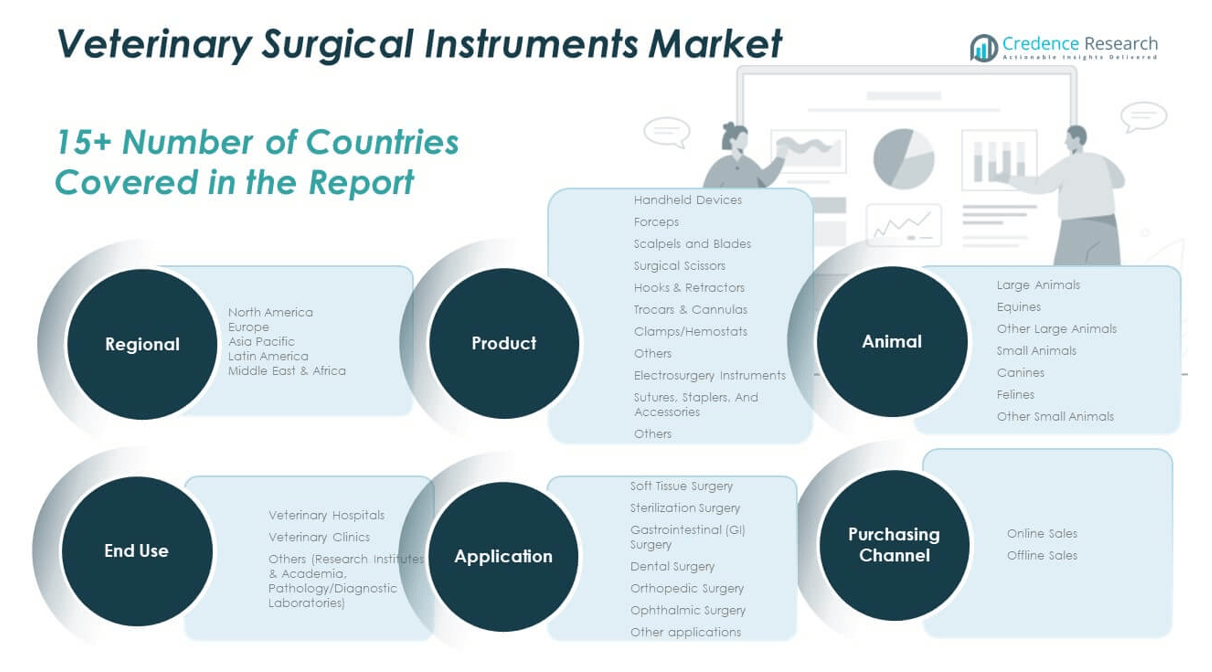
The Veterinary Surgical Instruments Market is segmented by product, application, end-use, animal type, and purchasing channel, each contributing to the market's growth dynamics.
By product, handheld devices dominate due to their widespread use across basic and complex procedures. Subcategories like forceps, scalpels, scissors, retractors, trocars, and hemostats meet varied surgical needs in both small and large animals. Electrosurgery instruments and sutures, staplers, and accessories are gaining traction due to rising adoption of precision and minimally invasive surgeries.
- For example, Jørgen Kruuse is a recognized global provider of veterinary surgical instruments, offering a comprehensive catalog of high-quality handheld tools such as Metzenbaum scissors, Adson forceps, Mayo-Hegar needle holders, and Senn retractors. These instruments are designed for use in both small and large animal surgeries and are widely used in veterinary clinics and hospitals worldwide.
By application, soft tissue and sterilization surgeries generate high demand due to routine preventive care. Orthopedic, dental, gastrointestinal, and ophthalmic procedures are expanding due to improved diagnostics and increased pet lifespan.
- For example, the American Veterinary Medical Association (AVMA) identifies spaying and neutering as some of the most frequent surgeries performed on dogs and cats in the U.S.
By end-use, veterinary hospitals account for the largest share, followed by clinics and research institutes that require advanced tools for specialized care.
By animal, the small animal segment especially canines and felines leads the market due to higher urban pet ownership. Large animals like equines also represent significant demand in agricultural regions.
By purchasing channel, offline sales dominate due to trust in direct suppliers, while online sales are rising through digital platforms offering broader product access and competitive pricing. Each segment drives distinct investment and innovation within the market.
Segmentation:
By Product
- Handheld Devices
- Forceps
- Scalpels and Blades
- Surgical Scissors
- Hooks & Retractors
- Trocars & Cannulas
- Clamps/Hemostats
- Others
- Electrosurgery Instruments
- Sutures, Staplers, and Accessories
- Others
By Application
- Soft Tissue Surgery
- Sterilization Surgery
- Gastrointestinal (GI) Surgery
- Dental Surgery
- Orthopedic Surgery
- Ophthalmic Surgery
- Other Applications
By End-Use
- Veterinary Hospitals
- Veterinary Clinics
- Others (Research Institutes & Academia, Pathology/Diagnostic Laboratories)
By Animal
- Large Animals
- Equines
- Other Large Animals
- Small Animals
- Canines
- Felines
- Other Small Animals
By Purchasing Channel
- Online Sales
- Offline Sales
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The North America Veterinary Surgical Instruments Market size was valued at USD 502.88 million in 2018 to USD 643.93 million in 2024 and is anticipated to reach USD 1,140.13 million by 2032, at a CAGR of 7.4% during the forecast period. North America holds the largest share of the global Veterinary Surgical Instruments Market, accounting for nearly 39.76% in 2024. The region’s strong position is supported by high pet ownership rates, advanced veterinary care infrastructure, and favorable reimbursement frameworks. It benefits from the widespread presence of veterinary clinics and hospitals equipped with state-of-the-art surgical tools. The United States leads in veterinary education, technology adoption, and regulatory compliance. Market players focus on innovation and distribution expansion across the U.S. and Canada. Growth is further fueled by awareness programs promoting preventive and surgical care for animals.
The Europe Veterinary Surgical Instruments Market size was valued at USD 349.00 million in 2018 to USD 435.29 million in 2024 and is anticipated to reach USD 732.76 million by 2032, at a CAGR of 6.8% during the forecast period. Europe represents 26.89% of the Veterinary Surgical Instruments Market in 2024, driven by robust animal welfare regulations and public awareness. Countries like Germany, France, and the UK dominate the regional landscape due to their high veterinary care standards. It sees strong demand for species-specific instruments and minimally invasive surgery kits. The European Union supports pet health initiatives, boosting the demand for surgical procedures. Veterinary universities and training centers enhance surgical proficiency across the region. Clinics prioritize advanced instruments that comply with EU health and safety norms. Emerging Eastern European markets are also witnessing infrastructure development. Europe sustains consistent growth through innovation and standardized practices.
The Asia Pacific Veterinary Surgical Instruments Market size was valued at USD 230.63 million in 2018 to USD 316.14 million in 2024 and is anticipated to reach USD 630.63 million by 2032, at a CAGR of 9.0% during the forecast period. Asia Pacific accounts for 19.53% of the Veterinary Surgical Instruments Market in 2024 and is the fastest-growing region. The expansion of companion animal ownership in urban India, China, and Southeast Asia is reshaping veterinary service demand. It benefits from growing disposable income and awareness of animal health. Governments are increasing investment in veterinary infrastructure and public health campaigns. Veterinary institutions in the region are modernizing, driving the adoption of advanced surgical instruments. Local manufacturers are emerging, reducing dependency on imports and offering cost-effective solutions.
The Latin America Veterinary Surgical Instruments Market size was valued at USD 87.50 million in 2018 to USD 112.30 million in 2024 and is anticipated to reach USD 186.44 million by 2032, at a CAGR of 6.6% during the forecast period. Latin America contributes 6.94% to the Veterinary Surgical Instruments Market in 2024, supported by a growing middle class and increased pet adoption in Brazil, Mexico, and Argentina. It is gaining from gradual modernization of animal health services across both urban and rural zones. Veterinary clinics are adopting surgical tools to expand service offerings. Government-led animal welfare campaigns and mobile veterinary programs boost surgical volume. However, unequal access to advanced veterinary care remains a constraint.
The Middle East Veterinary Surgical Instruments Market size was valued at USD 49.75 million in 2018 to USD 60.52 million in 2024 and is anticipated to reach USD 97.45 million by 2032, at a CAGR of 6.2% during the forecast period. The Middle East holds a 3.74% share of the Veterinary Surgical Instruments Market in 2024. Gulf countries, especially the UAE and Saudi Arabia, are leading in animal healthcare investment. It sees growing interest in veterinary care for companion animals and equines. Veterinary hospitals in urban centers offer advanced surgical capabilities. Governments promote pet ownership and regulate veterinary practices more strictly. Livestock health and food safety initiatives support surgical tool demand in rural regions. Import dependency and regulatory inconsistencies present challenges to expansion.
The Africa Veterinary Surgical Instruments Market size was valued at USD 30.25 million in 2018 to USD 50.18 million in 2024 and is anticipated to reach USD 86.69 million by 2032, at a CAGR of 6.9% during the forecast period. Africa represents 3.10% of the Veterinary Surgical Instruments Market in 2024, with growing momentum in veterinary services. The market is expanding with support from global NGOs and intergovernmental health initiatives. It relies heavily on imports for surgical instruments, especially in Sub-Saharan Africa. Veterinary outreach programs and rural animal health drives create basic tool demand. South Africa leads the regional market with better infrastructure and trained professionals.
Key Player Analysis:
- Braun SE
- Vimian: Movora
- Jørgen Kruuse A/S
- Johnson & Johnson (J&J)
- Avante Animal Health
- Steris
- Medtronic
- Integra LifeSciences
- Arthrex, Inc.
- Jorgensen Laboratories
Competitive Analysis:
The Veterinary Surgical Instruments Market features a competitive landscape with a mix of global and regional players focusing on product innovation, strategic partnerships, and geographic expansion. Leading companies include B. Braun Vet Care, Medtronic, Integra LifeSciences, Smiths Group, and Jørgen Kruuse A/S. These players invest heavily in R&D to develop specialized and ergonomic instruments for both routine and complex procedures. It attracts new entrants offering cost-effective and customized tools for emerging markets. Mergers and acquisitions are shaping the market structure by expanding product portfolios and distribution networks. Companies are also enhancing post-sale support, sterilization solutions, and digital integration. Competitive intensity remains high due to evolving veterinary demands and technological advancements. Manufacturers differentiate by targeting species-specific solutions, sustainability, and multi-functional designs.
Recent Developments:
- In October 2024, Avante Health Solutions entered into an Asset Purchase Agreement with an affiliate of Staple Street Capital, which is set to acquire most of Avante’s assets. This agreement is designed to recapitalize Avante, allowing the company to continue operating and serving the veterinary and broader medical markets with renewed financial strength
Market Concentration & Characteristics:
The Veterinary Surgical Instruments Market is moderately consolidated, with a few dominant players holding a significant share. It is characterized by high product differentiation, a growing focus on minimally invasive tools, and increasing demand for custom instruments. The market caters to both companion animal clinics and large-scale livestock operations. It remains innovation-driven, with recurring investments in materials, design, and automation features. Distribution partnerships and regional customization help players gain competitive advantage. The industry favors firms with strong regulatory compliance and efficient supply chains. Barriers to entry include stringent quality standards and capital-intensive production.
Report Coverage:
The research report offers an in-depth analysis based on product, application, end-use, animal type, and purchasing channel, It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising pet ownership and humanization trends will continue to fuel surgical demand in both developed and emerging economies.
- Increasing preference for minimally invasive and precision-guided surgeries will drive demand for advanced instruments.
- Growing veterinary infrastructure and government-backed animal health programs will expand market penetration in rural areas.
- Integration of smart technologies and digital tools will enhance real-time surgical monitoring and procedural accuracy.
- Customized instruments tailored to species-specific needs will gain popularity across clinics and academic institutions.
- Expanding veterinary education and skill development will improve adoption of high-end surgical equipment.
- E-commerce and digital procurement platforms will streamline distribution and enhance accessibility for small practices.
- Rising focus on sustainability will drive the shift toward reusable and environmentally compliant surgical tools.
- Strategic collaborations between manufacturers and veterinary organizations will support product innovation and training.
- The market will see increased localization of manufacturing in emerging regions to reduce dependency on imports.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Veterinary Surgical Instruments Market?
What are the key segments within the Veterinary Surgical Instruments Market?
What trends are emerging in the veterinary surgical instruments market?
How do technological advancements impact the veterinary surgical instruments market?
What opportunities exist for manufacturers in the veterinary surgical instruments market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 1,250.00 million → 2032: USD 2,874.11 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Veterinary Surgical Instruments Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Veterinary Surgical Instruments Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Veterinary Surgical Instruments Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Veterinary Surgical Instruments Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Veterinary Surgical Instruments Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Veterinary Surgical Instruments Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Veterinary Surgical Instruments Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Veterinary Surgical Instruments Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 1,250.00 million → 2032: USD 2,874.11 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Veterinary Surgical Instruments Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Veterinary Surgical Instruments Geographic Market Outlook, 2018-2032
- 13.1 Regional Market Size and Share, 2018
- 13.2 Regional Market Forecast, 2018-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Veterinary Surgical Instruments Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2018-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Veterinary Surgical Instruments Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2018
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2018-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
