
Market Overview:
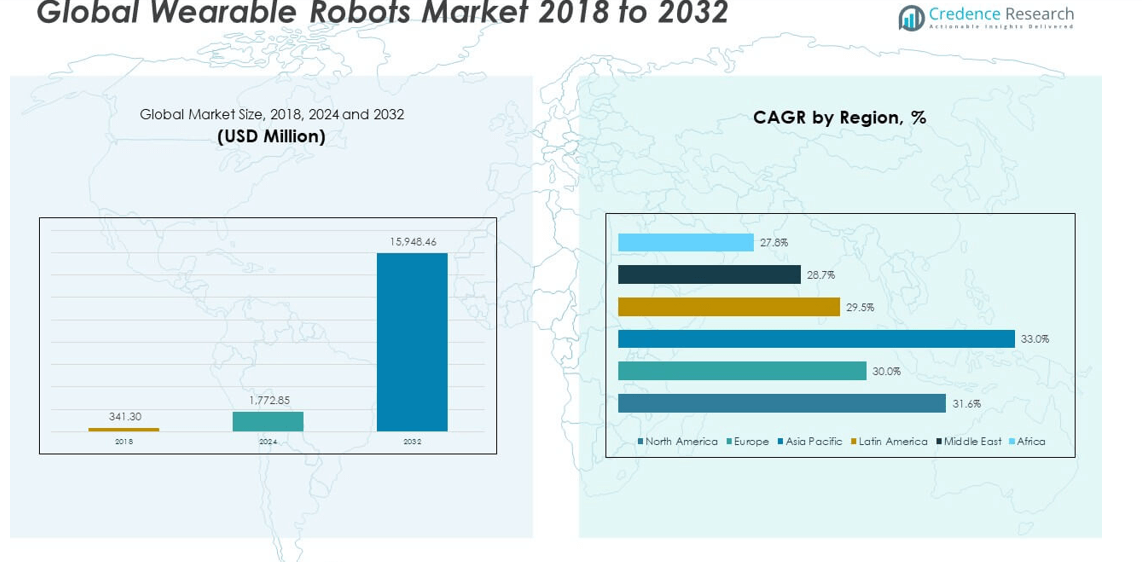
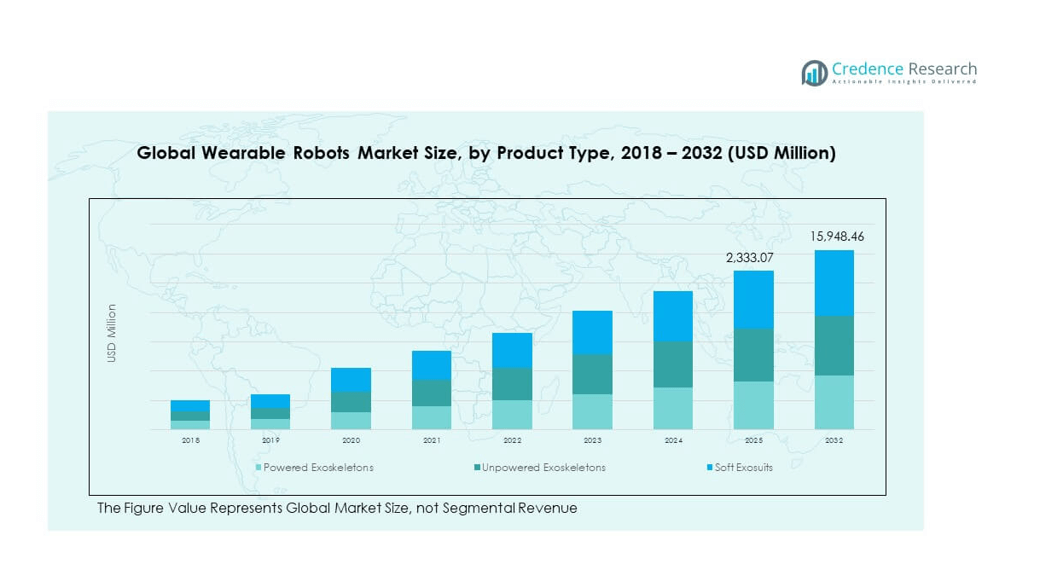
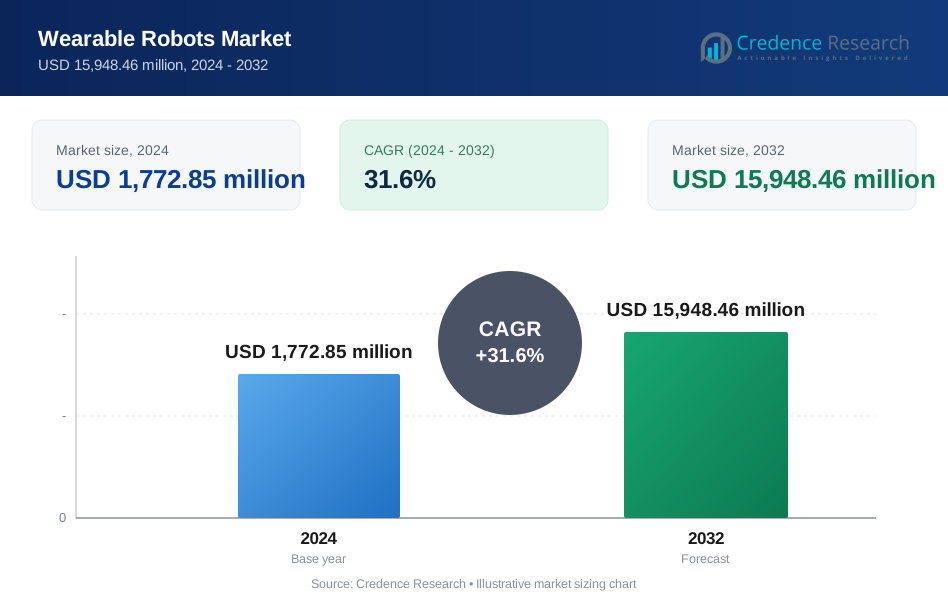
The Global Wearable Robots Market size was valued at USD 341.30 million in 2018 to USD 1,772.85 million in 2024 and is anticipated to reach USD 15,948.46 million by 2032, at a CAGR of 31.60% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wearable Robots Market Size 2024 | USD 1,772.85 million |
| Wearable Robots Market, CAGR | 31.60% |
| Wearable Robots Market Size 2032 | USD 15,948.46 million |
The market is driven by growing adoption in healthcare, defense, and industrial sectors. Rising demand for rehabilitation support, elderly care, and physical assistance for disabled individuals strengthens growth. Increasing use of wearable exoskeletons in military applications for enhanced soldier performance also fuels adoption. Industrial usage is expanding as companies focus on improving worker efficiency, reducing fatigue, and ensuring safety. Continuous advancements in robotics, artificial intelligence, and sensor technologies enhance performance and usability. Rising investments from governments and private players further accelerate development. The focus on wearable solutions for physical augmentation across multiple industries underpins long-term market expansion.
Regionally, North America leads the wearable robots market, supported by strong technological innovation, high healthcare expenditure, and defense investments. Europe follows closely, driven by demand for elderly care solutions and industrial adoption. Asia-Pacific emerges as the fastest-growing region due to increasing investments in robotics, expanding manufacturing sectors, and rising healthcare needs in countries like China, Japan, and South Korea. Emerging economies in Latin America and the Middle East also show rising potential, supported by growing interest in automation and healthcare robotics. This regional landscape highlights both established leadership and significant emerging opportunities worldwide.
Market Insights:
- The Global Wearable Robots Market size was valued at USD 341.30 million in 2018, reached USD 1,772.85 million in 2024, and is anticipated to reach USD 15,948.46 million by 2032, growing at a CAGR of 31.6%.
- North America led with 44% share in 2024, driven by advanced healthcare, strong R&D, and defense adoption. Europe followed with 18% share, supported by aging populations and industrial safety needs, while Asia Pacific held 30%, backed by strong manufacturing and healthcare robotics leadership.
- Asia Pacific is the fastest-growing region with 30% share in 2024, supported by rapid industrial automation, rising healthcare investments, and government-backed innovation in China, Japan, and South Korea.
- Powered exoskeletons accounted for nearly 60% share in 2024, dominating due to high demand across healthcare rehabilitation and defense applications.
- Soft exosuits contributed around 25% share in 2024, showing steady growth by offering lightweight, flexible, and consumer-friendly applications compared to traditional exoskeletons.
Market Drivers:
Rising Demand for Rehabilitation and Assistive Technologies in Healthcare
The Global Wearable Robots Market benefits strongly from rising demand for rehabilitation and assistive devices. Increasing cases of mobility impairment, stroke, and neurological conditions drive hospitals and rehabilitation centers to adopt advanced solutions. Wearable robots provide patients with improved mobility, muscle support, and faster recovery outcomes. The rising geriatric population also fuels demand for assistive technologies that enhance independence and reduce caregiver reliance. It supports improved quality of life for elderly individuals. Strong interest from healthcare providers and insurers in advanced rehabilitation methods accelerates market adoption. Continuous research in medical robotics further improves design and functionality. This demand positions healthcare as one of the leading growth drivers for the industry.
- For instance, clinical research published in July 2023 demonstrates that patients with stroke using the EksoNR robotic exoskeleton from Ekso Bionics achieved significant improvements in gait and functional status after undergoing robotic-assisted therapy, as measured by objective parameters such as average steps and walking time during rehabilitation sessions.
Expansion of Industrial Applications for Worker Efficiency and Safety
Industrial sectors actively integrate wearable robots to support workers in physically demanding environments. Manufacturers use exoskeletons to reduce fatigue, prevent injuries, and increase productivity on assembly lines. It improves ergonomics by reducing strain from repetitive lifting and handling tasks. Companies across automotive, logistics, and construction industries adopt wearable robots to support workforce health and efficiency. This trend is supported by stricter workplace safety regulations. Firms seek advanced solutions that balance productivity with employee well-being. Expanding industrial automation strengthens demand for human-robot collaboration. Growing awareness of workforce safety costs further drives exoskeleton adoption across industries.
- For instance, Hyundai Motor Group’s Vest EXoskeleton (VEX) has been adopted in production plants, delivering up to 5.5 kgf of additional force for overhead tasks, and is 22–42% lighter than competing products, directly supporting worker productivity and reducing musculoskeletal fatigue during factory pilot programs in the U.S. and Korea.
Defense Investments Driving Adoption of Military Wearable Robotics
Defense sectors remain key adopters of wearable robotics for enhancing soldier strength, endurance, and mobility. The Global Wearable Robots Market gains significant momentum from military-funded projects worldwide. Exoskeletons are deployed to reduce combat fatigue and improve load-carrying capabilities in missions. Governments invest heavily in robotic technologies to provide operational advantages. It strengthens battlefield performance while reducing physical strain on soldiers. Countries with strong defense budgets lead in integrating advanced wearable robotics. Collaborations between defense contractors and robotics firms accelerate innovation. Rising global defense modernization programs secure a consistent demand pipeline for military exoskeletons.
Technological Advancements and Integration of AI and Sensors
Ongoing advancements in robotics, AI, and sensor technology expand the potential of wearable robots. Enhanced battery life, lightweight materials, and compact designs improve usability across applications. It enhances the appeal of wearable robots for both commercial and medical uses. AI integration allows predictive motion control, improving efficiency and safety. Advanced sensors enable precise monitoring of body movement and health parameters. These innovations broaden the scope of adoption across healthcare, defense, and industrial sectors. Robotics firms invest in R&D to refine customization and adaptability. Continuous innovation ensures wearable robots remain central in addressing future mobility and workforce challenges.
Market Trends:
Integration of Wearable Robots with Smart Healthcare Systems
The Global Wearable Robots Market experiences rapid growth through integration with advanced healthcare systems. Hospitals and rehabilitation centers adopt connected wearable robots that track patient progress in real time. It enables clinicians to monitor recovery outcomes and adjust therapies more effectively. Integration with IoT platforms enhances patient data management and predictive analysis. Healthcare providers use these systems to reduce hospital stays and improve long-term rehabilitation. The shift toward personalized medicine aligns well with wearable robotic technologies. Insurance companies also show interest in supporting robotic rehabilitation programs. These integrated solutions expand the role of wearable robots in modern healthcare ecosystems.
- For instance, Cyberdyne Inc. HAL (Hybrid Assistive Limb) exoskeleton is highlighted in a June 2025 systematic review as the only device proven to induce neuroplasticity and deliver comprehensive therapeutic benefits for patients with spinal cord injury, verified across 27 clinical studies with 591 patients worldwide.
Emergence of Lightweight and Ergonomic Designs for Broader Adoption
Wearable robot manufacturers focus on lightweight and ergonomic designs to increase user comfort. Earlier models were often bulky and restrictive, limiting extended use. It drives companies to adopt advanced materials and flexible structures that improve wearability. Ergonomic solutions reduce strain and allow seamless movement across applications. Industries such as logistics and healthcare favor designs that balance performance with long-term comfort. Wearable robots with enhanced usability gain acceptance among older adults and non-specialist users. Companies highlight user-centered design in marketing strategies to expand demand. This trend positions ergonomics as a competitive differentiator in the wearable robots market.
- For instance, the German Bionic Cray X industrial exoskeleton delivers up to 30 kg (66 lbs) of lower back support per lifting movement and is integrated with AI to monitor ergonomics in warehousing and logistics, with field trials confirming substantial reduction in employee fatigue and overexertion in partner operations at DACHSER and DHL locations.
Collaboration Between Robotics Firms and Industry Verticals for Custom Solutions
Growing collaboration between robotics developers and industry players drives tailored wearable robot applications. Automotive companies work with exoskeleton providers to design solutions for assembly-line workers. It ensures that robots meet specific operational requirements while improving safety standards. Healthcare firms partner with robotics companies to adapt devices for rehabilitation programs. Defense contractors collaborate to create battlefield-ready exoskeletons for soldiers. These cross-sector partnerships accelerate product development and commercialization. Custom solutions build higher value and deeper market penetration. Strong alliances secure long-term contracts, driving consistency in demand and revenue growth.
Increased Focus on Human-Robot Collaboration in Industrial Workflows
Industries increasingly integrate wearable robots to enhance human-robot collaboration in operations. Companies explore exoskeletons as supportive tools rather than worker replacements. It helps balance productivity goals with employee well-being. Industrial sectors such as manufacturing, logistics, and construction deploy robots to reduce fatigue. Exoskeletons also lower risks associated with repetitive strain injuries. Human-robot synergy leads to safer, more efficient workplaces. This shift strengthens corporate adoption strategies across global markets. The trend highlights a future where wearable robots act as collaborative partners in industrial environments.
Market Challenges Analysis:
High Costs and Limited Affordability Restricting Widespread Adoption
The Global Wearable Robots Market faces challenges due to high production and acquisition costs. Advanced exoskeletons integrate cutting-edge sensors, AI, and lightweight materials, making them expensive. It limits affordability for smaller healthcare providers and industrial firms. High maintenance costs also deter adoption among price-sensitive users. Insurance coverage for robotic rehabilitation devices remains limited in many regions. Industrial users hesitate to invest heavily without clear cost-benefit guarantees. Small and medium-sized enterprises often lack budgets to adopt wearable robots. This financial barrier slows penetration, particularly in emerging markets where funding is scarce.
Regulatory Hurdles and Technical Limitations in Broader Deployment
Wearable robots face strict regulations regarding medical safety and industrial standards. Obtaining approvals from healthcare authorities and labor regulators delays product rollout. It impacts speed-to-market for many innovative designs. Technical limitations such as battery life, mobility range, and adaptability create further barriers. Lack of standardized frameworks also complicates adoption across regions. Training requirements for operators and patients add to complexity. Some users remain hesitant due to concerns over safety and reliability. The Global Wearable Robots Market continues to struggle with aligning technological innovation and regulatory compliance. These hurdles slow down rapid scaling despite growing global interest.
Market Opportunities:
Rising Demand in Emerging Economies with Expanding Healthcare and Industrial Sectors
Emerging economies present strong growth opportunities for the Global Wearable Robots Market. Countries in Asia-Pacific, Latin America, and the Middle East invest heavily in healthcare modernization and industrial automation. It supports the adoption of wearable robots across rehabilitation centers and manufacturing facilities. Rising awareness of robotic assistance drives demand among hospitals and caregivers. Expanding industrial sectors adopt exoskeletons to improve worker productivity and safety. Government initiatives supporting technology-driven healthcare solutions create additional opportunities. Local manufacturers collaborate with global players to introduce cost-effective designs. This rising demand highlights long-term growth potential in developing regions.
Advancements in AI and Customizable Robotic Solutions for Niche Applications
Advancements in AI, sensors, and robotics open new avenues for wearable robot applications. It enables development of personalized and adaptive exoskeletons for diverse user groups. Healthcare systems benefit from customized rehabilitation programs supported by robotic solutions. Industrial users gain tailored exoskeletons designed for specific operational needs. Defense organizations explore battlefield-ready devices for soldier augmentation. Continuous innovation creates niche opportunities in sports recovery and elderly care. Expanding customization enhances market attractiveness across sectors. These advancements strengthen the role of wearable robots as vital solutions in the evolving global landscape.
Market Segmentation Analysis:
By Product Type
The Global Wearable Robots Market is segmented into powered exoskeletons, unpowered exoskeletons, and soft exosuits. Powered exoskeletons dominate due to their advanced functionality in healthcare and defense. Unpowered exoskeletons gain traction in industries where cost-effectiveness and durability are essential. Soft exosuits emerge as lightweight solutions for rehabilitation and consumer applications, offering comfort and flexibility. It highlights strong adoption across both high-tech and practical use cases.
- For instance, ReWalk Robotics (rebranded Lifeward) received U.S. FDA clearance for its ReWalk 7 exoskeleton in March 2025, which allows spinal cord injury patients to stand and walk with robust therapeutic upgrades, marking an important step in medical wearable robotics.
By Application
Healthcare remains the leading application segment with rising demand for rehabilitation and mobility assistance. Industrial usage grows steadily as companies adopt exoskeletons to reduce workplace injuries and enhance productivity. Military and defense applications expand through investments in soldier performance enhancement. Consumer adoption is in its early stage but shows potential for fitness and lifestyle support. Other applications focus on research and niche activities, adding diversity to the market.
- For instance, Sarcos Defense developed the Guardian XO exoskeleton, which is being tested by the U.S. Marine Corps and Air Force; the suit can augment human strength for logistics tasks and is capable of lifting up to 200 pounds without operator fatigue during extended shifts, enhancing material handling and safety for military personnel.
By Component
Sensors play a critical role in ensuring precision and safety across wearable robots. Actuators provide motion control, making them indispensable in exoskeleton systems. Batteries define operational efficiency and remain central to innovation in lightweight designs. Control systems integrate software and hardware to ensure seamless performance, enhancing usability. It reflects the importance of advanced components in driving overall system reliability.
By End User Industry
Corporations represent the largest share, focusing on worker safety and operational efficiency. Individuals benefit from healthcare-focused wearable robots, especially for rehabilitation and mobility. Government agencies drive demand through defense projects and public healthcare initiatives. Others include academic and research institutions, exploring wearable robotics for specialized uses. This segmentation highlights balanced growth across industries with diverse adoption pathways.
Segmentation:
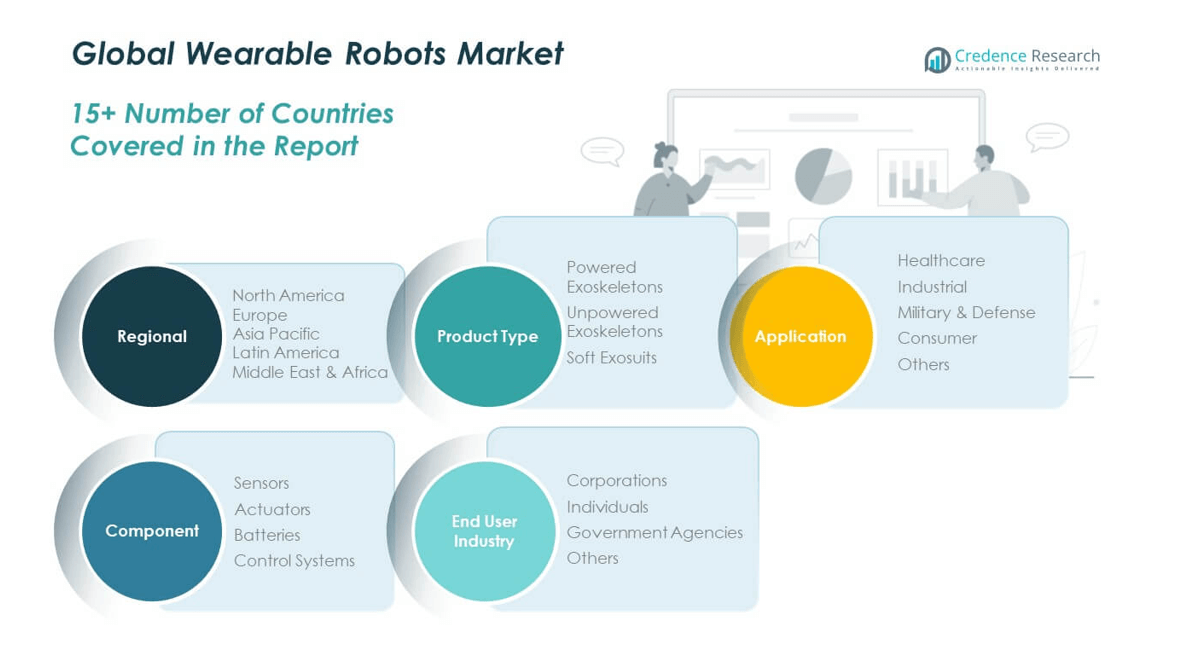
By Product Type- Powered Exoskeletons
- Unpowered Exoskeletons
- Soft Exosuits
- Healthcare
- Industrial
- Military & Defense
- Consumer
- Others
- Sensors
- Actuators
- Batteries
- Control Systems
- Corporations
- Individuals
- Government Agencies
- Others
- North America (U.S., Canada, Mexico)
- Europe (UK, France, Germany, Italy, Spain, Russia, Rest of Europe)
- Asia Pacific (China, Japan, South Korea, India, Australia, Southeast Asia, Rest of Asia Pacific)
- Latin America (Brazil, Argentina, Rest of Latin America)
- Middle East (GCC Countries, Israel, Turkey, Rest of Middle East)
- Africa (South Africa, Egypt, Rest of Africa)
Regional Analysis:
North America
The North America Global Wearable Robots Market size was valued at USD 150.59 million in 2018 to USD 774.20 million in 2024 and is anticipated to reach USD 6,983.81 million by 2032, at a CAGR of 31.6% during the forecast period. North America holds the largest share of the Global Wearable Robots Market, accounting for nearly 44% in 2024. Strong technological innovation, significant healthcare spending, and defense investments drive growth in the region. The U.S. leads due to robust adoption in rehabilitation, elderly care, and industrial sectors. Canada supports market expansion with increasing healthcare modernization. Mexico shows rising adoption through industrial safety programs. It benefits from early integration of robotics into healthcare systems and strong R&D infrastructure. Defense projects further accelerate the pace of adoption.
Europe
The Europe Global Wearable Robots Market size was valued at USD 63.56 million in 2018 to USD 312.03 million in 2024 and is anticipated to reach USD 2,551.87 million by 2032, at a CAGR of 30.0% during the forecast period. Europe contributes about 18% of the market share in 2024. The region sees strong demand for rehabilitation-focused wearable robots due to aging populations. Germany, the UK, and France dominate adoption in healthcare and industrial segments. Industrial sectors emphasize worker safety and productivity, fueling adoption of exoskeletons. It benefits from supportive policies promoting innovation in healthcare robotics. The region’s defense projects also explore military exoskeletons for mobility enhancement. Rising collaborations between universities and robotics firms strengthen growth. Europe remains a steady contributor with balanced adoption across sectors.
Asia Pacific
The Asia Pacific Global Wearable Robots Market size was valued at USD 97.35 million in 2018 to USD 534.28 million in 2024 and is anticipated to reach USD 5,247.19 million by 2032, at a CAGR of 33.0% during the forecast period. Asia Pacific accounts for nearly 30% of the market share in 2024. China, Japan, and South Korea drive adoption through advanced manufacturing and defense investments. Japan leads in healthcare robotics for rehabilitation and elderly care. China focuses on industrial integration of exoskeletons and large-scale production. South Korea emphasizes defense and technology innovation. India shows potential with expanding healthcare and industrial adoption. It benefits from government-backed investments and increasing consumer awareness. Asia Pacific’s strong economic growth and innovation ecosystem make it the fastest-growing region.
Latin America
The Latin America Global Wearable Robots Market size was valued at USD 15.40 million in 2018 to USD 78.96 million in 2024 and is anticipated to reach USD 624.79 million by 2032, at a CAGR of 29.5% during the forecast period. Latin America holds around 5% of the market share in 2024. Brazil dominates adoption, driven by industrial automation and healthcare rehabilitation programs. Mexico also supports demand with gradual adoption in logistics and industrial safety. It benefits from increasing government interest in modernizing healthcare services. Argentina shows potential through niche adoption in rehabilitation. Regional adoption is slower compared to developed markets but shows consistent progress. Industrial safety initiatives and localized partnerships drive awareness. Growth remains steady, with rising opportunities in manufacturing and healthcare robotics.
Middle East
The Middle East Global Wearable Robots Market size was valued at USD 9.26 million in 2018 to USD 43.82 million in 2024 and is anticipated to reach USD 330.40 million by 2032, at a CAGR of 28.7% during the forecast period. The region accounts for about 2.5% of the market share in 2024. GCC countries lead adoption through healthcare modernization and industrial safety initiatives. Israel drives innovation with strong R&D in robotics and defense. Turkey also contributes with rising industrial usage. It benefits from government-backed projects focusing on healthcare and defense robotics. The market is supported by investments in rehabilitation for disabled and elderly populations. Industrial automation adds momentum in manufacturing hubs. The Middle East shows potential despite smaller scale adoption.
Africa
The Africa Global Wearable Robots Market size was valued at USD 5.14 million in 2018 to USD 29.56 million in 2024 and is anticipated to reach USD 210.39 million by 2032, at a CAGR of 27.8% during the forecast period. Africa accounts for about 1.7% of the market share in 2024. South Africa leads regional adoption with growing use in healthcare rehabilitation. Egypt supports demand with gradual integration in hospitals and research. Other countries in the region adopt wearable robots at a slower pace. It benefits from increasing awareness of advanced healthcare solutions. Industrial applications are limited but expected to rise with modernization. International partnerships help introduce cost-effective solutions. The region shows early-stage growth but holds long-term opportunities as healthcare infrastructure develops.
Key Player Analysis:
- Cyberdyne Inc.
- Ekso Bionics Holdings Inc.
- Sarcos Corporation
- Honda Motor Co. Ltd.
- Lockheed Martin Corporation
- Panasonic Corporation
- ReWalk Robotics
- Bionik Laboratories Corp.
- Medtronic plc
- Ottobock SE & Co. KGaA
Competitive Analysis:
The Global Wearable Robots Market is highly competitive, with established players and emerging innovators driving advancements. Companies focus on healthcare, industrial, and defense applications by investing in R&D to develop lightweight, energy-efficient, and AI-enabled solutions. It benefits from strong partnerships between robotics firms, universities, and government agencies that accelerate innovation and adoption. Key players such as Cyberdyne Inc., Ekso Bionics, Sarcos, ReWalk Robotics, Honda, and Ottobock compete through product launches and strategic collaborations. The market emphasizes ergonomic designs, safety features, and customized solutions to strengthen differentiation and expand customer bases.
Recent Developments:
- In July and September 2025, Medtronic plc reported that it had received FDA clearance to expand the MiniMed™ 780G system portfolio by integrating Abbott’s Instinct sensor and by authorizing use in adults with type 2 diabetes. In April 2025, Medtronic also secured FDA approval for its new Simplera Sync™ sensor for use with the 780G system.
- In June 2025, Lockheed Martin Corporation completed the acquisition of Amentum’s Rapid Solutions business, enhancing Lockheed Martin’s capabilities in airborne and space Intelligence, Surveillance, and Reconnaissance (ISR), advanced communications, and tactical systems for defense applications.
- In May 2025, Ekso Bionics Holdings Inc. was accepted into the NVIDIA Connect program, supporting Ekso’s strategic push to build a proprietary foundation model for human motion, and shortly after, unveiled a new AI voice agent for intelligent control of its EksoNR device. The company also launched eksoUniversity in July 2025, a continuing education platform for physical therapists working in neurological rehabilitation.
- In March 2025, Cyberdyne Inc. entered into a strategic partnership with the Development Center for Biotechnology in Taiwan to promote Cybernics medical and healthcare innovation in Japan and Taiwan, reinforcing its international collaboration in the wearable robotics sector and expanding applications for its HAL-assisted technology.
- In August 2024, Honda Motor Co. Ltd. and Nissan signed a memorandum of understanding to deepen their ongoing strategic partnership, launching joint research on next-generation software-defined vehicle (SDV) platforms and cooperation in electrification and vehicle intelligence.
Report Coverage:
The research report offers an in-depth analysis based on product type and application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising adoption in healthcare rehabilitation and elderly care.
- Expanding industrial usage for safety and efficiency.
- Defense investments driving military-grade exoskeletons.
- Rapid growth in Asia-Pacific through manufacturing and healthcare.
- Integration of AI and IoT enhancing performance.
- Ergonomic and lightweight designs boosting user adoption.
- Strategic collaborations accelerating product innovation.
- Increasing acceptance in consumer fitness and wellness.
- Regulatory frameworks shaping product approvals.
- Emerging economies creating untapped opportunities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Wearable Robots Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Wearable Robots Market projected to grow between 2025 and 2032?
What are the key drivers for the growth of the global wearable robots market?
Which is the major segment in the wearable robots market by Type?
Which is the major segment in the wearable robots market by Application?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Wearable Robots Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Wearable Robots Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,772.85 million → 2032: USD 15,948.46 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Wearable Robots Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Wearable Robots Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Wearable Robots Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Wearable Robots Market Drivers
- 3.3 Wearable Robots Market Restraints & Challenges
- 3.4 Wearable Robots Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Wearable Robots Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Wearable Robots Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Wearable Robots category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Wearable Robots Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Wearable Robots Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Wearable Robots. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Wearable Robots Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Wearable Robots Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Wearable Robots Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Wearable Robots (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Wearable Robots
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Wearable Robots Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Wearable Robots Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Wearable Robots Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Wearable Robots Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Wearable Robots Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Wearable Robots Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Wearable Robots Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Wearable Robots Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
