
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Workout Clothes Market Size 2024 | USD 238195 million |
| Workout Clothes Market, CAGR | 6.01% |
| Workout Clothes Market Size 2032 | USD 379933.3 million |
Market Overview:
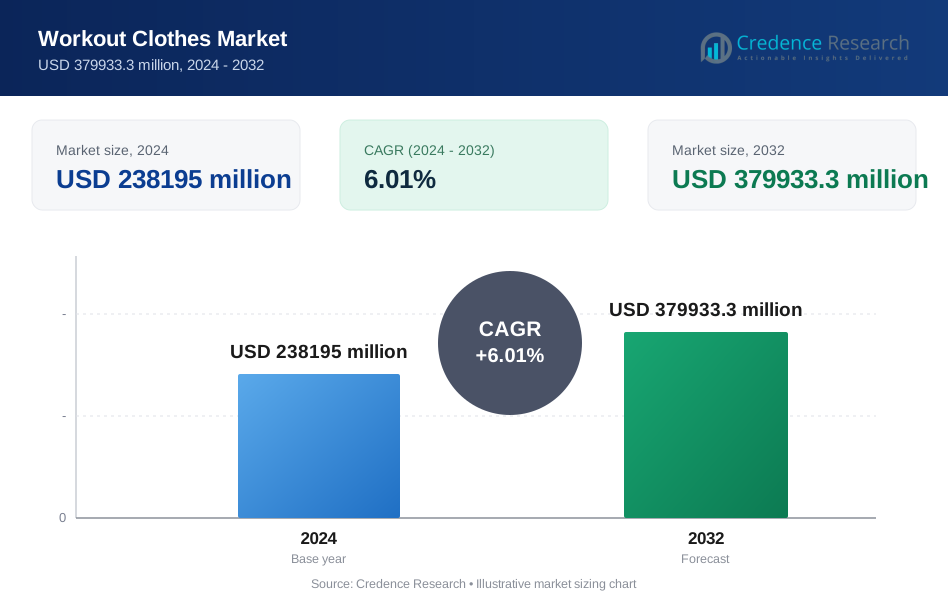
The Workout Clothes Market is projected to grow from USD 238195 million in 2024 to an estimated USD 379933.3 million by 2032, with a compound annual growth rate (CAGR) of 6.01 % from 2024 to 2032.
Several key factors drive the growth of the workout clothes market. Firstly, the increasing global health consciousness and fitness awareness have significantly boosted demand. More individuals are engaging in regular exercise, which necessitates functional and comfortable workout attire. Secondly, the athleisure trend has blurred the lines between casual wear and athletic wear, leading to higher demand for versatile and stylish workout clothes that can be worn in various settings. Additionally, technological advancements in fabric and garment design have enhanced the functionality, durability, and comfort of workout clothes, making them more appealing to consumers. The rise of e-commerce platforms has also facilitated greater market penetration and accessibility, allowing consumers to explore and purchase from a wide range of workout clothing brands and styles.
Geographically, the workout clothes market is segmented into North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. North America holds the largest market share, driven by high consumer spending on fitness and a well-established athleisure culture. The presence of major brands and a high rate of gym memberships further bolster the market in this region. Europe follows closely, with countries like Germany, the UK, and France leading the demand due to strong fitness trends and lifestyle changes. The Asia-Pacific region is expected to witness the fastest growth during the forecast period, attributed to rising disposable incomes, increasing health awareness, and the burgeoning middle-class population. Countries like China, India, and Japan are at the forefront of this growth. Latin America and the Middle East & Africa are also showing promising growth, although at a comparatively slower pace, driven by urbanization and growing interest in fitness activities.
Market Drivers:
Increasing Health and Fitness Awareness:
One of the primary drivers of the workout clothes market is the growing awareness of health and fitness among consumers. As more people become conscious of the benefits of maintaining a healthy lifestyle, there is a notable increase in participation in various physical activities such as gym workouts, yoga, running, and cycling. In the United States, around 19.3% of the population engaged in sports and exercise daily in 2019, with significant participation in activities like running and hiking. This shift towards a more active lifestyle necessitates appropriate attire that enhances performance and comfort.
Workout clothes, designed with features like moisture-wicking, breathability, and flexibility, meet these requirements, thereby driving their demand. The pandemic has further accelerated this trend, with many individuals setting up home gyms and engaging in virtual fitness classes. For instance, a significant increase in fitness app downloads was observed globally, particularly in India, where health and fitness app downloads rose by 46% during the early months of the pandemic. The influence of social media and fitness influencers amplifies this trend by promoting active lifestyles and stylish workout attire, encouraging more consumers to invest in quality workout clothes. The data indicates that 70% of millennials participated in fitness activities in 2021, highlighting a generational shift towards fitness consciousness.
Athleisure Trend:
The athleisure trend significantly impacts the workout clothes market, blending athletic wear with casual fashion. This trend has transcended traditional workout settings, making workout clothes suitable for a wide range of activities, including everyday wear. Consumers now seek multifunctional apparel that offers both performance and style, leading to increased demand for workout clothes that can be worn both in and out of the gym. For instance, the popularity of yoga pants has surged, with many women incorporating them into their daily outfits, reflecting a shift towards comfort and versatility in fashion choices. Major brands and fashion designers have embraced this trend, introducing stylish and versatile workout clothing lines. The rise of athleisure is evident across various demographics, from millennials, who often seek trendy and functional pieces, to older generations looking for comfortable yet fashionable attire. The influence of social media and fitness influencers plays a crucial role in promoting athleisure, as they showcase how to style these garments for both workouts and casual outings. This has contributed to the growing acceptance of athleisure in various settings, including workplaces, where comfortable yet polished looks are increasingly favored.
Technological Advancements in Fabric and Design:
Advancements in fabric technology and garment design are crucial drivers of the workout clothes market. Innovations such as moisture-wicking fabrics, anti-odor technology, compression garments, and seamless construction have enhanced the functionality and appeal of workout clothes. For instance, moisture-wicking fabrics effectively draw sweat away from the body, keeping athletes dry and comfortable during intense workouts, while breathable materials allow for better airflow, preventing overheating. Additionally, the integration of compression technology has been shown to improve blood circulation and reduce muscle fatigue, making these garments increasingly desirable for fitness enthusiasts. The market is also witnessing the rise of smart textiles, which incorporate embedded sensors that monitor physiological data, providing real-time feedback on performance metrics such as heart rate and calories burned. Eco-friendly and sustainable materials are gaining traction, appealing to environmentally conscious consumers. Brands are increasingly investing in research and development to introduce cutting-edge technologies and sustainable practices. For example, many companies are exploring the use of recycled textiles made from post-consumer waste, such as plastic bottles, and developing fabrics from organic materials like bamboo and hemp. These advancements not only improve product offerings but also differentiate brands in a competitive market.
Growth of E-commerce and Digital Platforms:
The rise of e-commerce and digital platforms has revolutionized the way consumers purchase workout clothes. Online shopping offers convenience, a wide range of options, and easy comparison of products, which has significantly contributed to the growth of the workout clothes market. E-commerce platforms also provide access to global brands, allowing consumers to explore and purchase from a diverse selection of workout clothing. Furthermore, digital marketing strategies, including social media advertising and influencer collaborations, have proven effective in reaching target audiences and driving sales. The integration of augmented reality (AR) and virtual fitting rooms in online shopping experiences also enhances consumer engagement and satisfaction, further boosting the market. Additionally, data analytics and personalized recommendations based on consumer preferences and buying behavior enable retailers to offer tailored shopping experiences, increasing customer loyalty and repeat purchases. As mobile commerce continues to rise, the seamless shopping experience across various devices further encourages consumers to shop for workout clothes online, solidifying e-commerce as a key driver in the market's growth.
Market Trends:
Rise of Sustainable and Eco-Friendly Apparel:
A significant trend in the workout clothes market is the increasing demand for sustainable and eco-friendly apparel. For instance, consumers are becoming more environmentally conscious, with 66% of global consumers indicating a preference for sustainable brands, and are actively seeking products that align with their values. This shift has led to the development and popularity of workout clothes made from organic, recycled, and biodegradable materials. For example, brands like Girlfriend Collective are leading the way by using recycled materials such as fabric scraps and plastic bottles in their production processes. This commitment to sustainability resonates with consumers, as evidenced by the growing preference for eco-friendly athletic apparel, which has reached an all-time high. Brands are also investing in sustainable manufacturing processes and adopting eco-friendly practices to reduce their carbon footprint. This includes utilizing recycled plastic fibers, organic cotton, and water-saving dyes, which not only appeal to eco-conscious consumers but also help brands differentiate themselves in a competitive market. For instance, Everlane has committed to eliminating virgin plastics from its supply chain, focusing on transparency and sustainability in its activewear line.
This trend is not only driven by consumer preference but also by regulatory pressures and the global movement towards sustainability. As governments and organizations push for more environmentally friendly practices, brands that prioritize sustainability are gaining a competitive edge and attracting a loyal customer base.
Technological Integration and Smart Clothing:
The integration of technology into workout clothes is another notable trend shaping the market. Smart clothing, embedded with sensors and connected devices, offers advanced functionalities such as monitoring heart rate, tracking physical activity, and providing real-time feedback on performance. For instance, a survey found that 70% of fitness enthusiasts are interested in smart clothing that can track their workouts and provide insights into their performance.
These innovations enhance the workout experience and help users achieve their fitness goals more efficiently. A study indicated that users of smart clothing reported a 30% improvement in their workout efficiency due to the real-time feedback provided by embedded sensors. Additionally, advancements in fabric technology, such as moisture-wicking, temperature regulation, and anti-odor properties, continue to improve the functionality and comfort of workout clothes. Around 60% of consumers prioritize moisture-wicking and breathable fabrics when selecting workout apparel. The convergence of fashion and technology is driving the development of innovative products that cater to the evolving needs of fitness enthusiasts. For example, smart socks equipped with sensors can track foot landing and provide feedback to runners, helping to reduce injury risk.
Customization and Personalization:
Customization and personalization are gaining traction in the workout clothes market. Consumers are increasingly seeking unique and personalized products that reflect their individual style and preferences. Brands are responding to this trend by offering customizable options, such as personalized prints, colors, and fits. Advances in digital printing and manufacturing technologies enable brands to provide bespoke workout clothes with shorter turnaround times and at competitive prices. This trend enhances customer satisfaction and engagement, as consumers feel more connected to products that are tailored to their specific needs. The ability to offer personalized experiences is becoming a key differentiator for brands in the competitive workout clothes market. Moreover, personalization extends beyond aesthetics; it also includes functional customization, such as adjusting support levels in sports bras or tailoring compression levels in leggings. These options cater to the diverse and specific needs of athletes and fitness enthusiasts, ensuring optimal performance and comfort. As brands continue to innovate in this space, the importance of customization and personalization will only grow, solidifying its role as a major trend in the workout clothes market.
Growth of Direct-to-Consumer (DTC) Brands:
The rise of direct-to-consumer (DTC) brands is significantly impacting the workout clothes market. DTC brands leverage digital platforms to sell directly to consumers, bypassing traditional retail channels. This business model allows them to offer high-quality products at lower prices by eliminating intermediaries. DTC brands are also known for their strong online presence, innovative marketing strategies, and customer-centric approaches. They use social media, influencer partnerships, and data-driven marketing to build strong relationships with their customers and create a loyal following. The success of DTC brands is prompting traditional retailers to rethink their strategies and enhance their online presence to remain competitive.
Market Restraints and Challenges:
High Competition and Market Saturation:
The workout clothes market faces intense competition and market saturation. Numerous brands, ranging from established players to new entrants, are vying for market share. This high level of competition pressures brands to continuously innovate and differentiate their products to maintain consumer interest. Additionally, market saturation can lead to reduced profit margins as companies engage in price wars and promotional activities to attract customers. This competitive landscape requires significant investment in marketing and product development, which can be challenging for smaller brands with limited resources.
Volatility in Raw Material Prices:
Fluctuations in the prices of raw materials, such as cotton, polyester, and other synthetic fibers, pose a significant challenge for the workout clothes market. These price volatilities can impact production costs and, consequently, product pricing. Brands may struggle to maintain consistent pricing strategies, which can affect their profitability and competitive positioning. Additionally, supply chain disruptions, whether due to geopolitical issues, natural disasters, or pandemics, can exacerbate these challenges, leading to delays in production and distribution.
Environmental and Ethical Concerns:
The growing emphasis on sustainability and ethical practices presents both an opportunity and a challenge for the workout clothes market. While there is increasing demand for eco-friendly and ethically produced apparel, transitioning to sustainable practices can be costly and complex. Brands must invest in sustainable materials, environmentally friendly manufacturing processes, and transparent supply chains. This transition requires substantial financial resources and time, and not all brands are equipped to make these changes swiftly. Additionally, consumers are becoming more scrutinizing of brand practices, and any perceived shortcomings in sustainability and ethics can harm brand reputation and consumer trust.
Rapidly Changing Fashion Trends:
The workout clothes market is heavily influenced by fashion trends, which can change rapidly. Keeping up with these trends requires brands to have agile design and production processes to quickly adapt to new styles and consumer preferences. This need for constant innovation can strain resources and complicate inventory management. Moreover, failing to anticipate or respond promptly to fashion trends can result in obsolete inventory, increased costs, and reduced consumer interest.
Market Segmentation Analysis:
By Product Type
The workout clothes market is segmented into various product types, including activewear, athleisure, and performance gear. Activewear encompasses items such as leggings, sports bras, and tank tops, designed for functionality during workouts. Athleisure combines athletic and casual wear, catering to consumers seeking versatile clothing suitable for both exercise and everyday use. Performance gear, including specialized equipment like compression wear and moisture-wicking fabrics, targets serious athletes and fitness enthusiasts requiring high-performance apparel.
By Consumer Orientation
The market is divided into two main segments based on consumer orientation: men’s and women’s workout clothes. Women’s workout clothes hold a larger market share due to the diverse range of products and growing interest in fitness among women. However, men’s workout apparel is also experiencing significant growth, driven by increasing participation in fitness activities and sports.
By Material Type
Workout clothes are categorized by material type into synthetic fabrics, natural fabrics, and blended fabrics. Synthetic materials, such as polyester and spandex, are popular for their moisture-wicking and stretch properties. Natural fabrics, including cotton, offer breathability and comfort, while blended fabrics combine the benefits of both synthetic and natural materials, enhancing functionality and durability.
By Sales Channel
The market is segmented by sales channel into online and offline channels. Online sales channels, including e-commerce platforms and brand websites, are growing rapidly due to their convenience and wide product selection. Offline channels, such as specialty stores, department stores, and fitness boutiques, remain significant, providing consumers with the opportunity to try on and purchase products in person.
Segmentation:
By Product Type
- Activewear
- Athleisure
- Performance gear
By Consumer Orientation
- Men
- Women workout clothes
By Material Type’s
- Synthetic Fabrics
- Natural Fabrics
- Blended Fabrics
By Sales Channel
- Online
- Offline channels.
By Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- Uk
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East & Africa
- UAE
- Saudi Arabia
- Qatar
- South Africa
- Rest of the Middle East & Africa
Regional Analysis:
North America
North America holds the largest market share in the workout clothes market, accounting for around 35% of the global market. The region's dominance is driven by high consumer spending on fitness and a well-established culture of health and wellness. The United States, in particular, is a significant contributor, with a high number of fitness centers, gyms, and health clubs. Additionally, the athleisure trend is deeply ingrained in North American lifestyle, with consumers seeking versatile clothing that can transition from workout settings to casual wear. Major brands and numerous startups in the region continually innovate and market their products effectively, further strengthening North America's leading position.
Europe
Europe follows North America with a market share of around 25%. Countries like Germany, the United Kingdom, and France are key players, driven by strong fitness trends and a growing awareness of the importance of a healthy lifestyle. The region also shows a significant inclination towards sustainable and eco-friendly workout clothes, with consumers preferring brands that emphasize ethical manufacturing practices. The presence of major sporting events and a vibrant sports culture contribute to the steady demand for workout clothes. Additionally, European brands are known for their quality and innovation, appealing to a broad consumer base within and outside the region.
Asia-Pacific
The Asia-Pacific region is expected to witness the fastest growth, currently holding a market share of about 20%. This growth is primarily attributed to rising disposable incomes, increasing health awareness, and a burgeoning middle-class population. Countries like China, India, and Japan are at the forefront of this expansion. The rapid urbanization and increasing number of fitness centers and health clubs in these countries are driving the demand for workout clothes. Moreover, the growing influence of Western fitness trends and the adoption of athleisure fashion among younger consumers are contributing to the market's growth. Local brands are also emerging, offering competitively priced products tailored to regional preferences, further boosting market dynamics.
Latin America
Latin America accounts for about 10% of the global workout clothes market. The region is experiencing steady growth driven by urbanization and a rising interest in fitness and wellness activities. Brazil and Mexico are the major contributors, with a growing number of fitness enthusiasts and an increasing number of gyms and health clubs. The influence of social media and fitness influencers is also significant in this region, promoting active lifestyles and fashionable workout attire. However, economic fluctuations and varying levels of disposable income across different countries can pose challenges to market growth.
Middle East & Africa
The Middle East & Africa region holds the remaining 10% market share. The market is relatively nascent but shows promising potential due to increasing urbanization, rising disposable incomes, and a growing awareness of health and fitness. The United Arab Emirates and South Africa are notable markets, with an increasing number of fitness centers and a rising trend of athleisure wear. The region's unique cultural preferences necessitate workout clothes that offer modesty and functionality, prompting brands to tailor their products accordingly. While the market faces challenges such as economic disparities and limited infrastructure in some areas, the overall outlook remains positive with a steady growth trajectory.
Key Player Analysis:
- NIKE, Inc
- PVH Corp
- PUMA SE
- Skechers USA, Inc
- Under Armour, Inc
- Adidas AG
- ASICS Corporation
- Columbia Sportswear Company
- DICK'S Sporting Goods, Inc
- Gap Inc
- V. F. Corporation (North Face, Inc.)
- Others
Competitive Analysis:
The workout clothes market is highly competitive, characterized by the presence of numerous global and regional players. Major brands like Nike, Adidas and Under Armour dominate the market, leveraging their strong brand equity, extensive distribution networks, and continuous innovation in product design and technology. These companies invest heavily in marketing, endorsements, and R&D to maintain their competitive edge. Additionally, emerging direct-to-consumer (DTC) brands such as Gymshark and Outdoor Voices are gaining traction by offering high-quality, trendy workout clothes at competitive prices, and utilizing digital marketing strategies effectively. The market also sees a significant presence of regional brands that cater to local preferences and offer more affordable options. The intense competition drives continuous innovation and differentiation, making the market dynamic and consumer-centric.
Overall, brand loyalty, product innovation, and strategic marketing are key factors that influence competitive positioning in the workout clothes market.
Recent Developments:
- Athleta, a premium sport and activewear brand based in the United States and part of Gap Inc., introduced a new workout collection for women in February 2024. The collection features proprietary fabrics designed for high-intensity workouts.
- Fitness expert Tracy Anderson launched her activewear line, the Tracy Anderson Collection, in January 2024. The debut includes the Power Mesh Shrug, available in beige and black, crafted from high-performance fabric.
- In March 2024, Fitness Junkie, a prominent fitness influencer, announced a collaboration with Spartan, a leading obstacle course race organizer, and More Hearts Than Scars, a respected NGO. This partnership focuses on transforming lives through fitness and community support.
- In June 2023, lululemon, a global leader in athletic apparel, partnered with Zalando to enhance its presence in Europe. The collaboration features lululemon’s innovative accessories and apparel, aiming to attract more customers.
- Professional basketball player Jonathan Isaac launched his athletic apparel line in August 2023, catering to conservative and Christian values. This new venture offers a brand that resonates with faith- and freedom-oriented consumers.
- Khosi Twala, winner of Big Brother Titans, introduced her Active Lifestyle Gym Apparel in July 2023, designed for fitness enthusiasts who prioritize both style and performance.
- Origin unveiled a new line of athletic wear in June 2023, emphasizing its commitment to quality with products made in the United States.
Market Concentration & Characteristics:
The workout clothes market exhibits a moderate to high level of concentration, with a few dominant players such as Nike, Adidas and Under Armour capturing a significant share of the market. These major brands benefit from strong brand recognition, extensive distribution networks, and continuous innovation. However, the market also includes numerous small to medium-sized enterprises (SMEs) and emerging direct-to-consumer (DTC) brands that cater to niche segments and local markets. Key characteristics of the market include a strong emphasis on product functionality, driven by technological advancements in fabric and garment design. Sustainability and eco-friendliness are increasingly important, influencing consumer preferences and brand strategies. Additionally, the athleisure trend blurs the lines between activewear and casual wear, expanding the market’s appeal. The market's dynamism is fueled by constant innovation, evolving fashion trends, and growing consumer health consciousness. The market balances between established leaders and innovative newcomers, each contributing to its growth and evolution.
Report Coverage:
The research report offers an in-depth analysis based on By Product Type, By Consumer Orientation, By Material Type and By Sales Channel It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The workout clothes market is projected to continue its robust growth, driven by increasing global health and fitness awareness.
- Innovations in fabric technology, such as moisture-wicking, temperature regulation, and smart clothing, will enhance product functionality and appeal.
- A growing emphasis on sustainability will push brands to adopt eco-friendly materials and ethical manufacturing practices, meeting consumer demand for greener products.
- Personalized and customizable workout clothes will become more prevalent, catering to individual consumer preferences and needs.
- The rise of e-commerce and mobile commerce will further facilitate market growth, offering consumers convenient access to a wide range of products and brands.
- The blending of athletic wear with casual fashion will continue to drive demand, expanding the market beyond traditional workout settings.
- Rapid urbanization and rising disposable incomes in emerging markets, particularly in Asia-Pacific and Latin America, will present significant growth opportunities.
- Brands will focus on differentiation through innovation, design, and marketing strategies to stand out in a competitive market.
- The integration of health and wellness features in workout clothes, such as built-in sensors for fitness tracking, will gain traction among tech-savvy consumers.
- Collaborations between fitness influencers, celebrities, and brands will play a crucial role in shaping trends and driving consumer engagement.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Health and Fitness Awareness
Rising global awareness of health and fitness is leading more individuals to engage in regular exercise, driving demand for functional and comfortable workout clothes tailored to various physical activities.
Athleisure Trend
The blending of athletic and casual wear has expanded the use of workout clothes beyond the gym, increasing demand for versatile, stylish apparel that fits both active and everyday lifestyles.
Technological Advancements in Fabric and Design
Innovations such as moisture-wicking, anti-odor, and compression technologies are enhancing the performance, comfort, and appeal of workout clothes, encouraging consumers to upgrade their athletic wardrobes.
Growth of E-commerce and Digital Platforms
The expansion of online shopping and digital marketing has made workout clothes more accessible, allowing consumers to easily compare, customize, and purchase from a wide range of brands and styles.
Sustainability and Eco-Friendly Materials
Growing consumer preference for sustainable and ethically produced apparel is pushing brands to adopt eco-friendly materials and transparent manufacturing practices, further stimulating market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the workout clothes market?
What are the key drivers of growth in the workout clothes market?
Which regions are leading the workout clothes market?
What are the main challenges facing the workout clothes market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Activewear
- 1.2.2 Athleisure
- 1.2.3 Performance gear
- 1.3 By Material Type
- 1.3.1 Synthetic Fabrics
- 1.3.2 Natural Fabrics
- 1.3.3 Blended Fabrics
- 1.4 By Sales Channel
- 1.4.1 Online
- 1.4.2 Offline channels
- 1.5 By Consumer Orientation
- 1.5.1 Men
- 1.5.2 Women workout clothes
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 238195 million → 2032: USD 379933.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Workout Clothes Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Workout Clothes Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Workout Clothes Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Workout Clothes Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Workout Clothes Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Workout Clothes Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Workout Clothes Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Workout Clothes Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 238195 million → 2032: USD 379933.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Workout Clothes Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Activewear
- 12.3.7.2 Athleisure
- 12.3.7.3 Performance gear
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Synthetic Fabrics
- 12.4.7.2 Natural Fabrics
- 12.4.7.3 Blended Fabrics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Online
- 12.5.7.2 Offline channels
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Consumer Orientation - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Men
- 12.6.7.2 Women workout clothes
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Workout Clothes Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Workout Clothes Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Workout Clothes Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 NIKE, Inc
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Adidas AG
- 17.4 Under Armour, Inc
- 17.5 PUMA SE
- 17.6 ASICS Corporation
- 17.7 Columbia Sportswear Company
- 17.8 Gap Inc (Athleta)
- 17.9 Skechers USA, Inc
- 17.10 V.F. Corporation (The North Face, Inc.)
- 17.11 DICK'S Sporting Goods, Inc
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

