
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| X-Ray Equipment Market Size 2023 | USD 17512.2 Million |
| X-Ray Equipment Market, CAGR | 3.40% |
| X-Ray Equipment Market11 Size 2032 | USD 23660.58 Million |
Market Insights
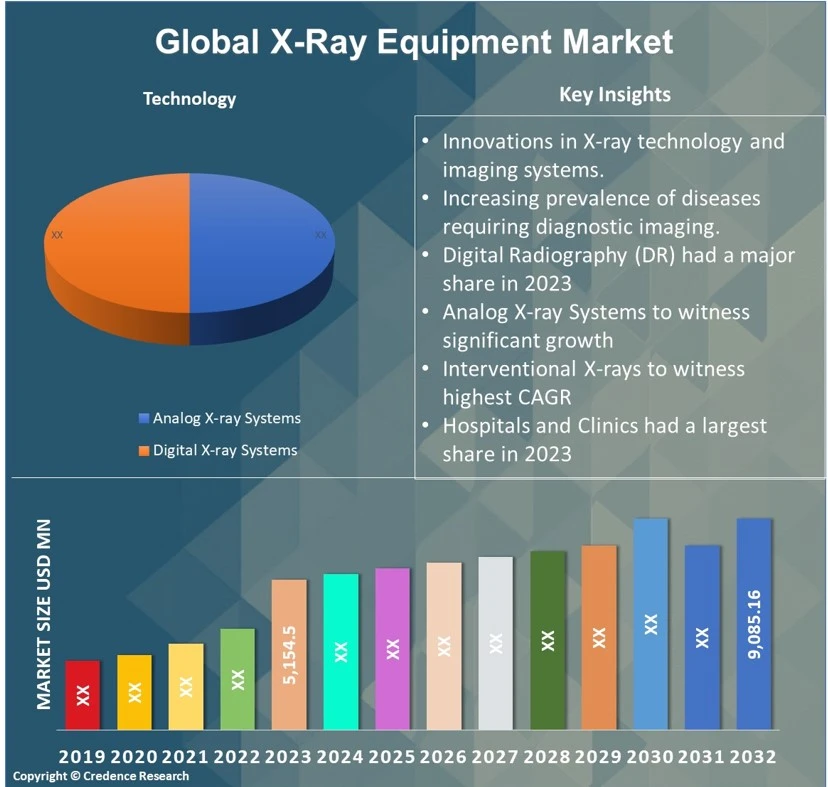
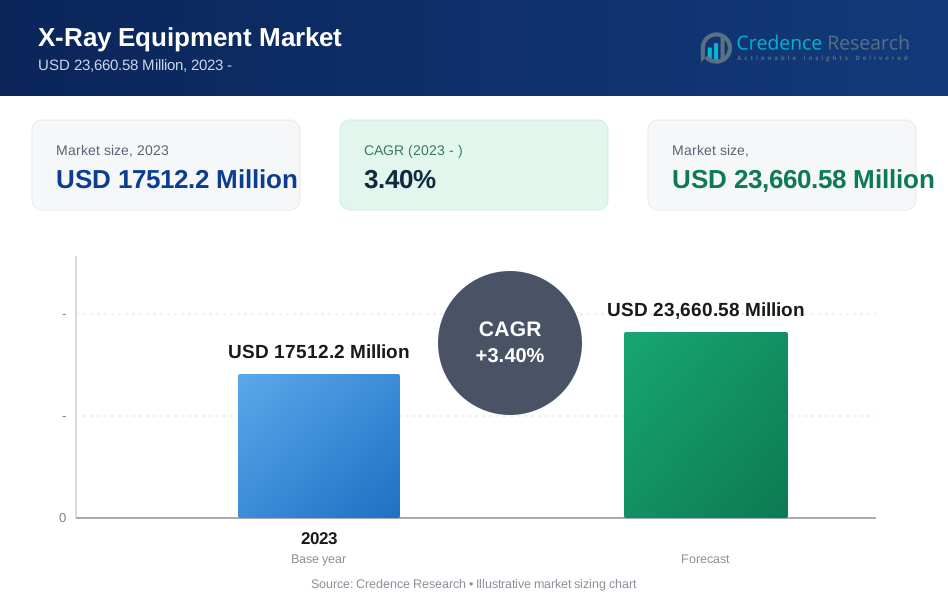
- The global demand for X-Ray Equipment was valued at USD 17512.2 Million in 2023 and is expected to reach USD 23660.58 Million in 2032, growing at a CAGR of 3.40% between 2024 and 2032.
- The Digital Radiography (DR) sector is the market leader by interface type, accounting for more than 31% of total value in 2023, while the Computed Tomography (CT) segment is expected to grow rapidly throughout the forecast period.
- The Analog X-ray Systems technology dominates the global need for X-Ray Equipment, accounting for more than 55% in 2023 and Digital X-ray Systems technology is predicted to expand at a high CAGR.
- The Interventional X-rays sector is predicted to grow fastest over the projection period, while the Diagnostic X-rays segment will have a market share of more than 25% in 2023.
- Over the projection period, the Diagnostic Imaging Centers end user is expected to expand at the highest rate, while the Hospitals and Clinics end user will dominate the market in 2023 with a 25% share.
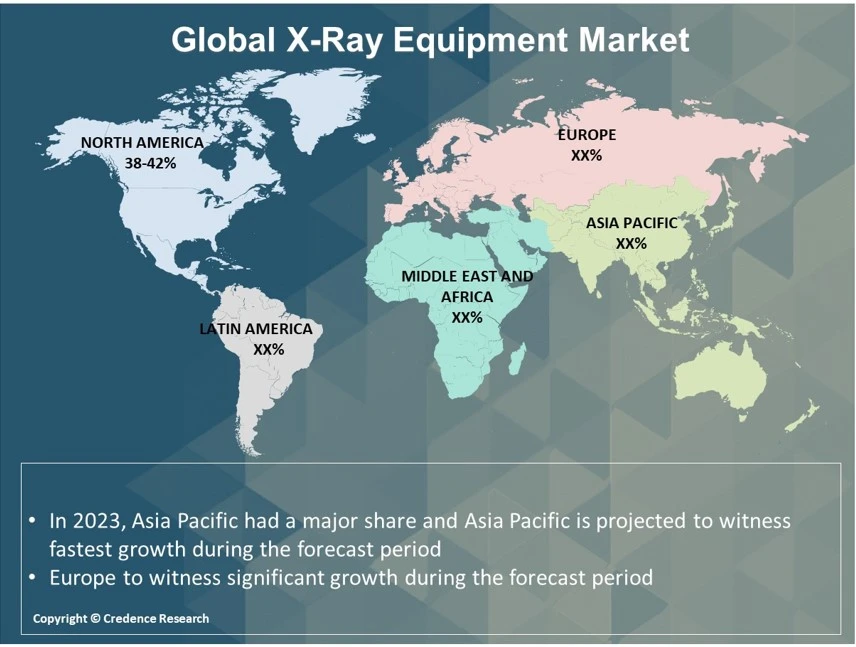
- North America is fueling the growth of the X-Ray Equipment industry with over one-third share in 2023, while Asia Pacific and Europe collectively account for just under 55% share in 2023. Europe held over 20% share in 2023.
- Due to rising incidence of chronic diseases, the market for X-Ray Equipment is driven by increasing awareness and health consciousness and increased adoption of X-Ray Equipment.
- The market's primary possibilities include the significant growth potential in North America, supportive government initiatives and policies.
Executive Summary
Market Definition
The X-ray equipment refers to a set of medical devices that utilize X-rays, which are a form of electromagnetic radiation, for diagnostic or therapeutic purposes. These devices are widely used in the field of medical imaging to visualize the internal structures of the human body. The basic components of X-ray equipment include an X-ray tube, which produces the X-rays, and a detector, which captures the X-rays after they pass through the body. The interaction of X-rays with different tissues in the body results in varying levels of radiation absorption, creating detailed images of bones, organs, and other structures.
Market Overview
The global demand for X-Ray Equipment was valued at USD 17512.2 Million in 2023 and is expected to reach USD 23660.58 Million in 2032, growing at a CAGR of 3.40% between 2024 and 2032.The key driver boosting the growth rate of the X-Ray Equipment market is the advancements in technology play a crucial role. When scientists and engineers discover new ways to make X-ray machines better, like producing clearer images or making the equipment more portable, it encourages more people to use these machines for medical purposes.
Furthermore, the increase in chronic diseases, especially as people get older, leads to a higher demand for diagnostic tools like X-rays. As more individuals face health challenges, the need for accurate and quick medical imaging grows, boosting the overall demand for X-ray equipment. These factors, along with improvements in healthcare infrastructure, awareness campaigns, and government support, contribute to the expansion of the X-ray equipment market.
In addition, the increasing investments in research and development and the miniaturization of X-ray equipment will create several new opportunities for the X-Ray Equipment market to expand during the time covered by the estimate.
Segmentation by Type of X-ray Equipment
- Digital Radiography (DR) is the leading segment by interface type and held over 31% share in value in 2023, attributable to the increasing prevalence of diseases requiring diagnostic imaging.
- The Computed Tomography (CT) segment will likely exhibit a significant CAGR during the forecast period. Growth in public awareness campaigns in driving demand for diagnostic services.
- Portable/Handheld X-ray Devices is another segment but contributes very little to the global X-Ray Equipment market compared to the Digital Radiography (DR), and Computed Tomography (CT) segments.
Segmentation by Technology
- The Analog X-ray Systems segment governs the demand for X-Ray Equipment in the world, holding a massive share of over 55% in 2023, and Digital X-ray Systems is also expected to grow at a rapid CAGR because influence of government policies on the adoption and accessibility of X-ray equipment. In addition, the rising R&D investments on product innovation and market growth.
- The Digital X-ray Systems sectors segment contributes to the demand for X-Ray Equipment during the forecast period.
Segmentation by Application
- The Interventional X-rays segment is expected to post the highest CAGR during the forecast period. This is primarily due to globalization in expanding the market for X-ray equipment.
- The Diagnostic X-rays segment is leading the market share with over 25% share in 2023.
Segmentation by End-User
- The diagnostic imaging centers segment is anticipated to register the highest CAGR during the projection period.
- With a market share of nearly 25% in 2023, the hospitals and clinics category is currently in the lead.
- The other end-user of X-Ray equipment includes ambulatory surgical centers, and emergency care centers.
Segmentation by Region
- North America is fueling the growth of the X-Ray Equipment industry with over one-third share in 2023 due to the supportive government policies on the adoption and accessibility of X-ray equipment.
- Asia Pacific and Europe collectively account for just under 55% share in 2023, with Europe holding over 20% share in the same year.
- The rest of the world, including Latin America, the Middle East, and Africa, supplies the remaining demand for X-Ray Equipment.
The market for X-Ray Equipment is driven by increasing prevalence of diseases requiring diagnostic imaging and growth potential in developing regions with expanding healthcare facilities.
North America is a dominating region in the global X-ray equipment market, driven by a combination of advanced healthcare infrastructure, a high prevalence of chronic diseases, and robust technological advancements. The region's well-established medical facilities and a strong emphasis on adopting cutting-edge diagnostic technologies contribute to the significant market share. Moreover, the presence of leading manufacturers and continuous investments in research and development further solidify North America's leadership position. The demand for sophisticated imaging solutions in the diagnosis and treatment of various medical conditions, coupled with a growing aging population, continues to propel the X-ray equipment market forward in this region.
The Asia Pacific is expected to be the fastest-growing region over the forecast period. The growth is fueled by factors such as increasing healthcare awareness, rising disposable income, and substantial investments in healthcare infrastructure. Developing economies within Asia Pacific are witnessing a surge in demand for medical imaging technologies, including X-ray equipment, as they strive to enhance their healthcare capabilities. The rapid urbanization and lifestyle changes in the region contribute to the growing incidence of chronic diseases, boosting the need for advanced diagnostic tools. Furthermore, supportive government initiatives, collaborations with global healthcare organizations, and the adoption of innovative technologies drive the expansion of the X-ray equipment market in the Asia Pacific region.
The primary factor driving the X-Ray Equipment market's growth rate is the advancements in technology play a crucial role. When scientists and engineers discover new ways to make X-ray machines better, like producing clearer images or making the equipment more portable, it encourages more people to use these machines for medical purposes.
Key Highlights of the Report
The global X-Ray Equipment market is segmented by type of x-ray equipment, technology, application, end-user, and region. Digital Radiography (DR)-based X-Ray Equipment are the most popular, while computed tomography (CT), and fluoroscopy are the primary segments. In addition, Analog X-ray Systems and Diagnostic X-rays are the most commonly used categories. However, Hospitals and Clinics dominate the market, with North America leading the market growth.
One of the main factors propelling the global market for X-Ray Equipment is the increase in chronic diseases, especially as people get older, leads to a higher demand for diagnostic tools like X-rays. As more individuals face health challenges, the need for accurate and quick medical imaging grows, boosting the overall demand for X-ray equipment. These factors, along with improvements in healthcare infrastructure, awareness campaigns, and government support, contribute to the expansion of the X-ray equipment market.
Nonetheless, North America is anticipated to have the greatest share of the worldwide X-Ray Equipment market because of the supportive government policies on the adoption and accessibility of X-ray equipment. Furthermore, the market is anticipated to expand at the highest rate in the Asia-Pacific (APAC) region due to the growth potential in developing regions with expanding healthcare facilities.
What Are The Main Drivers Of The Global X-Ray Equipment Market?
The main drivers of the global X-ray equipment market are multifaceted, encompassing technological advancements, increasing prevalence of chronic diseases, an aging population, global healthcare infrastructure development, and growing awareness and health consciousness. Continuous innovations in X-ray technology, such as enhanced imaging capabilities and the integration of artificial intelligence, play a pivotal role in driving market growth. The rising incidence of chronic diseases, particularly cardiovascular conditions and cancer, fuels the demand for diagnostic imaging services, contributing to the widespread adoption of X-ray equipment.
What Are The Major Challenges Faced By The Global X-Ray Equipment Market?
The global X-ray equipment market faces major challenges such as the high cost associated with acquiring and maintaining advanced X-ray equipment poses a significant barrier, particularly for healthcare facilities in resource-limited settings. Concerns about radiation exposure, despite safety measures, persist and lead to increased scrutiny and the need for ongoing safety improvements.
What Are The Growth Opportunities In The Global X-Ray Equipment Market?
Expanding market presence in emerging economies, driven by increasing healthcare investments and rising demand for diagnostic services, presents a significant avenue for growth. Continued investment in research and development for advanced imaging technologies, such as 3D and 4D imaging, offers opportunities for market expansion and product differentiation.
Market Drivers
The global X-Ray Equipment market is driven by several factors. The following are the key drivers of the global X-Ray Equipment market:
Technological Advancements and Innovation
The global X-ray equipment market is growing due to the continuous progress in technological advancements and innovation. Ongoing developments in X-ray technology, including improvements in imaging resolution, faster scanning times, and the integration of artificial intelligence (AI), enhance the diagnostic capabilities of X-ray equipment. Advanced features contribute to more accurate and efficient diagnoses, driving the adoption of X-ray equipment in medical facilities. The incorporation of innovative technologies not only improves the quality of medical imaging but also positions manufacturers at the forefront of market competition.
Market Restraints
The global X-Ray Equipment market faces some challenges that may hinder its growth. These include the following:
High Cost of Acquisition and Maintenance
The global X-ray equipment market is hampered by the high cost associated with acquiring and maintaining advanced X-ray machines. The initial investment required for purchasing state-of-the-art equipment and the ongoing expenses for maintenance and upgrades can be a significant financial burden for healthcare facilities, particularly in resource-limited settings. The cost factor poses challenges to widespread adoption, limiting access to advanced diagnostic services in certain regions and impacting the overall market penetration of X-ray equipment.
Opportunities
The global X-Ray Equipment market offers significant growth opportunities. These include the following:
Expansion in Emerging Markets
Growth in the global X-ray equipment market lies in expanding market presence in emerging economies. Increasing healthcare investments, rising disposable income, and growing awareness of the importance of early disease detection create a conducive environment for market expansion. As these regions focus on enhancing their healthcare infrastructure, there is an increased demand for advanced diagnostic services, providing a significant growth opportunity for X-ray equipment manufacturers. Capitalizing on the untapped potential in emerging markets can lead to increased sales and a broader market reach for X-ray equipment providers.
Competitive Landscape
Key Players
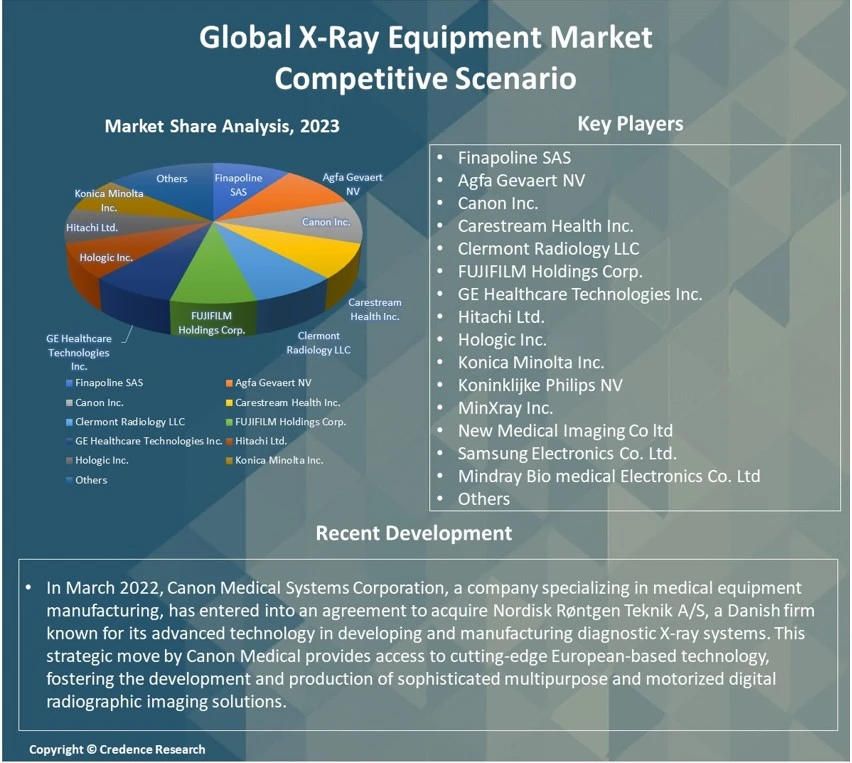
The global X-Ray Equipment market is highly competitive, with several key players. Some of the major players in the market and their market share are as follows:
- Finapoline SAS
- Agfa Gevaert NV
- Canon Inc.
- Carestream Health Inc.
- Clermont Radiology LLC
- FUJIFILM Holdings Corp.
- GE Healthcare Technologies Inc.
- Hitachi Ltd.
- Hologic Inc.
- Konica Minolta Inc.
- Koninklijke Philips NV
- MinXray Inc.
- New Medical Imaging Co ltd
- Samsung Electronics Co. Ltd.
- Mindray Bio medical Electronics Co. Ltd
- Others
These organizations prioritize product innovation, distribution channel expansion, and mergers and acquisitions to stay competitive.
The global X-Ray Equipment market's key players continually seek to stay ahead by offering new products and developments.
In March 2022, Canon Medical Systems Corporation, a company specializing in medical equipment manufacturing, has entered into an agreement to acquire Nordisk Røntgen Teknik A/S, a Danish firm known for its advanced technology in developing and manufacturing diagnostic X-ray systems. This strategic move by Canon Medical provides access to cutting-edge European-based technology, fostering the development and production of sophisticated multipurpose and motorized digital radiographic imaging solutions.
In May 2022, Carestream Health, a global provider of medical imaging systems and a subsidiary of Onex Corporation, has introduced Smart Noise Cancellation (SNC), a revolutionary artificial intelligence (AI)-based technology designed to significantly enhance image quality. This innovation results in images that are notably clearer compared to those produced through standard processing. SNC has received FDA 510(k) Clearance and is now available as an optional feature within Carestream’s ImageView Software, powered by Eclipse. This breakthrough technology marks a significant advancement in medical imaging, further reinforcing Carestream Health's commitment to delivering state-of-the-art solutions.
Summary of Key Findings
- The demand for x-ray equipment is rising due to the ongoing technological advancements play a pivotal role, with continuous innovations enhancing imaging capabilities, resolution, and the integration of artificial intelligence. The increasing prevalence of chronic diseases, such as cardiovascular conditions and cancer, which is boosting the growth of the X-Ray Equipment market.
- Market segmented by type of x-ray equipment, technology, application, end-user, and region.
- Digital Radiography (DR)-based X-Ray Equipment are the most popular, with innovations in X-ray technology and imaging systems.
- Analog X-ray Systems are most commonly used for devices.
- North America is leading market growth; the market is highly competitive with key players including Finapoline SAS, Agfa Gevaert NV, Canon Inc., Carestream Health Inc., Clermont Radiology LLC, FUJIFILM Holdings Corp., GE Healthcare Technologies Inc., Hitachi Ltd., Hologic Inc., Konica Minolta Inc., Koninklijke Philips NV, MinXray Inc., New Medical Imaging Co ltd, Samsung Electronics Co. Ltd., Mindray Bio medical Electronics Co. Ltd, and Others.
Future Outlook
- Positive outlook for the global X-Ray Equipment market with significant growth potential in the North American region
- One of the main factors promoting the market's expansion is the government and business sectors' current reliance on X-Ray Equipment.
- During the forecast period, high cost of equipment is a significant factor projected to restrain the growth of the X-Ray Equipment market.
- Key firms must focus on product innovation, growing market reach, and maintaining competitive pricing to keep ahead of the competition.
How CXOs Can Benefit from the Credence Research X-Ray Equipment Market Report
The Credence Research X-Ray Equipment Market Report provides CXOs with a comprehensive overview of the market, including:
- Market size and growth forecast: The report provides detailed estimates of the global X-Ray Equipment market size, segmented by type of x-ray equipment, technology, application, end-user, and region. It also includes forecasts for the market through 2032, based on key trends and drivers.
- Market segmentation: The report segments the X-Ray Equipment market by type of x-ray equipment, technology, application, end-user, and region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive landscape: The report profiles the key players in the X-Ray Equipment market and provides insights into their strategies, product offerings, and financial performance. This information can help CXOs to identify and assess their competition.
- Key trends and drivers: The report identifies and analyzes the key trends and drivers that are shaping the X-Ray Equipment This information can help CXOs to make informed decisions about their investments and strategies.
CXOs can use the insights from the Credence Research X-Ray Equipment Market Report to:
- Identify growth opportunities: The report can help CXOs to identify new growth opportunities in the X-Ray Equipment For example, the report identifies the growing demand for X-Ray Equipment from equipment providers and hospitals and clinics as a key opportunity.
- Make informed investment decisions: The report can help CXOs to make informed investment decisions about X-Ray Equipment. For example, the report provides insights into the key factors to consider when evaluating X-Ray Equipment providers and selecting X-Ray Equipment
- Develop competitive strategies: The report can help CXOs to develop competitive strategies for their X-Ray Equipment For example, the report identifies the key strategies that X-Ray Equipment providers are using to differentiate themselves from their competitors.
- Track market developments: The report can help CXOs to track market developments and stay ahead of the curve. For example, the report provides insights into the latest trends and innovations in the X-Ray Equipment
Overall, the Credence Research X-Ray Equipment Market Report is a valuable resource for CXOs who are looking to gain a deeper understanding of the market and identify opportunities for growth.
Segmentation
- By Type of X-ray Equipment
- Digital Radiography (DR)
- Computed Tomography (CT)
- Fluoroscopy
- Mammography
- C-Arm Systems
- Portable/Handheld X-ray Devices
- By Technology
- Analog X-ray Systems
- Digital X-ray Systems
- By Application
- Diagnostic X-rays
- Interventional X-rays
- Mammography
- Computed Tomography (CT)
- By End-User
- Hospitals and Clinics
- Diagnostic Imaging Centers
- Ambulatory Surgical Centers
- Emergency Care Centers
- By Region
- North America
- The U.S,
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
- North America
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global X-Ray Equipment market?
What is the expected growth rate of the X-Ray Equipment market between 2024 and 2032?
Which segment is leading the market share in terms of type of x-ray equipment?
Which end users segment governs the demand for X-Ray Equipment in the world?
Which application segment is expected to post the highest CAGR during the forecast period?
Who are the major players in the global X-Ray Equipment market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 X-Ray Equipment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global X-Ray Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (the forecast period) (2023: USD 17512.2 Million → forecast year: USD 23,660.58 Million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 X-Ray Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. X-Ray Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 X-Ray Equipment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 X-Ray Equipment Market Drivers
- 3.3 X-Ray Equipment Market Restraints & Challenges
- 3.4 X-Ray Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 X-Ray Equipment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 X-Ray Equipment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, X-Ray Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 X-Ray Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. X-Ray Equipment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the X-Ray Equipment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 X-Ray Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 X-Ray Equipment Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 X-Ray Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in X-Ray Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New X-Ray Equipment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global X-Ray Equipment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America X-Ray Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe X-Ray Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific X-Ray Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America X-Ray Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East X-Ray Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa X-Ray Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. X-Ray Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
