
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
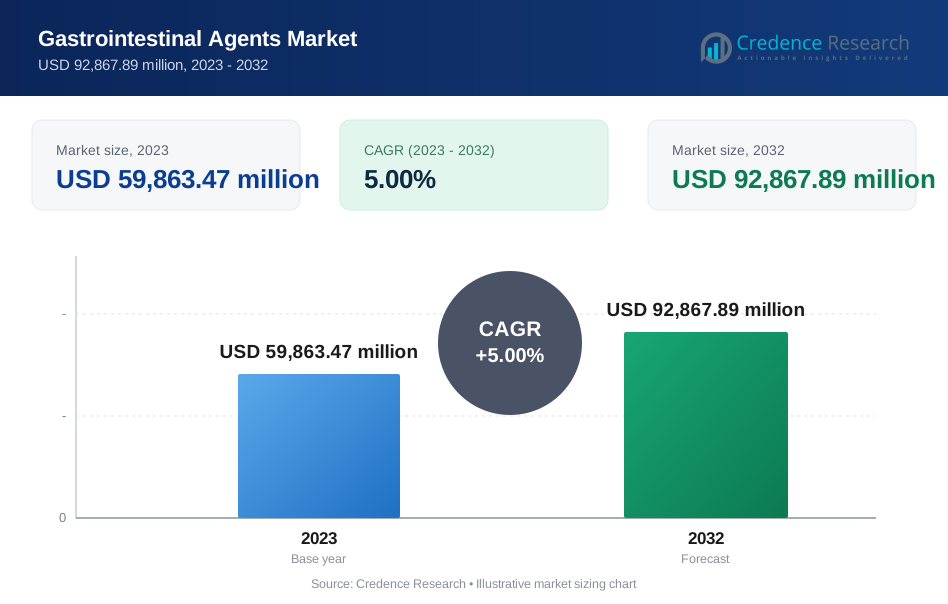
| Gastrointestinal Agents Market Size 2023 | USD 59,863.47 Million |
| Gastrointestinal Agents Market, CAGR | 5.00% |
| Gastrointestinal Agents Market Size 2032 | USD 92,867.89 Million |
Market Overview
The Gastrointestinal Agents Market is projected to grow from USD 59,863.47 million in 2023 to USD 92,867.89 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.00%.
The Gastrointestinal Agents Market is driven by the rising prevalence of gastrointestinal disorders such as irritable bowel syndrome, acid reflux, and inflammatory bowel disease, which increase the demand for effective treatments. Additionally, the aging global population, increasing awareness of gastrointestinal health, and a growing focus on preventive healthcare contribute to market expansion. Technological advancements in drug delivery systems and the development of novel therapeutics further enhance market growth. Moreover, the surge in lifestyle-related digestive disorders, driven by changing dietary habits and stress, continues to propel the demand for gastrointestinal agents worldwide.
The Global Gastrointestinal Agents Market exhibits significant geographical diversity, with North America and Europe holding the largest market shares due to high healthcare spending, advanced healthcare infrastructure, and a rising prevalence of gastrointestinal disorders. Asia-Pacific is expected to witness rapid growth, driven by increasing healthcare awareness, improving medical facilities, and a growing geriatric population. Key players dominating the market include Johnson & Johnson, Pfizer Inc., AstraZeneca, AbbVie Inc., and Takeda Pharmaceuticals. These companies leverage their extensive product portfolios, innovative drug development capabilities, and strategic partnerships to maintain a strong market presence and address the growing demand for gastrointestinal treatments.
Market Drivers
Advancements in Drug Development
Advancements in drug development are playing a crucial role in the growth of the gastrointestinal agents market. For example, the US Food and Drug Administration approved five new gastrointestinal targeted drugs in 2023, including for GERD, IBD, and colonoscopy prep. The introduction of novel therapies, including targeted treatments, biologics, and combination therapies, is providing more effective and personalized options for patients suffering from gastrointestinal disorders. These innovative treatments are designed to address specific disease mechanisms, improving efficacy and reducing side effects. Pharmaceutical companies are investing heavily in research and development to meet the unmet needs in gastrointestinal medicine. Increased R&D efforts are leading to the discovery of new therapeutic targets and the development of next-generation drugs, which are expected to drive market growth in the coming years.
Growing Awareness and Acceptance of Treatment
Increasing awareness and acceptance of gastrointestinal disorder treatments are contributing to market expansion. Improved patient education about the symptoms and management of gastrointestinal conditions is driving demand for medications. As patients become more informed about their treatment options, they are more likely to seek medical attention and adhere to prescribed therapies. Additionally, the stigma surrounding gastrointestinal disorders is diminishing, encouraging more individuals to seek help. This shift in perception is leading to higher diagnosis rates and an increased willingness to use pharmaceutical interventions, boosting the market for gastrointestinal agents.
Economic Growth and Rising Healthcare Spending
Economic growth and rising healthcare spending are also propelling the Global Gastrointestinal Agents Market. As disposable incomes increase, particularly in developing countries, people are allocating more funds toward healthcare, including the treatment of gastrointestinal conditions. For instance, overall direct healthcare costs for GI diseases are estimated to be $136 billion each year in the U.S., more than heart disease ($113bn) and mental health disorders ($99bn). Expanding healthcare infrastructure in these regions is improving access to healthcare facilities and services, making it easier for patients to receive the care they need. Furthermore, favorable regulatory environments, including drug approvals and supportive reimbursement policies, are encouraging the adoption of new gastrointestinal agents. These factors are creating a conducive environment for market growth, enabling pharmaceutical companies to expand their reach and provide advanced treatment options to a broader patient population.
Increasing Prevalence of Gastrointestinal Disorders
The rising prevalence of gastrointestinal disorders is a significant driver of the Global Gastrointestinal Agents Market. Factors such as unhealthy diets and sedentary lifestyles are contributing to an increase in obesity-related gastrointestinal issues. As obesity rates climb, the incidence of conditions like acid reflux, gastroesophageal reflux disease (GERD), and non-alcoholic fatty liver disease (NAFLD) is also on the rise. Additionally, the aging global population is experiencing higher rates of gastrointestinal diseases, including irritable bowel syndrome (IBS) and inflammatory bowel disease (IBD). Older adults are more susceptible to these conditions due to age-related changes in gastrointestinal function. Elevated stress levels, irregular eating habits, and excessive alcohol consumption further exacerbate gastrointestinal problems, highlighting the need for effective treatment options.
Market Trends
Shift Towards Personalized Medicine and Biologics
The Global Gastrointestinal Agents Market is experiencing a significant shift towards personalized medicine, driven by advancements in genomics and proteomics. For instance, the shift towards personalized medicine and biologics in the Global Gastrointestinal Agents Market is evident in the FDA’s approval of 19 personalized medicines in 2020, representing approximately 39 percent of all newly approved therapeutic molecular entities. These scientific fields are enabling the development of highly targeted therapies tailored to individual patient needs, offering more effective and precise treatment options. The identification of specific biomarkers plays a critical role in facilitating early diagnosis and customized treatment approaches, allowing healthcare providers to predict disease progression and response to therapy more accurately. This personalized approach not only enhances treatment efficacy but also minimizes side effects, improving overall patient outcomes. Alongside personalized medicine, there is an increased use of biologics in the treatment of gastrointestinal disorders. Biologics, including monoclonal antibodies and engineered proteins, are becoming increasingly prevalent, particularly in managing inflammatory bowel diseases such as Crohn’s disease and ulcerative colitis. These biologic therapies offer targeted action against specific pathways involved in the disease process, leading to better management of symptoms and disease progression. Immunotherapy approaches, such as checkpoint inhibitors and cellular therapies, are also being explored for the treatment of certain gastrointestinal cancers, offering new hope for patients with these challenging conditions.
Emphasis on Digital Health and Emerging Market Growth
Digital health technologies and telemedicine are revolutionizing the management of gastrointestinal disorders, offering innovative solutions for patient monitoring and care delivery. Remote monitoring tools enable healthcare providers to track patients' health metrics in real-time, improving adherence to treatment protocols and allowing for timely intervention when necessary. This approach not only enhances patient outcomes but also reduces healthcare costs by preventing complications and hospitalizations. Telemedicine consultations are expanding access to care, particularly in remote or underserved areas, where traditional healthcare services may be limited. By facilitating virtual consultations with specialists, telemedicine is improving the quality of care and patient satisfaction. Another critical trend in the gastrointestinal agents market is the growing focus on emerging markets. Developing countries are investing heavily in healthcare infrastructure, creating significant opportunities for market growth. With expanding healthcare access and rising disposable incomes, there is an increasing demand for effective gastrointestinal treatments. Moreover, the unmet need for these treatments in many emerging markets presents a substantial opportunity for pharmaceutical companies to introduce innovative therapies and capture market share.
Market Challenges Analysis
Complex Pathophysiology and Development Hurdles
The Global Gastrointestinal Agents Market faces significant challenges due to the complex pathophysiology of gastrointestinal diseases For instance, the complex pathophysiology of gastrointestinal diseases is evident in disorders like irritable bowel syndrome (IBS) and inflammatory bowel disease (IBD), which exhibit considerable heterogeneity in their symptoms, severity, and underlying causes. This complexity necessitates a multifaceted approach to treatment, which can complicate drug development. Additionally, many patients with gastrointestinal disorders suffer from co-morbidities, such as diabetes or cardiovascular diseases, which can further complicate treatment regimens and increase the risk of adverse effects. These co-existing health issues require careful consideration when developing new therapies, as they may influence drug efficacy and safety. The path to bringing new gastrointestinal agents to market is also fraught with high research and development (R&D) costs. Developing new drugs requires significant investment in clinical trials and research to ensure safety and efficacy. Regulatory challenges add another layer of difficulty, as obtaining approval from regulatory bodies involves meeting stringent requirements. This process can be lengthy and complex, delaying the introduction of innovative treatments to the market.
Adherence Issues and Access Barriers
Another major challenge in the Global Gastrointestinal Agents Market is adherence and compliance issues, which are common among patients with chronic gastrointestinal conditions. These diseases often require long-term treatment and strict adherence to medication regimens to manage symptoms and prevent flare-ups. However, side effects associated with gastrointestinal agents can lead to poor adherence, with patients discontinuing treatment due to discomfort or fear of adverse reactions. This non-compliance can result in suboptimal outcomes, disease progression, and increased healthcare costs. In addition to adherence challenges, access barriers pose a significant hurdle in the market. The high cost of certain gastrointestinal agents can limit access to treatment, particularly in countries with limited healthcare budgets. Cost pressures and budget constraints can make it difficult for healthcare systems to provide widespread access to the latest and most effective treatments. Reimbursement challenges further exacerbate access issues, as obtaining coverage for new drugs can be difficult, especially when healthcare budgets are strained, and there are competing priorities. These access barriers can prevent patients from receiving the care they need, underscoring the importance of addressing cost and reimbursement challenges to ensure broader access to effective gastrointestinal treatments.
Market Segmentation Analysis:
By Type:
The Global Gastrointestinal Agents Market is segmented into dietary supplements and drugs, with the latter further classified into various categories. Dietary supplements play a significant role in managing gastrointestinal health by promoting digestive function and preventing mild digestive disorders. On the other hand, drugs constitute a more extensive segment due to their critical role in treating specific gastrointestinal conditions. Key drug categories include antacids, which neutralize stomach acid to relieve heartburn; anti-diarrheal agents, which manage acute and chronic diarrhea; anti-emetics, which are used to prevent nausea and vomiting; H2 blockers, which reduce stomach acid production; laxatives, which alleviate constipation; and proton pump inhibitors, which are widely used to treat acid-related disorders by blocking acid production. Each drug category addresses different aspects of gastrointestinal disorders, catering to a wide range of patient needs and conditions, making them indispensable in gastrointestinal healthcare.
By Disease Type:
The Global Gastrointestinal Agents Market is also segmented based on disease type, including constipation, diarrhea, gastroesophageal reflux disease (GERD), inflammatory bowel disease (IBD), and peptic ulcer disease. Constipation is a common condition requiring effective management to prevent complications, while diarrhea, both acute and chronic, necessitates prompt treatment to avoid dehydration and other health issues. GERD, characterized by chronic acid reflux, demands effective acid suppression and mucosal protection strategies. Inflammatory bowel disease, encompassing Crohn's disease and ulcerative colitis, requires comprehensive treatment approaches, including immunosuppressants and biologics, to manage inflammation and prevent disease progression. Peptic ulcer disease, caused by Helicobacter pylori infection and NSAID use, relies on a combination of antibiotics, acid suppressants, and lifestyle modifications for management. Each disease type has specific therapeutic needs, driving the demand for diverse gastrointestinal agents tailored to address these varied conditions effectively.
Segments:
Based on Type:
- Dietary Supplements
- Drugs
- Antacids
- Anti-diarrheal Agents
- Anti-emetics
- H2 Blockers
- Laxatives
- Proton Pump Inhibitors
Based on Disease Type:
- Constipation
- Diarrhoea
- Gastroesophageal Reflux Disease
- Inflammatory Bowel Disease
- Peptic Ulcer Disease
Based on Route of Administration:
- Oral
- Parenteral
- Rectal
Based on End-User:
- Homecare
- Hospitals & Clinics
Based on Distribution Channel:
- Offline Pharmacies
- Online Pharmacies
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America leads the global gastrointestinal agents market with a dominant market share of approximately 45%. This substantial presence is primarily attributed to the high prevalence of gastrointestinal disorders in the region, coupled with advanced healthcare infrastructure and robust reimbursement policies. As per the National Institute of Diabetes and Digestive and Kidney Diseases, 60 to 70 million people are affected by all digestive diseases. Conditions such as gastroesophageal reflux disease (GERD), irritable bowel syndrome (IBS), and inflammatory bowel diseases (IBD) are prevalent, with IBD affecting between 2.4 and 3.1 million people. The United States, in particular, drives significant market growth due to its large patient population suffering from conditions such as gastroesophageal reflux disease (GERD), irritable bowel syndrome (IBS), and inflammatory bowel diseases (IBD). The region's market is characterized by a strong focus on innovative drug development, with major pharmaceutical companies investing heavily in research and development of novel gastrointestinal agents. Additionally, the increasing adoption of over-the-counter (OTC) gastrointestinal medications and the rising awareness about digestive health among consumers contribute to the market's expansion. The North American market also benefits from a favorable regulatory environment that facilitates faster approval processes for new drugs, further stimulating market growth.
Asia-Pacific
Asia-Pacific holds the second-largest share in the global gastrointestinal agents market, accounting for approximately 25% of the total market. This region's market is driven by its large population base, rapidly improving healthcare infrastructure, and increasing disposable incomes, particularly in countries like China and India. The growing prevalence of gastrointestinal disorders, partly due to changing dietary habits and lifestyles, fuels the demand for effective treatments. The Asia-Pacific market is characterized by a rising trend in medical tourism, especially for advanced gastrointestinal treatments, which contributes to market growth. Additionally, the region sees increasing government initiatives to improve healthcare accessibility and affordability, further boosting the market for gastrointestinal agents. The market in this region also benefits from the growing presence of both local and international pharmaceutical companies, leading to increased competition and broader availability of gastrointestinal medications.
Key Player Analysis
- Johnson & Johnson
- Pfizer Inc.
- AstraZeneca
- AbbVie Inc.
- Takeda Pharmaceuticals
- Bayer AG
- GlaxoSmithKline plc.
- Sanofi
- Allergan
- Boehringer Ingelheim
Competitive Analysis
The Global Gastrointestinal Agents Market is highly competitive, with leading players such as Johnson & Johnson, Pfizer Inc., AstraZeneca, AbbVie Inc., and Takeda Pharmaceuticals dominating the landscape. These companies maintain strong market positions through comprehensive product portfolios that address a wide range of gastrointestinal disorders, including irritable bowel syndrome (IBS), inflammatory bowel disease (IBD), and gastroesophageal reflux disease (GERD). They focus heavily on research and development to bring innovative and effective treatments to market, including biologics and targeted therapies. Strategic acquisitions, partnerships, and collaborations are also common strategies used by these companies to expand their market presence and enhance their product offerings. Additionally, their strong global distribution networks and significant investments in marketing and patient education initiatives help them capture a larger share of the market. As competition intensifies, these market leaders continue to prioritize innovation, regulatory compliance, and strategic expansion to maintain their leadership positions in the gastrointestinal agents market.
Recent Developments
- In October 2023, Janssen Pharmaceuticals, a Johnson & Johnson Company, announced new data from the QUASAR Phase 3 Induction Study demonstrating the efficacy and safety profile of TREMFYA® (guselkumab), a selective IL-23 p19 inhibitor, in patients with moderately to severely active ulcerative colitis.
- In October 2023, Pfizer announced that the U.S. Food and Drug Administration (FDA) has approved VELSIPITY™ (etrasimod), an oral, once-daily, selective sphingosine-1-phosphate (S1P) receptor modulator for adults with moderately to severely active ulcerative colitis.
- In June 2023, AstraZeneca presented data for Imfinzi (durvalumab) combinations from the HIMALAYA and TOPAZ-1 Phase III trials at the European Association for the Study of the Liver’s International Liver Congress 2022 (EASL 2022) and the European Society for Medical Oncology’s World Congress on Gastrointestinal Cancer (ESMO World GI 2022).
- In October 2023, Sanofi and Teva announced an exclusive collaboration to deliver inflammatory bowel disease treatment. TEV’574, a novel anti-TL1A therapy, is being developed to treat ulcerative colitis and Crohn’s disease.
Market Concentration & Characteristics
The Global Gastrointestinal Agents Market is characterized by a moderate to high level of market concentration, with a few dominant multinational corporations holding substantial market shares. Key players such as Johnson & Johnson, Pfizer Inc., and AstraZeneca leverage their extensive research and development capabilities, diverse product portfolios, and strong brand recognition to maintain competitive advantages. The market is marked by a continuous influx of innovative products, including biologics and targeted therapies, aimed at addressing unmet medical needs and improving patient outcomes. Additionally, the market is shaped by regulatory frameworks that ensure the safety and efficacy of gastrointestinal agents, posing both opportunities and challenges for new entrants. The demand for effective treatment options is further fueled by the rising prevalence of gastrointestinal disorders, aging populations, and lifestyle-related factors. The presence of numerous smaller players also contributes to the competitive landscape, driving ongoing innovation and diversification within the market.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Disease Type, Route of Administration, End-User, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Global Gastrointestinal Agents Market is expected to grow steadily, driven by the increasing prevalence of gastrointestinal disorders worldwide.
- Advancements in drug development, particularly in biologics and targeted therapies, will enhance treatment options and improve patient outcomes.
- Personalized medicine approaches will become more prevalent, with therapies tailored to individual patient needs based on genetic and biomarker profiles.
- The demand for over-the-counter gastrointestinal agents will rise as consumer awareness and self-medication practices increase.
- Digital health technologies and telemedicine will play a growing role in monitoring and managing gastrointestinal conditions, improving patient adherence and care.
- Emerging markets will present significant growth opportunities due to expanding healthcare infrastructure and rising disposable incomes.
- The market will see increased competition from biosimilars, offering cost-effective alternatives to branded biologics.
- Companies will focus on patient-centered care, emphasizing quality of life and long-term disease management in their product offerings.
- Regulatory challenges and high R&D costs will remain significant hurdles, necessitating strategic partnerships and innovation to stay competitive.
- The shift towards preventative care and early intervention will drive demand for diagnostic tools and early-stage treatment options in gastrointestinal medicine.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Gastrointestinal Agents Market?
What factors are driving the growth of the Global Gastrointestinal Agents Market?
What are the key segments within the Global Gastrointestinal Agents Market?
What are some challenges faced by the Global Gastrointestinal Agents Market?
Who are the major players in the Global Gastrointestinal Agents Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Gastrointestinal Agents Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Gastrointestinal Agents Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 59,863.47 million → 2032: USD 92,867.89 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Gastrointestinal Agents Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Gastrointestinal Agents Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Gastrointestinal Agents Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Gastrointestinal Agents Market Drivers
- 3.3 Gastrointestinal Agents Market Restraints & Challenges
- 3.4 Gastrointestinal Agents Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Gastrointestinal Agents Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Gastrointestinal Agents Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Gastrointestinal Agents category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Gastrointestinal Agents Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Gastrointestinal Agents Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Gastrointestinal Agents market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Gastrointestinal Agents Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Gastrointestinal Agents Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Gastrointestinal Agents Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Gastrointestinal Agents (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Gastrointestinal Agents Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Gastrointestinal Agents Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Gastrointestinal Agents Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Gastrointestinal Agents Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Gastrointestinal Agents Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Gastrointestinal Agents Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Gastrointestinal Agents Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Gastrointestinal Agents Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Gastrointestinal Agents Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
