
Dental Diagnostic And Surgical Market Overview:
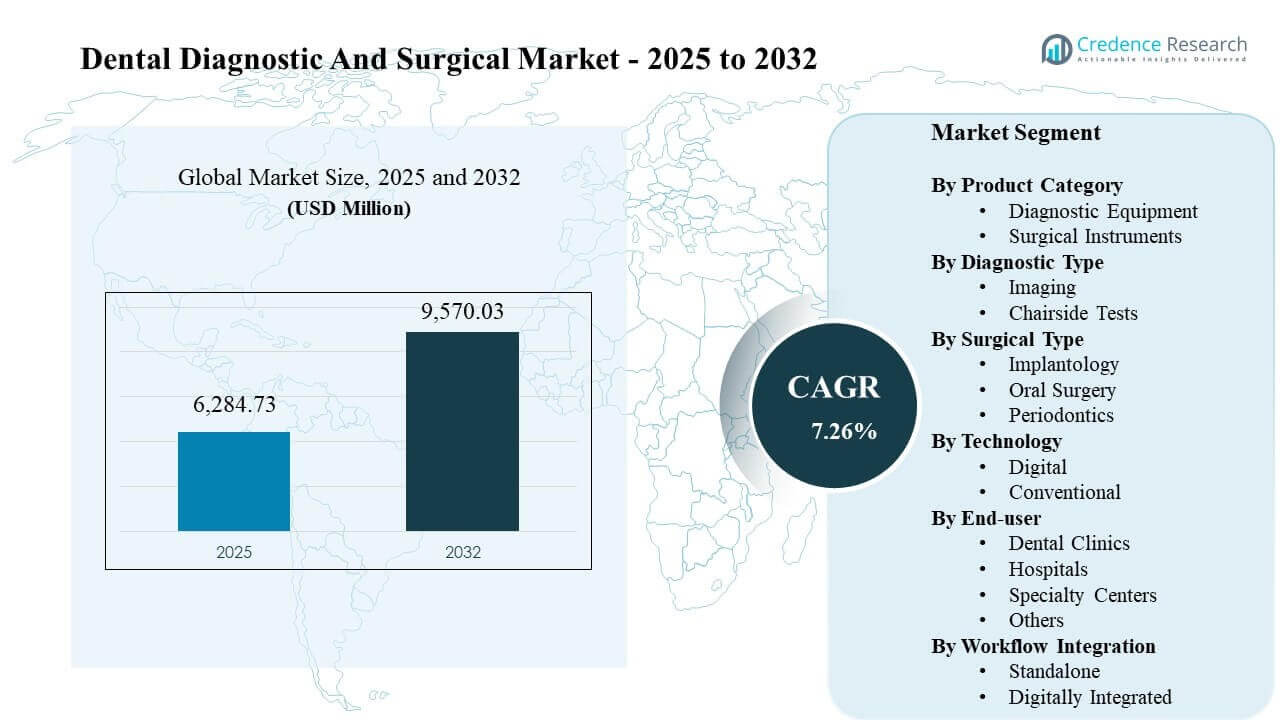
The global Dental Diagnostic And Surgical Equipment Market size was estimated at USD 6,284.73 million in 2025 and is expected to reach USD 9,570.03 million by 2032, growing at a CAGR of 7.26% from 2025 to 2032. Demand is being driven by faster adoption of digitally enabled diagnosis and treatment planning that improves clinical consistency, reduces chair time, and supports higher case acceptance for complex procedures. Asia Pacific is expanding the installed base through new clinic openings and modernization, supporting sustained equipment replacement and upgrade cycles across diagnostics and surgery.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Dental Diagnostic And Surgical Equipment Market Size 2025 | USD 6,284.73 million |
| Dental Diagnostic And Surgical Equipment Market, CAGR | 7.26% |
| Dental Diagnostic And Surgical Equipment Market Size 2032 | USD 9,570.03 million |
Key Market Trends & Insights
- North America accounted for 46.3% of 2025 revenue, reflecting strong purchasing power and faster refresh cycles for advanced diagnostic and surgical platforms.
- Diagnostic Equipment represented 41.6% of 2025 revenue, supported by rising screening volumes and higher utilization of imaging-led workflows in general dentistry.
- Surgical Instruments held 58.4% of 2025 revenue, supported by sustained procedure throughput across implantology, oral surgery, and periodontal interventions.
- Digital technology contributed 63.7% of 2025 revenue, reflecting workflow gains from connected software, guided planning, and improved documentation.
- Imaging accounted for 69.2% of 2025 diagnostic demand, reinforcing the central role of radiography and 3D imaging in treatment planning and surgical preparation.
Segment Analysis
Dental Diagnostic And Surgical Market demand is increasingly shaped by digitally integrated clinical pathways that connect diagnosis, planning, and procedure execution. Imaging-led workflows and software-driven planning are supporting higher standardization, better case documentation, and improved patient communication, which strengthens adoption in multi-chair clinics and growing group practices. Chairside testing continues to expand as practices prioritize same-visit decisions and stronger preventive positioning, especially where diagnostic confidence affects treatment acceptance.
Growth is also supported by procedure mix shift toward implantology and complex restorative care, which increases the need for reliable diagnostics, guided surgery tools, and high-precision instrumentation. Dental clinics remain the primary buying center because routine diagnostics and elective procedures are concentrated in outpatient settings, while hospitals and specialty centers contribute through complex-case volumes and advanced imaging utilization. Digitally integrated systems are gaining preference where practices seek predictable outcomes, faster throughput, and consistent clinical protocols across providers.
By Product Category Insights
Surgical Instruments accounted for the largest share of 58.4% in 2025. Higher procedure volumes in implantology and oral surgery continue to support steady utilization and replacement of surgical kits, hand instruments, and procedure-specific tools. Standardization of surgical protocols in high-throughput clinics encourages purchases of comprehensive instrument sets. Integration of guided planning with execution is also increasing demand for compatible surgical accessories that align with digital workflows.
By Diagnostic Type Insights
Imaging accounted for the largest share of 69.2% in 2025. Imaging remains the primary entry point for diagnosis and treatment planning, particularly for implant placement, oral surgery assessment, and periodontal evaluation. Practices are prioritizing faster scans, clearer visualization, and software-enabled interpretation to improve clinical confidence. Imaging-led communication also supports higher treatment acceptance by helping patients understand pathology and procedural need.
By Surgical Type Insights
Implantology accounted for the largest share of 46.8% in 2025. Implant workflows depend on pre-surgical diagnostics, guided planning, and precise instrumentation, which sustains robust equipment and instrument demand. Case complexity is increasing as more practices address compromised bone conditions, creating pull-through for planning tools and specialized surgical kits. Patient expectations for predictable outcomes also favor solutions that support guided placement and standardized protocols.
By Technology Insights
Digital accounted for the largest share of 63.7% in 2025. Digital platforms help reduce rework through better visualization, consistent documentation, and streamlined treatment planning. Software-enabled workflows support quicker clinical decisions and improve coordination across diagnosis and surgery. The move toward data-driven dentistry is also strengthening demand for connected systems that can support multi-site operations and consistent clinical standards.
By End-user Insights
Dental Clinics accounted for the largest share of 56.4% in 2025. High patient throughput and routine diagnostic needs make clinics the primary purchase channel for both diagnostic and surgical solutions. Clinic owners often prioritize solutions that improve chair utilization, enhance case acceptance, and reduce referral leakage for procedures that can be performed in-house. Growth of specialty-focused clinics also increases demand for advanced imaging and procedure-ready instrument systems.
By Workflow Integration Insights
Digitally Integrated accounted for the largest share of 61.2% in 2025. Integrated workflows improve continuity from diagnosis to planning and execution, which supports predictability and reduces operational friction. Practices adopting standardized protocols value systems that connect imaging, planning software, and compatible procedural tools. Multi-site providers also favor integration because centralized data management supports consistent clinical oversight and more repeatable outcomes.
Dental Diagnostic And Surgical Market Drivers
Rising procedure complexity increases reliance on diagnosis-to-surgery workflows
Dental Diagnostic And Surgical Market growth is supported by higher volumes of procedures that require precise planning and execution. Implantology and oral surgery pathways rely on imaging for site assessment, risk screening, and guided preparation. Dental clinics are expanding in-house procedural capabilities to reduce referrals and retain revenue. Clinical teams are prioritizing tools that support predictable outcomes and consistent documentation across providers.
Digital dentistry adoption accelerates replacement and upgrade cycles
Dental Diagnostic And Surgical Market demand benefits from upgrades from conventional systems to digital platforms that improve throughput and clinical consistency. Digital solutions streamline image capture, treatment planning, and communication across teams. Integrated software reduces workflow friction and supports repeatable protocols, which is important for growing clinic networks. Technology refresh is reinforced by provider expectations for faster scans, better visualization, and efficient documentation.
- For instance, Align Technology’s iTero Element 5D scanner captures up to 6,000 frames per second and integrates near-infrared imaging (NIRI) for interproximal caries detection, improving diagnostic accuracy without radiation exposure.
Preventive care and screening demand expands baseline diagnostic utilization
Dental Diagnostic And Surgical Market utilization rises as practices place stronger emphasis on preventive and early detection services. Higher screening volumes increase the need for dependable diagnostic equipment and image-driven assessment. Diagnostics also support patient education, which improves acceptance of recommended procedures and follow-on treatments. The combination of routine checkups and growth in elective procedures strengthens recurring equipment use.
- For instance, Planmeca’s ProMax 3D Classic CBCT system supports low-dose imaging protocols with radiation doses reduced by up to 77% compared to standard modes, enabling frequent screening while maintaining diagnostic clarity.
Expansion of outpatient dentistry sustains equipment and instrument purchasing
Dental Diagnostic And Surgical Market growth is reinforced by continued expansion of outpatient delivery models. Dental clinics and specialty centers are increasing capacity and broadening service lines, which drives demand across diagnostics and surgery. Operational priorities such as chair time efficiency and consistent patient experience favor modern systems and standardized instrument sets. Procurement decisions increasingly consider workflow integration and long-term serviceability.
Dental Diagnostic And Surgical Market Challenges
Dental Diagnostic And Surgical Market expansion is constrained by capital budgeting pressure in smaller practices, especially when upgrades require multiple connected components. Purchasing decisions often depend on financing availability and predictable utilization, which can delay replacement cycles. Integration demands can also add complexity, particularly when legacy systems do not connect smoothly with newer software environments. Training requirements for advanced diagnostic and guided workflows can slow adoption in resource-limited settings.
- For instance, Dentsply Sirona’s Primescan intraoral scanner delivers scanning speeds of up to 1 million 3D points per second with high-accuracy full-arch scans, but clinics often require additional investment in compatible CAD/CAM systems and operator training programs that can extend over several days to achieve optimal workflow efficiency.
Dental Diagnostic And Surgical Market suppliers also face service and support expectations that rise with digitalization. Downtime risk becomes more costly when imaging, planning, and procedure workflows are tightly connected. Practices may hesitate to adopt fully integrated platforms if support coverage, interoperability, and upgrade pathways are unclear. Price sensitivity can remain high in emerging markets, which limits adoption of premium configurations despite clinical interest.
Dental Diagnostic And Surgical Market Trends and Opportunities
Dental Diagnostic And Surgical Market opportunity is expanding through digitally integrated ecosystems that connect imaging, planning, and procedure execution. Providers increasingly prefer solutions that reduce steps and standardize protocols, especially in multi-chair clinics and growing group practices. Software-driven enhancements, including decision support, are strengthening the value proposition of digital platforms. This trend supports recurring revenue models tied to updates, connectivity, and workflow optimization.
Dental Diagnostic And Surgical Market growth potential is also supported by expanding specialty services within outpatient settings. Clinics are investing in equipment that enables in-house implantology and complex restorative work, improving revenue capture and patient retention. Demand is rising for solutions that improve patient communication and case acceptance through clearer visualization and standardized treatment plans. Emerging markets offer expansion potential as clinic infrastructure modernizes and provider training improves.
- For instance, Align Technology’s iTero Lumina scanner combined with the cloud-based iTero Design Suite (powered by exocad) enables full CAD-in-the-cloud workflows and is designed to deliver up to 2x faster scanning than the iTero Element 5D system with an average tolerance of ±0.1, which supports chairside design, improved case presentation, and higher treatment acceptance in busy outpatient clinics.
Regional Insights
North America
North America accounted for the largest share of 46.3% in 2025. Dental Diagnostic And Surgical Market demand in North America is supported by high procedure volumes, strong private clinic penetration, and faster adoption of digital workflows that connect diagnosis and surgery. Purchasing decisions often prioritize throughput, integration, and service reliability because clinic utilization is closely tied to operating efficiency. Growth of organized dentistry and multi-site providers also supports platform standardization and broader deployment of connected systems.
Europe
Europe held 27.6% of 2025 revenue. Dental Diagnostic And Surgical Market demand in Europe is supported by a mature dental services base and steady replacement cycles as clinics upgrade from conventional systems to digital platforms. Practices prioritize predictable outcomes and documentation, which supports integrated diagnostics and planning tools. Competitive intensity is elevated around workflow efficiency, interoperability, and cost-effective ownership, reinforcing focus on long-term service support and upgrade flexibility.
Asia Pacific
Asia Pacific represented 19.4% of 2025 revenue. Dental Diagnostic And Surgical Market growth in Asia Pacific is supported by clinic expansion, rising demand for elective procedures, and ongoing modernization of diagnostic infrastructure. Adoption of digital solutions is increasing as providers seek improved visualization and standardized planning, though price sensitivity can influence configuration choices. Larger urban clinics and specialty centers are key growth engines because they adopt advanced imaging and procedure-ready systems earlier.
Latin America
Latin America accounted for 4.2% of 2025 revenue. Dental Diagnostic And Surgical Market demand in Latin America is concentrated in private clinics in major cities where patients have higher willingness to pay for advanced procedures. Procurement can be constrained by financing conditions and import dependence, which elevates the importance of distributor support and service coverage. Growth is supported by gradual modernization of diagnostic capabilities and rising interest in procedures that require precise planning.
Middle East & Africa
Middle East & Africa contributed 2.5% of 2025 revenue. Dental Diagnostic And Surgical Market demand is driven by private healthcare expansion, premium clinic investments, and gradual upgrades in imaging capabilities. Adoption tends to be strongest in higher-income markets and major urban centers where clinics focus on advanced services and patient experience. Service support and training remain important adoption factors, especially for integrated digital workflows and advanced diagnostic configurations.
Competitive Landscape
Dental Diagnostic And Surgical Market competition is defined by breadth of portfolio, workflow integration, and the ability to support clinics with reliable service and upgrades. Suppliers compete on diagnostic clarity, software usability, interoperability, and the completeness of ecosystems that link imaging, planning, and procedure workflows. Channel strength matters because many practices buy through distributors and expect responsive maintenance coverage. Differentiation increasingly depends on digital integration, clinical workflow efficiency, and total cost of ownership.
Dentsply Sirona competes through an end-to-end approach that connects diagnostics, planning, and chairside execution across clinic environments. Dental Diagnostic And Surgical Market positioning for Dentsply Sirona benefits from the ability to support standardized workflows that scale across multi-provider practices. Emphasis on connected systems supports repeatability, predictable outcomes, and streamlined patient communication. The portfolio strategy aligns with demand for integrated platforms that can reduce workflow friction and support consistent clinical protocols.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Dentsply Sirona
- Straumann
- Danaher
- Planmeca
- Carestream Dental
- 3M
- Ivoclar
- GC Corporation
- Henry Schein
- Envista
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In January 2025, Carestream Dental announced a partnership with Pearl to integrate Pearl’s Second Opinion AI software into Carestream Dental’s CS Imaging platform across North America, a move aimed at improving diagnostic precision and helping dental professionals make more informed treatment decisions.
- In October 2024, HuFriedyGroup acquired SS White Dental, expanding its dental portfolio with SS White’s carbide burs, diamond burs, polishers, instruments, and endodontic products, thereby strengthening its position in clinically differentiated dental instruments and small equipment.
- In October 2024, BioHorizons launched SmartShape Healers, a new line of anatomically shaped healing abutments with a scannable design intended to simplify implant workflows and improve clinical performance in restorative and surgical dentistry.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 6,284.73 million |
| Revenue forecast in 2032 | USD 9,570.03 million |
| Growth rate (CAGR) | 7.26% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Product Category; By Diagnostic Type; By Surgical Type; By Technology; By End-user; By Workflow Integration |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Dentsply Sirona; Straumann; Danaher; Planmeca; Carestream Dental; 3M; Ivoclar; GC Corporation; Henry Schein; Envista |
| No.of Pages | 324 |
Segmentation
By Product Category
- Diagnostic Equipment
- Surgical Instruments
By Diagnostic Type
- Imaging
- Chairside Tests
By Surgical Type
- Implantology
- Oral Surgery
- Periodontics
By Technology
- Digital
- Conventional
By End-user
- Dental Clinics
- Hospitals
- Specialty Centers
- Others
By Workflow Integration
- Standalone
- Digitally Integrated
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Faster adoption of digital dentistry
Clinics are increasingly upgrading to digitally enabled diagnostic and surgical platforms, which streamline workflows, improve clinical consistency, and reduce chair time, driving higher equipment replacement and upgrade cycles.
Growth in complex procedures and implantology
Rising volumes of implantology and complex restorative procedures require advanced diagnostics, guided surgery tools, and precise instrumentation, fueling demand for both diagnostic and surgical equipment.
Expansion and modernization of dental clinics
Asia Pacific and other emerging regions are seeing rapid clinic expansion and modernization, increasing the installed base and supporting sustained demand for new and replacement equipment.
Emphasis on preventive care and screening
Greater focus on preventive dentistry and early detection is increasing baseline utilization of diagnostic equipment, particularly imaging systems, as practices prioritize routine screening and patient education.
Integration of digitally connected workflows
The move toward digitally integrated clinical pathways that connect diagnosis, planning, and execution is driving adoption of systems that support standardized protocols, improved documentation, and multi-site clinical consistency.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Dental Diagnostic And Surgical Market?
What is the CAGR for the Dental Diagnostic And Surgical Market?
Which segment leads the Dental Diagnostic And Surgical Market by product category?
What factors are driving growth in the Dental Diagnostic And Surgical Market?
Who are the key companies in the Dental Diagnostic And Surgical Market?
Which region leads the Dental Diagnostic And Surgical Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Digital
- 1.2.2 Conventional
- 1.3 By Surgical Type
- 1.3.1 Implantology
- 1.3.2 Oral Surgery
- 1.3.3 Periodontics
- 1.4 By Diagnostic Type
- 1.4.1 Imaging
- 1.4.2 Chairside Tests
- 1.5 By Product Category
- 1.5.1 Diagnostic Equipment
- 1.5.2 Surgical Instruments
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 6,284.73 million → 2032: USD 9,570.03 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dental Diagnostic and Surgical Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dental Diagnostic and Surgical Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dental Diagnostic and Surgical Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dental Diagnostic and Surgical Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dental Diagnostic and Surgical Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dental Diagnostic and Surgical Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dental Diagnostic and Surgical Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dental Diagnostic and Surgical Equipment Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 6,284.73 million → 2032: USD 9,570.03 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dental Diagnostic and Surgical Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Digital
- 12.3.7.2 Conventional
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Surgical Type - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Implantology
- 12.4.7.2 Oral Surgery
- 12.4.7.3 Periodontics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Diagnostic Type - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Imaging
- 12.5.7.2 Chairside Tests
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Category - Market Size and Forecast, 2025-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2025-2032
- 12.6.4 Volume Forecast, 2025-2032
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Diagnostic Equipment
- 12.6.7.2 Surgical Instruments
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dental Diagnostic and Surgical Equipment Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Dental Diagnostic and Surgical Equipment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Dental Diagnostic and Surgical Equipment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Dentsply Sirona
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Straumann
- 17.4 Danaher
- 17.5 Planmeca
- 17.6 Carestream Dental
- 17.7 3M
- 17.8 Ivoclar
- 17.9 GC Corporation
- 17.10 Henry Schein
- 17.11 Envista
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

