
Metastatic Melanoma Cancer Diagnostics Market Overview:
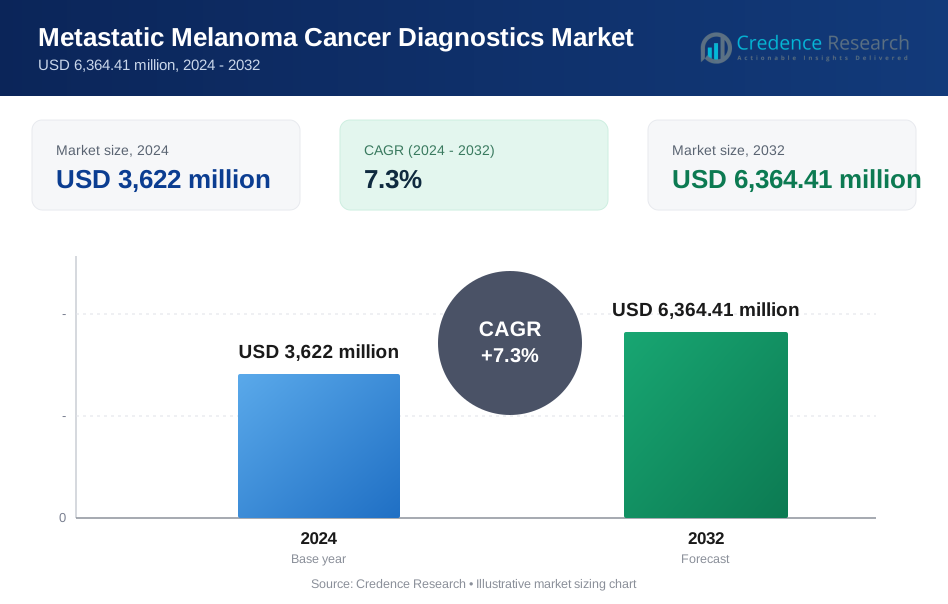
The Metastatic Melanoma Cancer Diagnostics Market size was valued at USD 3,622 million in 2024 and is anticipated to reach USD 6364.41 million by 2032, at a CAGR of 7.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Metastatic Melanoma Cancer Diagnostics Market Size 2024 | USD 3,622 million |
| Metastatic Melanoma Cancer Diagnostics Market, CAGR | 7.3% |
| Metastatic Melanoma Cancer Diagnostics Market Size 2032 | USD 6364.41 million |
Metastatic Melanoma Cancer Diagnostics Market Insights:
- North America holds ~38.5% share, Europe ~29.2%, and Asia-Pacific ~21.4% of the global market, driven respectively by high melanoma prevalence with advanced molecular testing access, structured cancer care systems with standardized diagnostics, and rapidly improving oncology infrastructure.
- Asia-Pacific is the fastest-growing region with ~21.4% share, supported by expanding healthcare access, rising cancer awareness, increasing private diagnostic investments, and government-backed oncology programs across emerging economies.
- By segment distribution, By Diagnosis accounts for ~44.6% share, led by molecular diagnostics and companion testing due to strong reliance on BRAF, NRAS, and KIT mutation profiling for treatment selection.
- By End-User contributes ~36.8% share, dominated by hospitals and oncology centers due to integrated care models, high patient volumes, and direct access to advanced diagnostic and imaging platforms.

Metastatic Melanoma Cancer Diagnostics Market Drivers:
Increasing Burden of Advanced Melanoma and Need for Early Metastatic Detection
The Metastatic Melanoma Cancer Diagnostics Market gains strong momentum from the growing global burden of late-stage melanoma cases. Higher incidence of skin cancer and delayed diagnosis in several populations increase demand for precise metastatic detection. It supports clinical decision-making by enabling early identification of tumor spread beyond the primary site. Improved survival expectations reinforce the importance of accurate and timely diagnostic assessment in advanced melanoma care.
- For instance, a multimodal AI model from Gwanggil Jeon's team fuses dermoscopic images and patient metadata to achieve 94.5% accuracy in melanoma detection.
Expanding Clinical Adoption of Precision Oncology and Biomarker Testing
The Metastatic Melanoma Cancer Diagnostics Market benefits from the rapid integration of precision oncology into routine cancer care. Targeted therapies and immunotherapies depend on accurate biomarker identification, including BRAF, NRAS, and KIT mutations. It drives consistent demand for molecular and companion diagnostics that guide treatment selection. Growing physician confidence in genomics-based decisions strengthens testing volumes across oncology centers.
- For instance, Roche's cobas 4800 BRAF V600 Mutation Test achieved 100% specificity for BRAF V600E detection in melanoma tissue samples from clinical validation studies.
Technological Progress in Molecular, Imaging, and Liquid Biopsy Diagnostics
The Metastatic Melanoma Cancer Diagnostics Market advances through continuous innovation in diagnostic technologies. Next-generation sequencing, high-sensitivity imaging, and liquid biopsy platforms improve detection accuracy and clinical efficiency. It enhances diagnostic turnaround time while reducing invasive tissue sampling requirements. Technology-driven performance improvements encourage wider clinical use across both academic and community oncology settings.
Strengthening Healthcare Infrastructure and Oncology Diagnostic Investments
The Metastatic Melanoma Cancer Diagnostics Market receives support from increased investment in oncology diagnostics infrastructure worldwide. Governments and private healthcare providers expand access to advanced cancer testing facilities. It aligns with broader cancer control strategies and improved reimbursement structures in developed regions. Expanding diagnostic capacity in emerging economies further supports long-term market growth.
Metastatic Melanoma Cancer Diagnostics Market Trends:
Rapid Shift Toward Integrated Molecular and Companion Diagnostic Approaches
The Metastatic Melanoma Cancer Diagnostics Market reflects a clear shift toward integrated molecular and companion diagnostic solutions within oncology workflows. Clinical practice increasingly relies on multi-gene panels that support therapy selection for immuno-oncology and targeted drugs. It shows preference for diagnostics that align directly with approved treatment protocols and clinical guidelines. Laboratories adopt standardized testing platforms to improve reproducibility and clinical confidence. Companion diagnostics gain importance during therapy initiation and monitoring phases. Regulatory approvals for biomarker-linked therapies reinforce this trend. Diagnostic providers focus on scalable platforms that support both tissue-based and blood-based analysis.
- For instance, Roche's cobas BRAF V600 Mutation Test, approved by the FDA, detects BRAF V600E/K mutations in melanoma tissue samples with 96% sensitivity and 98% specificity, enabling precise therapy selection.
Growing Adoption of Liquid Biopsy and High-Resolution Imaging Technologies
The Metastatic Melanoma Cancer Diagnostics Market demonstrates rising adoption of liquid biopsy and advanced imaging modalities across care settings. Clinicians favor blood-based tests due to minimal invasiveness and improved patient compliance. It supports real-time disease monitoring and therapy response evaluation. High-resolution imaging techniques enhance detection of metastatic spread in complex anatomical regions. Diagnostic pathways increasingly combine molecular data with imaging outputs to strengthen clinical interpretation. Healthcare systems invest in platforms that reduce diagnostic delays. This trend aligns with the need for faster, data-driven oncology decisions.
- For instance, Roche's cobas BRAF V600 Mutation Test, approved by the FDA, detects BRAF V600E/K mutations in melanoma tissue samples with 96% sensitivity and 98% specificity, enabling precise therapy selection.
Metastatic Melanoma Cancer Diagnostics Market Challenges Analysis:
High Diagnostic Costs and Limited Access to Advanced Testing Infrastructure
The Metastatic Melanoma Cancer Diagnostics Market faces persistent challenges related to high costs of advanced diagnostic procedures. Molecular profiling, next-generation sequencing, and high-resolution imaging require significant capital investment. It limits adoption across cost-sensitive healthcare systems and smaller diagnostic laboratories. Reimbursement variability further restricts test utilization in several regions. Budget constraints affect the frequency of repeat testing during disease monitoring. Limited access to skilled personnel also affects test accuracy. These factors collectively slow broader market penetration.
Clinical Complexity and Variability in Diagnostic Standardization
The Metastatic Melanoma Cancer Diagnostics Market encounters complexity due to heterogeneous tumor biology and evolving diagnostic standards. Variability in biomarker expression complicates test interpretation and clinical decision-making. It creates challenges for assay standardization across laboratories. Differences in sample quality influence diagnostic reliability. Rapid technological change demands continuous training for clinicians and pathologists. Regulatory alignment across regions remains uneven. Such challenges impact consistency and confidence in diagnostic outcomes.
Metastatic Melanoma Cancer Diagnostics Market Opportunities:
Expansion of Precision Oncology Programs and Biomarker-Driven Care Models
The Metastatic Melanoma Cancer Diagnostics Market presents strong opportunities through expanding precision oncology initiatives worldwide. Healthcare systems prioritize biomarker-driven treatment pathways for advanced melanoma. It increases demand for validated molecular and companion diagnostic tests. Growing clinical trial activity supports broader adoption of innovative diagnostic solutions. Pharmaceutical–diagnostic collaborations strengthen test development and clinical integration. Wider guideline adoption encourages standardized testing at diagnosis. These factors support sustained market expansion.
Growth Potential in Emerging Markets and Decentralized Diagnostic Platforms
The Metastatic Melanoma Cancer Diagnostics Market offers significant potential in emerging economies with improving oncology infrastructure. Rising cancer awareness drives earlier diagnostic intervention. It supports demand for accessible and cost-effective testing solutions. Decentralized laboratories and point-of-care platforms extend diagnostic reach beyond tertiary centers. Digital pathology and remote analysis improve specialist access. Public and private investments strengthen regional diagnostic capacity. This expansion creates long-term growth opportunities.
Metastatic Melanoma Cancer Diagnostics Market Segmentation Analysis:
By Diagnosis
The Metastatic Melanoma Cancer Diagnostics Market shows strong differentiation across diagnostic modalities that support detection, staging, and therapy selection. Molecular diagnostics, including mutation testing for BRAF, NRAS, and KIT, hold a leading position due to their role in treatment guidance. It relies on immunohistochemistry to confirm tumor origin and metastatic spread. Imaging techniques such as PET-CT and MRI support disease mapping and response assessment. Liquid biopsy gains traction for monitoring and minimal invasiveness. Diagnostic selection reflects clinical stage, test availability, and treatment intent.
- For Instance, Roche Diagnostics' VENTANA anti-BRAF V600E (VE1) antibody has demonstrated a sensitivity of 97.2% to 98% in detecting the BRAF V600E mutation in metastatic melanoma.
By Treatment
The Metastatic Melanoma Cancer Diagnostics Market aligns diagnostic demand closely with treatment pathways. Targeted therapy drives high utilization of companion diagnostics to identify actionable mutations. It supports immunotherapy decisions through biomarker assessment and disease profiling. Chemotherapy-related diagnostics show lower growth due to declining clinical preference. Combination therapy protocols increase the need for comprehensive diagnostic panels. Treatment-linked diagnostics continue to evolve alongside therapy innovation and guideline updates.
- For instance, Roche's Cobas 4800 BRAF V600 Mutation Test detects BRAF V600E/K mutations in 85% of metastatic melanoma cases, enabling precise targeted therapy selection with a 92% concordance rate to next-generation sequencing.
By End-User
The Metastatic Melanoma Cancer Diagnostics Market serves a diverse end-user base with distinct testing needs. Hospitals and oncology centers account for major demand due to integrated care delivery. It benefits from specialized diagnostic laboratories that offer advanced molecular testing. Academic and research institutes contribute through clinical trials and biomarker validation. Diagnostic access and testing volume vary by care setting. End-user adoption reflects infrastructure strength, expertise, and patient load.
Segmentations:
By Diagnosis
- Molecular Diagnostics
- Immunohistochemistry
- Imaging Diagnostics
- Liquid Biopsy
- Cytogenetic Testing
By Treatment
- Targeted Therapy Diagnostics
- Immunotherapy Diagnostics
- Chemotherapy-Related Diagnostics
- Combination Therapy Diagnostics
By End-User
- Hospitals
- Oncology Centers
- Diagnostic Laboratories
- Academic and Research Institutes
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Maintains Leadership Through Advanced Oncology Infrastructure
The Metastatic Melanoma Cancer Diagnostics Market shows strong regional dominance in North America due to mature oncology infrastructure and high disease awareness. The region reports elevated melanoma incidence, which drives consistent diagnostic demand. It benefits from widespread availability of molecular testing and high-resolution imaging platforms. Favorable reimbursement policies support routine biomarker testing in clinical practice. Strong pharmaceutical pipelines reinforce companion diagnostic adoption. Academic centers and reference laboratories sustain high testing volumes. Regulatory clarity supports rapid clinical uptake of novel diagnostic assays.
Europe Demonstrates Stable Growth Backed by Structured Cancer Care Systems
The Metastatic Melanoma Cancer Diagnostics Market experiences stable expansion across Europe through organized cancer screening and treatment frameworks. Public healthcare systems emphasize early detection and standardized diagnostic pathways. It relies on strong pathology networks and growing access to genomic testing. Adoption of precision oncology continues across major Western European countries. Research collaborations support biomarker validation and test harmonization. Centralized laboratory models improve diagnostic consistency. Eastern Europe shows gradual improvement with expanding oncology investments.
Asia-Pacific and Rest of World Offer High Growth Potential
The Metastatic Melanoma Cancer Diagnostics Market presents strong growth potential in Asia-Pacific and other developing regions. Rising cancer awareness increases diagnostic testing demand. It benefits from improving healthcare access and expanding oncology infrastructure. Private diagnostic providers accelerate adoption of molecular testing platforms. Government initiatives support cancer control and early diagnosis programs. Latin America and the Middle East invest in specialized oncology centers. These regions gradually reduce diagnostic gaps through technology adoption and training programs.
Key Player Analysis:
- Johnson & Johnson Private Limited (U.S.)
- Mylan N.V. (U.S.)
- Sun Pharmaceutical Industries Limited(India)
- Sanofi S.A.( France)
- Bayer AG (Germany)
- Lilly (U.S.)
- Merck & Co., Inc. (U.S.)
- GSK plc (U.K.)
- Novartis AG (Switzerland)
- AbbVie Inc. (U.S.)
- Bausch Health Companies Inc. (Canada)
- Hoffmann-La Roche Ltd (Switzerland)
- Amgen Inc. (U.S.)
Competitive Analysis:
The Metastatic Melanoma Cancer Diagnostics Market features a competitive landscape shaped by global diagnostics companies, specialized oncology testing providers, and emerging molecular diagnostics firms. Market leaders focus on advanced molecular assays, companion diagnostics, and high-throughput sequencing platforms to support precision oncology. It encourages continuous product refinement to improve sensitivity, specificity, and clinical relevance. Strategic partnerships between diagnostic developers and pharmaceutical companies strengthen test validation and clinical adoption. Competitive differentiation depends on assay accuracy, turnaround time, and regulatory compliance. Companies invest in expanding test menus aligned with immunotherapy and targeted therapy pipelines. Geographic expansion and laboratory network growth support market positioning. Innovation in liquid biopsy and digital pathology creates new competitive advantages. Smaller players emphasize niche biomarker panels and cost-effective solutions to compete with established brands.
Recent Developments:
- In December 2025, Sun Pharma Laboratories Ltd approved a ₹3,000 crore investment for a new greenfield formulations plant in Madhya Pradesh.
- In June 2025, Sanofi announced the acquisition of Blueprint Medicines to add Ayvakit for systemic mastocytosis and KIT-driven assets.
Report Coverage:
The research report offers an in-depth analysis based on Diagnosis, Treatment, End-User and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
North America Leads Through Strong Diagnostic Adoption and Precision Oncology Integration
The Metastatic Melanoma Cancer Diagnostics Market remains firmly established in North America due to advanced healthcare systems and high clinical awareness. The region reports elevated melanoma incidence, which sustains consistent diagnostic demand. It benefits from broad access to molecular testing, companion diagnostics, and high-end imaging platforms. Favorable reimbursement policies support routine biomarker assessment in oncology practice. Strong collaboration between diagnostic firms and pharmaceutical companies accelerates test adoption. Academic research centers contribute to validation of novel diagnostic assays. Regulatory frameworks support timely clinical deployment of innovative technologies.
Europe Shows Structured Growth Driven by Standardized Cancer Care Pathways
The Metastatic Melanoma Cancer Diagnostics Market demonstrates steady performance across Europe through well-defined cancer care models. National healthcare systems emphasize standardized diagnostic protocols and early metastatic assessment. It relies on established pathology networks and expanding genomic testing capabilities. Western Europe leads adoption of precision diagnostics within routine oncology workflows. Public funding supports research initiatives focused on melanoma biomarkers. Centralized laboratory services improve test quality and consistency. Eastern Europe advances gradually with targeted investments in oncology diagnostics.
Asia-Pacific and Other Regions Present Expanding Diagnostic Opportunities
The Metastatic Melanoma Cancer Diagnostics Market shows rising momentum across Asia-Pacific, Latin America, and the Middle East & Africa. Improving healthcare access increases diagnostic testing rates across urban centers. It benefits from private-sector investment in molecular laboratories and imaging facilities. Growing cancer awareness supports earlier diagnostic intervention. Government-led cancer control programs strengthen screening and referral systems. Diagnostic service providers expand regional footprints to address unmet demand. These regions continue to close infrastructure gaps through technology adoption and workforce development.
- The Metastatic Melanoma Cancer Diagnostics Market is expected to advance through deeper integration of precision oncology into routine clinical practice.
- Diagnostic strategies will increasingly focus on multi-biomarker panels that support complex treatment decisions in advanced melanoma care.
- Liquid biopsy platforms will gain broader clinical acceptance due to their ability to support disease monitoring and therapy assessment with minimal invasiveness.
- Molecular diagnostics will continue to evolve alongside targeted and immuno-oncology therapies, reinforcing the need for accurate mutation profiling.
- Artificial intelligence and digital pathology will enhance diagnostic accuracy, workflow efficiency, and interpretation consistency across laboratories.
- Healthcare providers will prioritize faster diagnostic turnaround times to support timely treatment initiation in metastatic settings.
- Regulatory agencies will refine frameworks that support validation and clinical adoption of novel diagnostic technologies.
- Emerging economies will strengthen oncology diagnostics capacity through infrastructure development and public–private collaboration.
- Pharmaceutical and diagnostic partnerships will play a critical role in aligning test development with therapeutic innovation.
- Clinical demand will increasingly favor diagnostics that combine analytical precision, operational efficiency, and patient-centered testing approaches.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Metastatic Melanoma Cancer Diagnostics Market?
What factors are driving the growth of the Metastatic Melanoma Cancer Diagnostics Market?
Which diagnostic segment holds significant potential in the market?
Who are the major end-users in the Metastatic Melanoma Cancer Diagnostics Market?
Which regions are expected to dominate the Metastatic Melanoma Cancer Diagnostics Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Metastatic Melanoma Cancer Diagnostics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Metastatic Melanoma Cancer Diagnostics Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,622 million → 2032: USD 6,364.41 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Metastatic Melanoma Cancer Diagnostics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Metastatic Melanoma Cancer Diagnostics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Metastatic Melanoma Cancer Diagnostics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Metastatic Melanoma Cancer Diagnostics Market Drivers
- 3.3 Metastatic Melanoma Cancer Diagnostics Market Restraints & Challenges
- 3.4 Metastatic Melanoma Cancer Diagnostics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Metastatic Melanoma Cancer Diagnostics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Metastatic Melanoma Cancer Diagnostics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Metastatic Melanoma Cancer Diagnostics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Metastatic Melanoma Cancer Diagnostics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Metastatic Melanoma Cancer Diagnostics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Metastatic Melanoma Cancer Diagnostics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Metastatic Melanoma Cancer Diagnostics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Metastatic Melanoma Cancer Diagnostics Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Metastatic Melanoma Cancer Diagnostics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Metastatic Melanoma Cancer Diagnostics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Metastatic Melanoma Cancer Diagnostics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Metastatic Melanoma Cancer Diagnostics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Metastatic Melanoma Cancer Diagnostics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Metastatic Melanoma Cancer Diagnostics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Metastatic Melanoma Cancer Diagnostics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Metastatic Melanoma Cancer Diagnostics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Metastatic Melanoma Cancer Diagnostics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Metastatic Melanoma Cancer Diagnostics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Metastatic Melanoma Cancer Diagnostics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
