
Market Overview:
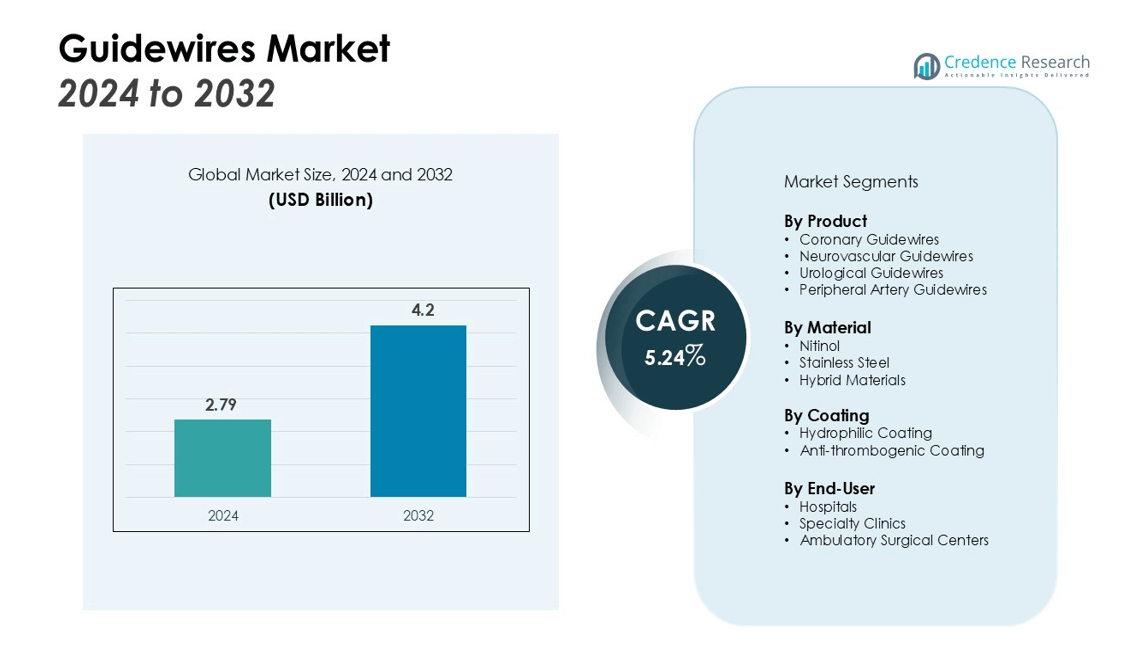
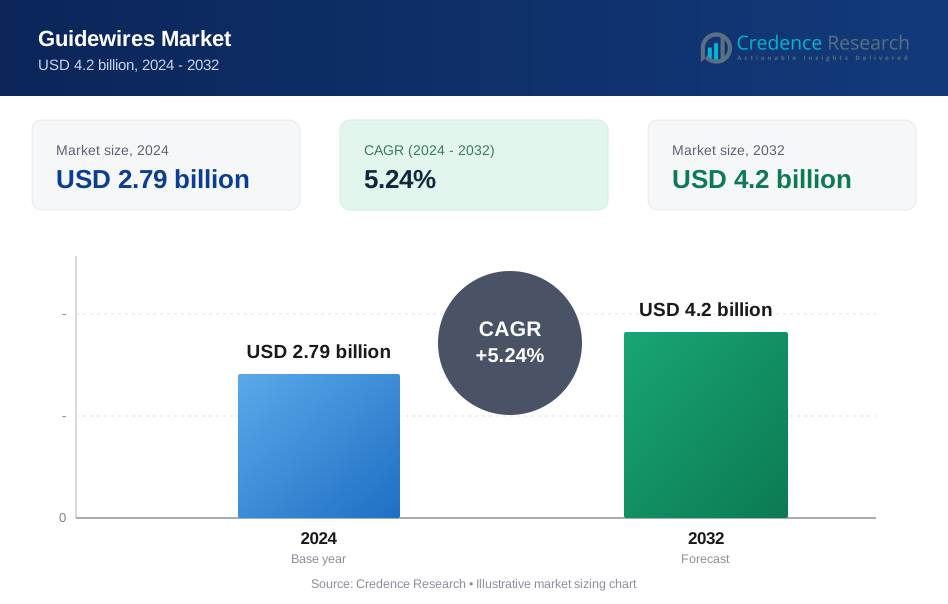
The Guidewires Market size was valued at USD 2.79 billion in 2024 and is anticipated to reach USD 4.2 billion by 2032, at a CAGR of 5.24% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Guidewires Market Size 2024 | USD 2.79 billion |
| Guidewires Market, CAGR | 5.24% |
| Guidewires Market Size 2032 | USD 4.2 billion |
The guidewires market continues to expand, driven by several strong growth factors. Rising prevalence of cardiovascular, peripheral artery, urological, and neurovascular diseases is creating consistent demand, as guidewires play a central role in these interventions. Growing preference for minimally invasive procedures is further accelerating adoption, as such methods lower recovery time, reduce hospital stays, and minimize risks compared to traditional surgeries. At the same time, advancements in material science, including nitinol-based products, along with improvements in hydrophilic and anti-thrombogenic coatings, have enhanced flexibility, steerability, and overall clinical performance. The aging global population also contributes to rising demand, as chronic conditions requiring guidewire-assisted procedures increase across both advanced and emerging economies.
Regionally, North America holds the largest share of the market, supported by well-established healthcare systems, high procedural volumes, and favorable reimbursement structures. Europe maintains steady growth due to its adoption of advanced minimally invasive techniques and a supportive regulatory environment. Asia-Pacific is emerging as the fastest-growing region, led by rising healthcare investments, higher incidence of chronic diseases, and stronger adoption of advanced medical technologies in countries such as China, India, and Japan. These dynamics position Asia-Pacific as a key growth engine, while North America and Europe continue to provide stable contributions to global market expansion.
Market Insights:
- The Guidewires Market is expanding due to rising prevalence of cardiovascular, peripheral artery, urological, and neurovascular diseases, increasing demand for interventional procedures.
- Growing preference for minimally invasive procedures is driving market growth as guidewires reduce recovery time, lower risks, and improve patient outcomes.
- Advancements in nitinol alloys and hydrophilic coatings are enhancing the flexibility, steerability, and overall performance of guidewires, improving procedural success.
- The aging population contributes to rising demand for guidewire-assisted treatments, particularly in cardiovascular and neurological interventions.
- North America leads the market with 38% share, driven by strong healthcare infrastructure, high procedure volumes, and advanced interventional techniques.
- Europe accounts for 29% of the market, with steady growth supported by the adoption of minimally invasive procedures and strong healthcare policies.
- Asia-Pacific holds 24% of the market and is the fastest-growing region, driven by rising healthcare investments, patient volumes, and adoption of advanced treatments.
Market Drivers:
Growing Prevalence of Chronic and Lifestyle-Related Diseases
The Guidewires Market is expanding due to rising cases of cardiovascular, peripheral artery, urological, and neurovascular disorders worldwide. Increasing lifestyle-related conditions such as hypertension, obesity, and diabetes have accelerated demand for interventional procedures. Guidewires provide critical support in diagnostic and therapeutic applications, making them essential in handling these high-burden diseases. Strong demand from hospitals and specialty clinics reinforces steady market growth.
- For instance, Boston Scientific's VICTORY™ guidewire is designed to treat peripheral artery disease, a chronic condition. It features a specialized 14-gram tip load, enabling physicians to navigate and cross highly calcified lesions that are difficult to treat with other devices.
Rising Demand for Minimally Invasive Procedures
Healthcare providers are adopting less invasive approaches because they reduce hospital stays, lower risks, and improve recovery outcomes. Guidewires serve as indispensable tools in such procedures, guiding catheters and instruments with precision. Their application spans coronary angioplasty, urological interventions, and neurovascular treatments, driving their use across multiple therapeutic areas. Patient preference for procedures with minimal pain and faster recovery further accelerates adoption.
- For instance, Abbott’s PressureWire™ X Guidewire enhances the precision of minimally invasive cardiac diagnostics, it provides wireless physiological data with exceptional stability, demonstrating a signal drift of less than 1 mmHg over a 30-minute period, which helps ensure accurate decision-making during procedures.
Advancements in Materials and Coating Technologies
Continuous technological improvements strengthen product performance and expand clinical acceptance. The use of nitinol alloys has enhanced flexibility and durability, while hydrophilic and anti-thrombogenic coatings improve navigation through complex anatomy. These developments increase procedural success rates and reduce complications. It ensures that healthcare providers rely more on advanced guidewire designs to achieve better patient outcomes.
Impact of Aging Population on Demand for Guidewires
Aging demographics contribute significantly to the Guidewires Market, as older populations face higher risks of chronic diseases. Rising life expectancy in developed and emerging economies heightens demand for cardiovascular, urological, and neurological interventions. Guidewires remain essential in these treatments, strengthening their role in modern healthcare. It is expected that this trend will sustain long-term growth by supporting a consistent rise in procedure volumes worldwide.
Market Trends:
Technological Innovation in Product Design and Performance
The Guidewires Market is experiencing steady innovation in design, materials, and coatings. Manufacturers are focusing on nitinol-based guidewires that enhance flexibility, torque control, and kink resistance. Hydrophilic and anti-thrombogenic coatings improve navigation through tortuous vessels, reducing procedural risk. It benefits healthcare providers by offering higher precision and reliability in critical interventions. Hybrid designs that combine strength with superior trackability are gaining acceptance in cardiovascular and neurovascular applications. These developments are positioning guidewires as advanced solutions that improve both safety and procedural efficiency.
- For instance, Terumo's GLIDEWIRE features a unique core-to-tip design that provides a 1:1 torque ratio, ensuring the guidewire's tip responds precisely to every turn made by the physician for enhanced control during procedures.
Expanding Applications and Shifting Regional Dynamics
Growing clinical use beyond cardiology highlights a key trend in the Guidewires Market, with strong uptake in urology, gastroenterology, and neurology. It reflects the broadening role of guidewires in minimally invasive medicine. Rising healthcare investments in Asia-Pacific are strengthening adoption, with China and India becoming focal points for growth. North America remains dominant due to established infrastructure, while Europe benefits from consistent uptake of advanced techniques. Hospitals and specialty centers are increasingly preferring guidewires designed for complex anatomies, driving product differentiation. The trend toward customized and procedure-specific guidewires ensures sustained demand across global regions.
- For instance, in July 2025, Medtronic significantly expanded its offerings for treating peripheral arterial disease by securing the exclusive U.S. distribution for a new line of guidewires, which includes the first 400 cm peripheral guidewire available in the nation.
Market Challenges Analysis:
High Costs and Procedural Limitations
The Guidewires Market faces pressure from high product costs and expenses linked to advanced procedures. Premium nitinol-based wires and specialized coatings raise procurement costs for healthcare providers. Limited budgets in public hospitals and price-sensitive markets restrict widespread adoption. It creates barriers for smaller healthcare facilities that struggle to access next-generation technologies. Complex procedures also demand skilled professionals, and a shortage of trained specialists reduces the potential for optimal usage. These factors slow penetration in developing healthcare systems where affordability remains critical.
Regulatory Hurdles and Safety Concerns
Strict regulatory standards and extended approval timelines pose challenges to new product launches. Compliance with regional frameworks requires significant investment in testing and certification. Safety concerns such as vessel perforation, kinking, or wire fracture highlight risks associated with guidewire use. It compels manufacturers to maintain consistent quality and reliability in production. Variability in reimbursement across regions further impacts adoption rates, especially in emerging economies. These challenges underline the need for continuous product improvement and robust clinical validation to sustain growth momentum.
Market Opportunities:
Rising Adoption of Minimally Invasive Interventions
The Guidewires Market holds strong opportunities from the expanding demand for minimally invasive procedures. Hospitals and specialty centers are increasing reliance on guidewires for cardiovascular, neurovascular, and urological interventions. It supports the global shift toward treatments that offer shorter recovery, lower risks, and reduced costs. Growing acceptance of day-care surgeries further increases procedural volumes. Emerging economies are investing in advanced catheterization labs, creating fresh opportunities for adoption. These factors strengthen the position of guidewires as vital tools in interventional medicine.
Emerging Markets and Technological Advancements
Expanding healthcare infrastructure in Asia-Pacific, Latin America, and the Middle East provides significant growth potential. Rising patient awareness and improved access to specialized care are creating favorable conditions. It also benefits from ongoing innovation in material science, coating technologies, and product customization. Next-generation guidewires designed for complex anatomies open doors for new clinical applications. Companies that align with regional needs and regulatory frameworks are well positioned to capture market share. This creates opportunities to expand both product portfolios and global presence.
Market Segmentation Analysis:
By Product
The Guidewires Market is segmented into various products, including coronary, neurovascular, urological, and peripheral artery guidewires. Coronary guidewires dominate due to the high volume of cardiovascular procedures. Neurovascular guidewires are witnessing rapid adoption driven by the increasing prevalence of neurovascular diseases and the growing number of minimally invasive procedures. Urological and peripheral artery guidewires are also seeing consistent demand, with advancements in materials and designs improving their performance in delicate interventions.
- For instance, Cardiovascular Systems, Inc. received FDA approval for its ViperWire Advance® Coronary Guide Wire with Flex Tip in September 2019. It was the first and only nitinol atherectomy guidewire designed to help physicians navigate and treat complex calcific coronary artery disease.
By Material
Guidewires are primarily made from materials such as stainless steel, nitinol, and hybrid materials. Nitinol is the leading material, known for its flexibility, shape memory, and high resistance to fatigue. It allows guidewires to navigate complex anatomy with ease, particularly in coronary and neurovascular interventions. Stainless steel is commonly used due to its cost-effectiveness and durability but lacks the flexibility of nitinol. Hybrid materials, combining nitinol and other alloys, are gaining traction, offering enhanced performance and better steerability for complex procedures.
- For instance, Boston Scientific's Sensor™ Guidewire has a kink-resistant nitinol core and a 5 cm hydrophilic coated floppy tip, which is specifically designed to help navigate past obstructions and through tortuous anatomy.
By Coating
Coatings play a crucial role in improving the performance and safety of guidewires. Hydrophilic coatings, which reduce friction, are widely used to enhance navigation through tortuous vessels. Anti-thrombogenic coatings help prevent blood clot formation, improving procedural outcomes. These advanced coatings have expanded the use of guidewires in high-risk procedures, particularly in the cardiovascular and neurovascular segments, where precision and safety are paramount.
Segmentations:
By Product- Coronary Guidewires
- Neurovascular Guidewires
- Urological Guidewires
- Peripheral Artery Guidewires
- Nitinol
- Stainless Steel
- Hybrid Materials
- Hydrophilic Coating
- Anti-thrombogenic Coating
- Hospitals
- Specialty Clinics
- Ambulatory Surgical Centers
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
Dominance of North America in Global Share
North America holds 38% of the Guidewires Market, leading globally due to its strong healthcare infrastructure and high adoption of advanced interventional techniques. The region benefits from the presence of prominent hospitals and specialized centers that perform a high volume of cardiovascular and neurovascular procedures. Aging populations and the increasing prevalence of chronic diseases further sustain demand for guidewire-assisted treatments. Continuous product innovation, along with faster regulatory approvals, further contributes to the region’s dominance and long-term growth prospects.
Steady Growth in Europe with Expanding Adoption
Europe accounts for 29% of the Guidewires Market, driven by the growing preference for minimally invasive procedures and strong healthcare policies. Key countries, such as Germany, France, and the U.K., remain leading adopters due to well-established healthcare infrastructure and skilled professionals. Strict regulatory frameworks ensure the safe use of guidewires in various clinical applications. Increased investments in research and collaborations with regional manufacturers enhance product availability. The rising demand for guidewires with advanced coatings and flexible designs supports consistent market expansion.
Rapid Expansion of Asia-Pacific as a Growth Engine
Asia-Pacific represents 24% of the Guidewires Market and is the fastest-growing region. Key markets, such as China, India, and Japan, drive this growth due to rising patient volumes, higher incidence of chronic conditions, and increasing affordability of advanced treatments. Expanding hospital networks, improved healthcare professional training, and government investments in healthcare infrastructure further promote adoption. With accelerating modernization in healthcare systems, Asia-Pacific is expected to increase its contribution to the global market in the coming years.
Key Player Analysis:
- Abbott
- Boston Scientific Corporation
- Medtronic
- Terumo Medical Corporation
- Cook Medical
- Olympus Corporation
- Teleflex Corporation
- Cardinal Health Inc.
- R. Bard, Inc.
- Merit Medical Inc.
Competitive Analysis:
The Guidewires Market is highly competitive, with key players such as Boston Scientific, Medtronic, Abbott Laboratories, Terumo Corporation, B. Braun Melsungen AG, and Cook Medical leading the industry. These companies dominate based on their extensive product portfolios, technological advancements, and strategic partnerships. For instance, Medtronic's launch of the Steerant Aortic Guidewire highlights the industry's focus on improving procedural efficiency and patient outcomes. Competition is intensifying as firms seek to expand through mergers, acquisitions, and innovation to maintain their market position. The market's growth is driven by technological innovations, an aging population, and the increasing demand for minimally invasive procedures, with companies continuing to adapt and invest in new technologies to strengthen their competitive edge.
Recent Developments:
- In May 2025, Medtronic announced its intention to separate its Diabetes business into a new, independent company that will be publicly traded.
- In July 2025, Cook Medical launched its new Interventional MRI (iMRI) division, dedicated to creating minimally invasive devices compatible with the iMRI environment.
Report Coverage:
The research report offers an in-depth analysis based on Product, Material, Coating, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Guidewires Market will continue to grow as minimally invasive procedures gain widespread acceptance across various medical disciplines.
- Advancements in materials, such as nitinol and hybrid alloys, will enhance the flexibility and durability of guidewires, improving procedural outcomes.
- The aging global population will drive demand for guidewire-assisted interventions, particularly in cardiovascular and neurovascular treatments.
- The increasing prevalence of chronic diseases such as hypertension, diabetes, and obesity will create sustained demand for guidewires in therapeutic procedures.
- The market will see expanding adoption of guidewires in emerging regions like Asia-Pacific, fueled by healthcare investments and improving access to advanced treatments.
- Technological innovations, such as hydrophilic and anti-thrombogenic coatings, will continue to play a key role in enhancing guidewire performance and safety.
- Hospitals and specialty clinics will remain the largest end-users, driven by a growing preference for advanced medical technologies in interventional procedures.
- Regulatory approvals for advanced guidewires will improve, enabling quicker access to innovative products in various regions.
- The growing focus on customized and patient-specific guidewires will create new opportunities for product differentiation and innovation.
- Competitive dynamics will intensify, with leading players focusing on strategic partnerships, acquisitions, and product innovation to capture larger market shares.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global Guidewires Market?
What is the expected growth rate of the Guidewires Market between 2024 and 2032?
Which segment is leading the market share in terms of Type of Guidewire?
Which Material segment is expected to post the highest CAGR during the forecast period?
Who are the major players in the global Guidewires Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Guidewires Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Guidewires Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2.79 billion → 2032: USD 4.2 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Guidewires Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Guidewires Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Guidewires Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Guidewires Market Drivers
- 3.3 Guidewires Market Restraints & Challenges
- 3.4 Guidewires Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Guidewires Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Guidewires Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Guidewires category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Guidewires Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Guidewires Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Guidewires market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Guidewires Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Guidewires Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Guidewires Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Guidewires (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Guidewires Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Guidewires Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Guidewires Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Guidewires Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Guidewires Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Guidewires Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Guidewires Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Guidewires Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Guidewires Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
