
Rare Disease Clinical Trials Market Overview:
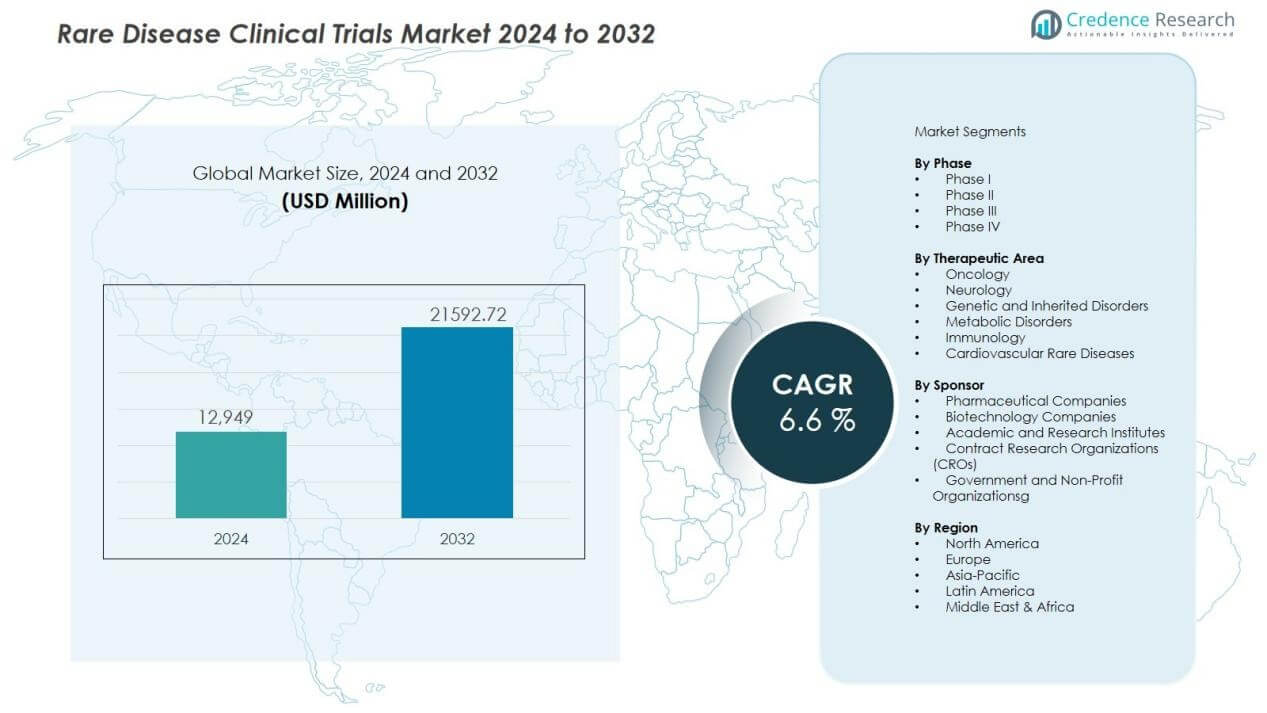
The Rare Disease Clinical Trials Market size was valued at USD 12,949 million in 2024 and is anticipated to reach USD 21592.72 million by 2032, at a CAGR of 6.6 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Rare Disease Clinical Trials Market Size 2024 | USD 6.6 million |
| Rare Disease Clinical Trials Market, CAGR | 10.17% |
| Rare Disease Clinical Trials Market Size 2032 | USD 21592.72 million |
Rare Disease Clinical Trials Market Insights:
- The Rare Disease Clinical Trials Market was valued at USD 12,949 million in 2024 and is projected to reach USD 21,592.72 million by 2032, expanding at a 6.6% CAGR, driven by orphan drug incentives, genomic diagnostics, and adaptive trial models.
- North America (42%), Europe (31%), and Asia-Pacific (19%) represent the top regional shares, supported by advanced research infrastructure, harmonized regulatory pathways, strong funding availability, and established rare disease networks.
- Asia-Pacific, holding nearly 19% share, is the fastest-growing region due to expanding healthcare infrastructure, increasing clinical trial outsourcing, government-backed rare disease programs, and improved diagnostic capabilities.
- By phase, Phase II trials account for approximately 38% share, followed by Phase I at 27%, reflecting emphasis on proof-of-concept validation and dose optimization in small patient populations.
- By sponsor, pharmaceutical and biotechnology companies hold around 64% share, while academic institutes and CRO-led trials contribute nearly 36%, highlighting balanced participation between innovation-driven and execution-focused stakeholders.
Rare Disease Clinical Trials Market Drivers:
Expanding Orphan Drug Development and Targeted Therapy Pipelines
The Rare Disease Clinical Trials Market benefits from a strong expansion in orphan drug and targeted therapy pipelines. Pharmaceutical and biotechnology companies prioritize rare indications due to regulatory incentives, premium pricing potential, and reduced competitive intensity. Precision biologics, gene therapies, and RNA-based treatments demand specialized trial designs that increase clinical research activity. It gains momentum from rising venture funding and strategic partnerships focused on high-unmet-need populations.
- For instance, Hygiena's Innovate System employs ATP bioluminescence to deliver actionable microbial detection results in under 30 minutes post-incubation.
Advances in Genomic Diagnostics and Patient Identification Capabilities
The Rare Disease Clinical Trials Market advances through improvements in genomic sequencing, biomarker discovery, and molecular diagnostics. These tools support accurate diagnosis, enable early patient identification, and improve cohort stratification. Better disease characterization strengthens endpoint selection and increases trial success probability. It benefits from structured patient registries and data-sharing initiatives that support recruitment efficiency.
- For instance, Illumina’s NovaSeq 6000 system enabled high-throughput exome sequencing of approximately 500 biological samples in a single run, significantly reducing the 'diagnostic odyssey' for patients by improving diagnostic rates for rare genetic conditions in clinical settings.
Supportive Regulatory Frameworks and Accelerated Approval Pathways
The Rare Disease Clinical Trials Market receives strong support from regulatory frameworks designed for orphan indications. Authorities provide fast-track designations, protocol assistance, tax credits, and extended market exclusivity. These mechanisms reduce development risk and improve sponsor confidence in rare disease programs. It progresses faster due to adaptive trial designs and acceptance of surrogate endpoints.
Growing Role of Patient Advocacy Groups and Specialized Research Networks
The Rare Disease Clinical Trials Market strengthens through active participation of patient advocacy organizations and specialized research networks. These groups improve disease awareness, support funding initiatives, and facilitate direct patient engagement. Close collaboration between sponsors and advocacy groups improves trial enrollment and retention. It benefits from trusted community networks that enhance trial visibility and patient commitment.
Rare Disease Clinical Trials Market Trends:
Rising Adoption of Adaptive Trial Designs and Precision-Focused Study Models
The Rare Disease Clinical Trials Market shows a clear shift toward adaptive trial designs and precision-focused study models. Sponsors apply smaller, flexible protocols that adjust dosing, endpoints, or cohort size based on interim data. This approach improves statistical efficiency and reduces patient exposure risk in ultra-small populations. It supports faster decision-making and better alignment with regulatory expectations. Increased use of biomarker-driven stratification strengthens endpoint relevance and trial predictability. Platform trials and basket studies gain preference due to their ability to evaluate multiple therapies within a single framework. These models improve cost control while maintaining scientific rigor.
- For Instance, Pfizer and Sangamo Therapeutics utilized an adaptive Phase I/II trial (the Alta study) for their Hemophilia A gene therapy, giroctocogene fitelparvovec, to establish an optimal dose
Expansion of Decentralized, Digital, and Patient-Centric Trial Approaches
The Rare Disease Clinical Trials Market reflects strong momentum toward decentralized and patient-centric trial execution. Sponsors deploy remote monitoring, telemedicine visits, and wearable devices to reduce patient burden. This trend improves participation for geographically dispersed rare disease populations. It benefits from electronic data capture and real-time safety monitoring that enhance data quality. Digital endpoints support continuous outcome assessment beyond traditional site visits. Patient-reported outcomes gain higher priority to capture real-world treatment impact. These approaches strengthen retention rates and trial continuity across long study durations.
- For Instance, Novartis has modernized its clinical trial operations by deploying advanced electronic data capture (EDC) systems across its global portfolio. While individual pivotal SMA trials like STR1VE or SMART typically utilize a targeted network of 12 to 40 specialized clinical sites, Novartis maintains a global SMA registry that is multicenter and multinational.
Rare Disease Clinical Trials Market Challenges Analysis:
Limited Patient Populations and Complex Recruitment Dynamics
The Rare Disease Clinical Trials Market faces persistent challenges due to extremely limited patient populations and fragmented disease awareness. Many conditions lack formal diagnosis pathways, which restricts patient identification and enrollment. Geographic dispersion of eligible patients increases logistical complexity and site dependency. It encounters longer recruitment timelines that elevate trial costs and delay development milestones. Strict eligibility criteria further narrow available cohorts. Competition among sponsors for the same patients intensifies enrollment pressure. These factors collectively constrain trial scalability and predictability.
High Development Costs and Regulatory Complexity Across Regions
The Rare Disease Clinical Trials Market confronts high development costs linked to specialized protocols, advanced analytics, and extended follow-up requirements. Small sample sizes reduce statistical power and demand complex study designs. It faces regulatory variation across regions that complicates protocol alignment and submission timelines. Limited historical data increases uncertainty in endpoint validation. Sponsors manage elevated operational risk due to protocol amendments and compliance demands. These challenges place pressure on timelines and overall development efficiency.
Rare Disease Clinical Trials Market Opportunities:
Expansion of Gene Therapy, Cell Therapy, and Precision Medicine Programs
The Rare Disease Clinical Trials Market presents strong opportunities through rapid expansion of gene therapy, cell therapy, and precision medicine programs. Advances in molecular targeting enable treatments for conditions with no approved therapies. Sponsors prioritize rare indications to leverage orphan incentives and premium reimbursement potential. It benefits from rising investment in platform technologies that support multiple indications. Growing acceptance of surrogate endpoints supports faster clinical validation. These factors create a favorable environment for innovative trial programs.
Growth of Decentralized Trials and Global Patient Access Initiatives
The Rare Disease Clinical Trials Market offers opportunities through decentralized trial models and expanded global patient access. Virtual visits and remote monitoring reduce participation barriers for small patient groups. It gains from trial expansion into emerging regions with improving research infrastructure. Global collaboration improves patient reach and enrollment diversity. Digital health tools strengthen data collection and safety oversight. These initiatives enhance feasibility and long-term trial sustainability.
Rare Disease Clinical Trials Market Segmentation Analysis:
By Phase
The Rare Disease Clinical Trials Market shows a strong concentration of activity across early and mid-stage development phases. Phase I and Phase II trials dominate due to the need for safety profiling, dose optimization, and proof-of-concept validation in small patient cohorts. Sponsors favor adaptive and seamless Phase I/II designs to improve efficiency and reduce timelines. Late-stage Phase III trials remain limited but increase steadily for conditions with established biomarkers and regulatory alignment. It reflects a development model that prioritizes scientific validation before large-scale confirmation.
- For Instance, Sarepta Therapeutics utilized a Phase IIb trial (Study 201) for eteplirsen in Duchenne muscular dystrophy, enrolling 12 ambulatory boys. At 48 weeks, the cohort receiving 50 mg/kg weekly demonstrated an 89.4-meter treatment benefit on the 6-minute walk test (6MWT) compared to the placebo/delayed-treatment group.
By Therapeutic Area
The Rare Disease Clinical Trials Market spans diverse therapeutic areas, with oncology, neurology, and genetic disorders holding major shares. Rare cancers attract sustained trial volume due to high unmet need and strong orphan incentives. Neurological and neuromuscular disorders follow, supported by advances in gene therapy and molecular diagnostics. Metabolic and immunological rare diseases also show rising trial activity due to improved disease awareness. It benefits from precision medicine approaches that align therapy design with disease biology.
- For instance, CRISPR Therapeutics' Casgevy achieved 16 of 17 sickle cell disease patients free of vaso-occlusive crises in phase III trials.
By Sponsor
The Rare Disease Clinical Trials Market reflects a balanced mix of sponsors, led by pharmaceutical and biotechnology companies. Biotech firms drive early-stage innovation through platform-based therapies and focused pipelines. Large pharmaceutical companies contribute scale, regulatory expertise, and late-stage execution strength. Academic institutions and research hospitals play a critical role in investigator-led studies and early discovery. It gains stability through collaborative partnerships that combine innovation with operational capability.
Segmentations:
By Phase
- Phase I
- Phase II
- Phase III
- Phase IV
By Therapeutic Area
- Oncology
- Neurology
- Genetic and Inherited Disorders
- Metabolic Disorders
- Immunology
- Cardiovascular Rare Diseases
By Sponsor
- Pharmaceutical Companies
- Biotechnology Companies
- Academic and Research Institutes
- Contract Research Organizations (CROs)
- Government and Non-Profit Organizations
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Supported by Advanced Research Infrastructure and Orphan Drug Incentives
The Rare Disease Clinical Trials Market in North America maintains a leading position due to mature clinical research infrastructure and strong regulatory incentives. The United States hosts a high concentration of specialized research centers and experienced investigators. Federal programs support orphan drug development through tax credits, expedited reviews, and extended exclusivity. It benefits from robust patient advocacy networks that support recruitment and trial awareness. Strong funding availability from public and private sources sustains trial volume. High adoption of digital health tools improves monitoring and data integrity.
Europe Driven by Harmonized Regulations and Established Rare Disease Networks
The Rare Disease Clinical Trials Market in Europe shows consistent expansion supported by coordinated regulatory frameworks. The region benefits from centralized approval pathways and well-established rare disease registries. Cross-border collaboration improves patient access for ultra-rare conditions. It gains strength from academic research institutions with deep expertise in genetic and neurological disorders. Public funding and nonprofit initiatives support investigator-led trials. Strong emphasis on ethical standards and data quality enhances trial credibility.
Asia-Pacific Emerging Through Infrastructure Growth and Clinical Outsourcing Potential
The Rare Disease Clinical Trials Market in Asia-Pacific records the fastest growth due to improving healthcare infrastructure and policy support. Countries such as Japan, China, South Korea, and Australia expand rare disease research initiatives. It benefits from growing clinical trial outsourcing due to cost efficiency and large patient pools. Government programs encourage genomic research and early diagnosis. Expanding hospital networks support site expansion and trial scalability. Increasing sponsor interest strengthens long-term regional participation.
Key Player Analysis:
- Takeda Pharmaceutical Company Limited
- Hoffmann-La Roche Ltd
- Pfizer Inc
- AstraZeneca
- Novartis AG
- Laboratory Corporation of America Holdings (LabCorp)
- IQVIA
- Charles River Laboratories
- ICON plc
- Parexel International (MA) Corporation
Competitive Analysis:
The Rare Disease Clinical Trials Market features a competitive landscape defined by specialized expertise, strategic partnerships, and global execution capability. Leading contract research organizations compete through deep experience in orphan indications, regulatory navigation, and patient-centric trial design. It favors firms that offer integrated services across clinical development, data management, and regulatory support. Large CROs leverage global site networks and advanced analytics to manage complex, multi-region studies. Mid-sized and niche players differentiate through focus on gene therapy, rare oncology, and neuromuscular disorders. Biopharmaceutical sponsors select partners based on recruitment performance, protocol flexibility, and compliance strength. Competitive intensity increases due to limited patient pools and overlapping pipelines. Companies invest in digital tools, decentralized trial capabilities, and real-world data integration to strengthen positioning. Strategic alliances with patient advocacy groups enhance enrollment success. The landscape rewards operational precision, scientific depth, and consistent regulatory outcomes.
Recent Developments:
- In September 2025, F. Hoffmann-La Roche Ltd entered a definitive merger agreement to acquire 89bio, targeting pegozafermin for MASH treatment.
- In October 2025, Takeda announced its initial oncology partnership with Innovent Biologics for late-stage solid tumor medicines outside Greater China.
Report Coverage:
The research report offers an in-depth analysis based on Phase, Therapeutic Area, Sponsor and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The Rare Disease Clinical Trials Market will advance through greater emphasis on precision medicine and molecularly targeted therapies tailored to defined patient subgroups.
- Sponsors will expand use of adaptive and seamless trial designs to improve efficiency and reduce development timelines in small populations.
- Decentralized trial models will gain wider acceptance to improve patient access, retention, and data continuity across long study durations.
- Regulators will continue to support flexible approval pathways and innovative endpoints for therapies addressing high unmet medical need.
- Gene therapy and cell-based programs will increase trial complexity and demand specialized clinical and regulatory expertise.
- Patient advocacy organizations will strengthen influence on trial design, recruitment strategy, and outcome relevance.
- Global collaboration will rise to address ultra-rare conditions that require cross-border patient enrollment.
- Digital health technologies will play a larger role in remote monitoring, safety oversight, and real-world outcome capture.
- Sponsors will prioritize partnerships with specialized research networks to improve execution quality and compliance consistency.
- Long-term outlook reflects sustained innovation, stronger patient engagement, and continuous evolution of trial methodologies.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Orphan Drug Development and Targeted Therapy Pipelines
Pharmaceutical and biotechnology companies are increasingly prioritizing rare disease indications due to regulatory incentives, premium pricing, and lower competition, which drives more clinical trials focused on orphan drugs and targeted therapies.
Advances in Genomic Diagnostics and Patient Identification Capabilities
Improvements in genomic sequencing, biomarker discovery, and molecular diagnostics enable earlier and more accurate identification of rare disease patients, facilitating better cohort selection and increasing the feasibility and success rates of clinical trials.
Supportive Regulatory Frameworks and Accelerated Approval Pathways
Regulatory agencies offer fast-track designations, tax credits, and extended exclusivity for rare disease therapies, reducing development risk and encouraging sponsors to invest in rare disease clinical trials.
Rising Adoption of Adaptive and Decentralized Trial Designs
Adaptive trial models and decentralized, patient-centric approaches allow for more flexible, efficient, and accessible studies, which are particularly valuable in rare diseases where patient populations are small and geographically dispersed.
Growing Role of Patient Advocacy Groups and Specialized Research Networks
Active involvement of patient advocacy organizations and research networks enhances disease awareness, supports recruitment, and improves trial retention, making it easier to enroll and retain rare disease patients in clinical studies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size of the Rare Disease Clinical Trials Market and its projected value by 2032?
What growth rate is expected for the Rare Disease Clinical Trials Market during the forecast period?
Which trial phase accounts for a significant share of activity in the market?
What are the key factors driving growth in the Rare Disease Clinical Trials Market?
Who are the leading participants operating in the Rare Disease Clinical Trials Market?
Which region held the largest share of the Rare Disease Clinical Trials Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Phase
- 1.2.1 Phase I
- 1.2.2 Phase II
- 1.2.3 Phase III
- 1.2.4 Phase IV
- 1.3 By Sponsor
- 1.3.1 Pharmaceutical Companies
- 1.3.2 Biotechnology Companies
- 1.3.3 Academic and Research Institutes
- 1.3.4 Contract Research Organizations (CROs)
- 1.3.5 Government and Non-Profit Organizations
- 1.4 By Therapeutic Area
- 1.4.1 Oncology
- 1.4.2 Neurology
- 1.4.3 Genetic and Inherited Disorders
- 1.4.4 Metabolic Disorders
- 1.4.5 Immunology
- 1.4.6 Cardiovascular Rare Diseases
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12,949 million → 2032: USD 21,592.72 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Rare Disease Clinical Trials Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Rare Disease Clinical Trials Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Rare Disease Clinical Trials Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Rare Disease Clinical Trials Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Rare Disease Clinical Trials Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Rare Disease Clinical Trials Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Rare Disease Clinical Trials Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Rare Disease Clinical Trials Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12,949 million → 2032: USD 21,592.72 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Rare Disease Clinical Trials Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Phase - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Phase I
- 12.3.7.2 Phase II
- 12.3.7.3 Phase III
- 12.3.7.4 Phase IV
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Sponsor - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pharmaceutical Companies
- 12.4.7.2 Biotechnology Companies
- 12.4.7.3 Academic and Research Institutes
- 12.4.7.4 Contract Research Organizations (CROs)
- 12.4.7.5 Government and Non-Profit Organizations
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Therapeutic Area - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oncology
- 12.5.7.2 Neurology
- 12.5.7.3 Genetic and Inherited Disorders
- 12.5.7.4 Metabolic Disorders
- 12.5.7.5 Immunology
- 12.5.7.6 Cardiovascular Rare Diseases
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Rare Disease Clinical Trials Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Rare Disease Clinical Trials Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Rare Disease Clinical Trials Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Takeda Pharmaceutical Company Limited
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Hoffmann-La Roche Ltd
- 17.4 Pfizer Inc
- 17.5 AstraZeneca
- 17.6 Novartis AG
- 17.7 Laboratory Corporation of America Holdings (LabCorp)
- 17.8 IQVIA
- 17.9 Charles River Laboratories
- 17.10 ICON plc
- 17.11 Parexel International (MA) Corporation
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

