
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Orthopaedic Prosthetics Devices Market Size 2024 | USD 7360 million |
| Orthopaedic Prosthetics Devices Market, CAGR | 5.7% |
| Orthopaedic Prosthetics Devices Market Size 2032 | USD 11467.7 million |
Market Overview:
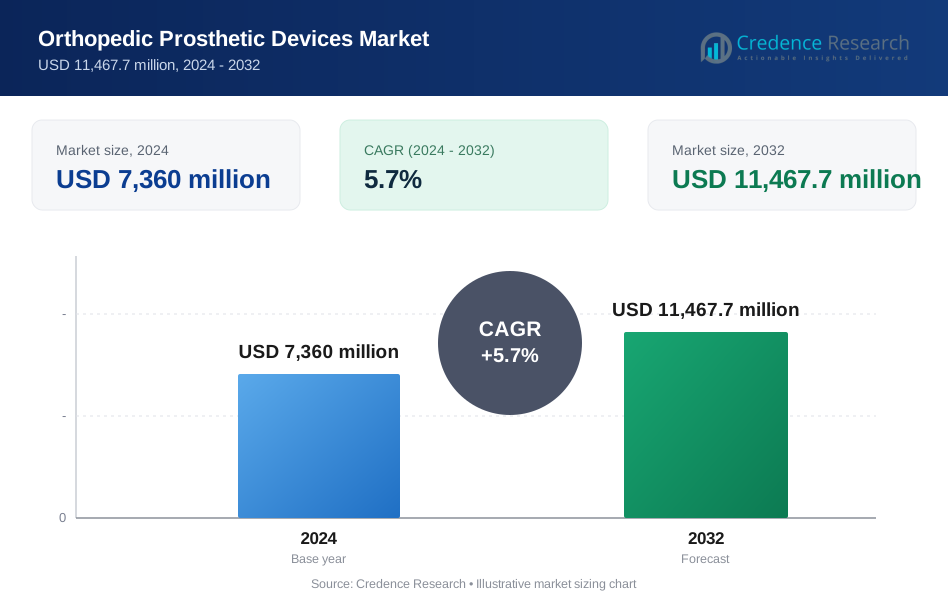
The Orthopedic Prosthetic Devices market is projected to grow from USD 7360 million in 2024 to an estimated USD 11467.7 million by 2032, with a compound annual growth rate (CAGR) of 5.7% from 2024 to 2032.
Key drivers of the Orthopedic Prosthetic Devices market include the rising prevalence of conditions that lead to limb amputation, such as diabetes and peripheral arterial disease, especially among aging populations. Road traffic accidents and combat injuries also contribute significantly to global amputation rates. Technological innovations, such as microprocessor-controlled knees, 3D printing for custom-fit limbs, and sensor-integrated solutions, are enhancing user comfort and improving mobility outcomes. Growing consumer awareness about the availability of advanced prosthetic solutions, coupled with increasing government and non-profit support, is making these technologies more accessible across various socioeconomic groups. In addition, manufacturers are focusing on developing lightweight, durable, and more life-like prosthetics that integrate seamlessly into patients’ lifestyles, thereby accelerating market adoption.
Regionally, North America leads the Orthopedic Prosthetic Devices market, accounting for over 38% of global revenue, fueled by high healthcare spending, early adoption of technology, and a strong reimbursement framework in the United States and Canada. Europe follows, with countries such as Germany, the UK, and France investing heavily in prosthetic innovation and patient rehabilitation. Asia-Pacific is emerging as the fastest-growing region due to improving healthcare infrastructure, rising disposable income, and large diabetic and aging populations, particularly in China, India, and Japan. Government programs and growing NGO involvement in limb replacement services are also strengthening market presence in these regions. Latin America and the Middle East & Africa show moderate growth potential, constrained by limited access and affordability but supported by expanding trauma care and charitable outreach programs. The global Orthopedic Prosthetic Devices market thus demonstrates strong long-term potential, driven by technological evolution, healthcare development, and a rising need for personalized, functional prosthetic solutions.
Market Insights:
- The Orthopedic Prosthetic Devices market is projected to grow from USD 7,360 million in 2024 to USD 11,467.7 million by 2032, reflecting a CAGR of 5.7%, driven by rising global demand for advanced limb replacement solutions.
- A sharp increase in limb amputations caused by diabetes, vascular disease, and traumatic injuries is creating consistent demand for Orthopedic Prosthetic Devices across aging populations and developing regions.
- Rapid innovation in prosthetic technology-including microprocessor-controlled joints, 3D printing, and myoelectric limbs-is elevating patient mobility and comfort, supporting higher adoption rates.
- Expanding global healthcare access, combined with stronger government subsidies, insurance schemes, and non-profit support, is helping make prosthetic devices more available across diverse socioeconomic groups.
- The market is seeing a shift toward highly personalized prosthetic solutions enabled by digital scanning and additive manufacturing, meeting individual needs across sports, pediatric, and elderly user segments.
- High costs and limited insurance reimbursement remain key barriers, especially for low-income patients and regions where advanced prosthetics remain unaffordable despite their clinical advantages.
- North America leads the global Orthopedic Prosthetic Devices market with a 38% share, followed by Europe at 27%, while Asia-Pacific emerges as the fastest-growing region, holding 22% of the market share and gaining momentum through public investment and infrastructure development.
Market Drivers:
Rising Amputation Rates Due to Chronic Conditions and Trauma Drive Global Demand:
A primary driver of the Orthopedic Prosthetic Devices market is the increasing number of amputations caused by diabetes, peripheral vascular disease, cancer, and traumatic injuries. Globally, diabetes-related foot complications have emerged as a leading cause of lower-limb amputations, especially among aging populations. Military conflicts, road accidents, and occupational hazards further add to the growing amputee population. The demand for effective prosthetic rehabilitation solutions is rising in parallel. Healthcare systems across regions are prioritizing early intervention and functional recovery, which increases the demand for high-quality prosthetic devices. The Orthopedic Prosthetic Devices market is responding to this demographic and epidemiological trend with steady product innovation and accessibility improvements.
- For instance, Ottobock reported in 2024 that its C-Leg microprocessor knee prosthesis has been fitted to over 100,000 users worldwide, supporting clinical programs in more than 50 countries to address the needs of patients following lower-limb amputations due to diabetes and trauma.
Technological Advancements Enhance Functionality and Patient Acceptance:
Rapid advancements in materials science, biomechanical engineering, and wearable technologies are significantly reshaping the Orthopedic Prosthetic Devices market. Innovations such as microprocessor-controlled joints, myoelectric limbs, and 3D-printed custom prosthetics are delivering enhanced mobility, comfort, and lifelike movement. These technologies improve quality of life by enabling patients to regain independence and confidence in daily tasks. Lighter composite materials and modular designs allow easier adjustments and longer wearability. Prosthetic developers continue to integrate smart sensors and AI-based systems that provide feedback and adaptive responses to different environments. The market benefits directly from the increasing acceptance and demand for high-performance solutions that match user expectations.
- For instance, Össur’s Rheo Knee® XC, a microprocessor-controlled knee, has been shown in clinical studies to reduce the risk of falls by 80% compared to mechanical knees, and the company has distributed over 60,000 microprocessor knees globally as of 2024.
Expanding Global Healthcare Access and Government Support Fuel Adoption:
Improved access to rehabilitation centers and orthopaedic care in both developed and developing regions contributes to the growth of the Orthopedic Prosthetic Devices market. Public health programs and government initiatives are making prosthetic devices more accessible through subsidies, insurance coverage, and charitable collaborations. Countries like the U.S., Germany, and Japan offer comprehensive reimbursement policies, which encourage wider adoption of advanced prosthetics. Emerging economies are also witnessing increased public-private partnerships to provide free or low-cost prosthetic care to underserved communities. Rising awareness through non-governmental organizations and advocacy groups helps drive utilization rates among amputees. It reinforces the role of institutional support in shaping demand patterns and expanding market reach.
Growing Emphasis on Personalized Rehabilitation and Lifestyle Integration:
The modern Orthopedic Prosthetic Devices market reflects a shift toward patient-centric solutions that prioritize customization, functionality, and lifestyle integration. Consumers expect devices tailored to their physical characteristics, mobility needs, and personal goals. Advances in digital scanning, computer-aided design, and additive manufacturing support individualized prosthetic fittings with high precision. Rehabilitation specialists increasingly collaborate with prosthetic manufacturers to align clinical outcomes with user preferences. Sports enthusiasts, children, and elderly users all require prosthetics adapted to specific use cases. The demand for adaptive, aesthetically pleasing, and high-performance devices underscores the market’s evolution toward patient empowerment and lifestyle-oriented design.
Market Trends:
Integration of Digital Health Platforms and Tele-rehabilitation Solutions:
Digital health integration is becoming a prominent trend in the Orthopedic Prosthetic Devices market. Remote monitoring tools, virtual fittings, and tele-rehabilitation platforms are streamlining patient care beyond traditional clinical settings. These technologies help patients access follow-up services and adjustments without frequent in-person visits, especially in rural or underserved regions. Telehealth platforms support better continuity of care and enhance patient adherence to rehabilitation protocols. Prosthetists and clinicians use remote assessment tools to fine-tune prosthetic performance in real time. The market is increasingly aligning with healthcare digitalization by embedding support services into virtual ecosystems.
- For instance, Ottobock’s new digital prosthetic and orthotic solutions, showcased at the I.S.P.O. World Congress 2025, include the speedhand app, which allows users to adjust prosthesis settings such as reaction speed directly from their smartphone, supporting remote customization and improved user experience.
Focus on Aesthetic and Lifestyle-Oriented Prosthetics Design:
User expectations are shifting toward prosthetics that blend functional performance with aesthetic appeal. Patients seek devices that look more natural, support athletic activities, or match personal fashion preferences. This trend influences the Orthopedic Prosthetic Devices market to offer sleek, customizable designs with user-defined color, shape, or finish. Cosmetic covers, athletic-grade prosthetics, and minimalistic limb designs reflect this preference shift. The market is expanding its offerings to suit the lifestyles of diverse user segments, including younger demographics and physically active individuals. Design innovation now targets emotional well-being and confidence, not just mobility.
- For instance, Össur’s acquisition of Naked Prosthetics in March 2024 expanded its upper limb product offering with functional, high-quality finger prostheses designed to mimic natural finger motion, supporting job retention and active lifestyles for partial-hand amputees.
Increased Commercialization of Bionic and AI-Based Prosthetic Solutions:
Bionic limbs and AI-enabled prosthetics are transitioning from research labs to commercial availability. Companies are scaling production and distribution of robotic limbs that interpret muscle signals, environmental inputs, and movement patterns. These advanced systems can adapt to walking surfaces, stairs, and complex physical tasks with real-time responsiveness. The Orthopedic Prosthetic Devices market sees increased investment in smart prosthetics that offer near-natural motion. Manufacturers collaborate with tech firms to develop software-driven enhancements that boost autonomy. The commercial adoption of these products is gaining momentum due to rising awareness and user demand for intuitive mobility aids.
Growing Role of 3D Printing in Reducing Production Time and Cost:
3D printing is revolutionizing the prosthetics manufacturing landscape by allowing faster prototyping, cost-efficient customization, and decentralized production. Clinics and hospitals use in-house printers to fabricate sockets and components tailored to patient anatomy. It helps reduce lead times and minimize material waste during production. The Orthopedic Prosthetic Devices market benefits from this trend by serving patients in low-resource settings with affordable alternatives. Open-source prosthetics and community-led innovation platforms are leveraging 3D printing for social impact. The scalability and flexibility of this technology support wider access and democratize device availability across regions.
Market Challenges Analysis:
High Cost and Limited Reimbursement Restrict Access for Patients:
Affordability remains one of the most significant challenges in the Orthopedic Prosthetic Devices market. Advanced prosthetics with microprocessor control, bionic components, or customized sockets can cost thousands of dollars, putting them out of reach for many patients. Insurance coverage varies widely across countries, with limited reimbursement policies in both developing and developed markets. This financial barrier discourages patients from accessing technologically advanced solutions that could significantly improve quality of life. It also impacts market adoption in middle- and low-income regions where public healthcare systems are underfunded. The Orthopedic Prosthetic Devices market must navigate complex reimbursement structures while advocating for broader financial support mechanisms.
Workforce Shortage and Inadequate Clinical Infrastructure Hinder Adoption:
The availability of trained prosthetists and clinical specialists significantly influences access to orthopaedic prosthetic services. Many regions, especially in rural and low-income countries, lack skilled professionals who can provide fitting, adjustment, and post-amputation care. Clinics often operate with outdated equipment and limited resources, reducing their capacity to deliver high-quality prosthetic solutions. The Orthopedic Prosthetic Devices market struggles to expand reach when clinical infrastructure fails to keep pace with growing demand. The need for proper patient education, follow-up, and rehabilitation also adds pressure to already strained systems. This gap between innovation and service delivery slows down adoption and weakens long-term patient outcomes.
Market Opportunities:
Technological Innovation Expands Functional Possibilities and Customization:
Advanced materials, robotics, and digital design tools are unlocking new opportunities for patient-specific orthopaedic prosthetic solutions. The integration of AI-driven gait analysis, 3D printing, and smart sensors allows manufacturers to deliver more personalized, responsive, and durable prostheses. The Orthopedic Prosthetic Devices market benefits from increased investments in R&D that support lightweight designs, improved joint mobility, and real-time adaptation to movement. It enables higher levels of patient comfort and function, especially in lower-limb prosthetics. The development of modular components and socket technologies tailored to individual anatomies further increases market potential. These innovations create new value propositions for healthcare providers and end users.
Emerging Markets Offer Growth Potential with Rising Amputation Rates and Healthcare Investment:
Rapid urbanization, aging populations, and a growing burden of non-communicable diseases contribute to a higher incidence of limb loss in emerging economies. Governments across Asia-Pacific, Latin America, and the Middle East are expanding healthcare infrastructure and adopting national disability programs. The Orthopedic Prosthetic Devices market can scale operations in these regions by forming partnerships with public health systems and local clinics. It has an opportunity to introduce cost-effective models while raising awareness about prosthetic solutions. Localized manufacturing and supply chains help reduce lead times and costs. Increasing healthcare access opens a viable pathway for market expansion beyond traditional high-income regions.
Market Segmentation Analysis:
By Product Type:
The Orthopedic Prosthetic Devices market includes upper extremity prosthetics, lower extremity prosthetics, sockets, liners, modular components, and other products. Lower extremity prosthetics, such as hip, knee, and foot devices, hold the largest share due to a higher incidence of lower limb amputations. Upper extremity prosthetics are advancing in complexity, while liners and modular components support customization and comfort, enhancing patient mobility and rehabilitation outcomes.
- For instance, Zimmer Biomet received FDA 510(k) clearance in December 2024 for its OsseoFit™ Stemless Shoulder System for total shoulder replacement, featuring an anatomically shaped design that preserves healthy bone and offers versatile patient-specific options, with commercial availability scheduled for Q1 2025.
By Technology:
Technology segmentation includes conventional, electric-powered, and hybrid prosthetics. Conventional prosthetics remain widely used for their affordability and simplicity, particularly in low-resource settings. Electric-powered prosthetics, including myoelectric and neuroprosthetic systems, are gaining traction for their improved functionality and patient control. Hybrid prosthetics, which combine mechanical durability with powered assistance, address diverse user needs and expand adoption in both developed and emerging healthcare systems.
- For instance, Phantom Neuro, with $19 million in Series A funding led by Ottobock in April 2025, is advancing minimally invasive neural interface technology for prosthetics. Its Phantom X platform achieved 94% accuracy in decoding real-time gestures across 11 hand and wrist movements, supporting lifelike control of prosthetic limbs and assistive devices.
By End User:
End users include hospitals, prosthetic clinics, orthopedic clinics, rehabilitation centers, and other healthcare providers. Prosthetic and O&P clinics form the core distribution channel due to their specialization and direct patient engagement. Hospitals and rehabilitation centers support initial fitting and therapy, while orthopedic clinics offer long-term follow-up and customization.
Segmentation:
By Product Type:
- Upper Extremity Prosthetics (e.g., shoulder, elbow, wrist, hand)
- Lower Extremity Prosthetics (e.g., hip, knee, ankle, foot)
- Sockets
- Liners
- Modular Components
- Other Products
By Technology:
- Conventional Prosthetics (mechanical, traditional)
- Electric-powered Prosthetics (myoelectric, neuroprosthetic)
- Hybrid Prosthetics (combination of mechanical and powered features)
By End User:
- Hospitals
- Prosthetic Clinics / Orthotists & Prosthetists (O&P) Clinics
- Orthopedic Clinics
- Rehabilitation Centers
- Other End Users
By Region:
- North America (U.S., Canada, Mexico)
- Europe (Germany, UK, France, Italy, Spain, Rest of Europe)
- Asia-Pacific (China, Japan, India, Australia, South Korea, Rest of Asia-Pacific)
- Middle East & Africa (GCC, South Africa, Rest of Middle East & Africa)
- South America (Brazil, Argentina, Rest of South America)
Regional Analysis:
North America Maintains Leadership through Technological Leadership and Advanced Healthcare Infrastructure
North America holds the largest share of the Orthopedic Prosthetic Devices market, accounting for approximately 38% of global revenue. The region benefits from strong reimbursement systems, high healthcare spending, and widespread adoption of advanced prosthetic technologies. The United States leads in terms of research, clinical trials, and the presence of top manufacturers and prosthetic clinics. It supports innovation through public-private partnerships and investments in robotics, smart prosthetics, and military rehabilitation programs. Canada complements the regional market with growing initiatives in mobility solutions and accessible care. High incidence of diabetes, vascular diseases, and trauma injuries continues to drive demand for limb replacement solutions.
Europe Leverages Public Health Systems and Regulatory Support
Europe represents around 27% of the Orthopedic Prosthetic Devices market, supported by established healthcare systems and aging demographics. Countries such as Germany, the UK, and France invest significantly in rehabilitation and prosthetic services. The European market places strong emphasis on product safety, patient outcomes, and functional integration, encouraged by strict regulatory frameworks. It fosters adoption of technologically advanced prosthetics while ensuring affordability through insurance coverage and state-funded programs. The presence of skilled orthotists and a collaborative network between hospitals and rehabilitation centers strengthens care quality. Increasing incidence of amputations related to chronic conditions and sports injuries supports stable demand across both lower- and upper-limb prosthetics.
Asia-Pacific Emerges as the Fastest-Growing Region Driven by Demographic and Economic Shifts
Asia-Pacific holds about 22% of the Orthopedic Prosthetic Devices market and is expected to grow at the highest through the forecast period. China, India, and Japan lead regional demand due to population size, rising life expectancy, and increasing chronic disease prevalence. Rapid urbanization and higher rates of road traffic accidents and diabetes contribute to the growing need for prosthetic services. It sees increasing government focus on inclusive healthcare and prosthetic accessibility, particularly in rural areas. Expansion of manufacturing capabilities and training of prosthetists improve product availability and service delivery. Rising health awareness and income levels continue to reshape demand patterns toward higher-quality, functional prosthetic solutions.
Key Player Analysis:
- Ottobock (Otto Bock)
- Össur
- Zimmer Biomet
- Blatchford
- Fillauer
- Willow Wood Global
- Mobius Bionics
- Hanger Inc.
- Steeper
- Coloplast
- Freedom Innovations
Competitive Analysis:
The Orthopedic Prosthetic Devices market features a competitive landscape with a mix of established global players and emerging regional firms. Key companies such as Össur, Ottobock, Fillauer, Blatchford Group, and Steeper Group lead through continuous product innovation and strong clinical support networks. It sees companies investing heavily in advanced materials, bionic limbs, and sensor-integrated prosthetics to enhance user comfort and mobility. Strategic collaborations with hospitals, rehabilitation centers, and defense sectors help expand patient reach and service quality. The market favors players with strong R&D pipelines and rapid customization capabilities to meet diverse patient needs. Competitive differentiation often hinges on technology integration, lightweight designs, and user-centric solutions. Companies are also focusing on expanding into emerging markets where demand for affordable prosthetic care is rising.
Recent Developments:
- In March 2025, Ottobockunveiled several new products at the I.S.P.O. World Congress, including the speedhand myoelectric prosthesis and the Maverick junior hydraulic knee joint for children. The speedhand system features a synchronized app for real-time adjustments, while the Maverick junior is the world’s smallest hydraulic knee joint, specifically designed to help children learn to walk correctly with a prosthesis. Ottobock also showcased advancements in digitalization, such as EasyScan technology for millimeter-accurate body measurements and cloud-based work.hub integration for prosthetics fabrication, underscoring its leadership in smart, patient-centered solutions.
- In December 2024, Zimmer Biometreceived FDA 510(k) clearance for its OsseoFit™ Stemless Shoulder System for total shoulder replacement. This innovative implant features an anatomically shaped design that preserves healthy bone and offers versatile, patient-specific options. The OsseoFit system integrates with Identity® Humeral Heads and Alliance® Glenoid and will be commercially available in Q1 2025.
- In September 2023, Willow Wood Globallaunched a new brand identity to reflect its expansion into new product lines and technologies, including high-performance prosthetic feet and myoelectric liners for upper-limb bionic prostheses. The company has introduced over 15 new products in the last two years, backed by $12 million in federal grant funding, and continues to seek acquisitions and partnerships to drive innovation in the prosthetics industry.
- In October 2023, Mobius Bionicsannounced the commercial launch of the LUKE prosthetic arm, developed in collaboration with DEKA Research & Development and DARPA. The LUKE arm provides unmatched flexibility, strength, and dexterity for upper-limb amputees, representing a breakthrough in integrated prosthetic arm technology.
Market Concentration & Characteristics:
The Orthopedic Prosthetic Devices market shows moderate to high market concentration, with a few global players controlling a significant share. It is characterized by strong brand loyalty, clinical partnerships, and high entry barriers due to regulatory approvals and technical expertise. Customization plays a critical role, requiring companies to maintain advanced manufacturing capabilities and tailored patient care. The market leans heavily on innovation, especially in bionic and myoelectric technologies, while maintaining compliance with strict medical device standards. It exhibits a steady demand pattern driven by long-term care needs and rising amputation rates. Pricing remains premium, particularly for advanced products, though emerging markets are shifting demand toward cost-effective solutions.
Report Coverage:
The research report offers an in-depth analysis based on By Product Type, By Technology, By End User and By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising global incidence of limb loss will drive sustained demand for prosthetic solutions.
- Aging populations in developed regions will increase the need for lower-limb prosthetics.
- Advancements in materials science will enable lighter, more durable prosthetic devices.
- Growing adoption of myoelectric and sensor-based technologies will enhance user mobility.
- Increased healthcare spending in emerging markets will support broader access to prosthetics.
- Integration of 3D printing will reduce production time and support personalized prosthesis design.
- Expanding use of digital health platforms will improve remote fitting and post-operative care.
- Strategic collaborations between manufacturers and rehabilitation centers will enhance distribution.
- Regulatory focus on patient safety and device performance will shape product development.
- Military and trauma-related amputations will continue to influence research and innovation efforts.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Amputation Rates Due to Chronic Conditions and Trauma
Increasing prevalence of diabetes, peripheral vascular disease, and traumatic injuries such as road accidents and military conflicts is leading to higher rates of limb amputations globally, fueling demand for orthopedic prosthetic devices.
Technological Advancements in Prosthetics
Innovations like microprocessor-controlled joints, myoelectric limbs, 3D printing, and sensor-integrated solutions are improving mobility, comfort, and customization, making prosthetic devices more attractive and accessible to a wider patient base.
Expanding Global Healthcare Access and Government Support
Broader insurance coverage, government subsidies, and non-profit initiatives are making advanced prosthetic devices more available, especially in emerging markets, thus expanding the addressable market.
Growing Emphasis on Personalized and Lifestyle-Oriented Prosthetics
Patients increasingly seek prosthetics tailored to their individual needs, lifestyles, and aesthetic preferences, driving manufacturers to offer more personalized, adaptive, and user-friendly solutions.
Integration of Digital Health and Tele-rehabilitation
The adoption of digital health platforms and tele-rehabilitation tools enables remote fitting, monitoring, and adjustment of prosthetic devices, improving patient outcomes and expanding access, particularly in underserved regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Orthopedic Prosthetic Devices market?
What factors are driving the growth of the Orthopedic Prosthetic Devices market?
What are the key segments within the Orthopedic Prosthetic Devices market?
What are some challenges faced by the Orthopedic Prosthetic Devices market?
Who are the major players in the Orthopedic Prosthetic Devices market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Prosthetic Clinics / Orthotists & Prosthetists (O&P) Clinics
- 1.2.3 Orthopedic Clinics
- 1.2.4 Rehabilitation Centers
- 1.2.5 Other End Users
- 1.3 By Technology
- 1.3.1 Conventional Prosthetics (mechanical, traditional)
- 1.3.2 Electric-powered Prosthetics (myoelectric, neuroprosthetic)
- 1.3.3 Hybrid Prosthetics (combination of mechanical and powered features)
- 1.4 By Product Type
- 1.4.1 Upper Extremity Prosthetics (shoulder, elbow, wrist, hand)
- 1.4.2 Lower Extremity Prosthetics (hip, knee, ankle, foot)
- 1.4.3 Sockets
- 1.4.4 Liners
- 1.4.5 Modular Components
- 1.4.6 Other Products
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,360 million → 2032: USD 11,467.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Orthopedic Prosthetic Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Orthopedic Prosthetic Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Orthopedic Prosthetic Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Orthopedic Prosthetic Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Orthopedic Prosthetic Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Orthopedic Prosthetic Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Orthopedic Prosthetic Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Orthopedic Prosthetic Devices Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,360 million → 2032: USD 11,467.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Orthopedic Prosthetic Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Prosthetic Clinics / Orthotists & Prosthetists (O&P) Clinics
- 12.3.7.3 Orthopedic Clinics
- 12.3.7.4 Rehabilitation Centers
- 12.3.7.5 Other End Users
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Conventional Prosthetics (mechanical, traditional)
- 12.4.7.2 Electric-powered Prosthetics (myoelectric, neuroprosthetic)
- 12.4.7.3 Hybrid Prosthetics (combination of mechanical and powered features)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Upper Extremity Prosthetics (shoulder, elbow, wrist, hand)
- 12.5.7.2 Lower Extremity Prosthetics (hip, knee, ankle, foot)
- 12.5.7.3 Sockets
- 12.5.7.4 Liners
- 12.5.7.5 Modular Components
- 12.5.7.6 Other Products
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Orthopedic Prosthetic Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Orthopedic Prosthetic Devices Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Orthopedic Prosthetic Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Orthopedic Prosthetic Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Ottobock
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Össur
- 18.4 Zimmer Biomet
- 18.5 Blatchford
- 18.6 Fillauer
- 18.7 Willow Wood Global
- 18.8 Mobius Bionics
- 18.9 Hanger Inc.
- 18.10 Steeper
- 18.11 Freedom Innovations
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

