
Market Overview
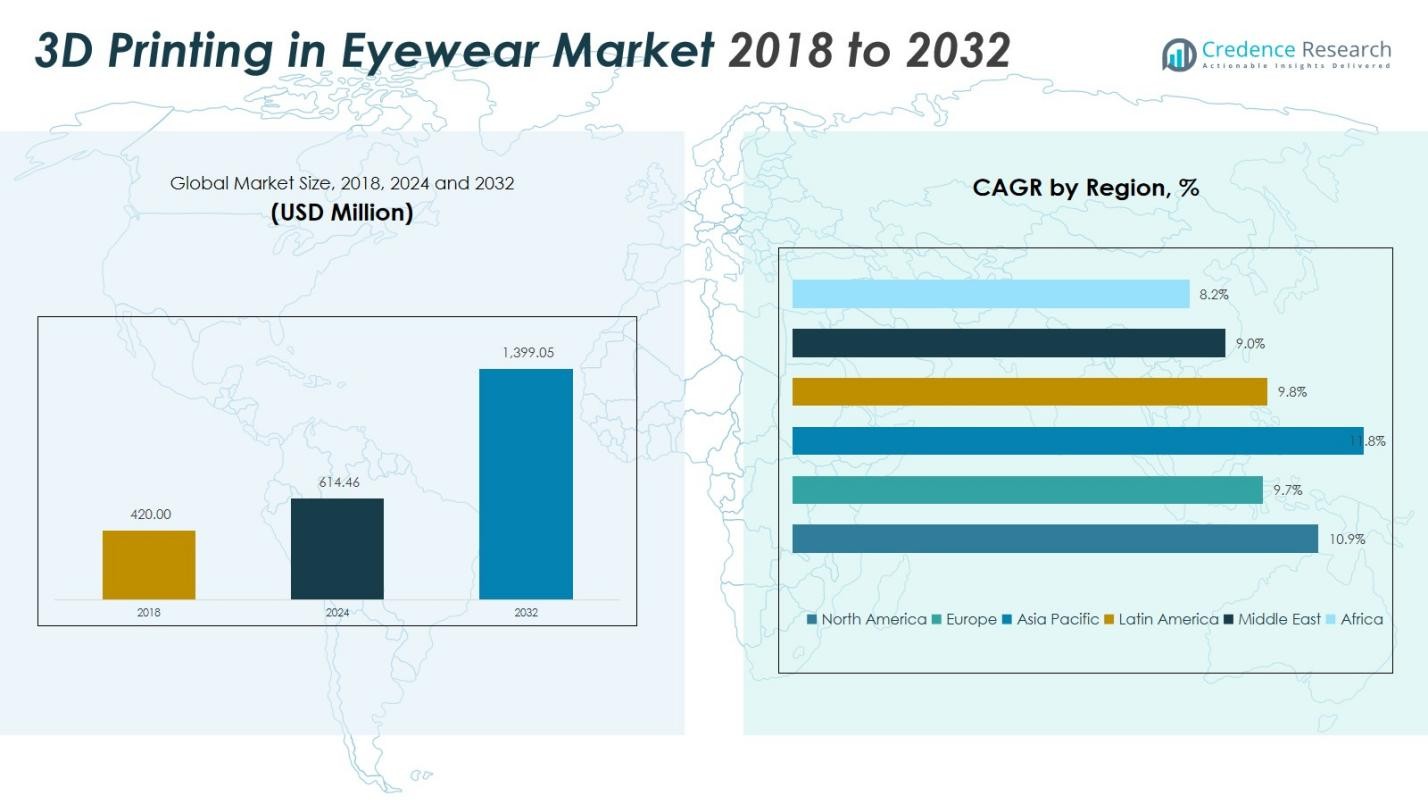
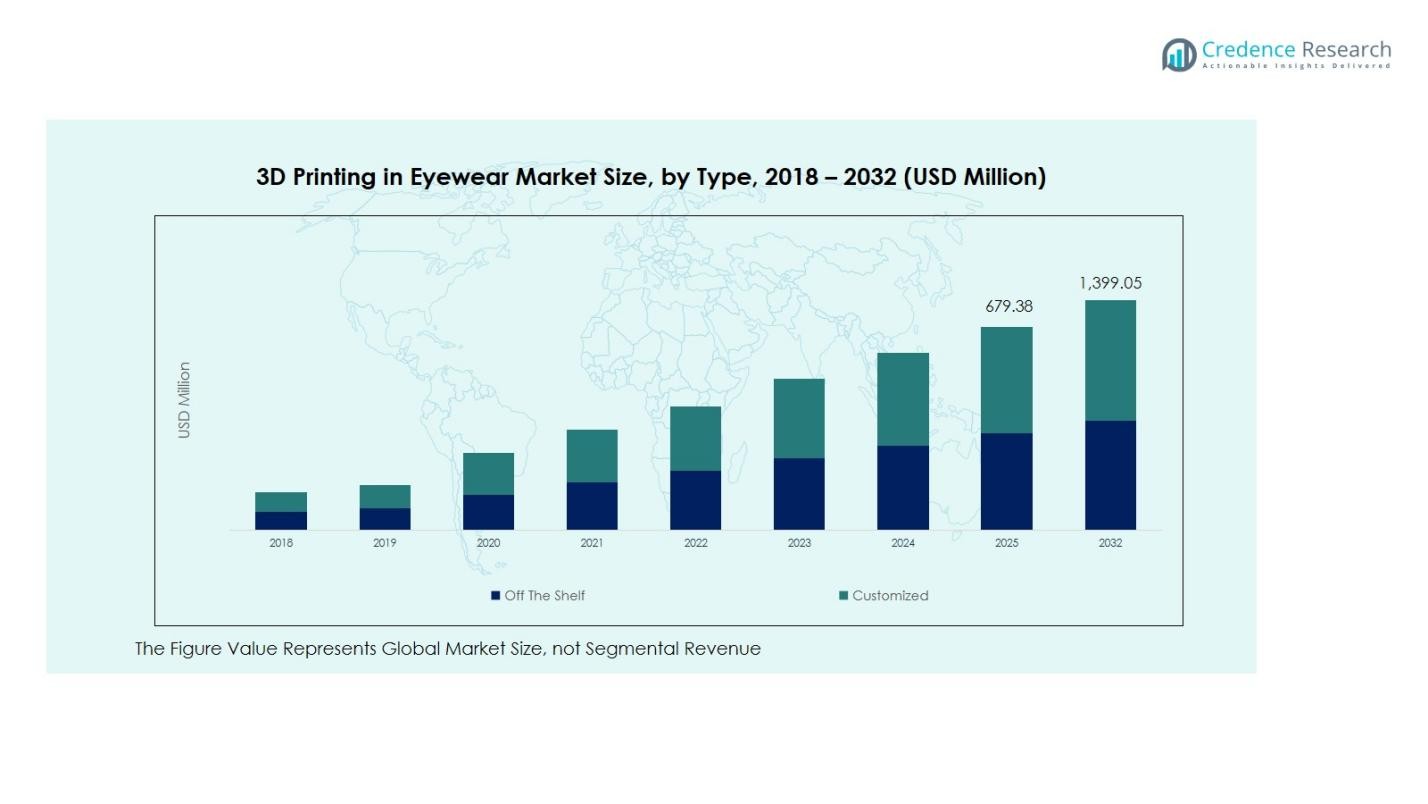
The 3D Printing in Eyewear Market size was valued at USD 420.00 million in 2018, reaching USD 614.46 million in 2024, and is anticipated to attain USD 1,399.05 million by 2032, growing at a CAGR of 10.87% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| 3D Printing in Eyewear Market Size 2024 | USD 614.46 Million |
| 3D Printing in Eyewear Market, CAGR | 10.87% |
| 3D Printing in Eyewear Market Size 2032 | USD 1,399.05 Million |
The 3D Printing in Eyewear Market is characterized by strong competition among leading players such as Luxottica Group, MYKITA GmbH, Formlabs, Carbon, Inc., LuxCreo, HOYA Corporation, Luxexcel, and Photocentric Ltd. These companies focus on technological innovation, digital customization, and sustainable material development to enhance product quality and design flexibility. Strategic collaborations, AI integration, and automation in additive manufacturing have further strengthened their market presence. Asia Pacific emerged as the leading region in 2024, commanding a 37.6% market share, driven by rapid industrialization, growing consumer preference for customized eyewear, and expanding 3D printing infrastructure across China, Japan, and South Korea.
Market Insights
- The 3D Printing in Eyewear Market was valued at USD 614.46 million in 2024 and is projected to reach USD 1,399.05 million by 2032, growing at a CAGR of 10.87% during the forecast period.
- Rising demand for customized eyewear, driven by consumer preference for personalization, comfort, and sustainable materials, is fueling market expansion across both luxury and mass-market segments.
- The market is witnessing trends such as the integration of AI, 3D scanning, and digital modeling for precision design, along with the adoption of eco-friendly materials like bio-based polymers and recycled composites.
- Leading players including Luxottica Group, MYKITA GmbH, Formlabs, and Carbon, Inc. are investing in advanced additive manufacturing technologies to gain a competitive edge and enhance scalability.
- Asia Pacific dominates with a 6% regional share, while the Customized segment leads globally with 63% share, reflecting strong demand for personalized and technology-driven eyewear solutions.
 Market Segmentation Analysis:
By Type:
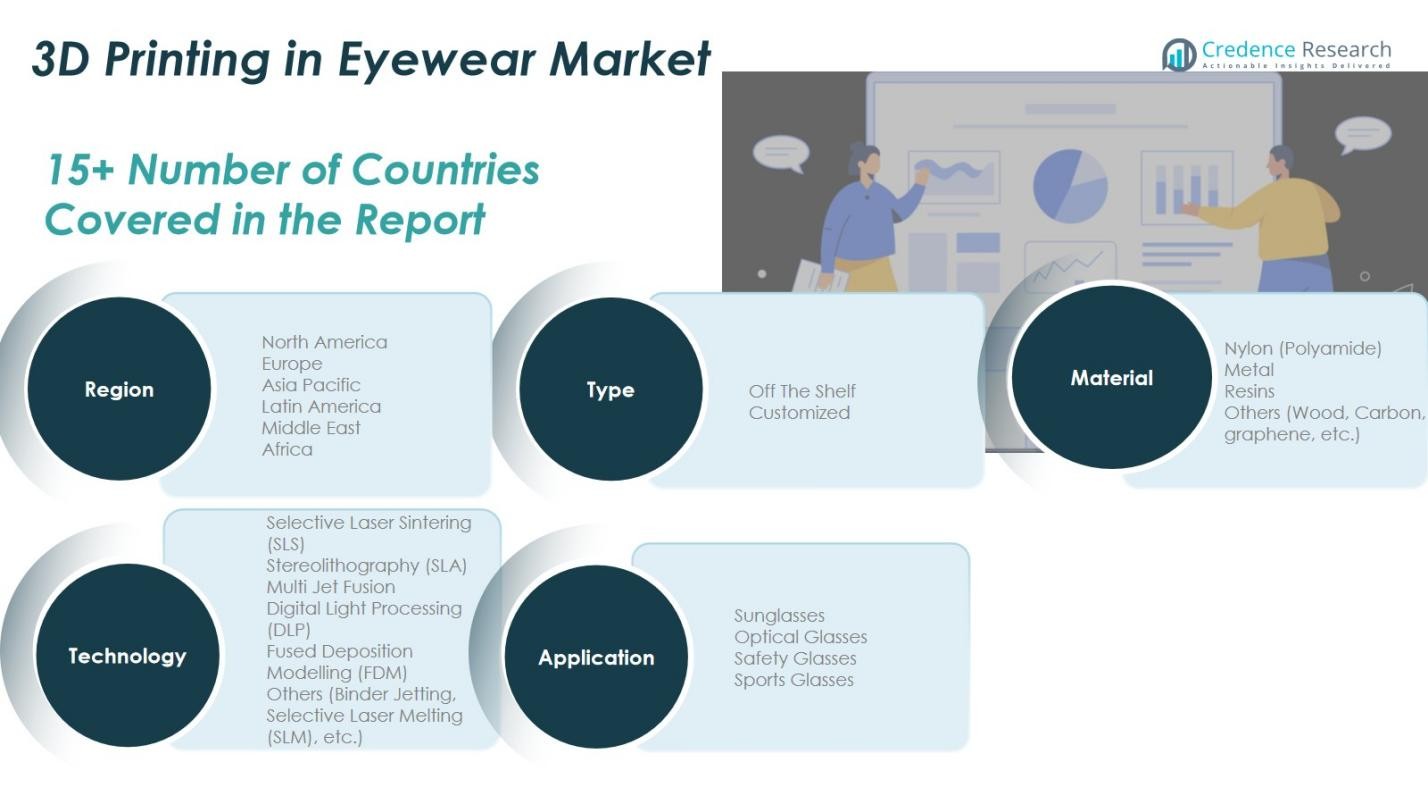
The 3D Printing in Eyewear Market by type is segmented into Off the Shelf and Customized eyewear. The Customized segment dominated the market with over 63% share in 2024, driven by rising consumer demand for personalized designs, superior comfort, and precise fitting. Technological advancements in 3D scanning and digital modeling have enhanced customization accuracy, enabling brands to deliver tailor-made frames efficiently. Meanwhile, the Off the Shelf segment holds a smaller market portion, primarily catering to cost-conscious consumers and fast-fashion eyewear brands seeking mass production efficiency with limited personalization options.
By Application:
Based on application, the market is segmented into Sunglasses, Optical Glasses, Safety Glasses, and Sports Glasses. Optical Glasses held the leading market share of around 42% in 2024, owing to their high usage in prescription eyewear and increasing adoption of 3D printing for lightweight, durable, and ergonomic frames. Sunglasses follow closely, driven by fashion-conscious consumers and innovative designs offered through additive manufacturing. Safety and sports glasses are emerging segments, benefiting from industrial and athletic applications that demand high-performance, impact-resistant materials and custom-fit features.
For instance, YOU MAWO uses infrared scanning on an iPad to create a full facial 3D scan in less than 20 seconds, feeding into a parametric design engine that configures bespoke frames for each customer.
By Material:
The material segment includes Nylon (Polyamide), Metal, Resins, and Others such as Wood, Carbon, and Graphene. Nylon (Polyamide) dominated the market with approximately 58% share in 2024, attributed to its flexibility, lightweight properties, and suitability for complex geometric designs in eyewear frames. Metal-based 3D printed eyewear is gaining traction for premium and luxury applications due to its superior strength and sleek aesthetics. Resins and other advanced materials are gradually expanding, supported by ongoing research into sustainable and high-strength composites that enhance product durability and environmental performance.
For instance, the French company Netlooks, working with Sculpteo, fabricates optical frames in PA12 via powder sintering, adjusting temple length, face width, and color per customer morphology.
 Key Growth Drivers
Rising Demand for Customized and Personalized Eyewear
The growing consumer preference for personalized eyewear designs is a major driver of the 3D Printing in Eyewear Market. Additive manufacturing enables the production of tailor-made frames that perfectly fit individual facial features, enhancing comfort and style. This customization trend aligns with the broader shift toward consumer-centric design and luxury personalization. Brands are increasingly adopting 3D scanning and digital modeling technologies to streamline production, reduce waste, and deliver unique eyewear experiences, positioning customization as a key differentiator in the competitive eyewear industry.
For instance, Netlooks produces PA12-based eyewear frames where the temple length, bridge width and frame color are dynamically adjusted per customer morphology via its digital modelling pipeline.
Advancements in Additive Manufacturing Technologies
Continuous improvements in 3D printing technologies, such as Selective Laser Sintering (SLS), Stereolithography (SLA), and Multi Jet Fusion (MJF), have significantly expanded the design and material capabilities for eyewear manufacturing. These technologies enable intricate frame geometries, superior durability, and enhanced aesthetic appeal. The integration of automation, AI-based design software, and high-speed printing systems further improves production efficiency. This technological progress is driving widespread adoption across both luxury and mass-market eyewear brands, fostering innovation and reducing prototyping and production costs.
For instance, MYKITA’s MYLON® range uses SLS-printed polyamide powder to create frames that are 30 % lighter than acetate and allow much thinner temple and bridge designs than conventional materials
Sustainability and Waste Reduction in Eyewear Manufacturing
Sustainability has become a key growth driver in the 3D Printing in Eyewear Market. Traditional eyewear manufacturing generates significant material waste, while 3D printing allows on-demand production and optimized material usage. Eco-friendly materials such as bio-based polymers and recyclable resins are increasingly used to create sustainable frames. Moreover, localized additive manufacturing reduces carbon emissions associated with global supply chains. This environmentally conscious approach appeals to eco-aware consumers and supports companies’ commitments to carbon neutrality, making sustainability a core factor driving market expansion.
Key Trends & Opportunities
Integration of Smart and Functional Eyewear Designs
The integration of smart features and functional materials into 3D-printed eyewear presents a significant trend. Manufacturers are exploring embedded sensors, augmented reality lenses, and adaptive fit technologies made possible through additive manufacturing precision. This convergence of digital functionality and advanced design offers opportunities for brands to enter the smart eyewear segment. As consumer demand grows for multifunctional products that blend technology with fashion, 3D printing provides the flexibility and speed needed to innovate and prototype next-generation wearable devices.
For instance, Luxexcel partnered with WaveOptics to develop 3D-printed prescription lens modules for AR glasses, these modules integrate corrective vision and AR waveguide lenses, enabling a standard eyewear form factor with embedded functionality.
Expansion of Digital Retail and On-Demand Production Models
The rise of digital retail platforms and on-demand eyewear production is creating new growth opportunities. Consumers can now use online customization tools to design their frames, which are then produced through additive manufacturing and shipped directly. This digital-to-manufacture model minimizes inventory requirements and accelerates delivery times. Optical brands leveraging virtual try-on technologies and AI-driven design recommendations are strengthening customer engagement and reducing returns. The combination of 3D printing and e-commerce is reshaping the eyewear supply chain, promoting agility and cost efficiency.
For instance, 3DNA reports that its smart manufacturing platform has processed 4,500+ frame orders through its digital system and deployed 40+ retail kiosks, while eliminating traditional inventory-holding for partner brands.
Key Challenges
High Equipment and Material Costs
One of the primary challenges in the 3D Printing in Eyewear Market is the high cost of advanced 3D printers and materials suitable for eyewear-grade production. Industrial-grade printers, especially those using SLS and SLA technologies, require substantial investment. Additionally, high-quality printing materials such as durable polymers and metals increase production expenses. These costs can limit adoption among small and medium-sized eyewear manufacturers. Overcoming this challenge will depend on technological innovations that lower equipment prices and improve material cost-efficiency without compromising product quality.
Regulatory and Standardization Barriers
Regulatory compliance and lack of industry-wide standards present significant hurdles for the widespread commercialization of 3D-printed eyewear. Quality consistency, product durability, and safety testing remain critical concerns, especially in optical and medical-grade lenses. Differences in certification requirements across regions further complicate market entry for global brands. To address these issues, manufacturers must adopt standardized production processes, transparent quality control mechanisms, and compliance with international optical and safety regulations to ensure consumer trust and accelerate market acceptance.
 Regional Analysis
North America
The North America 3D Printing in Eyewear Market held the largest share of 33.7% in 2024, valued at USD 206.95 million, up from USD 143.30 million in 2018, and is projected to reach USD 470.50 million by 2032, growing at a CAGR of 10.9%. The region’s leadership stems from strong technological infrastructure, high consumer spending on premium eyewear, and the early adoption of 3D printing for customized optical solutions. Major players such as Luxottica and Carbon Inc. are leveraging advanced manufacturing to meet demand for lightweight, sustainable, and design-flexible eyewear products across the U.S. and Canada.
Europe
Europe accounted for 17.4% of the global market in 2024, valued at USD 106.78 million, rising from USD 77.28 million in 2018, and expected to reach USD 223.50 million by 2032, with a CAGR of 9.7%. The region benefits from a strong luxury eyewear base, particularly in Italy, France, and Germany, where established brands integrate additive manufacturing for design innovation. Stringent environmental standards and consumer preference for sustainable, customized eyewear further fuel adoption. Government support for digital manufacturing and advancements in polymer and resin materials also contribute to the region’s steady market growth.
Asia Pacific
Asia Pacific dominated the global 3D Printing in Eyewear Market with a 37.6% share in 2024, valued at USD 230.94 million, increasing from USD 153.30 million in 2018, and is forecasted to reach USD 562.84 million by 2032, registering the highest CAGR of 11.8%. Rapid urbanization, expanding middle-class income, and growing fashion awareness in China, Japan, and South Korea are propelling market expansion. Regional manufacturers are investing heavily in localized 3D printing hubs and digital design technologies. Moreover, the presence of cost-effective production facilities and adoption of innovative materials drive strong growth across the Asia Pacific region.
Latin America
The Latin America 3D Printing in Eyewear Market represented 6.0% of the global share in 2024, valued at USD 37.11 million, up from USD 25.62 million in 2018, and projected to reach USD 78.17 million by 2032, growing at a CAGR of 9.8%. Countries such as Brazil and Mexico are witnessing increasing adoption of additive manufacturing technologies for eyewear customization and low-volume production. Rising disposable incomes and expanding e-commerce penetration are supporting consumer access to affordable 3D-printed eyewear. Additionally, partnerships between local eyewear producers and technology firms are driving innovation and design flexibility in the region.
Middle East
The Middle East 3D Printing in Eyewear Market accounted for 3.1% of global share in 2024, valued at USD 16.28 million, up from USD 12.14 million in 2018, and expected to reach USD 32.19 million by 2032, registering a CAGR of 9.0%. The region’s growth is driven by increasing adoption of premium and designer eyewear, particularly in the UAE and Saudi Arabia. Investments in 3D printing technologies within the healthcare and fashion sectors are expanding local manufacturing capabilities. Moreover, the rise of luxury retail and personalization trends is encouraging regional brands to integrate additive manufacturing processes.
Africa
Africa held a 2.2% share of the global 3D Printing in Eyewear Market in 2024, valued at USD 16.41 million, compared to USD 8.36 million in 2018, and is projected to reach USD 31.86 million by 2032, at a CAGR of 8.2%. The region’s growth is emerging from increasing awareness of 3D printing applications and gradual expansion of eyewear retail networks. South Africa leads the market due to its growing technology ecosystem and local additive manufacturing initiatives. Though the market remains nascent, rising affordability and digital innovation are expected to enhance regional production and distribution capacity over time.
Market Segmentations:
By Type
- Off the Shelf
- Customized
By Application
- Sunglasses
- Optical Glasses
- Safety Glasses
- Sports Glasses
By Material
- Nylon (Polyamide)
- Metal
- Resins
- Others (Wood, Carbon, Graphene, etc.)
By Technology
- Selective Laser Sintering (SLS)
- Stereolithography (SLA)
- Multi Jet Fusion (MJF)
- Digital Light Processing (DLP)
- Fused Deposition Modelling (FDM)
- Others (Binder Jetting, Selective Laser Melting (SLM), etc.)
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the 3D Printing in Eyewear Market features prominent players such as Adidas America, Inc., Carbon, Inc., Formlabs, HOYA Corporation, Luxexcel, LuxCreo, Luxottica Group, MYKITA GmbH, MONOQOOL, Photocentric Ltd, and Rapid 3D. These companies are actively focusing on technological innovation, material advancement, and design flexibility to strengthen their market positions. Strategic collaborations, product launches, and investments in digital manufacturing capabilities define the competition. Luxury eyewear brands such as Luxottica and MYKITA are leveraging 3D printing for customized and sustainable frame production, while technology-driven firms like Formlabs and Carbon, Inc. are pioneering scalable additive manufacturing solutions. The market also witnesses rising participation from niche startups offering eco-friendly and digitally customizable eyewear collections. Continuous R&D investments, coupled with automation and AI-enabled design processes, are enhancing product precision and reducing production cycles, thereby intensifying competition among established global players and emerging innovators.
Key Player Analysis
- Adidas America, Inc.
- Carbon, Inc.
- Forma Eyewear Ltd
- Formlabs
- HOYA Corporation
- LuxCreo, Inc.
- Luxexcel
- Luxottica Group
- MONOQOOL
- MYKITA GmbH
- Photocentric Ltd
- Rapid 3D
Recent Developments
- On 17 September 2024, EssilorLuxottica announced an extension of its long-term partnership with Meta Platforms to develop multi-generational smart eyewear products.
- In October 2023, Mister Spex launched its “EyeD” custom 3D-printed eyewear collection, using 3D scanning and additive manufacturing to deliver perfect fit frames.
- In December 2023, Spectra Additive initiated full-scale production of 3D-printed eyewear frames in partnership with material specialist Henkel using DLP technology and Loctite® 3D MED9851 resin, targeting 30,000 frames in 2025.
- In 2025, Tech Print Industries (TPI) launched its “Design Gallery” at SILMO Paris 2025 a web-based platform enabling eyewear brands to design, customize, and produce frames on demand via 3D printing and AI tools.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Material, Technology and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to expand as demand for personalized and lightweight eyewear increases globally.
- Advancements in additive manufacturing will enable faster production and higher precision in eyewear design.
- Integration of AI and 3D scanning technologies will improve customization accuracy and design efficiency.
- Sustainable materials such as bio-based polymers and recycled composites will gain significant traction.
- The adoption of 3D printing by luxury and fashion brands will drive premium product innovation.
- Expanding digital retail platforms will enhance consumer access to on-demand customized eyewear.
- Collaborations between eyewear manufacturers and 3D printing technology providers will accelerate innovation.
- Asia Pacific will emerge as the fastest-growing regional market due to industrial and technological development.
- Automation in post-processing and finishing will streamline production and reduce operational costs.
- Continuous material innovations and government support for digital manufacturing will shape the market’s long-term growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Personalization and Custom Fit Demand
The ability of 3D printing to deliver highly customized eyewear frames tailored to individual facial features is driving market growth. Consumers increasingly seek unique designs and superior comfort, and brands are leveraging digital modeling and 3D scanning to efficiently produce bespoke products at scale.
Advancements in Additive Manufacturing Technologies
Continuous improvements in 3D printing methods such as SLS, SLA, and MJF have enabled the production of lightweight, durable, and complex eyewear designs. These technological advancements reduce prototyping time, enhance design flexibility, and lower production costs, making 3D printing more accessible for both luxury and mass-market eyewear brands.
Sustainable Materials and Waste Reduction
3D printing allows for on-demand manufacturing and optimized material usage, significantly reducing waste compared to traditional eyewear production. The adoption of eco-friendly materials like bio-based polymers and recycled composites appeals to environmentally conscious consumers and supports brands' sustainability initiatives.
Integration of Digital Retail and On-Demand Production
The rise of digital retail platforms and virtual try-on technologies enables consumers to design and order customized eyewear online, which is then produced using 3D printing. This model minimizes inventory, accelerates delivery, and enhances customer engagement, driving broader adoption of 3D-printed eyewear.
Collaboration Between Eyewear Brands and Technology Providers
Strategic partnerships between eyewear manufacturers and 3D printing technology companies are accelerating innovation in frame design, smart eyewear integration, and scalable production. These collaborations foster the development of advanced features and materials, strengthening the competitive position of market leaders.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the 3D Printing in Eyewear Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the 3D Printing in Eyewear Market projected to grow between 2025 and 2032?
Which 3D Printing in Eyewear Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the 3D Printing in Eyewear Market?
Who are the leading companies in the 3D Printing in Eyewear Market?
Which region commanded the largest share of the 3D Printing in Eyewear Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Off the Shelf
- 1.2.2 Customized
- 1.3 By Material
- 1.3.1 Nylon (Polyamide)
- 1.3.2 Metal
- 1.3.3 Resins
- 1.3.4 Others (Wood, Carbon, Graphene, etc.)
- 1.4 By Technology
- 1.4.1 Selective Laser Sintering (SLS)
- 1.4.2 Stereolithography (SLA)
- 1.4.3 Multi Jet Fusion (MJF)
- 1.4.4 Digital Light Processing (DLP)
- 1.4.5 Fused Deposition Modelling (FDM)
- 1.4.6 Others (Binder Jetting, Selective Laser Melting (SLM), etc.)
- 1.5 By Application
- 1.5.1 Sunglasses
- 1.5.2 Optical Glasses
- 1.5.3 Safety Glasses
- 1.5.4 Sports Glasses
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 614.46 million → 2032: USD 1,399.05 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global 3D Printing in Eyewear Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global 3D Printing in Eyewear Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global 3D Printing in Eyewear Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global 3D Printing in Eyewear Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global 3D Printing in Eyewear Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global 3D Printing in Eyewear Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global 3D Printing in Eyewear Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global 3D Printing in Eyewear Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 614.46 million → 2032: USD 1,399.05 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global 3D Printing in Eyewear Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Off the Shelf
- 12.3.7.2 Customized
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Nylon (Polyamide)
- 12.4.7.2 Metal
- 12.4.7.3 Resins
- 12.4.7.4 Others (Wood, Carbon, Graphene, etc.)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Selective Laser Sintering (SLS)
- 12.5.7.2 Stereolithography (SLA)
- 12.5.7.3 Multi Jet Fusion (MJF)
- 12.5.7.4 Digital Light Processing (DLP)
- 12.5.7.5 Fused Deposition Modelling (FDM)
- 12.5.7.6 Others (Binder Jetting, Selective Laser Melting (SLM), etc.)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Sunglasses
- 12.6.7.2 Optical Glasses
- 12.6.7.3 Safety Glasses
- 12.6.7.4 Sports Glasses
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global 3D Printing in Eyewear End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global 3D Printing in Eyewear Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global 3D Printing in Eyewear Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global 3D Printing in Eyewear Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Luxottica Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 MYKITA GmbH
- 18.4 Formlabs
- 18.5 Carbon, Inc.
- 18.6 LuxCreo
- 18.7 HOYA Corporation
- 18.8 Luxexcel
- 18.9 Photocentric Ltd
- 18.10 MONOQOOL
- 18.11 Adidas America, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

