
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
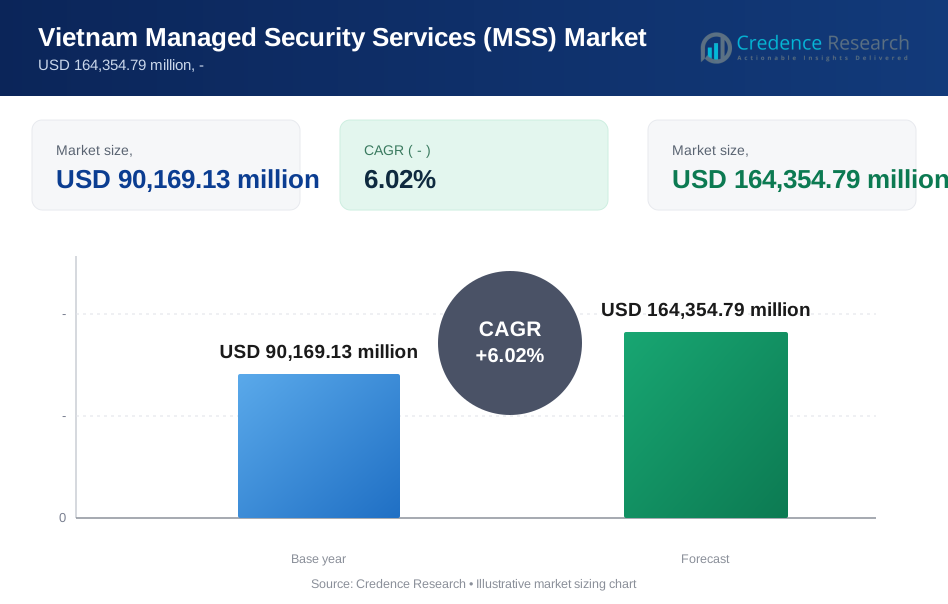
| Vietnam Managed Security Services (MSS) Market Size 2023 | USD 90,169.13 million |
| Vietnam Managed Security Services (MSS) Market, CAGR | 6.02% |
| Vietnam Managed Security Services (MSS) Market Size 2032 | USD 164,354.79 |
Market Overview
The Vietnam Managed Security Services Market is projected to witness remarkable growth, with its value expected to surge from USD 90,169.13 million in 2023 to USD 164,354.79 million by 2032, exhibiting a robust CAGR of 6.02%. The Vietnam Managed Security Services (MSS) market is a crucial segment within the cybersecurity landscape, marked by an increasing focus on safeguarding digital assets and upholding the integrity of information systems. As digital transformation accelerates across various industries and cyber threats become more sophisticated, there's a burgeoning demand for robust managed security services in Vietnam. This overview delves into the fundamental aspects, trends, challenges, and opportunities that define the Vietnam MSS market.
Driven by several factors, the Vietnam MSS market is experiencing significant growth. The proliferation of digital technologies like cloud computing, IoT, and AI has expanded the attack surface, necessitating advanced security measures. Furthermore, stringent regulatory frameworks and compliance requirements have spurred awareness and investment in cybersecurity among Vietnamese enterprises. The escalating frequency and complexity of cyber threats, ranging from malware to data breaches, emphasize the importance of proactive security measures, propelling the adoption of MSS within the region.
Despite promising growth prospects, the Vietnam MSS market faces notable challenges. The shortage of skilled cybersecurity professionals exacerbates the talent gap, hindering the effective implementation of managed security services. Moreover, the evolving nature of cyber threats necessitates continuous investment in research and development to stay ahead of adversaries, posing financial constraints for smaller enterprises. Additionally, ensuring regulatory compliance amidst evolving regulatory landscapes presents a challenge, requiring comprehensive strategies and solutions to navigate compliance requirements effectively.
Segmentation Analysis
By Type
In the Vietnam Managed Security Services (MSS) market, services are primarily segmented into two categories: fully managed and co-managed. Fully managed services involve outsourcing the entire spectrum of security operations to a third-party provider, allowing organizations to focus on their core business activities while ensuring comprehensive security coverage. On the other hand, co-managed services entail a collaborative approach where organizations retain some control over security operations while leveraging external expertise for specific tasks or functions.
By Service Type
The Vietnam MSS market offers a diverse range of services tailored to address specific security needs and challenges faced by organizations. These services include managed IAM (identity and access management), managed vulnerability management, managed risk and compliance, managed detection and response, managed firewalls, managed IDS/IPS (intrusion detection and prevention systems), managed SIEM (security information and event management), and others, encompassing managed encryption and additional specialized offerings. This segmentation enables organizations to select customized solutions that address their unique security requirements, whether it's enhancing access control, mitigating vulnerabilities, ensuring regulatory compliance, or detecting and responding to cyber threats effectively.
By Enterprise Size
Enterprises in Vietnam vary significantly in size, from large corporations to small and medium-sized businesses (SMBs), each with distinct security needs and resource constraints. The MSS market segments enterprises based on size, catering to the requirements of both large enterprises and SMBs. Large enterprises typically have complex IT infrastructures and higher security demands, necessitating comprehensive and scalable managed security solutions. SMBs, on the other hand, often have limited IT resources and budgetary constraints, requiring cost-effective yet robust security offerings tailored to their scale and requirements. This segmentation ensures that MSS providers can offer solutions that are scalable, affordable, and tailored to the specific needs of businesses across the spectrum of sizes.
By End User
Different industries in Vietnam face unique cybersecurity challenges and regulatory requirements, driving the need for industry-specific security solutions. The MSS market segments end users based on industry verticals, including banking, financial services, and insurance (BFSI), healthcare, manufacturing, retail, telecom, and IT, and others, such as government entities. Each industry vertical has distinct security priorities, compliance mandates, and threat landscapes, shaping the demand for specialized managed security services.
Segmentations:
By Type
- Fully Managed
- Co-Managed
By Service Type
- Managed IAM
- Managed vulnerability management
- Managed Risk and Compliance
- Managed Detection and Response
- Managed Firewall
- Managed IDS/IPS
- Managed SIEM
- Others (including managed encryption)
By Deployment Mode
- On-premises
- Cloud
By Enterprise Size
- Large Enterprises
- Small and medium-sized enterprises
By End User
- BFSI
- Healthcare
- Manufacturing
- Retail
- Telecom & IT
- Others (including the government)
Market Drivers
Increasing Digitization Across Industries
Vietnam’s rapid digitization across various sectors, including e-commerce, banking, and healthcare, is expanding the attack surface for cybercriminals. For instance, in 2023, there were 77.93 million internet users in Vietnam, with internet penetration standing at 79.1 percent. In the banking sector, 94 percent of banks in Vietnam are investing in digitization. With businesses and individuals increasingly reliant on digital technologies, the need for robust security measures has become paramount. This dependency on digital infrastructure underscores the importance of managed security services (MSS) providers, who offer specialized expertise in safeguarding against cyber threats amidst the expanding digital landscape.
Rising Sophistication of Cyber Threats
Cyberattacks in Vietnam are evolving in sophistication and targeting, posing a significant risk of data breaches, malware intrusions, and ransomware attacks. For instance, in the first half of 2022, there were over 6.6 thousand cyberattacks recorded in Vietnam. Organizations are recognizing the limitations of their in-house security capabilities and turning to MSS providers for advanced threat detection and response solutions. MSS providers offer proactive monitoring, rapid incident response, and threat intelligence capabilities, equipping organizations with the necessary defenses to combat emerging cyber threats effectively.
Stringent regulatory compliance
The Vietnamese government's implementation of stricter data privacy regulations, such as the Personal Data Protection Law (PDPL), underscores the imperative for organizations to enhance their security posture. Compliance with these regulations necessitates the implementation of robust security measures to safeguard sensitive data. MSS services play a critical role in ensuring compliance by providing comprehensive security solutions tailored to meet regulatory requirements, thus mitigating the risk of non-compliance penalties and reputational damage.
Adoption of cloud-based solutions
The burgeoning adoption of cloud technologies in Vietnam presents both opportunities and security challenges for organizations. As businesses migrate their operations to cloud environments to enhance agility and scalability, they require specialized security solutions to protect their data and applications. MSS providers offer expertise in securing cloud infrastructure and applications, leveraging advanced security controls and monitoring mechanisms to safeguard against cloud-specific threats. By partnering with MSS providers, organizations can effectively navigate the complexities of cloud security and ensure the integrity and confidentiality of their digital assets.
Growing awareness about cybersecurity risks
There is a growing awareness among businesses and individuals in Vietnam about the escalating cyber threats and the potential consequences of security breaches. This heightened awareness has led to a greater prioritization of cybersecurity measures, with organizations actively seeking out MSS providers to bolster their security defenses. MSS providers play a pivotal role in educating businesses about emerging threats, implementing proactive security measures, and fostering a culture of cybersecurity awareness and resilience.
Shortage of In-House Security Expertise
Many organizations in Vietnam face challenges in building and maintaining a comprehensive cybersecurity posture due to a shortage of in-house security expertise and resources. MSS providers offer a cost-effective solution by providing access to a pool of skilled security professionals who can manage and monitor security systems 24/7. By outsourcing security operations to MSS providers, organizations can benefit from round-the-clock protection, expert guidance, and proactive threat mitigation strategies, thus strengthening their security posture and mitigating the risk of cyber incidents.
Market Trends
Focus on cloud security solutions
As cloud adoption accelerates in Vietnam, there’s a burgeoning demand for cloud-based managed security services (MSS). These services are specifically designed to secure cloud environments, offering features such as workload protection, data encryption, and cloud access security brokering (CASB) solutions. Workload protection solutions provide real-time visibility into the attack surface, enabling security teams to assess and mitigate risks effectively, particularly concerning application exposure. Data encryption solutions are software systems that employ data encryption algorithms to protect sensitive data, combined with management tools for deploying and monitoring data encryption across an organization. Organizations migrating their operations to the cloud seek MSS providers who can ensure the security and integrity of their data and applications in the cloud, addressing concerns around data privacy, compliance, and cloud-specific cyber threats.
Specialization in Security Services
The market is witnessing a rise in specialized MSS offerings tailored to meet the unique security needs of different industries. Financial institutions, healthcare providers, and government agencies, among others, require specialized security solutions to address their specific compliance requirements and cyber threats. MSS providers are catering to these industry-specific needs by offering tailored security solutions, such as healthcare compliance solutions, financial fraud detection services, and government-grade security frameworks, thereby enhancing their value proposition and relevance to diverse industry verticals. Healthcare compliance solutions streamline compliance processes and create a structured framework for adhering to guidelines imposed by regulatory bodies, such as the Health Insurance Portability and Accountability Act (HIPAA). Financial fraud detection services are used to detect illegitimate and high-risk online activities. These tools continuously monitor user behavior and calculate risk figures to identify potentially fraudulent purchases, transactions, or access. Government-grade security frameworks are developed to ensure that government agencies and departments adhere to set compliance guidelines and revise compliance practices based on changing regulations.
Integration with Security Automation and AI
To combat increasingly sophisticated cyber threats, MSS providers are incorporating artificial intelligence (AI) and automation tools into their service offerings. By leveraging AI-driven threat intelligence, machine learning algorithms, and automation capabilities, MSS providers can enhance their ability to detect and respond to cyber threats in real-time. This integration with security automation and AI not only improves threat detection and incident response times but also enables MSS providers to deliver more proactive and predictive security measures, thereby strengthening overall cybersecurity defenses.
Rise of Hybrid and Co-Managed Security Services
A hybrid approach combining in-house security teams with MSS provider expertise is gaining traction in Vietnam. Organizations are adopting co-managed security services, where security responsibilities are shared between the client and the provider. This collaborative model allows organizations to leverage the expertise and resources of MSS providers while retaining control over certain security functions. Additionally, hybrid security models enable organizations to customize their security posture according to their unique requirements, risk profiles, and budget constraints, thereby optimizing security investments and outcomes.
Growing Demand for Managed Detection and Response (MDR) Services
Organizations in Vietnam are increasingly recognizing the need for proactive security measures to combat evolving cyber threats. Managed Detection and Response (MDR) services are gaining popularity for their capabilities in continuous threat monitoring, threat hunting, and rapid incident response. MSS providers offering MDR services equip organizations with the necessary tools, technologies, and expertise to detect and respond to cyber threats in real-time, minimizing the impact of security incidents and reducing dwell time. This growing demand for MDR services reflects a shift towards more proactive and intelligence-driven cybersecurity approaches in Vietnam.
Market Restraints and Challenges
Limited cybersecurity awareness
While awareness of cybersecurity is increasing in Vietnam, particularly among larger enterprises, some businesses, particularly smaller ones, may still lack a comprehensive understanding of the evolving cyber threat landscape and the benefits of managed security services (MSS). This limited understanding can lead to a reluctance to invest in these services, leaving organizations vulnerable to cyber threats and potential data breaches.
Skilled Cybersecurity Workforce Gap
Vietnam faces a shortage of cybersecurity professionals, which poses a significant challenge for MSS providers. The scarcity of skilled cybersecurity professionals can restrict the ability of MSS providers to scale their services and meet the growing demands of clients. This talent gap may result in higher service costs or limitations on service availability, impeding market growth and hindering organizations' ability to effectively manage cyber risks.
Data Privacy Concerns and Regulations
Outsourcing critical security functions and sensitive data to external MSS providers can raise concerns for organizations regarding data privacy and regulatory compliance. Uncertainty surrounding data privacy regulations and the potential for security breaches within the MSS provider's infrastructure can deter organizations from adopting MSS. Addressing these concerns and ensuring compliance with evolving data privacy regulations are crucial for fostering trust and driving market growth in Vietnam's MSS sector.
Cost Considerations
Implementing and maintaining MSS can be expensive for organizations, particularly for small and medium-sized enterprises (SMEs) with limited resources. The ongoing costs associated with MSS subscriptions, potential infrastructure upgrades, and data transfer fees can pose a barrier to wider adoption. Organizations may hesitate to invest in MSS due to concerns about cost-effectiveness and return on investment (ROI), impacting the growth potential of the MSS market in Vietnam.
Key Players
- NTT DATA, Inc.
- AT&T Inc.
- Wipro Limited
- Symantec Corporation
- Trustwave Holdings, Inc.
- DXC Technology
- Accenture plc
- Cisco Systems, Inc.
- Fortinet, Inc.
- Dell Technologies, Inc.
- HCL Technologies
- Tata Consultancy Services
- Fujitsu
Recent Developments
In August 2023, Schneider Electric, a digital automation and energy management company based in France, launched Managed Security Services (MSS) to meet the demands of customers in operational technology (OT) environments.
Regional Analysis
Northern
The northern region of Vietnam, which includes the capital city of Hanoi, holds the largest market share in the Vietnamese MSS market, accounting for 40% in 2023. This dominance can be attributed to the concentration of government agencies, financial institutions, and large enterprises in the region, as well as the presence of a robust IT infrastructure. The region's growing demand for advanced cybersecurity solutions and the availability of skilled IT professionals have been the primary drivers of the MSS market's expansion.
Southern
The southern region of Vietnam, which includes the commercial hub of Ho Chi Minh City, will hold the second-largest market share at 35% in 2023. The region's thriving manufacturing and services sectors, as well as the rapid growth of the digital economy, have fueled the demand for comprehensive managed security services. Additionally, the region's status as a technology and innovation hub has attracted leading MSS providers, further strengthening the market's presence.
Central
The central region of Vietnam, comprising provinces such as Danang and Hue, will account for 15% of the MSS market share in 2023. While the region's market size is relatively smaller compared to the northern and southern regions, it has witnessed steady growth in recent years. The region's increasing industrialization, the development of infrastructure projects, and the growing adoption of cloud-based technologies have created opportunities for MSS providers to expand their services.
Future Outlook
- Continued Growth: The Vietnam Managed Security Services Market is expected to witness sustained growth driven by increasing digitization and cybersecurity awareness.
- Rising Demand for Cloud Security: With the growing adoption of cloud technologies, there will be an increased demand for cloud-based security solutions.
- Specialization in Industry Verticals: MSS providers will focus on offering specialized security services tailored to meet the unique needs of different industry verticals.
- Integration of AI and Automation: Artificial intelligence and automation tools will play a crucial role in enhancing threat detection and response capabilities.
- Emphasis on Compliance: Compliance-as-a- Service solutions will gain prominence as organizations strive to meet evolving regulatory requirements.
- Addressing Talent Shortage: MSS providers will seek innovative strategies to address the shortage of cybersecurity professionals and scale their services effectively.
- Hybrid Security Models: Hybrid and co-managed security services will become more prevalent, allowing organizations to blend in-house expertise with external MSS support.
- Focus on Threat Intelligence: MSS providers will invest in developing robust threat intelligence capabilities to stay ahead of evolving cyber threats.
- Enhanced Incident Response: Managed Detection and Response (MDR) services will see increased adoption for proactive threat monitoring and rapid incident response.
- Localization of Services: MSS providers will tailor their offerings to address region-specific cybersecurity challenges and regulatory landscapes in Vietnam.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Vietnam Managed Security Services Market between 2023 and 2032?
What factors are driving the growth of the Vietnam managed security services market?
Who are the major players in the Vietnamese managed security services market?
How is the availability of the Vietnam Managed Security Services Market expanding, and through what channels?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Vietnam Managed Security Services (MSS) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Vietnam Managed Security Services (MSS) Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 90,169.13 million → forecast year: USD 164,354.79 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Vietnam Managed Security Services (MSS) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Vietnam Managed Security Services (MSS) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Vietnam Managed Security Services (MSS) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Vietnam Managed Security Services (MSS) Market Drivers
- 3.3 Vietnam Managed Security Services (MSS) Market Restraints & Challenges
- 3.4 Vietnam Managed Security Services (MSS) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Vietnam Managed Security Services (MSS) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Vietnam Managed Security Services (MSS) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Vietnam Managed Security Services (MSS) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Vietnam Managed Security Services (MSS) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Vietnam Managed Security Services (MSS) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Vietnam Managed Security Services (MSS) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Vietnam Managed Security Services (MSS) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Vietnam Managed Security Services (MSS) Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Vietnam Managed Security Services (MSS) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Vietnam Managed Security Services (MSS) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Vietnam Managed Security Services (MSS) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Vietnam Managed Security Services (MSS) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Vietnam Managed Security Services (MSS) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Vietnam Managed Security Services (MSS) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Vietnam Managed Security Services (MSS) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Vietnam Managed Security Services (MSS) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Vietnam Managed Security Services (MSS) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Vietnam Managed Security Services (MSS) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Vietnam Managed Security Services (MSS) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
