
iPhone support brings RCS business messages to most phones
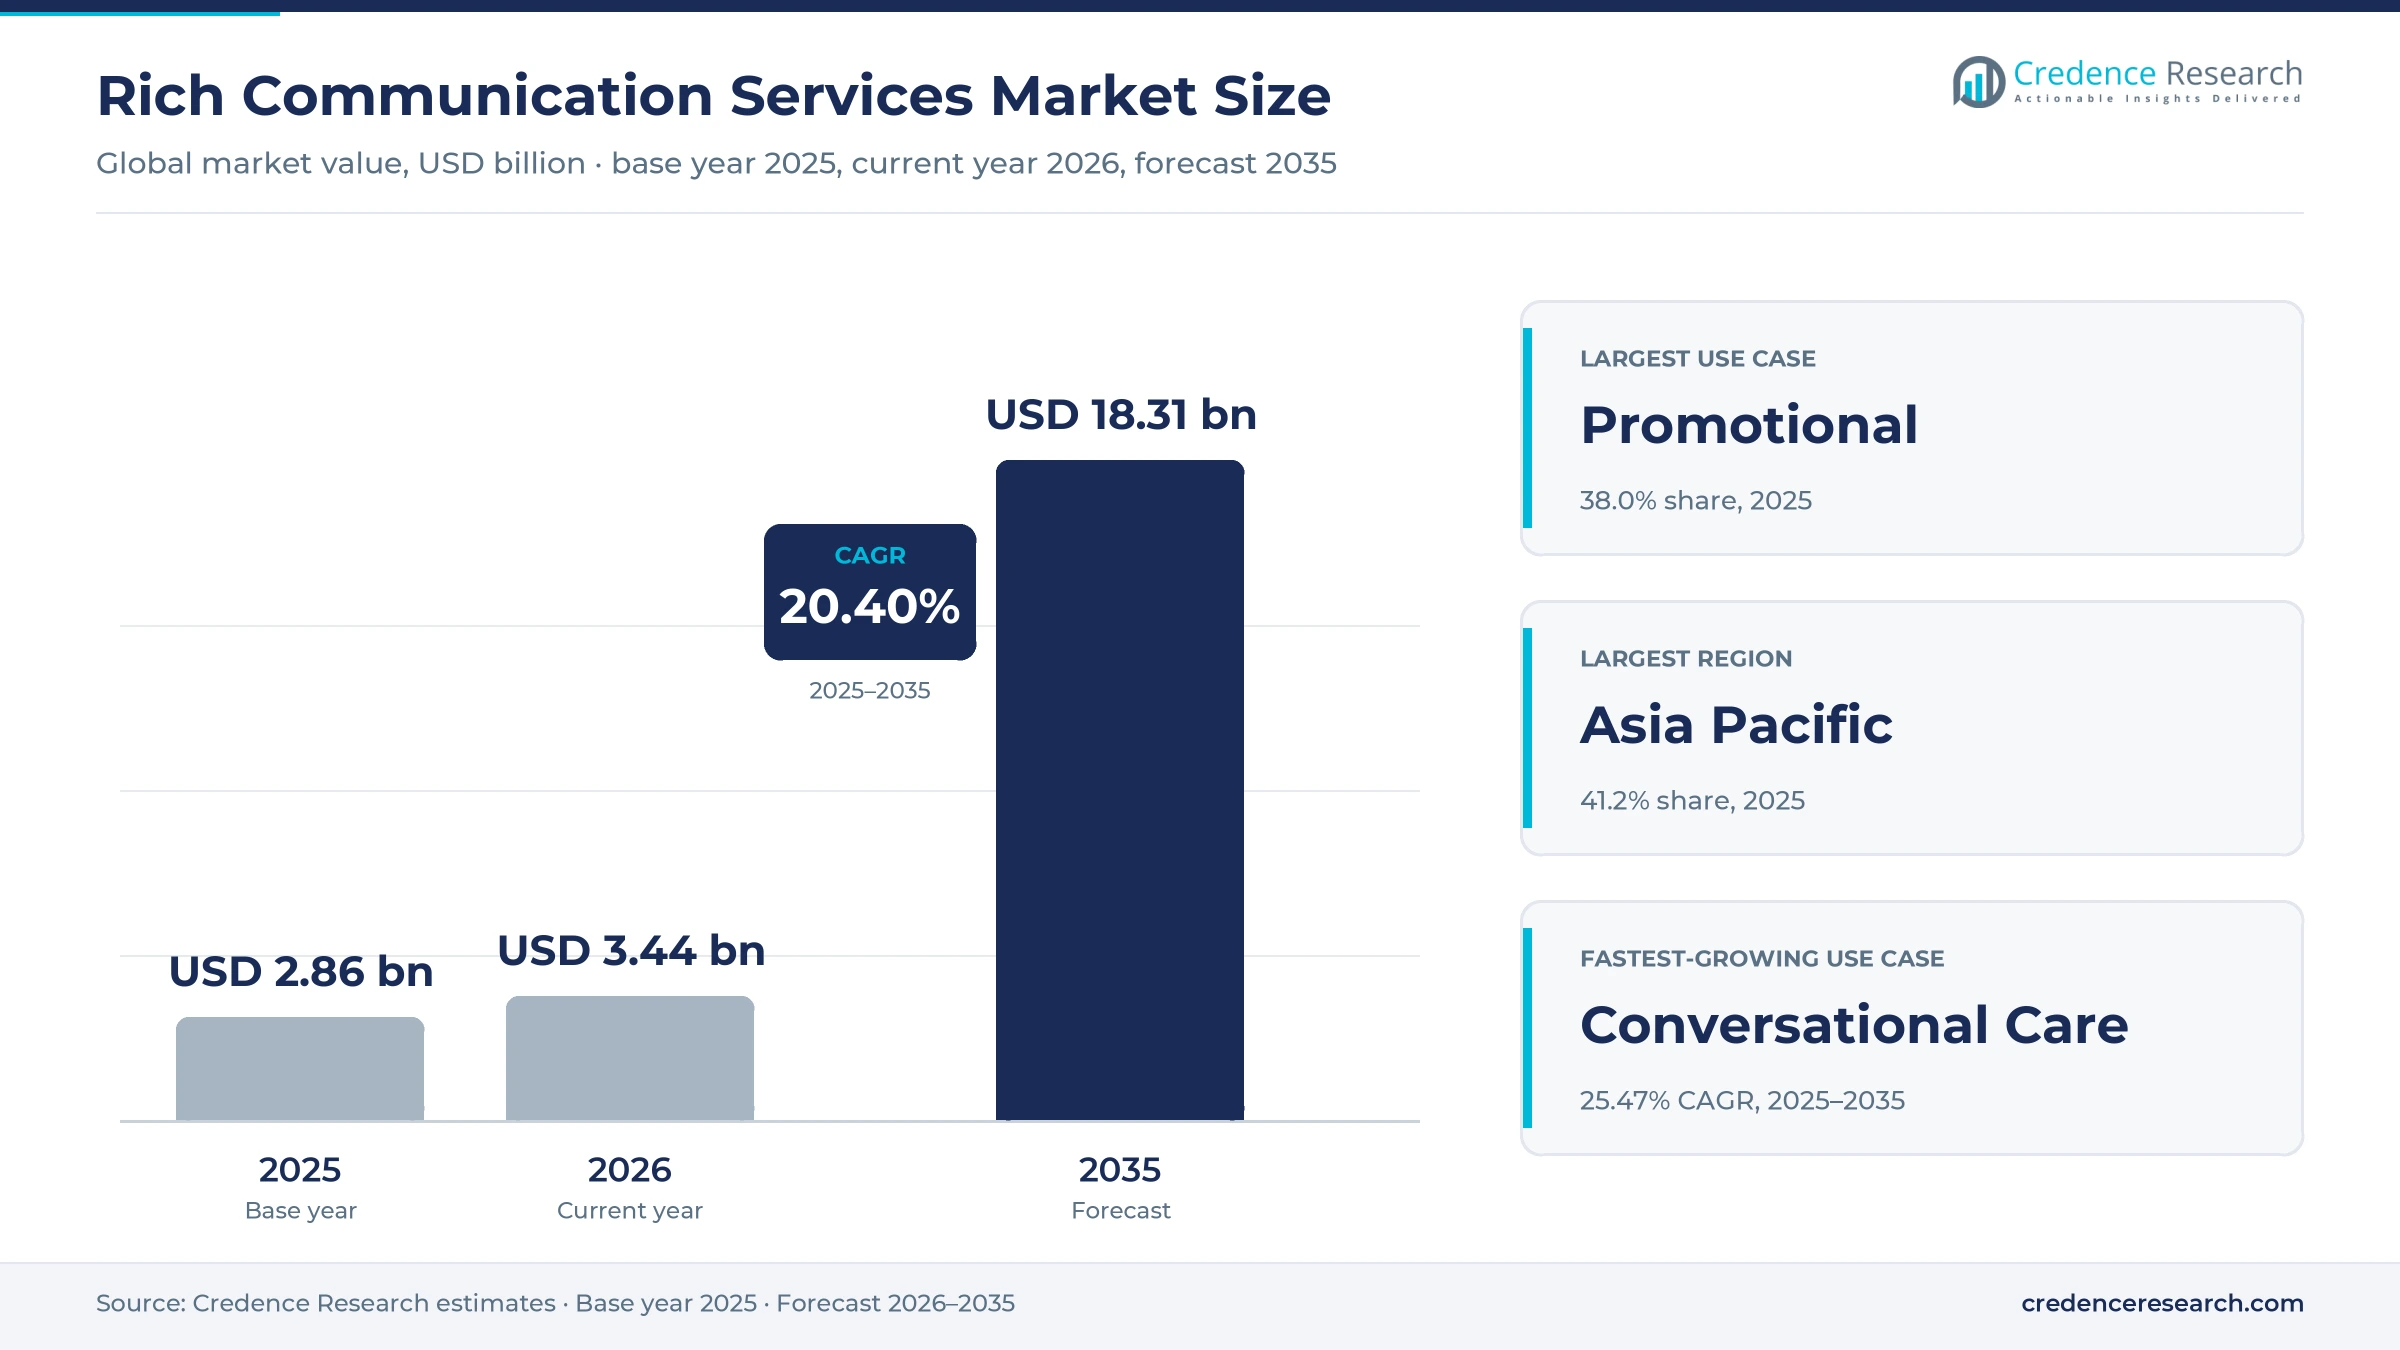
The rich communication services market was valued at USD 2.86 billion in 2025 and is projected to increase from USD 3.44 billion in 2026 to USD 18.31 billion by 2035, registering a CAGR of 20.40% during 2025–2035. Three forces carry demand, as brands upgrade SMS campaigns, alerts and one-time passwords to verified, branded messages, banks and retailers look for a channel that resists spoofing, and operators want more revenue per message as plain SMS stalls. Asia Pacific held the largest regional share, 41.2% in 2025, on the very high message volumes sent in India, while North America is the fastest-growing region at 23.33% a year. The decisive commercial change came in September 2024, when Apple added RCS to the iPhone with iOS 18, so one business channel now reaches nearly every smartphone. The GSMA's Universal Profile 3.0, published in March 2025, then added end-to-end encryption, which matters most to banks, insurers and health providers.
How do brands pay for RCS business messaging?
RCS business messaging, often called RBM, is bought much like business SMS. A brand pays a messaging provider or an operator per message, or per conversation session for two-way traffic, and the provider pays the operator a wholesale rate. Each sender must first pass brand verification, and messages can carry rich cards, carousels, buttons and read receipts.
The market counts promotional, transactional, authentication and customer care traffic plus the platform fees tied to it. It excludes person-to-person RCS chat, which users do not pay for separately, plain business SMS, over-the-top apps such as WhatsApp, and handset or network equipment. Those exclusions matter because business SMS remains far larger by volume, and each message moved to RCS earns operators and platforms more.
Rich Communication Services Market Insights
- The rich communication services market is projected to rise from USD 3.44 billion in 2026 to USD 18.31 billion by 2035, a 20.40% CAGR, as brands move SMS traffic to RCS.
- Asia Pacific held 41.2% of 2025 value, the largest regional share, because India, the largest single RCS business messaging market, sends very high message volumes.
- Promotional and marketing messages accounted for 38.0% of 2025 value, the largest use case, as retailers, operators and banks sell through rich cards and carousels.
- Apple's September 2024 iOS 18 update brought RCS to the iPhone, turning an Android-only service into one business channel for nearly every smartphone.
- Conversational customer care grows fastest through 2035 at 25.47% a year, so messaging providers invest in AI agents and session pricing rather than cutting per-message prices.
Promotions lead as conversational care and healthcare surge
Promotional messages lead by use case while conversational care grows fastest
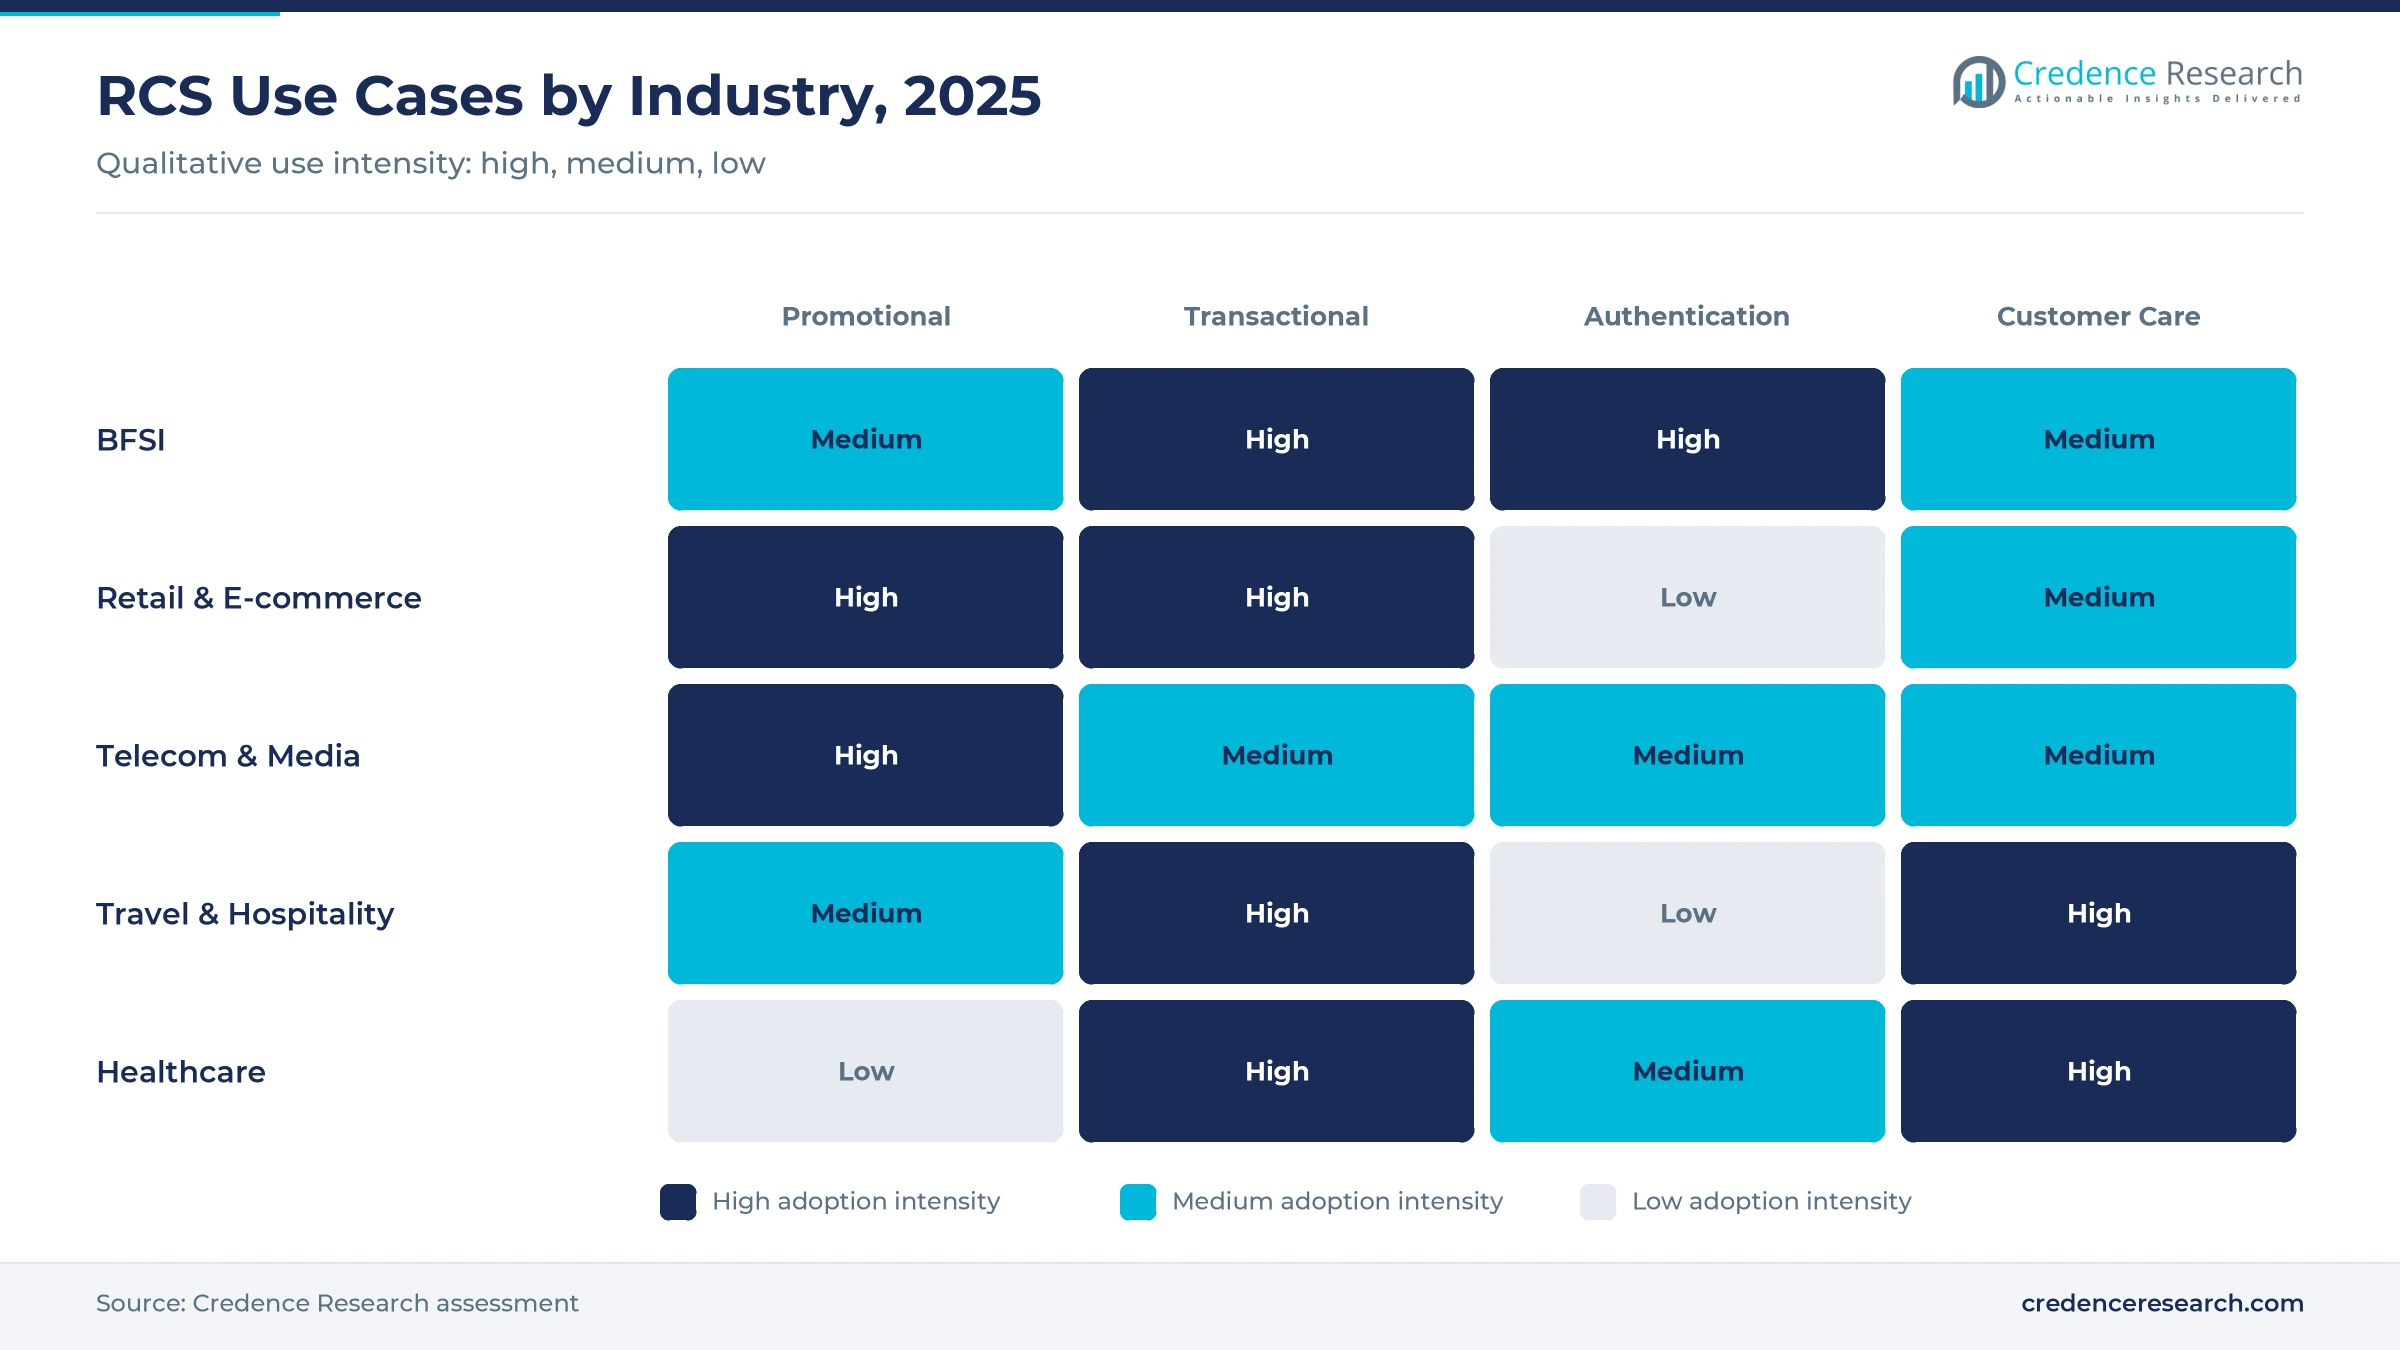
Based on use case, the market is categorized into promotional and marketing, transactional and alerts, authentication and OTP, and conversational customer care. Promotional and marketing messages led with 38.0% of 2025 value, because retailers, telecom operators and banks were the first to test rich cards, carousels and suggested replies, and higher response rates justify a higher price per message. Conversational customer care grows fastest at 25.47% a year as session pricing and AI agents make two-way service cheaper to run at scale.
Banks spend the most by industry while healthcare adds traffic fastest
Based on end-use industry, the market is categorized into BFSI, retail and e-commerce, telecom and media, travel and hospitality, healthcare and others. BFSI led with 27.4% of 2025 value, because banks, insurers and payment apps send large volumes of account alerts and login codes and value verified senders that cut phishing. Healthcare grows fastest at 23.08% a year as appointment reminders, prescription alerts and secure follow-ups move to an encrypted, verified channel.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2025–2035 |
|---|---|---|---|---|
| By Use Case | Promotional & Marketing | 38.0% | Conversational Customer Care | 25.47% |
| By End-Use Industry | BFSI | 27.4% | Healthcare | 23.08% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
iPhone reach, encryption and verified senders lift RCS
iPhone support turned RCS into a channel for nearly every smartphone
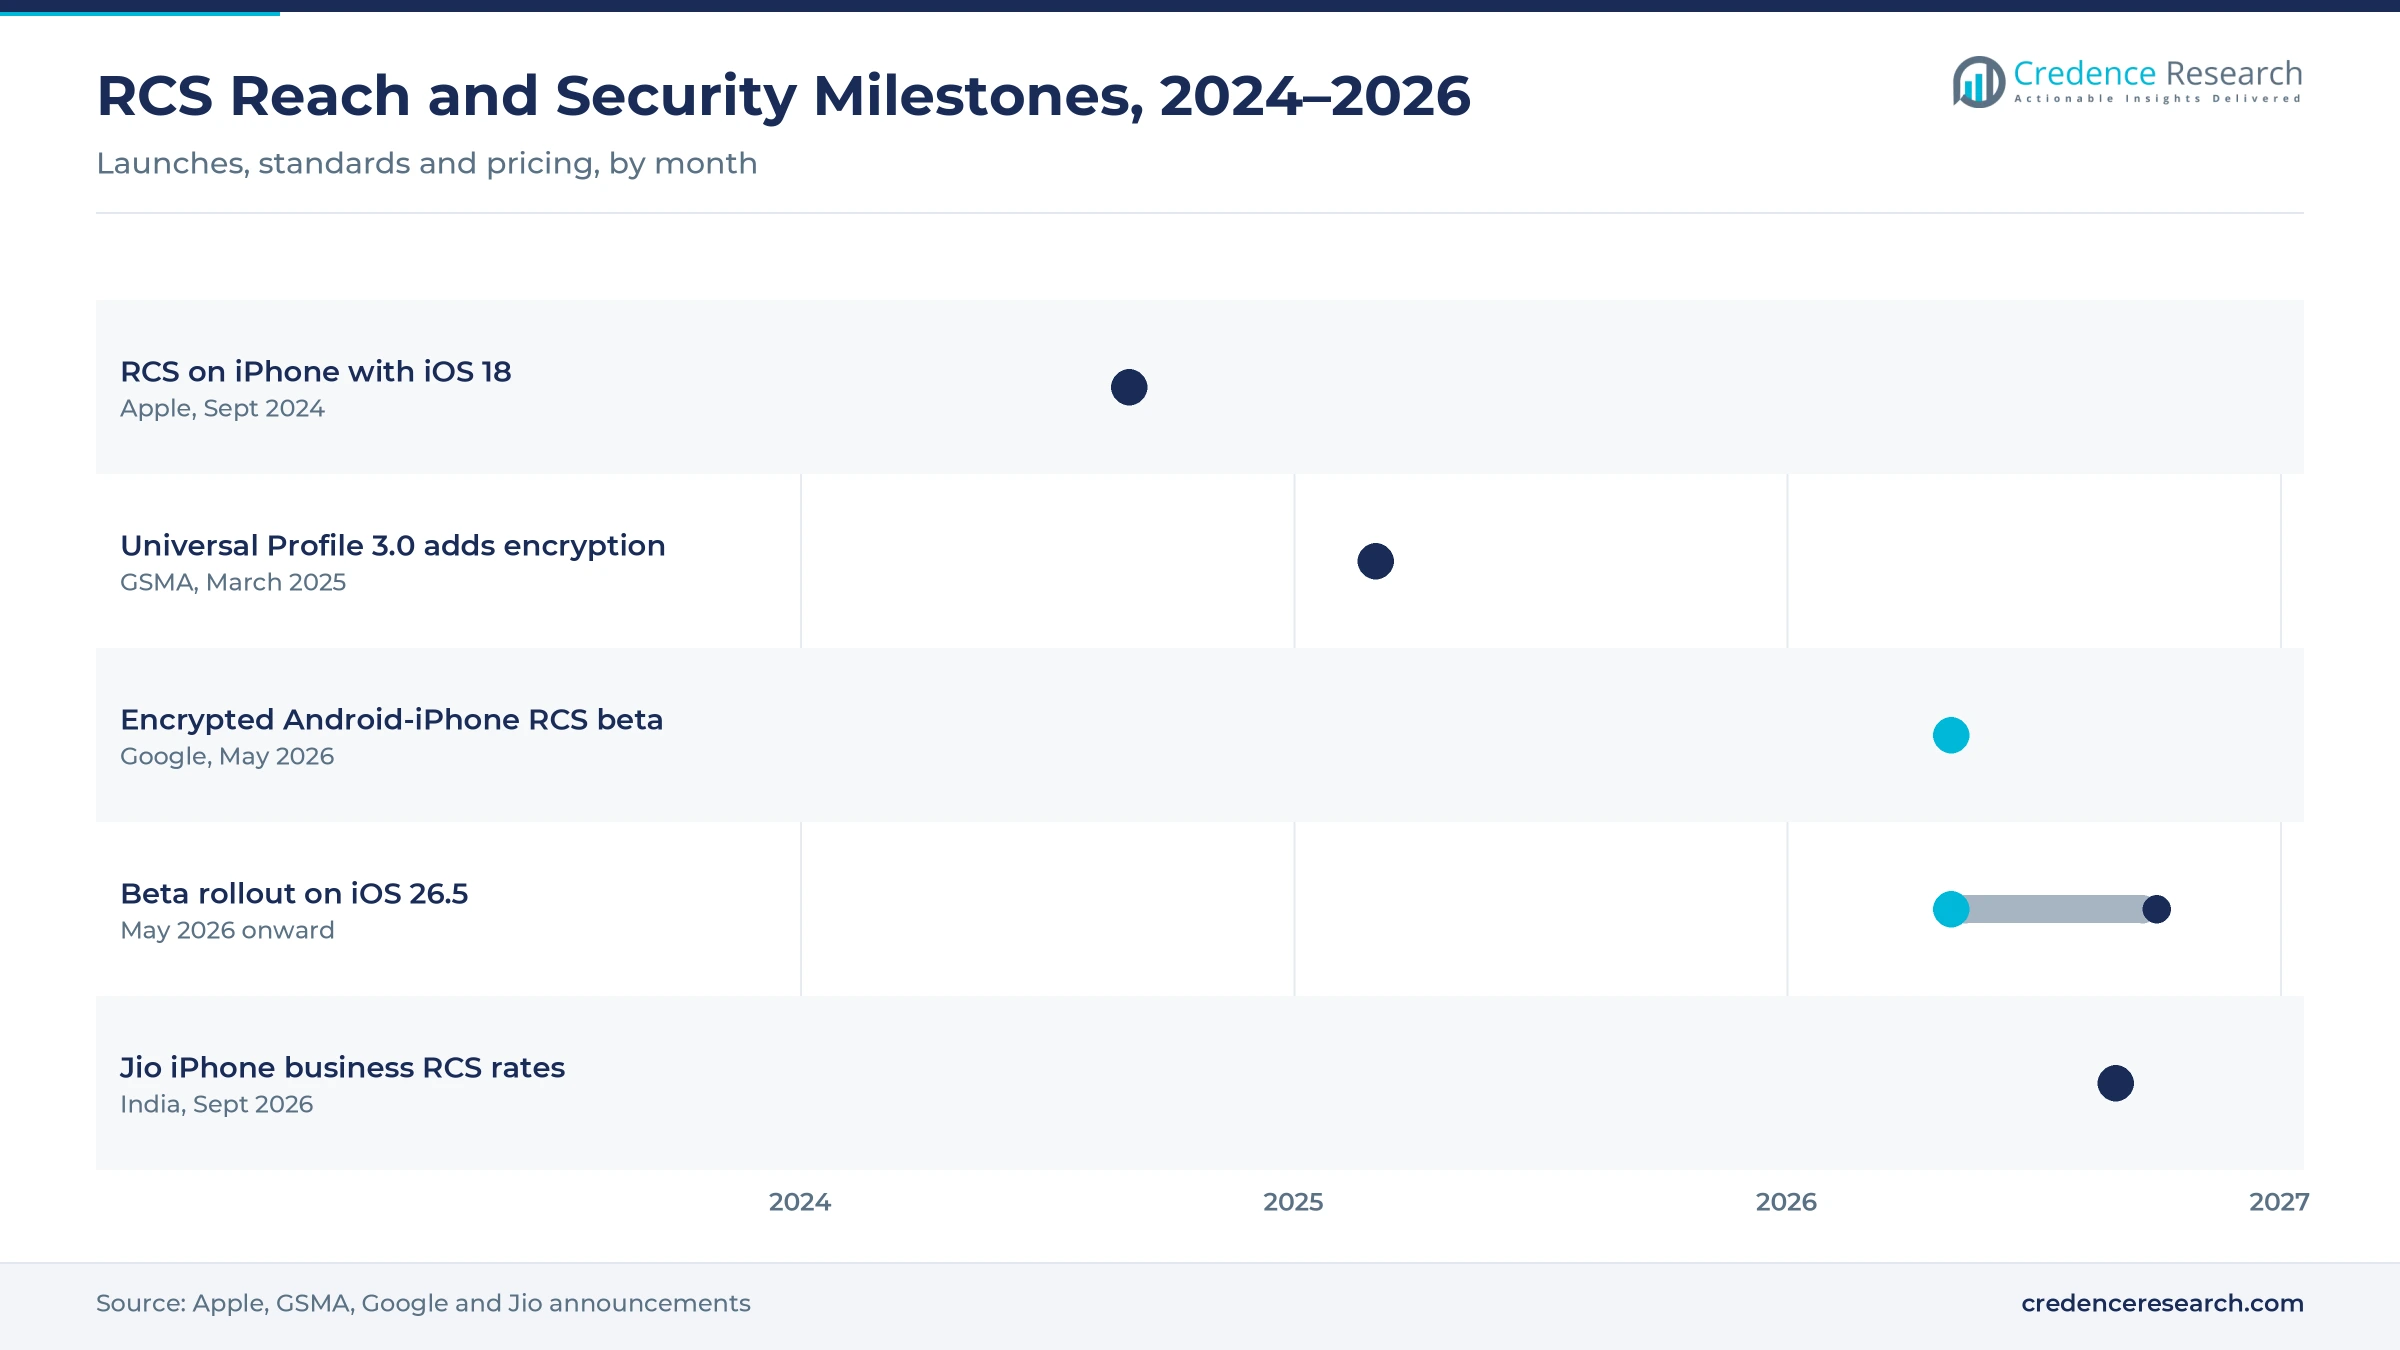
Until 2024, RCS reached only Android phones, so brands still sent SMS to iPhone users and ran 2 parallel campaigns. Apple added RCS to the iPhone with iOS 18 in September 2024, and business RCS on iPhones is rolling out through operators in the U.S., the U.K., Germany, France and Spain. A single channel that reaches nearly every handset raises demand from retailers and banks through the late 2020s, and it is the main reason North America grows fastest.
End-to-end encryption opens the channel to regulated industries
Banks, insurers and health providers hesitate to send account details by SMS. In March 2025, the GSMA published Universal Profile 3.0, adding end-to-end encryption to RCS based on the Messaging Layer Security protocol, and in May 2026 Google said end-to-end encrypted RCS was rolling out in beta between Android and iPhone users on iOS 26.5. Encrypted, cross-platform delivery removes a compliance barrier over the medium term and helps BFSI hold 27.4% of 2025 value, the largest industry share.
Verified senders give banks and operators a tool against text fraud
SMS sender IDs are easy to fake, and phishing by text hits bank customers hardest. RCS senders must pass brand verification before they can message users, and every message shows the company's name, logo and a verified badge. Operators and regulators that want to curb SMS fraud now treat RCS as part of the answer, often paired with an SMS firewall that blocks grey-route traffic. Login codes and account alerts are the near-term beneficiaries as banks and payment apps switch channels over 2 to three years.
Priced operator offers turn RCS from pilot into budget line
Operators earn little from person-to-person chat, but business messaging is a paid wholesale service. In India, Jio introduced new RCS business messaging rates for messages to iPhone users from September 2026, replacing an earlier flat tariff. Clear wholesale pricing lets enterprises budget for RCS instead of running pilots, and it gives operators a reason to promote rich messages over SMS. The effect is immediate in Asia Pacific, the largest region, growing 19.13% a year, and it spreads as other operators publish rates.
Two-way service, session pricing and in-message payments
Messaging shifts from one-way broadcasts to two-way conversations
Brands are moving from sending offers to holding conversations, as customers ask questions, book appointments and pay without leaving the native messaging app, often through a bot that hands off to a human agent. Conversational customer care is the fastest-growing use case at 25.47% a year, against 20.40% for the whole market. The shift favors providers with dialog design and conversational AI tools, and it moves value from campaign volume toward resolved service requests.
Session pricing and automatic SMS fallback cut the cost of trying RCS
Operators and platforms are moving from a price per message to a price per conversation session for two-way traffic, which suits customer care, where a single exchange can involve many messages. Platforms also send RCS first and fall back to SMS when a handset or network cannot receive it, so brands no longer run two campaigns, and as reach grows the fallback share shrinks, raising average revenue per message.
Healthcare and travel messages moving to a verified channel open an opportunity
Healthcare is the fastest-growing industry at 23.08% a year, because appointment reminders, prescription alerts and secure follow-ups suit an encrypted, verified channel where providers can show their own logo instead of an unknown short code. Travel and hospitality brands send boarding passes, gate changes and rebooking options in rich cards. Providers that meet health-data rules and integrate with booking and patient systems can win this demand over the next five years.
Payments and AI agents inside the message offer an opportunity
Payment buttons inside RCS messages let customers pay bills, top up accounts and complete orders in 1 step. In India and Brazil, where instant payment systems are common, RCS payment links are an early opening. AI agents that answer questions and complete tasks inside RCS conversations turn the channel from broadcast into service. Platforms that combine RCS with CPaaS APIs and AI tools can capture more of each conversation's value, provided spam controls keep users engaged.
Patchy operator support, SMS price gaps and spam slow RCS
Uneven operator support keeps SMS in charge across much of Africa
RCS needs both the handset and the operator to support it. Some operators in Africa, the Middle East and parts of Latin America still do not offer business RCS, and older phones cannot receive it. Brands that need guaranteed delivery keep SMS as their main channel there, which holds Middle East & Africa growth to 18.53% a year, the slowest of the five regions. Automatic SMS fallback and GSMA interconnection work let brands start RCS now and widen reach as operators launch.
Price gaps with SMS and chat apps limit use in cost-sensitive markets
RCS messages cost more than SMS in most markets, and WhatsApp Business competes hard on price and features in India, Brazil and Indonesia. Brands with tight budgets test RCS only for high-value campaigns, which slows volume growth among small and mid-sized senders. Session pricing, volume tiers and proof of higher conversion are the main tools operators and providers use to close the price gap.
Spam risk forces strict onboarding that slows new senders
Rich, branded messages are attractive to marketers, and too many of them push users to block senders or switch off RCS altogether. Operators and Google run brand verification and rate limits, and Indian operators also apply their own spam filters. These controls protect the channel's value for banks and retailers, but they slow onboarding for new brands. Providers mitigate the delay with pre-verified templates and consent tools that keep campaigns within operator rules.
Fragmented hubs and country rules raise setup costs
Brands must work with several hubs, aggregators and operator agreements to reach every user, and approval processes and prices differ by country. That raises setup costs, especially for mid-sized companies sending across 5 or more markets, and it delays multi-country launches. Large providers absorb part of this cost by bundling operator connections into 1 API, so brands concentrate traffic with a few of them, while common GSMA specifications should ease the burden over time.
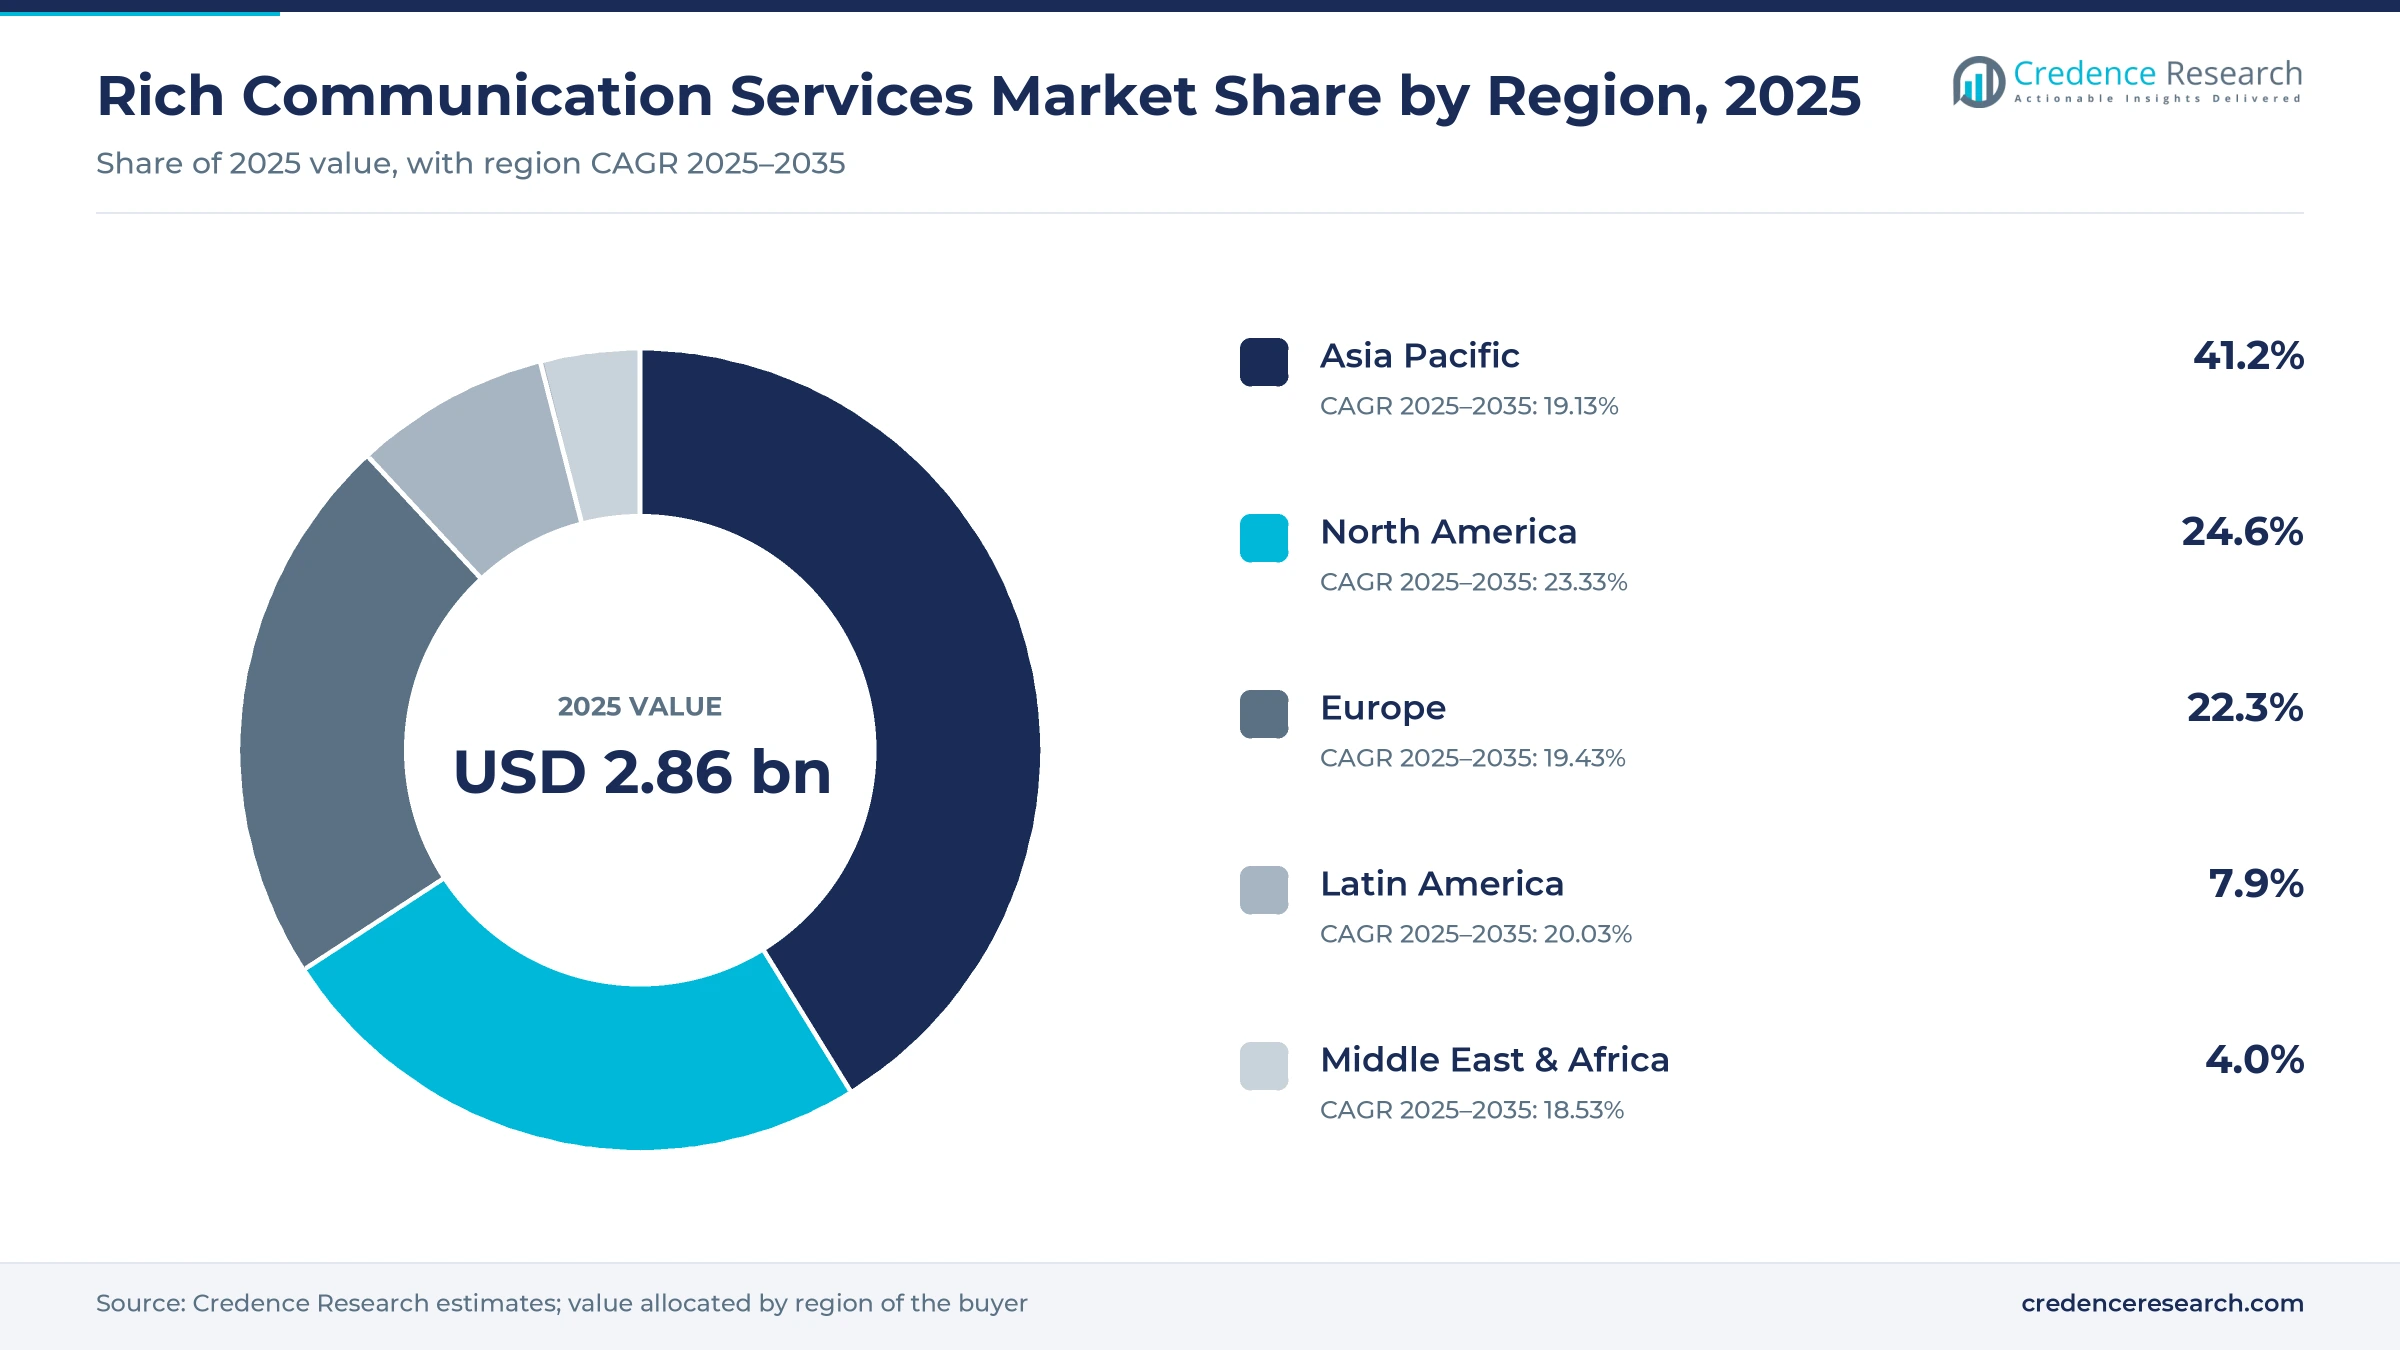
Asia Pacific volume leads as North America grows fastest
| Region | Share, 2025 | CAGR, 2025–2035 |
|---|---|---|
| Asia Pacific | 41.2% | 19.13% |
| North America | 24.6% | 23.33% |
| Europe | 22.3% | 19.43% |
| Latin America | 7.9% | 20.03% |
| Middle East & Africa | 4.0% | 18.53% |
Asia Pacific leads as India and China send the largest volumes
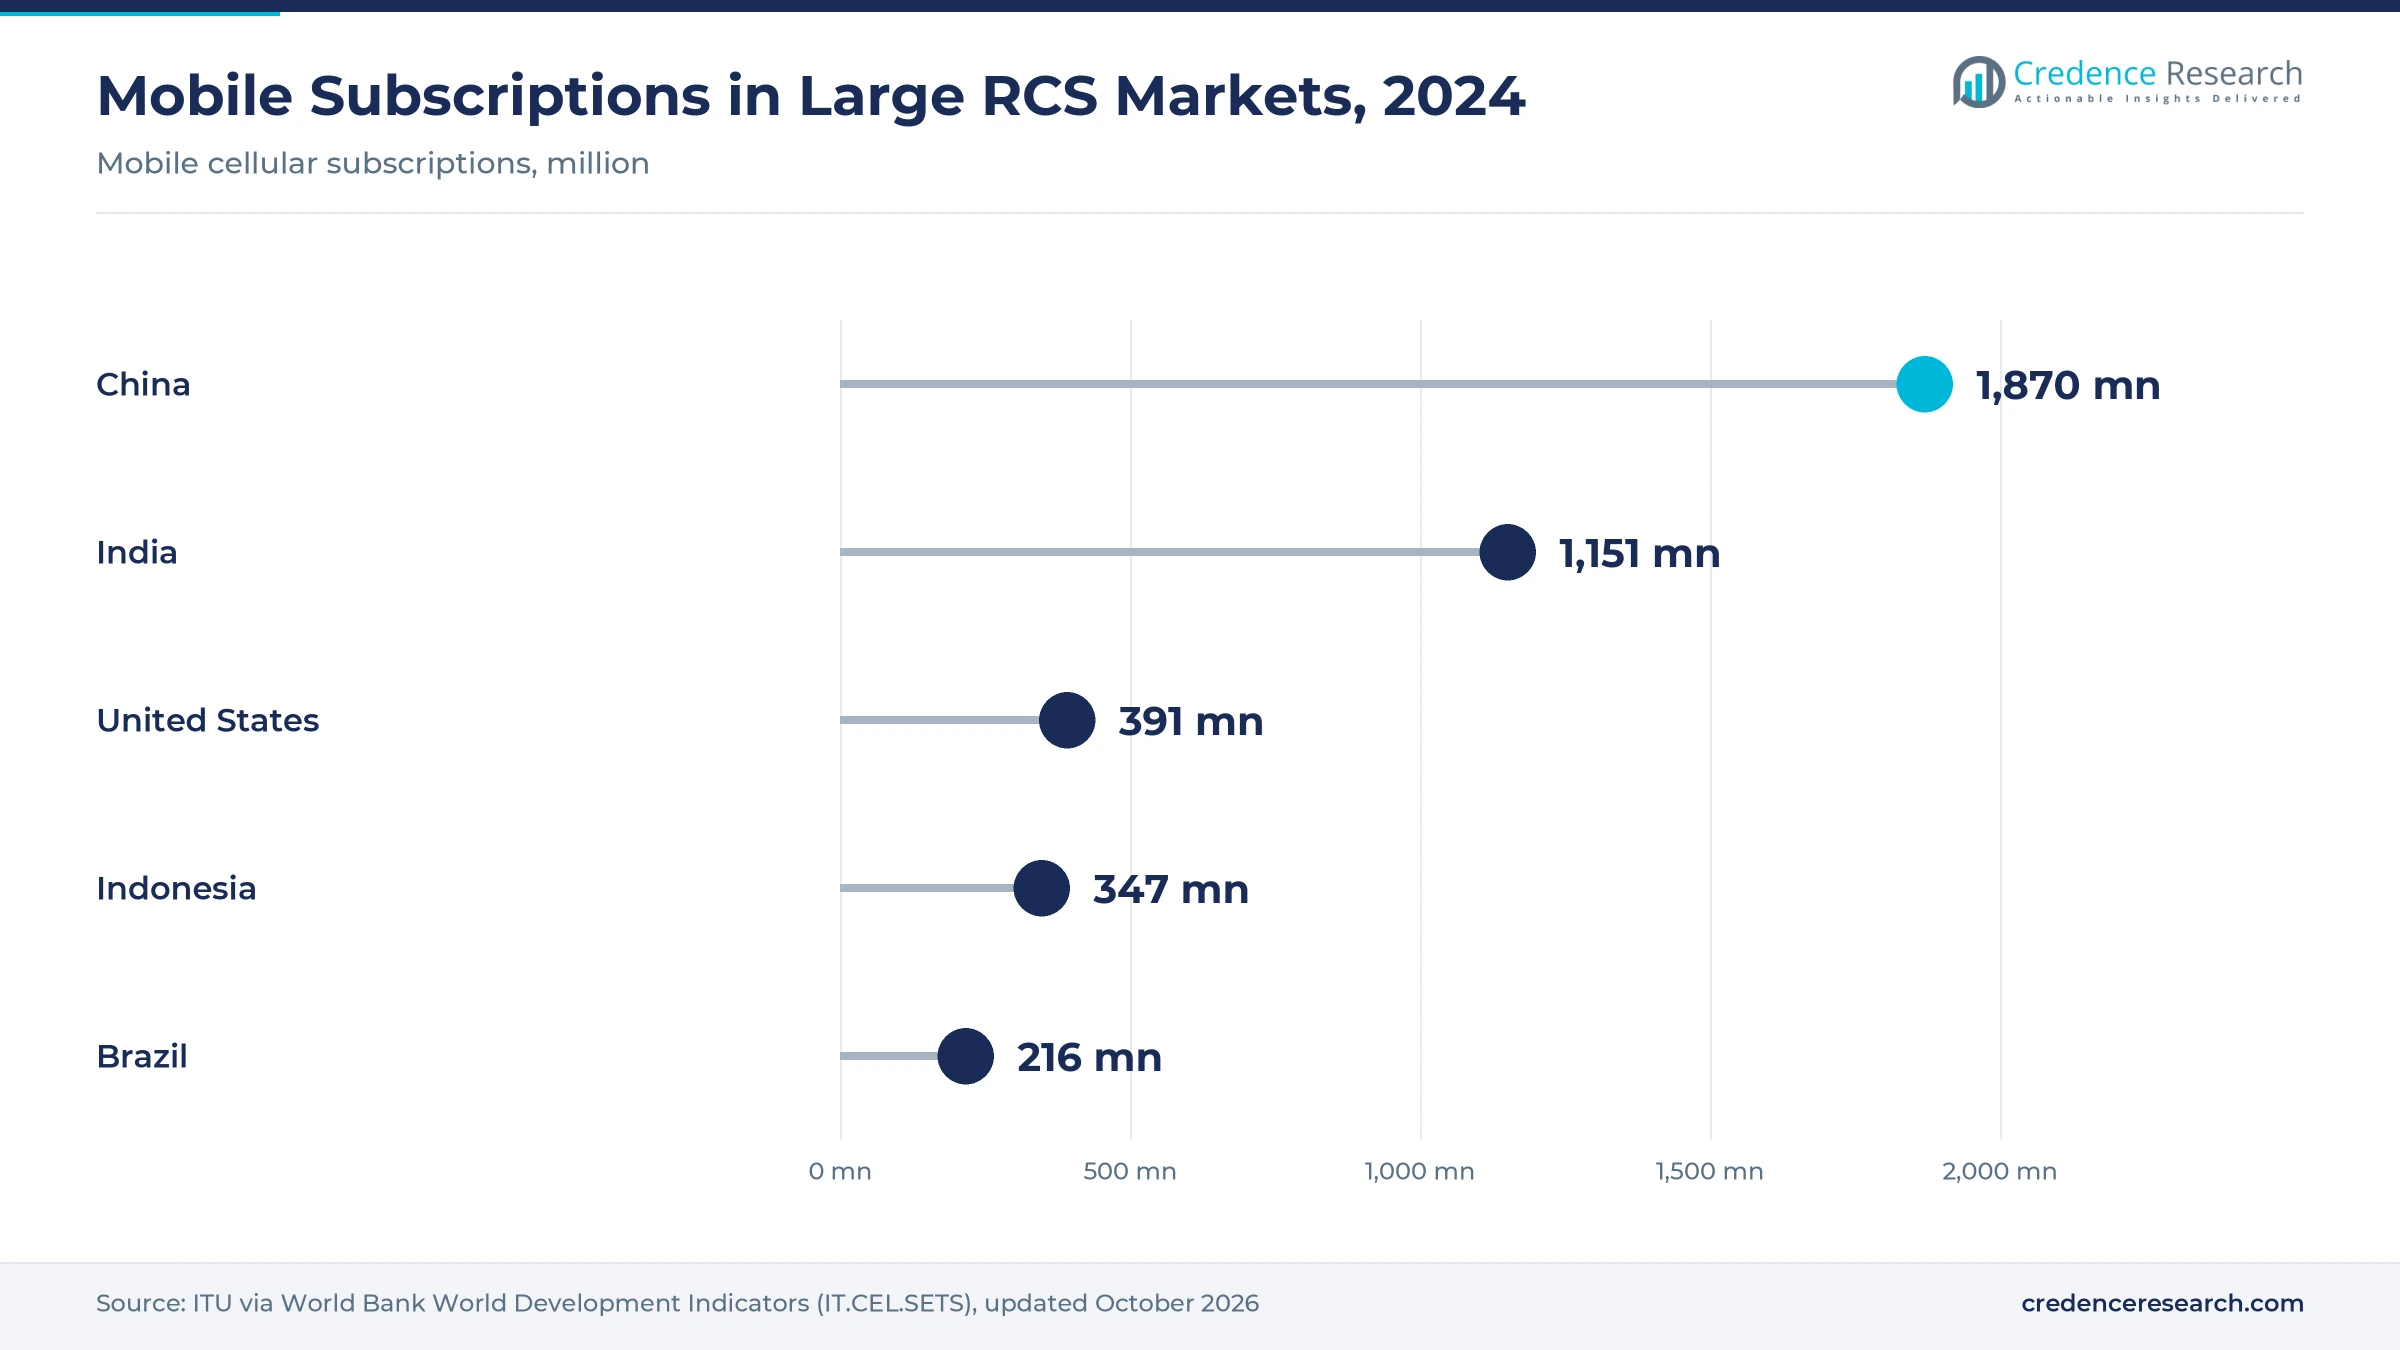
Asia Pacific held 41.2% of 2025 value and grows at 19.13% a year. India is the largest single RCS business messaging market, with Jio, Airtel and Vi all active and banks and fintechs sending most of the traffic; the country had about 1,151 million mobile subscriptions in 2024, according to World Bank data. China runs its own operator-led 5G messaging service through China Mobile and its peers. Japan, Indonesia and the Philippines are scaling RCS for marketing and alerts, while price competition from chat apps keeps rates lower than in the West.
North America grows fastest on iPhone support
North America held 24.6% of 2025 value and is the fastest-growing region at 23.33% a year. The United States had low RCS reach while most of its smartphones were iPhones, but now AT&T, Verizon and T-Mobile U.S. customers can receive business RCS on both platforms, and the U.S. had about 391 million mobile subscriptions in 2024. Retailers and banks lead the switch from SMS, and Canada follows the same path as its operators enable business RCS.
Europe's data protection rules favor verified, encrypted messages
Europe held 22.3% of 2025 value and grows at 19.43% a year. Germany, France, Spain and the United Kingdom lead, with operators and Apple rolling out business RCS on iPhones. Strict data protection rules favor verified, encrypted messaging and retailers and banks are the main buyers. Vodafone and Deutsche Telekom set prices and spam rules for business RCS across several countries, which helps multi-country brands launch campaigns with fewer separate agreements.
Latin America and Middle East & Africa uptake depends on chat apps and patchy support
Latin America held 7.9% of 2025 value and grows at 20.03% a year. Brazil and Mexico lead, with banks and retailers using RCS alongside WhatsApp Business. Middle East & Africa held 4.0% and grows at 18.53% a year. Saudi Arabia, the United Arab Emirates and South Africa lead, but operator support is patchy outside the Gulf and SMS remains the main business channel across most of Africa.
iOS 18, Universal Profile 3.0 and Jio pricing, 2024–2026
| Development | Status and market relevance |
|---|---|
| In September 2026, Jio introduced new RCS business messaging rates for messages to iPhone users in India, replacing a flat tariff. | In force. Turns iPhone RCS into a priced product in the largest RCS market. |
| In May 2026, Google announced that end-to-end encrypted RCS was rolling out in beta between Google Messages and iPhones on iOS 26.5. | Beta. Brings encrypted cross-platform messaging closer for regulated industries. |
| In March 2025, the GSMA announced Universal Profile 3.0, adding end-to-end encryption to RCS based on Messaging Layer Security. | Published. Sets the standard for encrypted, interoperable RCS. |
| In September 2024, Apple launched RCS support on the iPhone with iOS 18. | Shipped. Ends the Android-only limit on RCS reach. |
Encryption, verified branding and AI agents shape RCS
- Encryption arrives as Universal Profile 3.0 applies Messaging Layer Security to RCS, and cross-platform encrypted chats entered beta in 2026, easing compliance for banks and health providers.
- Verified branding through brand verification, logos and verified badges makes spoofing harder than with SMS sender IDs and supports higher prices per message.
- AI agents in the form of bots that answer questions, book appointments and take payments inside the thread raise the value of each two-way session.
- Routing and fallback platforms send RCS first and fall back to SMS automatically, so brands run 1 campaign while reach keeps expanding.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Platform owners, operators and providers split RCS value
Competition runs in three layers, starting with platform owners, which control the messaging apps and brand verification. Google runs the Jibe RCS cloud, Google Messages and the RBM platform that routes most business RCS outside China, and Apple brought RCS to the iPhone in 2024. Operators, including Reliance Jio, Bharti Airtel, Vodafone, Deutsche Telekom, AT&T, Verizon and T-Mobile U.S., set wholesale prices and spam rules, while China Mobile leads an operator-run 5G messaging service. Messaging providers such as Sinch, Infobip, Twilio, Vonage, Route Mobile and Tanla Platforms sell RCS to brands with SMS fallback, analytics and chatbot tools, competing on reach, delivery quality and price. Entry barriers are low for resellers but high for hubs that need operator agreements. Platform owners hold the strongest position because verification and the app sit with them. No company discloses RCS revenue on a comparable basis, so no share ranking is given.
Companies profiled and their roles
| Company | Type | Role in the market |
|---|---|---|
| Platform owner | Jibe RCS cloud, Google Messages and RBM brand verification | |
| Apple | Platform owner | RCS on the iPhone since iOS 18; business RCS via operators |
| Reliance Jio | Operator | Business RCS in India, including priced iPhone traffic |
| Bharti Airtel | Operator | Business RCS and spam filtering in India |
| Vodafone | Operator | Business RCS pricing and delivery in Europe |
| Deutsche Telekom | Operator | Business RCS pricing and delivery in Europe |
| AT&T, Verizon, T-Mobile U.S. | Operators | Business RCS on Android and iPhone in the U.S. |
| China Mobile | Operator | Leads the operator-run 5G messaging service in China |
| Sinch, Infobip, Twilio, Vonage | Messaging providers | RCS APIs with SMS fallback, analytics and chatbot tools |
| Route Mobile, Tanla Platforms | Messaging providers | High-volume RCS and SMS delivery, led by India |
RCS is the upgrade path for business SMS
Credence Research's view is that the share of business SMS traffic that RCS converts, rather than RCS as a separate channel, sets the market's value through 2035. The largest new revenue lies in conversational care, encrypted alerts for banks and health providers, and in-message payments. Providers that pair broad operator reach with AI agents and strong spam controls are best positioned. The main strategic risk is price, because if RCS stays far dearer than SMS and chat apps, volume will lag reach.
How Credence Research sized RCS business messaging
The report uses 2025 as the base year and forecasts to 2035, with CAGR calculated over 2025–2035. Market values come from Credence Research's market model, built from business messaging traffic, the share sent as RCS and prices per message or session; segment and regional splits are Credence Research estimates. Supporting evidence comes from GSMA specifications, operator and platform announcements, company filings and World Bank mobile subscription data, though scarce operator pricing disclosure limits precision for smaller markets.
Conversations, not broadcasts, set the pace through 2035
Through 2035, business messaging will shift from one-way SMS blasts toward verified, two-way RCS conversations. Encryption between Android and iPhone will become standard, brand verification will be expected by banks and regulators, and session pricing will spread. North America will gain share from 24.6% after the iPhone switch, while Asia Pacific remains the largest region on volume. Investment will flow to AI agents, payments inside the thread and operator hubs. The pace will depend on how quickly operators narrow the price gap with SMS and keep spam under control.
Frequently Asked Questions
What was the size of the rich communication services market in 2025?
What is the forecast value and CAGR of the RCS market?
What is driving RCS business messaging demand?
Which region holds the largest share of the RCS market?
Which use case leads the rich communication services market?
Who are the major companies in the RCS market?
Which industry spends the most on RCS?
What challenges could slow the rich communication services market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Use Case
- 1.2.1 Promotional & Marketing
- 1.2.2 Transactional & Alerts
- 1.2.3 Authentication & OTP
- 1.2.4 Conversational Customer Care
- 1.3 By End-Use Industry
- 1.3.1 BFSI
- 1.3.2 Retail & E-commerce
- 1.3.3 Others
- 1.3.4 Telecom & Media
- 1.3.5 Travel & Hospitality
- 1.3.6 Healthcare
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 2.86 billion → 2035: USD 18.31 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Rich Communication Services Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Rich Communication Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Rich Communication Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Rich Communication Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Rich Communication Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Rich Communication Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Rich Communication Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Rich Communication Services Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 2.86 billion → 2035: USD 18.31 billion)
- 11.1.2 Historical Market Size, 2018-2025
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Rich Communication Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Use Case - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Base-Year Market Share, 2025
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Promotional & Marketing
- 12.3.6.2 Transactional & Alerts
- 12.3.6.3 Authentication & OTP
- 12.3.6.4 Conversational Customer Care
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By End-Use Industry - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Base-Year Market Share, 2025
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 BFSI
- 12.4.6.2 Retail & E-commerce
- 12.4.6.3 Others
- 12.4.6.4 Telecom & Media
- 12.4.6.5 Travel & Hospitality
- 12.4.6.6 Healthcare
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Rich Communication Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Rich Communication Services Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Rich Communication Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2025-2035
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Rich Communication Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Google
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Apple
- 18.4 Reliance Jio
- 18.5 Bharti Airtel
- 18.6 Vodafone
- 18.7 Deutsche Telekom
- 18.8 AT&T
- 18.9 Verizon
- 18.10 T-Mobile US
- 18.11 China Mobile
- 18.12 Sinch
- 18.13 Infobip
- 18.14 Twilio
- 18.15 Vonage
- 18.16 Route Mobile
- 18.17 Tanla Platforms
- 18.18 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

