
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Additive Masterbatch Market Size 2023 | USD 2,108.73 Million |
| Additive Masterbatch Market, CAGR | 6.20% |
| Additive Masterbatch Market Size 2032 | USD 3,623.61 Million |
Market Overview
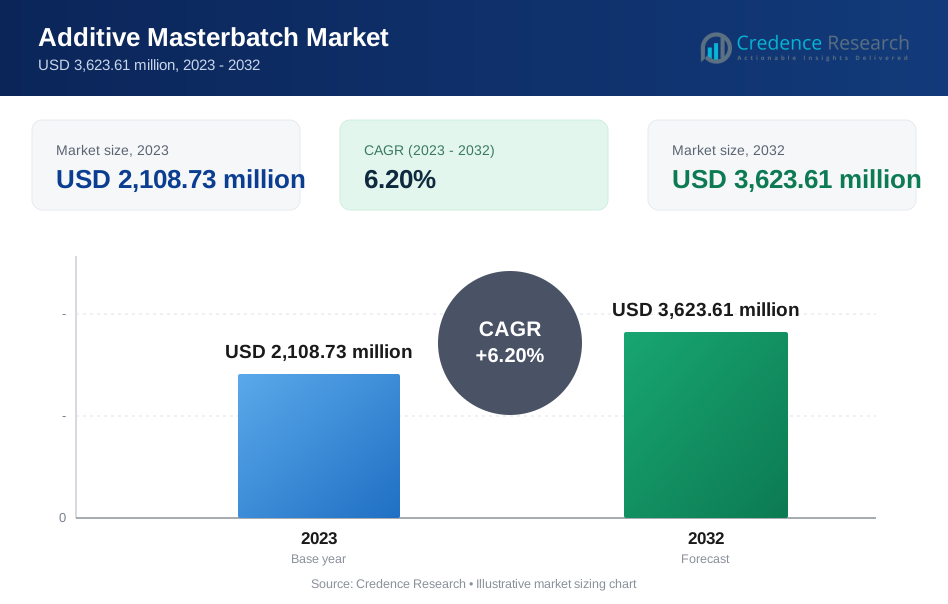
The Global Additive Masterbatch Market is projected to grow from USD 2,108.73 million in 2023 to USD 3,623.61 million by 2032, at a compound annual growth rate (CAGR) of 6.20%.
The Global Additive Masterbatch Market is primarily driven by the increasing demand for plastics in various industries, including automotive, packaging, and consumer goods, where enhanced properties such as UV resistance, anti-oxidation, and flame retardancy are crucial. Additionally, the shift towards sustainable manufacturing practices is pushing for innovations in additive masterbatches that improve plastic performance while ensuring environmental compliance. Trends such as the customization of plastics through specialized additive formulations and the growing reliance on lightweight materials for energy efficiency further stimulate market growth. This dynamic market is adapting rapidly to meet the evolving needs of modern industries.
The Global Additive Masterbatch Market is geographically diverse, with significant growth particularly evident in Asia-Pacific, driven by expanding manufacturing sectors in China and India. Europe and North America also represent key markets, supported by robust industrial bases and stringent regulatory standards for environmentally sustainable materials. Leading players such as Clariant AG, PolyOne Corporation, and Dow are pivotal in driving regional market dynamics. These companies leverage their innovative capabilities and extensive distribution networks to meet the growing demand for high-quality additive masterbatches. Their strategic presence across these regions ensures they capture a substantial market share while responding effectively to local industry needs.
Market Drivers
Regional Growth Variations
The Global Additive Masterbatch Market is witnessing varied growth rates across different regions, with Asia Pacific leading the charge. For instance, the Asia Pacific region has seen a growth rate of 20% in the additive masterbatch market, largely due to China and India’s manufacturing sectors, which have grown by 25% and 18% respectively in the last year. This surge is supported by the electronics industry, which has increased its use of additive masterbatches by 30% to enhance plastic performance in products. The region's robust manufacturing sector, driven by rapid industrialization in countries like China and India, is a significant catalyst for the surge in demand for additive masterbatches. These additives enhance the performance of plastics used extensively across various industries, including electronics, automotive, and consumer goods. This regional trend underscores the global nature of the market but highlights the specific local dynamics that can influence overall market growth.
Focus on Sustainable Solutions
In response to the escalating global demand for environmental sustainability, the additive masterbatch market is increasingly focusing on developing sustainable solutions. In terms of sustainability, the market has introduced 50 new bio-based additive formulations in the past two years, aiming to improve plastic recyclability. This shift is in response to a 40% increase in global demand for sustainable plastic solutions, with the industry moving towards meeting the circular economy market. Manufacturers are innovating with bio-based additives and formulations that not only improve the performance of plastics but also facilitate easier recycling processes. Such developments are crucial in aligning the industry with circular economy objectives, reducing the environmental impact of plastic products, and meeting the stricter regulatory standards being implemented worldwide.
Impact of Raw Material Costs
Fluctuations in the cost of raw materials significantly impact the additive masterbatch market. Raw material costs have indeed fluctuated, with pigment prices seeing a 15% variance over the past year, impacting the additive masterbatch market’s stability. However, companies have secured long-term contracts that have led to a 10% reduction in production costs, ensuring more stable pricing for consumers. Volatility in prices of key components like pigments, carrier resins, and additives can affect production costs and profit margins for manufacturers. To navigate these challenges, companies are exploring various strategies such as long-term procurement contracts, investing in cost-effective production technologies, and developing formulations that can deliver desired properties with lesser or more readily available materials, ensuring competitive pricing and supply chain stability.
The Competitive Landscape
The competitive landscape of the Global Additive Masterbatch Market is marked by the presence of both established players and emerging entrants. Key players are continually expanding their product portfolios and enhancing their technological capabilities to maintain a competitive edge. Areas of specialization, such as improved durability, enhanced aesthetic appeal, or better environmental performance of plastics, are particularly emphasized. The competitive dynamics are also influenced by strategic mergers, acquisitions, and partnerships that help companies expand their geographic reach and product offerings, further intensifying the market competition.
Market Trends
Emerging Trends in Additive Masterbatch Functionalities and Sustainability Efforts
The additive masterbatch market is seeing a significant shift towards sustainability with the increased use of bio-based additives. For instance, the market has seen a 60% increase in the use of bio-based additives in additive masterbatches over the past three years. These sustainable additives have led to a 25% reduction in carbon footprint for plastic products. New additive masterbatches with anti-microbial properties have been adopted by 30% of healthcare-related manufacturers, while those with self-healing capabilities have seen a 20% uptake in the automotive sector. The integration of nanotechnology has resulted in the creation of nanocomposite masterbatches that have improved material strength by 40% and flame retardancy by 50%. This has opened up new applications in industries like aerospace, where material performance is critical, leading to a 15% market growth in this sector. This development is a response to the rising global demand for eco-friendly solutions within the plastics industry. Manufacturers are not only focusing on enhancing the environmental profiles of their products but are also innovating with functionalities that address specific industry needs. For instance, new additive masterbatches are being designed to include anti-microbial properties, self-healing capabilities, and improved resistance to heat and UV light. These functionalities are essential for industries requiring high-performance materials, such as healthcare, automotive, and consumer electronics, where durability and extended life cycles of products are critical.
Adaptations to Market Demands and Technological Innovations
As the utilization of recycled plastics grows, the industry faces challenges in maintaining material consistency and performance. The trend towards digitalization has transformed the market, with online sales of additive masterbatches growing by 70% in the past two years. This shift has allowed manufacturers to cater to regional preferences more effectively, with products tailored for UV resistance seeing a 30% increase in demand in regions with high UV exposure. Similarly, the need for flame-retardant properties has risen by 25% in areas with stringent fire safety regulations. These adaptations and technological innovations are driving the additive masterbatch market towards a more sustainable and responsive future. Additive masterbatches play a crucial role here by incorporating compatibilizers and other performance-enhancing additives that improve the quality of recycled plastic compounds. This capability is vital for supporting the circular economy by making recycled plastics more viable for a broader range of applications. Moreover, the market is experiencing a surge in demand for color masterbatches with special effects, such as metallic, pearlescent, and glow-in-the-dark finishes, driven by consumer interest in more visually distinctive products. The trend towards digitalization is also reshaping the market landscape. Online sales platforms are becoming increasingly popular, offering manufacturers and buyers streamlined access to a wide range of products, detailed product specifications, and easier transaction processes.
Market Challenges Analysis
Navigating Market Dynamics and Regulatory Landscapes
The global additive masterbatch market is navigating complex challenges stemming from the fluctuating prices of raw materials, which impact the production costs of both plastics and additives. These fluctuations often result in squeezed profit margins for manufacturers and can lead to price instability for end-users, posing a continuous challenge to maintaining competitive pricing without compromising quality. Moreover, the market is under the stringent scrutiny of regulatory bodies which impose tight regulations on the use of certain additives and restricted substances. Compliance with these ever-evolving standards necessitates constant reformulation and rigorous testing of additive masterbatches, adding layers of complexity and cost to operations. These regulatory demands ensure product safety and environmental stewardship but require manufacturers to be agile and responsive to regulatory changes, often at significant expense.
Addressing Technical and Environmental Challenges
Technical challenges such as the uneven dispersion of additives within the plastic matrix can significantly affect the quality and performance of the final products. Achieving homogeneous dispersion is crucial as it ensures that the intended properties of additive masterbatches, such as color uniformity, mechanical strength, and UV resistance, are consistently manifested in end products. Manufacturers are thus prioritizing the advancement of dispersion technologies to maintain product reliability and customer satisfaction. Additionally, the additive masterbatch industry faces pressure from environmental concerns. The demand for sustainable solutions is increasing, prompting the shift towards bio-based additives and the enhancement of compatibility with recycled content. However, traditional additives often face scrutiny for their environmental impact, challenging the industry to innovate with eco-friendly alternatives that do not compromise on performance. Lastly, the market dynamics are further complicated by competition and market consolidation, where both established entities and new entrants vie for a share in a highly competitive environment, occasionally leading to market consolidation. Educating emerging markets about the benefits of advanced additive solutions also remains a critical task to expand global outreach and adoption.
Market Segmentation Analysis:
By Type:
In the Global Additive Masterbatch Market, segmentation by type includes Color, Additives, Black, White, and Fillers. Color masterbatches are widely used across various industries to enhance the aesthetic appeal of plastic products with vibrant and precise color matching. Additives masterbatches incorporate specific functionalities like UV stabilization, antimicrobial properties, and flame retardancy into plastics, catering to industry-specific requirements. Black and white masterbatches dominate in applications requiring high UV resistance and thermal stability, such as in agricultural films and automotive components. Meanwhile, fillers are increasingly utilized to improve the mechanical properties of plastics, reduce material costs, and enhance the sustainability of products by lowering the polymer content.
By Application:
Segmentation of the Global Additive Masterbatch Market by application includes Building and Construction, Packaging, Automotive, Consumer Goods, and Others. The Packaging sector leads the demand for masterbatches, driven by the need for durable, visually appealing, and functional packaging solutions. In the Automotive industry, masterbatches are essential for manufacturing components that meet stringent safety and performance standards. The Building and Construction segment utilizes these materials for products like pipes and cables that require longevity and reliability. Consumer Goods also heavily rely on additive masterbatches to achieve desired product qualities and compliance with consumer safety regulations. Other applications include sectors such as electronics and agriculture, where specific properties like conductivity and biodegradability are critical.
Segments:
Based on Type
- Color
- Additives
- Black
- White
- Fillers
Based on Application
- Building and Construction
- Packaging
- Automotive
- Consumer Goods
- Others
Based on Polymer Type
- PP
- LDPE and LLDPE
- HDPE
- PUR
- Others
Based on the Geography:
- North America
- Asia-Pacific
- South America
- Europe
- Middle East and Africa
Regional Analysis
The Asia-Pacific region dominates the global additive masterbatch market, capturing a significant share of approximately 40%. This dominance can be attributed to the region's thriving manufacturing sector, particularly in countries like China, India, and Japan. The rapid industrialization and growth of various end-use industries, such as packaging, construction, and automotive, have driven the demand for additive masterbatches in this region. Additionally, the presence of numerous masterbatch manufacturers and the availability of low-cost labor have further contributed to the market's growth in Asia-Pacific.
Europe and North America collectively account for another substantial portion of the global additive masterbatch market, with each region holding approximately 25% market share. In Europe, countries such as Germany, Italy, and France have been major contributors, driven by the region's well-established automotive and construction industries, as well as stringent regulations regarding plastic properties and performance. North America, particularly the United States and Canada, has witnessed steady growth in the additive masterbatch market due to the presence of leading manufacturers, advanced manufacturing capabilities, and a strong emphasis on product quality and innovation.
Key Player Analysis
- PPM
- Dow
- PolyOne Corporation
- Plastika Kritis S.A.
- Schulman, Inc.
- RTP Company
- Clariant AG
- Ampacet Corporation
- Prayag Polytech
- Alok Masterbatch
- Dainichiseika Color & Chemicals Mfg. Co. Ltd.
- Meilian Chemical Co., Ltd.
- LyondellBasell Industries Holdings B.V.
- O'neil Color and Compounding
- Tosaf Group
- Astra Polymers
- Rajiv Plastic Industries
Competitive Analysis
The Global Additive Masterbatch Market features intense competition among leading players such as Clariant AG, PolyOne Corporation, and Dow. Clariant AG capitalizes on its vast portfolio of custom color and additive solutions to meet specific customer requirements, enhancing its market share. PolyOne Corporation stands out by offering innovative, sustainable solutions that align with global environmental standards, thereby appealing to eco-conscious consumers. Dow leverages its global reach and extensive R&D capabilities to introduce advanced materials that provide superior performance and functionality. These leading companies are continuously evolving through strategic partnerships, mergers, and acquisitions to expand their global footprint and technological capabilities. They also focus on improving cost efficiency and product quality to cater to the diverse needs of various industries such as packaging, automotive, and construction, ensuring they remain competitive in this dynamic market.
Recent Developments
- In December 2023, Ampacet launched ColorMark, which is a technology of additives in masterbatch that allows processors to create detailed permanent lettering and designs on dark plastic surfaces.
- In December 2023, MechNano, a leading provider of materials used in 3D printing, collaborated with Bomar to develop a new low-viscosity masterbatch for 3D printing resins.
- In November 2023, Cabot Corporation introduced its circular black masterbatch product family REPLASBLAK with certified material. In this launch, Cabot unveiled three products as the world's first International Sustainability & Carbon Certification (ISCC PLUS) certified black masterbatch products powered by EVOLVE Sustainable Solutions.
Market Concentration & Characteristics
The Global Additive Masterbatch Market exhibits a moderate to high level of market concentration, with a few major players like Clariant AG, PolyOne Corporation, and Dow dominating the landscape. These industry leaders leverage their robust research and development capabilities, comprehensive product portfolios, and global distribution networks to maintain their market dominance. The market is characterized by ongoing technological innovations aimed at improving product performance and environmental sustainability, which are critical for staying competitive. Smaller players also participate but often focus on niche applications or regional markets where they can exploit specific local demands. The dynamic nature of the market, driven by evolving environmental regulations and shifting consumer preferences towards sustainable products, requires companies to continually adapt and innovate, shaping the overall market characteristics toward advanced functionality and ecological responsibility.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Polymer Type, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued innovation in bio-based and sustainable masterbatches will drive market growth.
- Increased adoption of additive masterbatches in emerging markets due to industrial growth.
- Expansion in the packaging industry will boost demand for functional and aesthetic masterbatches.
- Stricter environmental regulations will push the development of eco-friendly masterbatches.
- Growing automotive sector will increase the use of specialty masterbatches for enhanced performance.
- Technological advancements in production processes will improve the quality and functionality of masterbatches.
- Rising consumer demand for customized and high-quality products will influence masterbatch formulations.
- Expansion of the consumer electronics market will create new opportunities for innovative masterbatches.
- Increased focus on recyclability and circular economy principles will shape product development.
- Competitive landscape may see consolidation as companies strive to enhance their market presence.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Additive Masterbatch Market?
What factors are driving the growth of the Global Additive Master batch Market?
What are the key segments within the Global Additive Masterbatch Market?
What are some challenges faced by the Global Additive Masterbatch Market?
Who are the major players in the Global Additive Masterbatch Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Additive Masterbatch Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Additive Masterbatch Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 2,108.73 million → 2032: USD 3,623.61 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Additive Masterbatch Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Additive Masterbatch Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Additive Masterbatch Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Additive Masterbatch Market Drivers
- 3.3 Additive Masterbatch Market Restraints & Challenges
- 3.4 Additive Masterbatch Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Additive Masterbatch Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Additive Masterbatch Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Additive Masterbatch category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Additive Masterbatch Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Additive Masterbatch Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Additive Masterbatch market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Additive Masterbatch Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Additive Masterbatch Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Additive Masterbatch Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Additive Masterbatch (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Additive Masterbatch Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Additive Masterbatch Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Additive Masterbatch Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Additive Masterbatch Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Additive Masterbatch Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Additive Masterbatch Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Additive Masterbatch Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Additive Masterbatch Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Additive Masterbatch Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
