
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Ferrous Slag Market Size 2023 | USD 12581.2 Million |
| Ferrous Slag Market, CAGR | 6.50% |
| Ferrous Slag Market Size 2032 | USD 22175.25 Million |
Market Insights
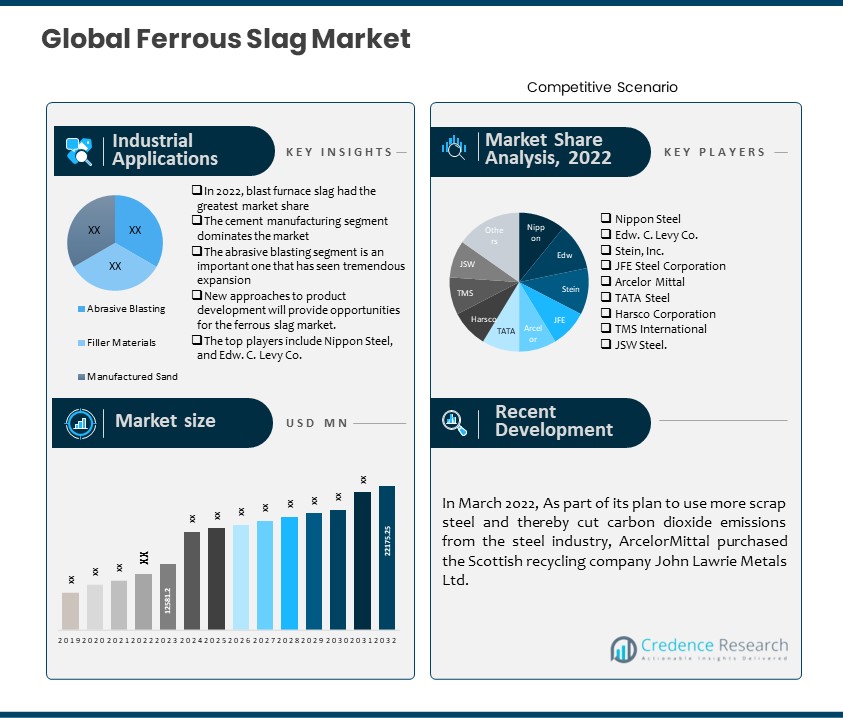
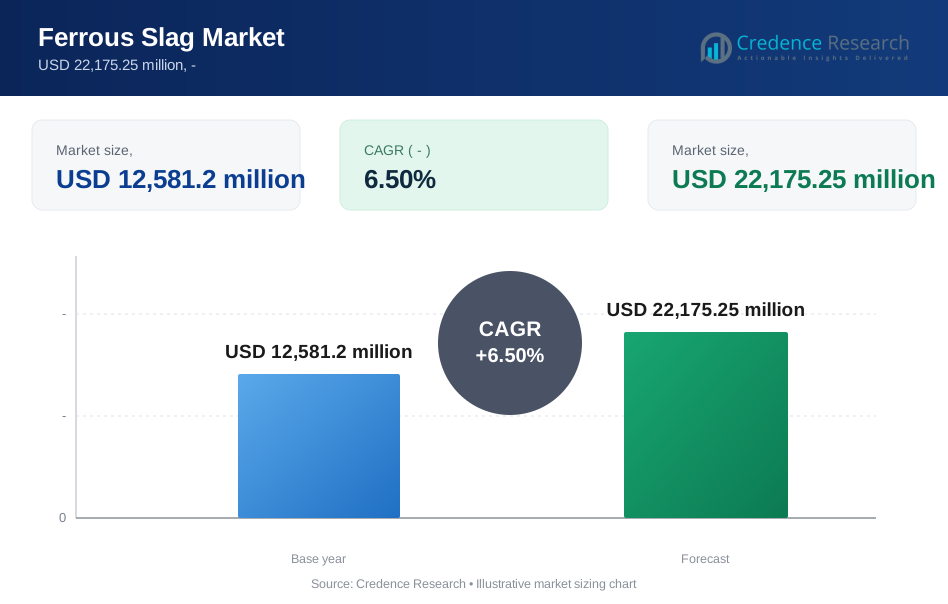
- The global market for ferrous slag is expected to develop at a compound annual growth rate (CAGR) of 6.50% between 2024 and 2032, from its estimated USD 12581.2 million in 2023 to USD 22175.25 million in 2032.
- The largest category is blast furnace slag. Steel slag, on the other hand, is expected to grow at a strong CAGR.
- The cement manufacturing category will expand at a rapid rate of growth.
- The CAGR for the abrasive blasting is expected to be the highest during the projection period.
- North America dominated the ferrous slag market.
- Regarding the market share of ferrous slag, Europe is expected to come second.
- In the ferrous slag market, Asia Pacific is anticipated to grow fastest.
- The expansion of the construction sector, the development of infrastructure, and the ways in which production volumes and practices in the steel industry affect the availability and cost of ferrous slag are among the factors supporting global market growth.
- Growing urbanization raises the need for building supplies, and strict laws supporting environmentally friendly building methods promote the usage of recycled materials like ferrous slag.
Executive Summary
Market Definition
The ferrous slag market includes the production, processing, and usage of slag produced during the iron and steel manufacturing process. When iron ore or iron pellets are melted in a blast furnace to make pig iron or crude steel, a byproduct known as ferrous slag is created. The main constituents of this slag are silicates and oxides, with the possibility of traces of metallic metals.
Market Overview
The ferrous slag sector is estimated to develop at a 6.50% compound annual growth rate (CAGR) between 2024 and 2032, maintaining its current upward trend. The market will continue to develop, rising from its estimated USD 12581.2 million in 2023 to USD 22175.25 million in 2032.
The market for ferrous slag is expanding primarily due to its performance advantages. Building materials like asphalt and concrete are made more durable by ferrous slag. By increasing resistance to elements like abrasion, weathering, and chemical deterioration, its application can lead to infrastructure that lasts longer and requires less care.
The compressive and flexural strengths of concrete can be improved by adding ferrous slag to the mixture. This makes it possible to develop structures that are stronger and more resilient, which is especially vital in situations like high-rise buildings and bridges where structural integrity is essential. The heat of hydration of ferrous slag is lower than that of conventional cementitious materials. This characteristic increases the overall lifetime and durability of concrete by reducing the chance of heat cracking, particularly in big pours or mass concrete buildings. Ferrous slag is a good choice for projects aiming for certification in Leadership in Energy and Environmental Design (LEED) or other green building credentials due to its environmental qualities and performance advantages. This increases the need for materials based on slag in environmentally friendly building projects.
Segmentation by Type of Ferrous Slag
- Blast furnace slag is the market leader in terms of type of ferrous slag. Slag from blast furnaces is frequently utilized in construction projects like making concrete, cement, and building roads. As a result, the demand for blast furnace slag is directly impacted by the need for building materials.
- The steel slag category will exhibit a sizable CAGR during the projected period. Due to its distinct physical and chemical characteristics, steel slag can be used in a variety of engineering applications, such as soil stabilization, railroad ballast, and embankment building.
- Other types of ferrous slag influence the need for ferrous slag, including basic oxygen furnace (BOF) slag, electric arc furnace (EAF) slag, ladle furnace slag, and argon oxygen decarburization (AOD) slag.
Segmentation by End-Use Applications
- Cement manufacturing is considered the best end-use application category. Steel and blast furnace slag, in particular, are ferrous slags that can be utilized as SCM in the production of cement. When ground finely, these slag minerals have hydraulic or pozzolanic qualities. This implies that when water is present, it can react with calcium hydroxide to generate cementitious compounds. Because of this characteristic, ferrous slag is a great alternative to conventional clinker in the manufacturing of cement.
- The construction and building materials category will likely register a significant CAGR during forecasting. Ferrous slag is used in building materials and construction in compliance with laws and sustainability programs that minimize waste production, conserve resources, and lessen environmental effects. Standards and laws have been put in place in many areas to encourage the use of substitute materials in building projects, such as ferrous slag.
- Other end-use applications, such as concrete production, road construction, railroad ballast, mine reclamation, soil stabilization and remediation, and agricultural applications, also contribute to the demand for ferrous slag.
Segmentation by Industrial Applications
- The abrasive blasting category is projected to grow faster over the projection period. Abrasive blasting is the most popular method for preparing a surface for painting, coating, or bonding. It eliminates rust, scale, old paint, and other surface impurities to guarantee correct adhesion and coating longevity.
- Other industrial applications influence the need for ferrous slag, including filler materials and manufactured sand.
Segmentation by Region
- North America leads the ferrous slag industry. In North America, one of the biggest users of ferrous slag is the building sector. The requirement for building materials, including concrete, asphalt, and aggregates, rises as the region's infrastructure, residential construction, and commercial developments all grow. The qualities of ferrous slag, especially steel and blast furnace slag, make them useful for a variety of construction applications. These benefits include increased strength, durability, and ecological advantages.
- Europe is estimated to rank second in market size for ferrous slag.
- The ferrous slag industry is predicted to flourish rapidly in Asia Pacific.
- The remaining need for ferrous slag is met by regions like Latin America, the Middle East, and Africa.
The need for alternative materials, such as ferrous slag, in construction applications is being driven by growing awareness and legislation about sustainable construction techniques. In concrete and asphalt, slag is frequently utilized in place of natural aggregates to lessen the environmental impact of these materials.
Based on projections, North America is anticipated to control the ferrous slag market. Construction materials, especially ferrous slag, are in great demand in North America due to government efforts and private expenditures in infrastructure projects. Major building initiatives, including roads, bridges, railroads, and airports, need a lot of concrete and asphalt, which can both include ferrous slag as an extra component. Because ferrous slag is recyclable and has a lower ecological effect than other building materials, its usage is supported by the expanding emphasis on sustainable building approaches.
Moreover, Asia Pacific is anticipated to increase at a high rate over the projection period. The establishment of highways, metro systems, and smart cities are just a few of the ambitious infrastructure development projects in India that are supporting the country's demand for building supplies like ferrous slag. Government programs like "Make in India" and "Smart Cities Mission" encourage infrastructure spending and boost the building industry. Steel and blast furnace slag from South Korea's thriving steel industry are produced in enormous quantities and are successfully utilized in civil engineering and building projects. Merging the steel and building industries improves ferrous slag usage and encourages cooperation for creative uses.
Key Highlights of the Report
The global ferrous slag market is segmented by type of ferrous slag, end-use applications, industrial applications, and region. As far as the type of ferrous slag is concerned, blast furnace slag is the market spearhead. Cement manufacturing is the top end-use application category. Throughout the projection period, the category of abrasive blasting is expected to grow at the greatest CAGR. The ferrous slag market is expanding mostly in North America.
The market for ferrous slag is expanding largely due to regulatory policies. Regulations have been put in place in many areas with the goal of minimizing landfilling and encouraging the recycling or reuse of industrial wastes, such as ferrous slag. These rules encourage steel producers to discover valuable uses for their slag, which expands the market. Standards and requirements for building materials—including those containing ferrous slag—are frequently set by regulatory authorities. Adherence to these guidelines could mandate or encourage the utilization of slag-derived materials in building endeavors, thus fostering industry expansion.
North America is expected to account for the largest ferrous slag market globally. In some cases, ferrous slag is less expensive in North America than conventional building materials. Due to its accessibility as a byproduct of the steel-making process and comparatively reduced production costs, it is a financially acceptable choice for building projects. Due to its affordable pricing and superior effectiveness, ferrous slag is becoming an increasingly popular choice for businesses looking to cut costs without sacrificing quality. The Asia Pacific region is also assumed to have the market's sharpest growth. China's increasing need for building supplies, particularly ferrous slag, is supported by the country's fast urbanization and ongoing infrastructure development. The utilization of ferrous slag in concrete, asphalt, and road building is stimulated by large-scale projects like high-speed railroads, highways, and urban infrastructure.
Which Key Factors Are Driving The Global Ferrous Slag Market?
The ferrous slag market is expanding due to a number of factors, including government policies and incentives, technical developments, sustainability initiatives, and rising worldwide population demand for housing, infrastructure, and building materials.
What Are The Main Challenges Confronting The Global Ferrous Slag Market?
The transport expenses and logistical limitations related to bulk processing and distribution of ferrous slag materials, as well as a lack of financing for research and development in ferrous slag use, are the main barriers to the sector's expansion.
What Market Opportunities Exist For Ferrous Slag Globally?
The utilization of modern construction technology, which increases the requirement for suitable materials like ferrous slag, spending in the energy sector, and the creation of smart city projects might all result in an expansion of the ferrous slag market.
Market Drivers
Multiple factors propel the ferrous slag industry across the globe. The primary factors propelling the global ferrous slag market are as follows:
Growth Of The Steel Industry
Ferrous slag production rises in direct proportion to the size of the steel industry, which is expanding to fulfill the increasing demand on a global scale. This increased output volume guarantees a consistent and sufficient supply of ferrous slag for a range of uses. More ferrous slag is available for use when more steel is produced. Due to its accessibility, ferrous slag is becoming more and more popular as a substitute for conventional building materials across a range of industries. Diverse kinds of ferrous slag with diverse qualities are produced as a result of the expanding steel industry. Due to this variability, slag-based products that are customized for certain purposes can be developed, broadening the market's appeal to the manufacturing, infrastructure, and construction industries. Cost benefits over conventional raw materials are frequently realized due to the availability of ferrous slag that is produced as a byproduct of steel production. Slag-based products are profitable for end users due to their cost competitiveness, which propels market expansion even further.
Market Restraints
There are several obstacles that the global ferrous slag market must overcome to continue growing. Among them are the following:
Alternative Building Materials Present a Competition for Ferrous Slag
In some applications, the advent of substitute building materials poses competition for ferrous slag, which could limit the market's expansion. Bio-based and recycled building materials like bamboo, straw bales, recycled plastic, and recovered wood are becoming more and more popular as sustainability and environmentally friendly construction techniques become more and more important. These materials provide low-impact, sustainable substitutes for ferrous slag and other conventional building materials. Therefore, instead of ferrous slag, builders and developers may choose these alternatives in applications where sustainability is a top priority. Due to developments in materials science, new composite materials with improved durability and performance over traditional building materials have been created. For instance, lightweight, highly-strength alternatives to steel and concrete are offered by fiber-reinforced composites, engineered wood materials, and new polymers, which can eliminate the requirement for ferrous slag in some structural applications.
Opportunities
There are plenty of potential prospects in the global ferrous slag industry. Among these are the following:
New Approaches To Product Development
The ferrous slag market has an excellent opportunity to grow its applications through innovation in product development. Technological advancements in the processing industry can improve the adaptability, efficiency, and quality of products made from ferrous slag. Ferrous slag can be refined using cutting-edge methods like grinding, pelletizing, and heat treatment to create high-performance materials with unique qualities appropriate for certain uses. For instance, slag particles' reactivity may be enhanced by finer grinding, increasing their usefulness as additional cementitious materials in the creation of concrete. Customizing Ferrous Slag products to fit certain application needs offers a chance to cater to niche markets and clientele. Manufacturers can create specialized ferrous slag solutions that are ideal for use in metallurgical processes, water treatment, abrasive blasting, and soil stabilization by knowing the performance requirements and technical specifications of various industries. Providing customized solutions can set ferrous slag providers apart and add value for clients looking for specialty materials. The ferrous slag market has a lot of potential to expand into new markets, broaden its product line, and produce value-added solutions that satisfy changing industry standards and consumer needs because of creativity in product development.
Competitive Landscape
Key Players
Several major competitors exist in the fiercely competitive global ferrous slag market. The following are a few of the leading market participants and their market shares:
- Nippon Steel
- Edw. C. Levy Co.
- Stein, Inc.
- JFE Steel Corporation
- Arcelor Mittal
- TATA Steel
- Harsco Corporation
- TMS International
- JSW Steel
- Others
These companies prioritize product innovation, distribution channel expansion, mergers, and acquisitions to remain competitive.
The most significant suppliers in the global market for ferrous slag consistently strive to keep one step ahead of the competition by creating novel ideas and goods.
In February 2023, Nippon Steel Corporation declared that it had reached a deal with Elk Valley Resources Ltd. (EVR) to indirectly purchase up to 10% of the latter's common shares, preference shares, and royalty interest.
In July 2022, BP plc and ThyssenKrupp Steel announced their partnership. The strategic partnership aims to decarbonize the steel industry, as Germany's 2.5% CO2 emissions come from ThyssenKrupp Steel. To manufacture green steel and goods, ThyssenKrupp Steel and BP plc intend to replace the blast furnaces that burn coal.
In August 2021, Russian scientists used an electric furnace and ladle slag to create pig iron and clinker in a waste-free manner.
In June 2021, JSW Cement unveiled fresh possibilities to combine ethical building practices with innovation in concrete mix products. Concreting with screen slag rather than river sand conserves natural resources and lessens air pollution, floods, and landslides. JSW Cement's construction chemicals are some of the greenest on the market.
Summary of Key Findings
- Opportunities exist in the domains of water treatment and land reclamation because the market is dominated by the need for cost-effective and sustainable solutions. By utilizing slag's unique attributes, such as its potential for adsorption and soil-enhancing capabilities, industries and governments can address environmental challenges, improve resource efficiency, and contribute to sustainable development.
- The market is segmented by type of ferrous slag, end-use applications, industrial applications, and region.
- In the market, blast furnace slag is the most widely used type of ferrous slag.
- Cement manufacturing is the foremost end-use application category.
- The abrasive blasting category is expected to grow fastest in terms of CAGR during the forecast period.
- North America is leading market development; the market is highly competitive with key players including Nippon Steel, Edw. C. Levy Co., Stein, Inc., JFE Steel Corporation, Arcelor Mittal, TATA Steel, Harsco Corporation, TMS International, JSW Steel, and Others.
Future Outlook
- The ferrous slag industry is expected to increase significantly in North America, and its outlook is positive worldwide.
- Slag supply has increased as a result of increased steel production, supporting market expansion.
- Alternative building materials like fly ash, silica fume, and natural aggregates may compete with ferrous slag, which could limit the market's expansion.
- To stay ahead of the competition, key enterprises must develop new products, expand their market reach, and keep their prices competitive.
How CXOs Can Benefit from the Credence Research Ferrous Slag Market Report
CXOs may get a detailed picture of the market in the Credence Research Ferrous Slag Market Report, which includes:
- Market size and growth forecast: The report provides detailed estimates of the global ferrous slag market size, segmented by type of ferrous slag, end-use applications, industrial applications, and region. It also includes forecasts for the market through 2032 based on key trends and drivers.
- Market segmentation: The research report breaks down the market for ferrous slag into segments based on type of ferrous slag, end-use applications, industrial applications, and region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive landscape: The research report offers a detailed analysis of the major companies in the ferrous slag industry, including information on their business plans, product lines, and earnings. CXOs can use this information to evaluate and identify their competitors.
- Key trends and drivers: The research report identifies and evaluates the main trends and factors influencing the ferrous slag market. CXOs can use this information to make well-informed choices regarding their plans and investments.
CXOs can use the insights from the Credence Research Ferrous Slag Market Report to:
- Identify growth opportunities: This analysis may help CXOs identify new growth opportunities in the ferrous slag sector. For example, the report identifies the growing demand for ferrous slag from the road construction industry as a key opportunity.
- Make informed investment decisions: The report helps CXOs make wise choices regarding ferrous slag. For example, the research study provides information on the critical factors to consider when selecting ferrous slag solutions and evaluating suppliers.
- Develop competitive strategies: CXOs can use the research report to develop competitive strategies for their ferrous slag businesses. For example, the research paper outlines the main strategies that ferrous slag suppliers utilize to differentiate themselves from competitors.
- Track market developments: This research report may help CXOs stay ahead of the curve by tracking market developments. For instance, it offers insights into the most recent developments and trends in the ferrous slag market.
CXOs seeking to expand their industry knowledge and spot growth prospects will find the Credence Research Ferrous Slag Market Report useful.
Segmentation
- By Type of Ferrous Slag
- Blast Furnace Slag
- Granulated Blast Furnace Slag (GBFS)
- Air-Cooled Blast Furnace Slag
- Steel Slag
- Basic Oxygen Furnace (BOF) Slag
- Electric Arc Furnace (EAF) Slag
- Ladle Furnace Slag
- Argon Oxygen Decarburization (AOD) Slag
- Blast Furnace Slag
- By End-Use Applications
- Construction and Building Materials
- Concrete Production
- Road Construction
- Railroad Ballast
- Mine Reclamation
- Cement Manufacturing
- Soil Stabilization and Remediation
- Agricultural Applications
- By Industrial Applications
- Abrasive Blasting
- Filler Materials
- Manufactured Sand
- By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- The Rest of the Middle East and Africa
- North America
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
How much does the global market currently hold for ferrous slag?
What is the ferrous slag market's projected growth rate between 2024 and 2032?
In terms of the type of ferrous slag, which market category is leading?
Which industrial applications segment is estimated to have the highest CAGR throughout the forecast period?
Who are the main players in the global ferrous slag industry?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Ferrous Slag Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Ferrous Slag Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 12,581.2 million → forecast year: USD 22,175.25 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Ferrous Slag Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Ferrous Slag Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Ferrous Slag Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Ferrous Slag Market Drivers
- 3.3 Ferrous Slag Market Restraints & Challenges
- 3.4 Ferrous Slag Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Ferrous Slag Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Ferrous Slag Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Ferrous Slag category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Ferrous Slag Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Ferrous Slag Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Ferrous Slag market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Ferrous Slag Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Ferrous Slag Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Ferrous Slag Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Ferrous Slag (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Ferrous Slag Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Ferrous Slag Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Ferrous Slag Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Ferrous Slag Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Ferrous Slag Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Ferrous Slag Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Ferrous Slag Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Ferrous Slag Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Ferrous Slag Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
