
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
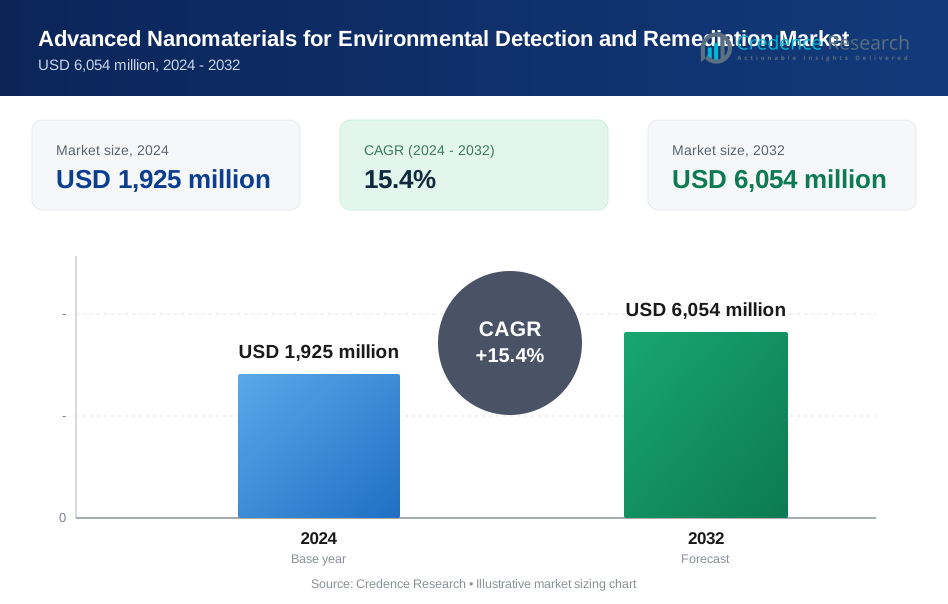
| Advanced Nanomaterials for Environmental Detection & Remediation Market Size 2024 | USD 1,925 million |
| Advanced Nanomaterials for Environmental Detection & Remediation Market, CAGR | 15.4% |
| Advanced Nanomaterials for Environmental Detection & Remediation Market Size 2032 | USD 6,054 million |
Market Overview
The market for advanced nanomaterials used in environmental detection and remediation is projected to grow from USD 1,925 million in 2024 to USD 6,054 million by 2032, with a compound annual growth rate (CAGR) of 15.4%.
The market for advanced nanomaterials in environmental detection and remediation is driven by growing environmental concerns, increased regulations on pollution control, and the demand for sustainable solutions. Nanomaterials, with their high surface area and unique properties, offer enhanced sensitivity and efficiency in detecting and removing contaminants such as heavy metals, pollutants, and organic compounds from air, water, and soil. Key trends include the development of multifunctional nanomaterials that combine detection and remediation in a single step, advancements in nano-catalysts for water and air purification, and the integration of nanotechnology with artificial intelligence and machine learning for real-time environmental monitoring. The push for cleaner energy sources and carbon reduction also promotes the use of nanomaterials in reducing industrial emissions and improving waste management. With continued innovations in nanotechnology and increasing governmental focus on sustainability, the market is expected to see significant growth in the coming years.
The advanced nanomaterials market for environmental detection and remediation is geographically diverse, with North America holding the largest market share, driven by strict environmental regulations and strong R&D investments. Europe follows closely, supported by sustainability initiatives like the EU Green Deal, particularly in countries like Germany, the UK, and France. The Asia-Pacific region, including China, India, and Japan, is experiencing rapid growth due to industrialisation and increasing environmental concerns. In the rest of the world, including Latin America, the Middle East, and Africa, the market is expanding steadily, with a focus on water treatment and air purification. Key players driving the global market include DuPont, BASF, Dow, Arkema S.A., Graphenea, and Sigma-Aldrich, leveraging technological advancements and sustainability-focused innovations to maintain their competitive edge across regions.
Market Insights
- The advanced nanomaterials market for environmental detection and remediation is projected to grow from USD 1,925 million in 2024 to USD 6,054 million by 2032, with a CAGR of 15.4%.
- Growing environmental concerns and stricter regulations are driving the demand for nanomaterials, offering enhanced sensitivity in detecting pollutants like heavy metals and organic compounds.
- Multifunctional nanomaterials that combine detection and remediation in a single step are key trends, along with advancements in nanocatalysts for air and water purification.
- Integration of nanotechnology with AI and machine learning for real-time environmental monitoring is gaining traction, improving the precision of detection and remediation processes.
- The push for clean energy sources and carbon reduction initiatives supports the adoption of nanomaterials for reducing emissions and improving industrial waste management.
- North America leads the market, holding a 35% share in 2024, followed by Europe at 28%, and Asia-Pacific, experiencing rapid growth, holds a 25% market share.
- Leading players include DuPont, BASF, Dow, Arkema S.A., and Graphenea, focusing on technological advancements and sustainability-driven innovations.
Market Drivers
Growing Environmental Regulations and Awareness
The increasing global focus on environmental protection and stricter regulations on pollution control are key drivers for the advanced nanomaterials market in environmental detection and remediation. Governments and regulatory bodies worldwide are imposing stringent standards on industries to limit emissions and manage waste effectively. For instance, the European Union's REACH regulation requires industries to manage and reduce chemical risks, driving demand for advanced detection technologies. This has led to a rising demand for technologies capable of detecting and removing harmful pollutants, such as heavy metals, organic compounds, and microplastics, from air, water, and soil. Advanced nanomaterials, with their superior capabilities, are well-positioned to meet these regulatory requirements.
Technological Advancements in Nanomaterials
Ongoing innovations in nanotechnology are significantly driving market growth. The unique properties of nanomaterials, such as high surface area, enhanced reactivity, and multifunctionality, make them ideal for detecting and neutralising environmental contaminants. For instance, nano-catalysts developed by BASF are improving the efficiency and effectiveness of environmental remediation efforts. Recent developments in nano-catalysts, sensors, and filtration systems have improved the efficiency and effectiveness of environmental remediation efforts. The ability to customise nanomaterials for specific applications, such as targeted pollutant removal or real-time environmental monitoring, further expands their use in this sector.
Increasing Demand for Sustainable Solutions
As industries and consumers place greater emphasis on sustainability, the demand for eco-friendly technologies has surged. Advanced nanomaterials offer environmentally friendly solutions for detecting and remediating pollutants, reducing the environmental impact of industrial processes. For instance, nanomaterials used by Veolia in wastewater treatment are helping to minimise pollution while promoting sustainable resource management. The growing adoption of green technologies in industries such as energy, agriculture, and manufacturing further fuels the demand for nanomaterials.
Integration of AI and Machine Learning
The integration of artificial intelligence (AI) and machine learning (ML) into environmental monitoring systems using nanomaterials is another key market driver. AI and ML enhance the precision of detection and remediation by analysing large datasets and predicting environmental changes in real time. For instance, IBM's AI-driven environmental monitoring solutions are making use of advanced nanomaterials to improve detection accuracy. This integration enables more efficient and cost-effective solutions, making advanced nanomaterials a critical tool in environmental management.
Market Trends
Development of Multifunctional Nanomaterials
A key trend in the advanced nanomaterials market for environmental detection and remediation is the development of multifunctional materials. These nanomaterials are designed to perform both detection and remediation simultaneously, offering a more efficient solution to environmental pollution. By combining multiple functionalities, such as sensing, catalysis, and pollutant degradation, these materials enable real-time monitoring and immediate action on contaminants. For instance, DuPont is developing multifunctional nanomaterials that can detect and degrade pollutants in water treatment systems. This trend is especially relevant in industries where continuous pollutant monitoring is required, such as water treatment and air purification.
Advancements in Nano-Catalysts
Another significant trend is the advancement of nano-catalysts used for environmental remediation. Nano-catalysts have shown remarkable potential in breaking down toxic substances and converting them into less harmful forms. Recent research has focused on improving the catalytic efficiency of nanomaterials, making them more effective in removing pollutants from industrial waste, water, and air. For instance, BASF is working on advanced nano-catalysts that address pressing environmental challenges, including the degradation of persistent organic pollutants and industrial chemicals. These advancements in nano-catalysts are playing a crucial role in addressing pressing environmental challenges.
Integration with Smart Technologies
The integration of advanced nanomaterials with smart technologies, such as artificial intelligence (AI) and the Internet of Things (IoT), is another emerging trend. Smart sensors made from nanomaterials are being developed to detect contaminants with high sensitivity and accuracy. For instance, IBM is pairing AI and IoT with nanomaterial-based sensors to provide real-time data on pollutant levels, enabling quicker decision-making and more proactive environmental management. This integration enhances the overall effectiveness of environmental monitoring systems.
Focus on Sustainable Nanomaterials
Sustainability is a growing focus in the development of nanomaterials for environmental applications. Researchers and companies are increasingly prioritising the use of biodegradable and non-toxic nanomaterials to minimise their ecological impact. For instance, NatureWorks is developing biodegradable nanomaterials for environmental remediation. This trend aligns with the broader shift towards sustainable technologies and the circular economy, ensuring that the solutions used for remediation do not contribute to further environmental harm.
Market Challenges Analysis
High Costs of Nanomaterial Production
One of the primary challenges facing the advanced nanomaterials market for environmental detection and remediation is the high cost of production. The synthesis of nanomaterials, especially those that require precise control over size, shape, and surface properties, can be expensive. The costs associated with raw materials, manufacturing technologies, and energy consumption make it difficult for companies to scale up production while maintaining affordability. Furthermore, certain nanomaterials, such as those involving precious metals or complex fabrication processes, remain cost-prohibitive for widespread adoption, particularly in developing regions. This challenge is further exacerbated by the need for specialised equipment and highly skilled personnel to manage the production and deployment of nanomaterials in environmental applications. The high costs associated with nanomaterial production also limit their commercialisation and hinder their large-scale use in industries like water treatment, air purification, and soil remediation. While ongoing research is focused on finding cost-effective alternatives and more efficient synthesis methods, the economic barrier remains a significant hurdle in realising the full potential of advanced nanomaterials for environmental detection and remediation.
Environmental and Health Concerns
While advanced nanomaterials offer significant potential for environmental remediation, concerns surrounding their environmental and health impacts present another major challenge. Nanoparticles, due to their small size and reactivity, can pose risks to ecosystems and human health if not carefully managed. The potential toxicity of certain nanomaterials, particularly metal-based nanoparticles, raises concerns about their release into the environment during production, use, or disposal. This challenge necessitates stringent regulatory oversight and comprehensive safety assessments to ensure that nanomaterials used for environmental remediation do not contribute to new forms of pollution or harm. The lack of long-term studies on the effects of nanomaterials in natural environments further complicates their widespread adoption. Regulatory frameworks governing the safe use of nanomaterials are still evolving, and companies must navigate these uncertainties while addressing potential risks to public health and the environment.
Market Opportunities
The advanced nanomaterials market for environmental detection and remediation presents significant growth opportunities driven by the increasing demand for efficient pollution control solutions across various industries. As global environmental regulations tighten and public awareness of pollution-related health risks rises, industries are seeking advanced technologies that offer superior performance in detecting and eliminating contaminants. Nanomaterials, with their high surface area, enhanced reactivity, and tunable properties, provide a promising solution for addressing complex environmental challenges. Industries such as water treatment, air purification, and soil remediation can benefit from the enhanced sensitivity and efficacy of nanomaterials, opening opportunities for new product development and commercialisation in these sectors.
Additionally, the growing focus on sustainability and green technologies offers another opportunity for the application of advanced nanomaterials in environmental remediation. The development of eco-friendly nanomaterials, including biodegradable or non-toxic alternatives, aligns with the broader market trend towards reducing environmental impact. This focus on sustainability encourages innovation in the nanotechnology space, particularly in developing next-generation materials that offer minimal ecological footprints while ensuring high remediation efficiency. Furthermore, the integration of nanomaterials with smart technologies, such as AI-driven monitoring systems and IoT-enabled sensors, enhances the potential for real-time environmental monitoring and targeted remediation. These advancements create new avenues for growth, particularly in sectors aiming to meet sustainability goals and reduce pollution in a cost-effective manner.
Market Segmentation Analysis:
By Type
The advanced nanomaterials market for environmental detection and remediation can be segmented by type into nanoparticles, nanotubes, nanofibers, and nanocomposites. Nanoparticles, particularly metal-based and carbon-based variants, dominate due to their high reactivity and surface area. These materials are widely utilised for detecting and neutralising pollutants in water, air, and soil.
By Medium
Segmentation by medium includes air, water, and soil. The water segment holds the largest share due to the critical need for clean water and the growing application of nanomaterials in wastewater treatment. Nanomaterials are increasingly employed for removing heavy metals, organic pollutants, and other contaminants from water, driving demand in this segment.
By Application
By application, the market is divided into water treatment, air purification, soil remediation, and industrial wastewater treatment. Water treatment leads the market as industries and municipalities invest in advanced nanomaterials for efficient purification processes. Air purification is also gaining momentum, especially in urban areas, where pollution control is critical.
Segments:
Based on Type:
- Metal-based
- Carbon-based
- Silica-based
- Polymer-based
Based on Medium
- Air
- Soil
- Water
Based on Application
- Wastewater & Industrial Effluent Treatment
- Environmental Monitoring
- Soil & Land Management
- Sustainable Agriculture
- Energy Storage
- Other
Based on End-User Industry
- Pharmaceuticals
- Chemicals
- Agriculture
- Construction
- Others
Based on the geography:
- North America
- S.
- Canada
- Mexico
- Europe
- Germany
- France
- K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the advanced nanomaterials market for environmental detection and remediation, with an estimated market share of 35% in 2024. The region's market is driven by stringent environmental regulations, particularly in the United States, where the Environmental Protection Agency (EPA) enforces strict pollution control standards. Additionally, the growing focus on sustainability and the presence of leading nanotechnology companies in the U.S. and Canada contribute to market growth. North America is also seeing increased investment in research and development (R&D) initiatives aimed at enhancing nanomaterial applications in pollution control and environmental monitoring.
Europe
Europe is another key market, accounting for 28% of the global market share in 2024. The European Union's (EU) Green Deal and strict regulatory framework around environmental protection have been major drivers for the adoption of nanomaterials in the region. Countries like Germany, the United Kingdom, and France are leading the way in the application of nanotechnology for air, water, and soil remediation. The EU's focus on sustainability, carbon reduction, and its Circular Economy Action Plan further supports the growth of advanced nanomaterials in environmental applications. Collaboration between industry players and academic institutions is also fostering innovation in the nanomaterials sector.
Asia-Pacific
The Asia-Pacific region is expected to witness the fastest growth in the advanced nanomaterials market, with a market share of 25% in 2024. Rapid industrialisation and urbanisation in countries like China, India, and Japan have increased pollution levels, driving the demand for effective remediation technologies. Governments in the region are increasingly focusing on addressing environmental issues, particularly in water and air purification. China is a major player in the nanomaterials market due to its large-scale industrial production of nanomaterials and strong government support for environmental sustainability. The region’s growing investment in nanotechnology research and the rising demand for cleaner industrial processes are expected to propel further growth.
Rest of the World
The rest of the world, including Latin America, the Middle East, and Africa, holds a smaller share of the market, estimated at 12% in 2024. However, the market in these regions is expected to grow steadily due to increasing environmental awareness and governmental initiatives aimed at pollution control. In Latin America, countries like Brazil and Mexico are adopting nanomaterials for water treatment and waste management. In the Middle East, the focus is on addressing water scarcity and improving air quality through advanced nanomaterials. Africa is also gradually investing in nanotechnology, particularly for water purification solutions in areas facing severe water contamination challenges.
Key Player Analysis
- Graphenea
- Aaxis Nano Technologies Pvt. Ltd.
- Carbotecnia
- DuPont
- QuantumSphere, Inc.
- Proventus Global
- Nenvitech
- Sigma-Aldrich
- Dow
- InMat Inc.
- Arkema S.A.
- BASF
Competitive Analysis
The competitive landscape of the advanced nanomaterials market for environmental detection and remediation is characterised by the presence of several leading players such as DuPont, BASF, Dow, Arkema S.A., and Sigma-Aldrich, who dominate the market through their strong product portfolios and extensive R&D capabilities. For instance, BASF is focused on developing innovative nanomaterials with enhanced properties for applications in water treatment, air purification, and soil remediation. Graphenea and QuantumSphere, Inc. are key players in graphene-based materials, while Aaxis Nano Technologies Pvt. Ltd. and InMat Inc. specialise in nanocomposites and advanced coatings for environmental applications. Carbotecnia and Proventus Global are notable for their contributions to adsorption technologies and environmental consultancy, respectively. The market is highly competitive, with companies vying to differentiate through technological advancements and sustainability-driven solutions, while also focusing on strategic partnerships and mergers to expand their reach. Additionally, increasing demand for eco-friendly nanomaterials is pushing companies to explore cost-effective and scalable production methods to stay competitive.
Recent Developments
- In March 2023, NanoXplore Inc., a graphene company, took full ownership of Voltaxplore by acquiring Martinrea International’s stake. Voltaxplore was originally a joint venture between NanoXplore and Martinrea, a global automotive supplier that specialises in the design, development, and production of advanced lightweight structures and propulsion systems.
- In May 2024, Claros Technologies and Kureha Corporation formed a strategic partnership to advance clean technology. This collaboration focuses on capturing, concentrating, and destroying harmful perfluoroalkyl and polyfluoroalkyl substances (PFAS) from wastewater.
- In June 2024, ARMO launched its ARMO Cloud Detection & Response solution, which offers comprehensive protection for workloads.
- In July 2023, EnviCore Inc. partnered with Eco-Agg Concrete Recycling Ltd. to revolutionise concrete waste management. Together, they are working to create low-carbon cementitious materials from recycled concrete, promoting sustainable construction practices.
Market Concentration & Characteristics
The advanced nanomaterials market for environmental detection and remediation is moderately concentrated, with a few key players holding significant market shares due to their strong technological capabilities and extensive R&D investments. Companies like DuPont, BASF, Dow, and Arkema S.A. lead the market, offering innovative nanomaterials tailored to environmental applications. Market concentration is driven by the need for specialised expertise in nanotechnology, as well as high production costs associated with developing advanced materials. This market is characterised by rapid technological advancements, with a focus on multifunctional nanomaterials that combine detection and remediation in a single solution. Additionally, growing demand for eco-friendly and sustainable technologies is shaping the competitive landscape, encouraging companies to focus on reducing industrial emissions and improving pollution control. While the market is competitive, the presence of well-established players with cutting-edge innovations makes entry challenging for smaller firms or new entrants.
Report Coverage
The research report offers an in-depth analysis based on type, medium, application, end-use industry, and geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, a SWOT analysis, and current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The advanced nanomaterials market for environmental detection and remediation is expected to witness strong growth, driven by increasing environmental regulations globally.
- Continuous advancements in nanotechnology will enhance the capabilities of nanomaterials in detecting and removing pollutants more efficiently.
- Integration of artificial intelligence (AI) and machine learning (ML) will further improve real-time monitoring and predictive capabilities in environmental applications.
- Growing demand for sustainable solutions will push industries to adopt nanomaterials for eco-friendly pollution control.
- The market will see increased adoption of multifunctional nanomaterials that combine detection and remediation in a single step.
- North America and Europe are expected to continue dominating the market due to stringent environmental policies and strong R&D investment.
- Asia-Pacific is likely to experience the fastest growth, driven by industrialisation and rising environmental concerns.
- Water treatment and air purification will remain key application areas for nanomaterials in the coming years.
- High production costs may continue to be a challenge, but efforts to lower costs and improve scalability are expected.
- The market will see increased collaboration between governments, industries, and academic institutions to develop advanced environmental solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Environmental Regulations and Awareness
Stricter global regulations on pollution control and heightened public awareness are compelling industries to adopt advanced nanomaterials for more effective detection and remediation of environmental contaminants, ensuring compliance and reducing ecological impact.
Technological Advancements in Nanomaterials
Continuous innovation in nanotechnology is enhancing the sensitivity, selectivity, and multifunctionality of nanomaterials, making them more effective for detecting and neutralizing a wide range of pollutants in air, water, and soil.
Increasing Demand for Sustainable Solutions
Industries and governments are prioritizing eco-friendly and sustainable technologies, driving the adoption of advanced nanomaterials that offer efficient pollutant removal with minimal environmental footprint, especially in water and air purification.
Integration of AI and Machine Learning
The combination of nanomaterials with AI and machine learning is enabling real-time environmental monitoring and predictive analytics, improving the precision and efficiency of detection and remediation processes.
Rising Industrialization and Urbanization in Emerging Markets
Rapid industrial growth and urban expansion in regions like Asia-Pacific are increasing pollution levels, creating a strong demand for advanced nanomaterials to address complex environmental challenges in these fast-developing areas.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Advanced Nanomaterials for Environmental Detection & Remediation market?
What factors are driving the growth of the Advanced Nanomaterials for Environmental Detection & Remediation market?
What are the key segments within the Advanced Nanomaterials for Environmental Detection & Remediation market?
Who are the major players in the Advanced Nanomaterials for Environmental Detection & Remediation market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Metal-based
- 1.2.2 Carbon-based
- 1.2.3 Silica-based
- 1.2.4 Polymer-based
- 1.3 By Medium
- 1.3.1 Air
- 1.3.2 Soil
- 1.3.3 Water
- 1.4 By Application
- 1.4.1 Wastewater & Industrial Effluent Treatment
- 1.4.2 Environmental Monitoring
- 1.4.3 Soil & Land Management
- 1.4.4 Sustainable Agriculture
- 1.4.5 Energy Storage
- 1.4.6 Other
- 1.5 By End-User Industry
- 1.5.1 Pharmaceuticals
- 1.5.2 Chemicals
- 1.5.3 Agriculture
- 1.5.4 Construction
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,925 million → 2032: USD 6,054 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Advanced Nanomaterials for Environmental Detection and Remediation Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Advanced Nanomaterials for Environmental Detection and Remediation Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Advanced Nanomaterials for Environmental Detection and Remediation Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Advanced Nanomaterials for Environmental Detection and Remediation Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Advanced Nanomaterials for Environmental Detection and Remediation Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Advanced Nanomaterials for Environmental Detection and Remediation Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Advanced Nanomaterials for Environmental Detection and Remediation Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Advanced Nanomaterials for Environmental Detection and Remediation Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,925 million → 2032: USD 6,054 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Advanced Nanomaterials for Environmental Detection and Remediation Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Metal-based
- 12.3.7.2 Carbon-based
- 12.3.7.3 Silica-based
- 12.3.7.4 Polymer-based
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Medium - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Air
- 12.4.7.2 Soil
- 12.4.7.3 Water
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Wastewater & Industrial Effluent Treatment
- 12.5.7.2 Environmental Monitoring
- 12.5.7.3 Soil & Land Management
- 12.5.7.4 Sustainable Agriculture
- 12.5.7.5 Energy Storage
- 12.5.7.6 Other
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Pharmaceuticals
- 12.6.7.2 Chemicals
- 12.6.7.3 Agriculture
- 12.6.7.4 Construction
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Advanced Nanomaterials for Environmental Detection and Remediation End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Advanced Nanomaterials for Environmental Detection and Remediation Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Advanced Nanomaterials for Environmental Detection and Remediation Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Advanced Nanomaterials for Environmental Detection and Remediation Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DuPont
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 BASF
- 18.4 Dow
- 18.5 Arkema S.A.
- 18.6 Sigma-Aldrich
- 18.7 Graphenea
- 18.8 QuantumSphere, Inc.
- 18.9 Aaxis Nano Technologies Pvt. Ltd.
- 18.10 InMat Inc.
- 18.11 Carbotecnia
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

