
Market Overview:
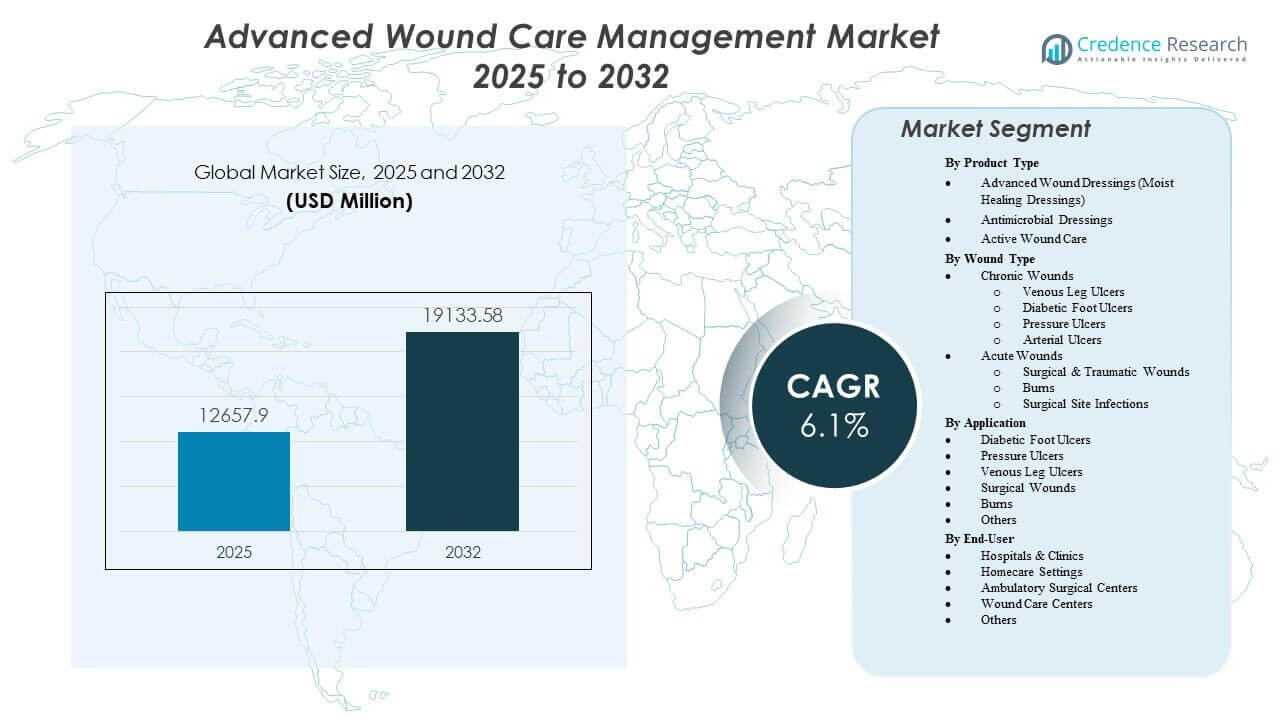
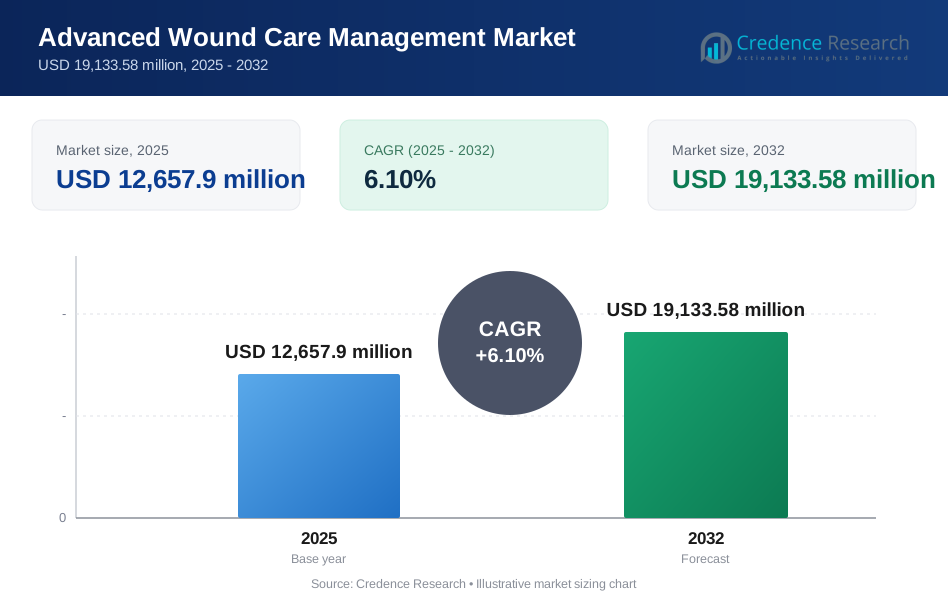
The Advanced Wound Care Management Market is projected to grow from USD 12,657.9 million in 2025 to an estimated USD 19,133.58 million by 2032, with a compound annual growth rate (CAGR) of 6.1% from 2025 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Advanced Wound Care Management Market Size 2025 | USD 12,657.9 million |
| Advanced Wound Care Management Market, CAGR | 6.1% |
| Advanced Wound Care Management Market Size 2032 | USD 19,133.58 million |
Market expansion is driven by increasing cases of diabetic foot ulcers, venous leg ulcers, and surgical wounds that require specialized treatment tools. Providers adopt advanced dressings to improve moisture balance and reduce healing delays. Demand rises for regenerative solutions such as biomaterials and skin substitutes that support tissue repair. Hospitals integrate NPWT platforms to manage complex wounds more efficiently. Homecare use grows with patients seeking easier long-term management. Innovation accelerates as companies design products that enhance comfort, infection control, and treatment consistency across care environments.
Regionally, North America leads due to strong clinical adoption, advanced healthcare systems, and wide availability of high-performance wound care solutions. Europe follows with structured reimbursement policies and rising demand from aging populations. Asia Pacific emerges as a fast-growing region driven by expanding hospital infrastructure and increasing chronic wound cases in China, India, and Southeast Asia. Latin America and the Middle East & Africa gain traction as healthcare investments rise and access to advanced treatment improves across public and private care networks.
Market Insights:
- The Advanced Wound Care Management Market is projected to grow from USD 12,657.9 million in 2025 to USD 19,133.58 million by 2032, supported by a 6.1% CAGR during the forecast period.
- Growing cases of diabetic foot ulcers, venous leg ulcers, pressure ulcers, and surgical wounds strengthen demand for advanced dressings, regenerative therapies, and NPWT systems.
- Market restraints include high treatment costs, limited access in low-income regions, and skill gaps among care teams that affect consistent wound management outcomes.
- North America holds the leading share due to advanced healthcare systems and high adoption rates, while Europe maintains steady demand driven by aging populations and clinical guidelines.
- Asia Pacific shows rapid expansion with rising chronic wound prevalence and improving healthcare infrastructure, supported by growing investments across China, India, and Southeast Asia.
Market Drivers
Rising Burden of Chronic Wounds and Growing Focus on Faster Healing Outcomes
The Advanced Wound Care Management Market gains strong momentum due to a rising number of chronic wounds linked to diabetes, vascular disorders, and pressure injuries. Healthcare systems demand products that support faster closure and stronger tissue recovery. Clinicians prefer solutions that reduce infection risk and improve long-term prognosis. Hospitals adopt smart dressings that stabilize moisture balance for better healing. Patients seek treatments that lower pain and limit frequent clinic visits. Providers support advanced therapies that cut repeated wound complications. Governments invest in better wound protocols to manage swelling healthcare loads. This trend strengthens uptake of evidence-backed solutions.
- For instance, Smith & Nephew’s PICO Single Use Negative Pressure Wound Therapy (sNPWT) has demonstrated its clinical efficacy by reducing wound area by 40% more than traditional dressings in venous leg ulcers over a 12-week period.
Increased Geriatric Population Driving Higher Adoption of Advanced Wound Solutions
Global aging trends support broad adoption because older adults face higher risk of skin breakdown and delayed recovery. Clinicians observe more non-healing ulcers that require specialized tools. Demand rises for dressings that maintain stable wound environments for fragile patients. Hospitals integrate advanced protocols that improve geriatric outcomes. Home care teams rely on user-friendly systems that simplify daily dressing changes. Family caregivers prefer products that limit odor and leakage. Manufacturers design solutions that reduce time-intensive wound routines. Providers align protocols with wider senior health needs.
Greater Emphasis on Minimizing Surgical Site Infections Across Care Settings
Surgical teams adopt advanced methods that stabilize post-operative wounds. Hospitals track infection indicators to reduce readmissions and penalties. Providers choose antimicrobial dressings that support early protection of incision sites. Research groups create barrier technologies that limit bacterial penetration. Surgeons encourage solutions that handle exudate without harming tissue. Patients follow guided wound care plans to prevent complications. Clinics train staff to use modern wound protocols. This approach supports safer recovery cycles.
Surge in Home Healthcare and Community Care Services Broadening Product Reach
More patients receive treatment in home or community settings where simple, reliable tools hold strong value. Clinicians adopt products that need less supervision. Telehealth platforms guide dressing adjustments for chronic users. Home caregivers rely on odor-control features that support daily comfort. Manufacturers develop secure adhesive systems that suit active lifestyles. Providers focus on devices that reduce dressing failures. Demand strengthens for pack sizes designed for regular home use. This shift expands reach across broader patient groups.
- For instance, ConvaTec’s AQUACEL Ag+ Extra dressings are engineered to disrupt biofilm and kill bacteria, maintaining effectiveness for up to 7 days, which reduces the required frequency of home nursing visits by approximately 33% for patients with chronic wounds.
Market Trends
Growing Role of Digital Wound Monitoring and Remote Assessment Platforms
The Advanced Wound Care Management Market sees rising use of digital tools that support image capture, size tracking, and automated assessments. Providers rely on platforms that guide more timely decisions. Remote teams monitor high-risk patients to prevent complications. Mobile devices capture wound changes that support clinical reviews. AI tools help standardize progress scoring. Clinics reduce staff burden through automated documentation. Patients gain confidence through continuous updates. This trend supports data-driven wound care.
Expansion of Bioactive and Regenerative Wound Therapies Across Clinical Uses
Bioactive dressings gain momentum due to improved tissue support. Clinicians use collagen, hydrogel, and matrix-based products for hard-to-heal wounds. Research groups explore regenerative materials that support cell growth. Hospitals introduce advanced solutions for pressure injuries and diabetic ulcers. Patients benefit from softer textures that reduce skin stress. Providers select bioactive options for wounds that resist closure. Demand grows for therapies that shorten healing cycles. Regenerative tools gain visibility in global guidelines.
Rising Preference for Eco-Friendly and Skin-Friendly Wound Care Materials
Sustainability influences product design across many regions. Manufacturers test biodegradable films and gentler adhesives for sensitive skin. Clinics adopt latex-free and chemical-reduced alternatives. Patients prefer materials that limit redness and irritation. Home caregivers rely on breathable layers that improve comfort. Providers look for packaging with lower environmental impact. Research groups evaluate plant-derived polymers for new dressings. These choices shape future product offerings.
- For instance, Advancis Medical has integrated Manuka honey into its Eclypse Adherent dressings, utilizing medical-grade honey that maintains a low pH of 3.2 to 4.5, which inhibits bacterial growth while remaining 100% free of synthetic preservatives.
Shift Toward Customized Wound Care Protocols Driven by Patient-Specific Needs
Personalized care gains attention due to wide variation in wound types. Providers tailor protocols based on exudate levels, skin condition, and mobility status. Clinics combine multiple technologies to reach targeted outcomes. Older adults receive cushioning solutions to reduce tissue strain. Active patients use flexible dressings that support movement. Surgeons match incision needs with specialized barriers. Data insights refine decisions over time. This trend fuels more precise wound management.
- For instance, Smith & Nephew’s ALLEVYN Life dressings feature a unique five-layer design specifically engineered for varied exudate management, which has been shown in clinical evaluations to increase dressing wear time to an average of 4.4 days, significantly reducing the frequency of changes compared to standard foam dressings.
Market Challenges Analysis
High Treatment Costs and Limited Access to Advanced Wound Technologies Across Regions
The Advanced Wound Care Management Market faces pressure from high product costs that strain budgets in many settings. Rural hospitals struggle to adopt premium dressings. Patients avoid long-term care due to recurring expenses. Clinics limit use of advanced options when reimbursement gaps appear. Providers face difficulty explaining cost benefits to smaller facilities. Home users find premium packs difficult to afford. Research groups highlight access gaps across low-income regions. This keeps disparities in adoption patterns.
Complex Wound Cases and Skill Gaps Among Care Teams Impacting Treatment Outcomes
Care teams face diverse wounds that respond differently to each protocol. Hospitals struggle when staff lack training in modern dressing use. Incorrect applications slow healing progress. Patients face longer recovery paths when wounds fail early stabilization. Clinics lack structured assessment tools for complex ulcers. Recordkeeping gaps reduce consistent monitoring. Providers work to update skills through fresher training content. This challenge slows uniform adoption of advanced tools.
Market Opportunities
Expanding Use of Smart Wound Technologies and Connected Care Tools
The Advanced Wound Care Management Market holds strong opportunities through sensors, moisture trackers, and AI-enhanced platforms. Clinics reduce manual checks through continuous updates. Patients gain safer healing paths with early alerts. Remote teams support rural cases through guided steps. Hospitals adopt automated measurement tools that strengthen accuracy. Manufacturers design dressings with embedded indicators. Providers align protocols with digital workflows. Growth strengthens through rising telehealth use.
Wider Growth Potential Across Emerging Markets with Rising Healthcare Investments
Emerging economies support adoption due to improving hospital budgets. Governments expand wound care programs to reduce long-term disabilities. Clinics adopt modern dressings for diabetic and vascular patients. Patients gain access through new reimbursement schemes. Providers train staff in structured wound protocols. Manufacturers expand distribution in fast-growing regions. Home care teams use easy-apply products to support wider populations. Investments drive future expansion.
Market Segmentation Analysis:
By Product Type
The Advanced Wound Care Management Market shows strong traction across advanced wound dressings due to broad use in chronic and acute wound cases. Foam, hydrocolloid, hydrogel, film, alginate, collagen, and composite dressings support moisture balance and faster tissue recovery. Demand grows for antimicrobial dressings where silver and non-silver options support infection control needs. Active wound care expands through growth factors, biomaterials, skin substitutes, and dermal replacements that support regenerative healing. Hospitals increase adoption of NPWT and bioengineered products for complex wounds. Manufacturers focus on improved exudate handling and stronger antimicrobial actions to support clinical performance. Product diversification continues to shape competitive positioning.
By Wound Type
Chronic wounds hold a significant share of the Advanced Wound Care Management Market due to rising diabetic foot ulcers, venous leg ulcers, pressure ulcers, and arterial ulcers. Providers adopt advanced dressings and bioactive therapies to reduce recurrence and shorten healing cycles. Acute wounds create steady demand through surgical cases, trauma injuries, burns, and surgical site infections. Hospitals rely on advanced solutions that stabilize wound environments and reduce infection risk. Surgeons use film dressings and protective barriers for incision care. Burn units integrate hydrogels and skin substitutes to support tissue repair. It continues to see rising demand across both chronic and acute categories.
- For instance, Integra LifeSciences’ Integra Bilayer Wound Matrix has demonstrated clinical success in reconstructive surgery and burns, where it has been shown to achieve 96% wound closure in complex, full-thickness wounds that failed to respond to conventional treatments.
By Application
Diabetic foot ulcers lead the Advanced Wound Care Management Market due to high case volumes in hospital and homecare settings. Pressure ulcers and venous leg ulcers maintain strong use of moisture-balancing and antimicrobial dressings. Surgical wounds create consistent demand for post-operative protection and early wound stabilization. Burns require specialized hydrogels, skin substitutes, and bioactive solutions that support regeneration. The application segment grows with rising focus on personalized wound care pathways. Providers align treatment tools with specific wound profiles. It strengthens clinical outcomes through targeted application strategies.
- For instance, Coloplast’s Biatain Silicone Ag dressing, when applied to diabetic foot ulcers, has been clinically proven to reduce wound size by 75% within 4 weeks of treatment by effectively managing exudate and sustained silver release.
By End-User
Hospitals and clinics dominate the Advanced Wound Care Management Market due to strong use of advanced dressings, bioactive therapies, and wound therapy devices. Homecare settings expand with rising preference for user-friendly dressings that support long-term wound maintenance. Ambulatory surgical centers adopt products that reduce post-surgical complications. Wound care centers gain attention for specialized treatment protocols that integrate NPWT and regenerative tools. Other facilities increase structured care programs for chronic and post-operative wounds. Providers emphasize cost-effective and outcome-driven product selections. It strengthens adoption across diversified care environments.
Segmentation:
By Product Type
By Advanced Wound Dressings (Moist Healing Dressings)
- Foam Dressings
- Hydrocolloid Dressings
- Film Dressings
- Alginate Dressings
- Hydrogel Dressings
- Collagen Dressings
- Other Advanced Dressings (superabsorbent, composite, contact layers)
By Antimicrobial Dressings
- Silver Dressings
- Non-silver Antimicrobial Dressings (PHMB, iodine, medical honey, etc.)
By Active Wound Care
- Growth Factors
- Biomaterials
- Skin Substitutes
- Dermal Replacement Products
By Wound Type
- Chronic Wounds
- Venous Leg Ulcers
- Diabetic Foot Ulcers
- Pressure Ulcers
- Arterial Ulcers
- Acute Wounds
- Surgical & Traumatic Wounds
- Burns
- Surgical Site Infections
By Application
- Diabetic Foot Ulcers
- Pressure Ulcers
- Venous Leg Ulcers
- Surgical Wounds
- Burns
- Others
By End-User
- Hospitals & Clinics
- Homecare Settings
- Ambulatory Surgical Centers
- Wound Care Centers
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America holds the largest share of the Advanced Wound Care Management Market, representing nearly 40% of global revenue due to strong adoption of advanced dressings and therapy devices. The region benefits from high chronic wound prevalence linked to diabetes and obesity. Hospitals invest in premium wound healing systems to support better patient outcomes. Manufacturers expand local portfolios to meet strong demand for bioactive and antimicrobial products. Homecare growth strengthens distribution networks across urban and rural areas. The presence of major players keeps innovation cycles active and competitive.
Europe accounts for roughly 30% market share and maintains steady demand driven by aging populations and structured reimbursement policies. Clinics apply strict treatment protocols that increase the use of moist-healing and regenerative solutions. Providers focus on reducing hospital stays through early adoption of advanced dressings. Research institutions support product development through clinical evidence. Governments promote standards that raise patient safety and enable quicker adoption of new solutions. The region sees stable expansion across Germany, the UK, France, and the Nordic countries.
Asia Pacific captures close to 20% of global share and grows faster than mature regions due to expanding healthcare infrastructure. The Advanced Wound Care Management Market gains traction across China, India, Japan, and South Korea where chronic wound cases rise sharply. Hospitals upgrade wound units to integrate NPWT and engineered tissue substitutes. Governments increase spending to improve access in public healthcare settings. Local manufacturers expand production to meet rising volume needs. It continues to see strong interest from international players establishing regional distribution networks.
Key Player Analysis:
- Smith & Nephew plc
- Mölnlycke Health Care AB
- ConvaTec Group plc
- Solventum
- Coloplast A/S
- Integra LifeSciences
- Medtronic plc
- Braun Melsungen AG
- Cardinal Health, Inc.
- Organogenesis Inc.
Competitive Analysis:
The Advanced Wound Care Management Market features strong competition driven by innovation, clinical evidence, and expanding product portfolios. Companies strengthen their positions through advanced dressings, bioengineered tissues, and NPWT platforms. Firms invest in R&D to improve moisture balance, antimicrobial protection, and regenerative outcomes. Major players expand global reach through partnerships with hospitals and distributors. Pricing strategies reflect growing pressure across low-income regions where access gaps remain. Competitors focus on regulatory alignment to accelerate product approvals and broaden their wound care offerings. It moves toward consolidation as large companies acquire smaller firms with specialized technologies, strengthening market coverage across all major regions.
Recent Developments:
- In January 2026, Tiger BioSciences acquired advanced wound care technology focused on platelet-rich fibrin matrix (PRFM) and dressings. This acquisition broadens their regenerative medicine offerings across various care sites.
- In December 2025, New Horizon Medical Solutions acquired the business assets of Applied Tissue Technologies, a 25-year-old wound care innovator based in Boston, Massachusetts. This move strengthens NHMS's portfolio with cutting-edge products aimed at enhancing wound management outcomes.
- In November 2025, Solventum announced an agreement to acquire Acera Surgical, entering the synthetic tissue matrices space for regenerative wound care. The deal leverages Solventum's expertise in advanced wound care and negative pressure therapy.
- In September 2025, Smith & Nephew plc launched the CENTRIO Platelet-Rich-Plasma (PRP) System, a biodynamic hematogel for advanced wound care. In this US market introduction, the company entered an exclusive private label distribution agreement with Nuo Therapeutics Inc. to enhance its Advanced Wound Bioactives portfolio, supporting chronic wound healing through patient-derived platelets and plasma.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Wound Type, Application, End-User, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Advanced Wound Care Management Market will see strong adoption of digital wound monitoring tools that support faster decision-making across clinical and homecare settings.
- Demand for bioactive and regenerative solutions will increase as providers focus on therapies that accelerate healing and reduce complication risks.
- Antimicrobial dressings will gain traction due to infection control needs across chronic and surgical wounds in high-volume healthcare systems.
- Wound therapy devices such as NPWT will expand in emerging regions where hospitals upgrade infrastructure and treatment protocols.
- Home-based wound care will grow rapidly as patients seek convenient, low-supervision solutions that align with long-term care plans.
- R&D investment will rise to support advanced materials that improve moisture balance, adhesion strength, and tissue repair.
- Market consolidation will intensify as major players acquire specialized firms to broaden product portfolios.
- Reimbursement improvements will support wider adoption of premium products across aging populations.
- Sustainability initiatives will encourage development of eco-friendly dressings with safer materials.
- Regional expansion will accelerate with global firms strengthening distribution in Asia Pacific, Latin America, and MEA.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Burden of Chronic Wounds and Focus on Faster Healing
Increasing prevalence of diabetes, vascular disorders, and pressure injuries is leading to more chronic wounds that require advanced wound care solutions. Healthcare providers and patients are seeking products that accelerate healing, reduce infection risk, and improve long-term outcomes.
Aging Population Increasing Demand for Advanced Solutions
The global rise in the geriatric population is driving higher adoption of advanced wound care products, as older adults are more susceptible to skin breakdown and delayed wound healing. This demographic trend is boosting demand for specialized dressings and regenerative therapies.
Emphasis on Minimizing Surgical Site Infections
Hospitals and surgical centers are prioritizing infection control, leading to increased use of antimicrobial dressings and advanced wound management protocols. This focus helps reduce readmissions and complications, supporting market growth.
Expansion of Home Healthcare and Community Care
The shift toward home-based and community care is broadening the reach of advanced wound care products. Patients and caregivers prefer user-friendly, long-wear dressings that reduce the need for frequent clinic visits, driving demand for innovative solutions.
Technological Innovation and Digital Wound Monitoring
Advancements in digital wound monitoring, bioactive materials, and smart dressings are enhancing clinical outcomes and enabling more precise, data-driven wound management. These innovations are accelerating adoption across both hospital and homecare settings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Advanced Wound Care Management Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Advanced Wound Care Management Market projected to grow between 2025 and 2032?
Which Advanced Wound Care Management Market segment held the largest share in 2025?
What are the primary factors fueling the growth of the Advanced Wound Care Management Market?
Who are the leading companies in the Advanced Wound Care Management Market?
Which region commanded the largest share of the Advanced Wound Care Management Market in 2025?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Hospitals & Clinics
- 1.2.2 Homecare Settings
- 1.2.3 Ambulatory Surgical Centers
- 1.2.4 Wound Care Centers
- 1.3 By Wound Type
- 1.3.1 Chronic Wounds
- 1.3.2 Acute Wounds
- 1.3.3 Surgical Site Infections
- 1.4 By Application
- 1.4.1 Diabetic Foot Ulcers
- 1.4.2 Pressure Ulcers
- 1.4.3 Venous Leg Ulcers
- 1.4.4 Surgical Wounds
- 1.4.5 Burns
- 1.5 By Product Type
- 1.5.1 Foam Dressings
- 1.5.2 Hydrocolloid Dressings
- 1.5.3 Film Dressings
- 1.5.4 Alginate Dressings
- 1.5.5 Hydrogel Dressings
- 1.5.6 Antimicrobial Dressings
- 1.5.7 Active Wound Care (Growth Factors, Biomaterials, Skin Substitutes)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 12,657.9 million → 2032: USD 19,133.58 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Advanced Wound Care Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Advanced Wound Care Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Advanced Wound Care Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Advanced Wound Care Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Advanced Wound Care Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Advanced Wound Care Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Advanced Wound Care Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Advanced Wound Care Management Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 12,657.9 million → 2032: USD 19,133.58 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Advanced Wound Care Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals & Clinics
- 12.3.7.2 Homecare Settings
- 12.3.7.3 Ambulatory Surgical Centers
- 12.3.7.4 Wound Care Centers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Wound Type - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Chronic Wounds
- 12.4.7.2 Acute Wounds
- 12.4.7.3 Surgical Site Infections
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Diabetic Foot Ulcers
- 12.5.7.2 Pressure Ulcers
- 12.5.7.3 Venous Leg Ulcers
- 12.5.7.4 Surgical Wounds
- 12.5.7.5 Burns
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Type - Market Size and Forecast, 2025-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2025-2032
- 12.6.4 Volume Forecast, 2025-2032
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Foam Dressings
- 12.6.7.2 Hydrocolloid Dressings
- 12.6.7.3 Film Dressings
- 12.6.7.4 Alginate Dressings
- 12.6.7.5 Hydrogel Dressings
- 12.6.7.6 Antimicrobial Dressings
- 12.6.7.7 Active Wound Care (Growth Factors, Biomaterials, Skin Substitutes)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Advanced Wound Care Management End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Advanced Wound Care Management Geographic Market Outlook, 2025-2032
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Advanced Wound Care Management Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Advanced Wound Care Management Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Smith & Nephew plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mölnlycke Health Care AB
- 18.4 ConvaTec Group plc
- 18.5 Solventum
- 18.6 Coloplast A/S
- 18.7 Integra LifeSciences
- 18.8 Medtronic plc
- 18.9 B. Braun Melsungen AG
- 18.10 Cardinal Health, Inc.
- 18.11 Organogenesis Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

