
Market Overview
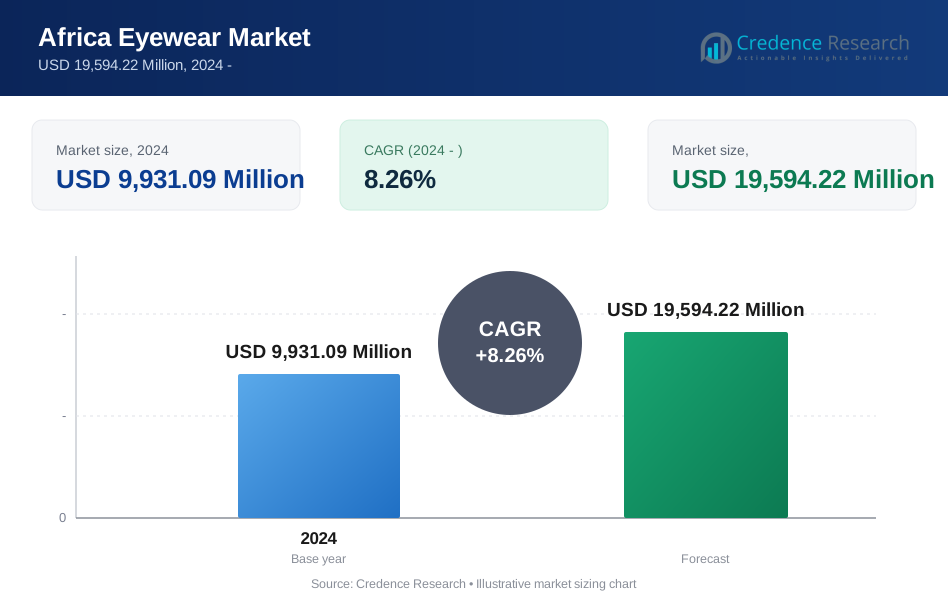
The Africa Eyewear Market is projected to grow from USD 9,931.09 Million in 2024 to an estimated USD 19,594.22 Million by 2032, with a CAGR of 8.26% from 2024 to 2032. Market expansion is driven by rising vision correction needs, growing awareness of eye health and broader access to affordable optical retail across urban and semi-urban centers.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period: | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Africa Eyewear Market Size 2024 | USD 9,931.09 Million |
| Africa Eyewear Market CAGR | 8.26% |
| Africa Eyewear Market Size 2032 | USD 19,594.22 Million |
Market Insights
- North Africa accounts for the largest share of the Africa eyewear market, driven by relatively advanced healthcare systems, higher urbanization, and stronger retail ecosystems in countries such as Egypt, Morocco, and Algeria.
- Prescription (RX) Glasses led the product segment in 2024 with an estimated 46.8% share, supported by rising diagnosis of refractive errors.
- Brick & Mortar remained the dominant distribution channel, reflecting strong consumer preference for in-store eye testing, fitting and frame selection.
- EssilorLuxottica, Bausch + Lomb Corporation, CooperVision Limited, Zeiss Group and Lapaire represent five major participants shaping competition across the market.
- Key market trend centers on affordable omnichannel retail, with brands combining low-cost prescription eyewear, digital ordering and localized optical services.

Market Segmentation Analysis
By product, prescription eyewear anchors core demand
On the basis of product, the market is classified into Contact Lenses, Prescription (RX) Glasses and Sunglasses. Prescription (RX) Glasses held the largest market share of 46.8% in 2024. This leadership reflects high unmet need for vision correction, increasing eye examinations and stronger consumer willingness to purchase functional eyewear before discretionary fashion products. Retail opticians and clinic-linked chains continue to expand RX frame assortments at entry and mid-tier prices. Key companies operating in this segment include EssilorLuxottica, Zeiss Group and Lapaire.
By price range, value-priced products capture mass-market spending
On the basis of price range, the market is classified into Upto USD 150, USD 151-300 and Above USD 300. Upto USD 150 accounted for the leading 58.4% share in 2024. The segment benefits from price-sensitive consumers, broad adoption of basic prescription glasses and rising penetration of affordable sunglasses in informal and organized retail channels. Local assembly, lower-cost frames and promotional bundle offers further support volume growth. Key companies operating in this segment include Waridi Eyewear, Wazi Vision and Lapaire.
By gender, female consumers generate slightly higher eyewear demand
On the basis of gender, the market is classified into Male and Female. Female held the largest market share of 52.6% in 2024. Demand remains strong because women buy eyewear for both vision correction and appearance, supporting repeat purchases across prescription and sun categories. Fashion-led frame choices, color variety and social media influence also strengthen replacement cycles in urban markets. Key companies operating in this segment include De Rigo Vision S.p.A., JINS Inc. and Titan Company Limited.
By distribution channel, physical retail sustains market leadership
On the basis of distribution channel, the market is classified into E-Commerce and Brick & Mortar. Brick & Mortar led with a 72.3% market share in 2024. Consumers continue to prefer stores for eye testing, lens fitting, frame trial and after-sales adjustments, especially in prescription purchases. Optical chains, pharmacies and independent stores remain important access points in markets where digital trust and logistics are still developing. Key companies operating in this segment include Lapaire, EssilorLuxottica and Fielmann AG.
Key Growth Drivers
Rising burden of refractive errors and preventable vision impairment
Growing prevalence of myopia, hyperopia, astigmatism and presbyopia continues to create fundamental demand for eyewear across Africa. Consumers increasingly seek prescription glasses as routine screening expands through hospitals, optical chains, mobile clinics and school-based outreach. Demand is also supported by aging populations in several African countries, where near-vision correction becomes more important for work and daily living. According to global public health estimates, at least 2.2 billion people live with near or distance vision impairment worldwide, and at least 1 billion of those cases could have been prevented or remain unaddressed. This large untreated pool supports sustained demand for low-cost vision correction. As awareness improves, eyewear purchases are shifting from occasional need-based transactions to repeat replacement cycles, particularly for basic RX glasses and sun protection products.
Expansion of affordable optical retail and organized distribution
Market growth is accelerating as organized eyewear retailers widen access to affordable products in large cities and secondary urban centers, where chains, clinic-linked outlets, and digitally enabled optical businesses are reducing long-standing barriers tied to high pricing, narrow assortment, and slow fulfillment for prescription eyewear.
Consumers increasingly benefit from broader access to eye tests, private-label frames, and bundled lens packages at clearer price points, which matters in African markets where value remains central to purchase decisions and standardized service models can improve trust, conversion, and repeat buying. Expansion is also being supported by better last-mile reach, localized merchandising, employer partnerships, and school screening efforts that help retailers connect first-time users with entry-level prescription glasses while gradually building a path toward premium upselling over time.
The commercial and public health need is substantial, with WHO Africa stating that about 26.3 million people in the region live with visual impairment, while Spec-Savers says it operates over 270 franchise outlets across South Africa, Namibia, Lesotho, and Botswana, showing how scale retail is improving affordable access.
Higher screen exposure and lifestyle-led demand for multiple eyewear types
Rising digital device usage is strengthening eyewear demand across Africa as office workers, students, and mobile-first consumers become more aware of eye strain, blue-light exposure, and the need for regular vision checks, which is increasing interest in prescription eyewear, plano blue-light lenses, and everyday sunglasses as practical products for both work and lifestyle use.
As screen exposure becomes more routine across urban and semi-urban populations, more consumers report visual discomfort that pushes them toward eye testing, corrective lenses, and replacement purchases, while sunglasses also benefit from higher outdoor mobility, stronger fashion consciousness, and wider awareness of UV protection in high-sunlight environments. This combination of functional and lifestyle demand is broadening category participation and encouraging multiple-pair ownership, which supports more frequent replacement cycles and higher annual spending per buyer across the region’s evolving optical retail landscape.
The digital backdrop is clear, as GSMA said Africa’s mobile internet usage gap still reached 64 percent in 2024 even after the coverage gap narrowed to 9 percent, while MTN reported 172 million data customers and broadband coverage of more than 94 percent of the population across its African markets in 2025, showing how deeper connectivity is reinforcing eyewear demand linked to daily screen use.
Key Trends & Opportunities
Trends
Affordable omnichannel optical retail gains traction
Eyewear brands in Africa are increasingly blending physical eye care services with digital discovery, online ordering and home delivery. This omnichannel model helps retailers acquire younger consumers while preserving in-store trust for exams, fittings and prescription fulfillment. It is particularly effective in major urban markets, where consumers compare prices online before visiting stores. Public company performance in global eyewear retail also supports the model, as leading players continue investing in digital storefronts, virtual try-on tools and integrated fulfillment to improve conversion and repeat purchases. In Africa, this trend is pushing retailers to simplify assortments, shorten turnaround times and promote transparent package pricing for frames and lenses.
Fashion utility convergence reshapes product demand
Consumers increasingly view eyewear as both a medical necessity and a personal style accessory. This shift is supporting stronger demand for lightweight frames, branded sunglasses and design-led prescription collections that balance value and appearance. Female buyers and younger urban consumers are driving demand for multiple frame styles, while male consumers increasingly adopt sunglasses and work-friendly RX products. Retailers are responding with color variety, slimmer frame shapes and entry premium collections. As a result, the market is becoming less transactional and more brand influenced, especially in cities with growing middle-income populations and stronger exposure to international fashion trends.
Opportunities
Untapped rural and secondary city vision care markets
Large underserved populations outside major cities represent one of the strongest long-term opportunities in the market. Many consumers in rural and peri-urban areas still face limited access to eye testing, qualified opticians and affordable prescription products. Companies that deploy mobile screening, community partnerships and low-cost fulfillment can unlock meaningful first-time buyer demand. Basic RX glasses, reading glasses and protective sunglasses are especially well positioned in these areas because they address practical, high-frequency use cases. Firms that localize distribution and maintain reliable replenishment can build durable brand recognition where formal optical infrastructure remains limited.
Localized sourcing and private-label development can widen margins
Market participants have room to improve profitability by expanding private-label portfolios, local assembly and region-specific frame design. Import dependence and currency volatility often raise final retail prices, which can weaken affordability in value-sensitive segments. Companies that shorten supply chains, source regionally where feasible and optimize lens finishing closer to demand centers can reduce lead times and improve pricing flexibility. This approach also supports faster replenishment of high-volume SKUs in the Upto USD 150 segment. Over time, localized product strategies can help brands serve mass-market demand more effectively while still preserving selective premium positioning in urban stores and online channels.
Key Challenges
Challenges-
Affordability constraints and fragmented access limit conversion
Affordability remains a core challenge across the Africa Eyewear Market because many consumers prioritize immediate household needs over preventive eye care purchases. Even when vision issues are recognized, spending on eye exams and prescription eyewear may be delayed. Market fragmentation also creates uneven access, with modern optical retail concentrated in major cities while rural areas depend on informal channels or limited clinical supply. This environment constrains diagnosis rates, slows replacement cycles and supports continued reliance on low-cost unbranded products that pressure formal sector margins.
Import dependence and supply chain volatility pressure pricing
Many market participants remain dependent on imported frames, lenses and lens-processing inputs, making pricing vulnerable to currency movements, shipping costs and customs delays. These pressures can narrow retailer margins or force higher end-user prices, especially in entry and mid-tier segments. Long lead times also complicate inventory planning, causing stockouts in fast-moving SKUs and weaker fulfillment for prescription orders. For online sellers, logistics reliability and returns management add another layer of complexity. Together, these issues challenge service consistency and slow broader market formalization.
Regional Analysis
North Africa – 27.8%
North Africa accounts for the largest share of the Africa eyewear market, driven by relatively advanced healthcare systems, higher urbanization, and stronger retail ecosystems in countries such as Egypt, Morocco, and Algeria. The region benefits from growing awareness of vision correction, rising adoption of prescription spectacles, and expanding availability of branded sunglasses. Urban consumers increasingly prefer fashion-oriented eyewear, while pharmacies and optical chains play a key role in distribution. Demand is also supported by improving disposable income levels and proximity to European supply chains, which enhances product availability and variety.
South Africa – 24.3%
South Africa represents a major share due to its well-developed optical retail network, strong presence of organized eyewear chains, and higher consumer purchasing power compared to most African countries. The market is characterized by rising demand for both prescription eyewear and fashion frames, supported by increasing eye health awareness and urban lifestyles. The growth of e-commerce and omnichannel retail further strengthens accessibility. South Africa also acts as a regional hub for eyewear distribution across Southern Africa, reinforcing its dominant position within the continent.
West Africa – 18.6%
West Africa holds a significant share, primarily driven by populous countries such as Nigeria and Ghana. The region’s growth is volume-driven, supported by increasing cases of vision impairment and rising demand for affordable eyewear products. However, the market remains largely fragmented, with a strong presence of informal optical retailers and limited penetration of premium brands. Urban centers are witnessing gradual expansion of modern optical stores, while low-cost imports dominate the mass segment. Awareness campaigns and NGO-led eye care initiatives are also contributing to gradual market development.
East Africa – 15.4%
East Africa is an emerging market supported by improving healthcare access and expanding urban populations in countries such as Kenya, Ethiopia, and Tanzania. The region is witnessing steady adoption of prescription eyewear due to increasing diagnosis of vision disorders and growing access to optometry services. Retail infrastructure is developing, with a mix of independent optical stores and international players entering key cities. Demand remains largely price-sensitive, with mid-range and affordable eyewear products dominating the market. Government and non-profit vision care programs continue to play a role in expanding access in rural areas.
Central Africa – 13.9%
Central Africa accounts for the smallest share of the Africa eyewear market due to relatively limited healthcare infrastructure, lower consumer purchasing power, and underdeveloped retail networks. Countries in this region rely heavily on imports, and access to optical services is concentrated in urban areas. The market is primarily driven by basic prescription eyewear demand rather than fashion or premium segments. However, gradual improvements in healthcare systems and increasing NGO involvement in vision care are expected to support incremental growth over time.
Market Segmentations
- Product
- Contact Lenses
- Prescription (RX) Glasses
- Sunglasses
- Price Range
- Up to USD 150
- USD 151-300
- Above USD 300
- Gender
- Male
- Female
- Distribution Channel
- E-Commerce
- Brick & Mortar
Competitive Landscape
The Africa Eyewear Market features a mix of global optical majors, lens specialists and region-focused retailers competing on affordability, access and service quality. Leading players prioritize innovation in lens performance, lightweight materials and digital retail tools, while local and regional brands focus on value-priced assortments and community-based eye care delivery. Product strategies center on broad prescription portfolios, entry-level frames and selective premium collections in urban markets.
Distribution remains a key differentiator, with companies expanding clinic partnerships, branded stores, pharmacies and e-commerce capabilities to improve reach and customer retention. Competitive intensity is increasing as organized players target underserved populations with transparent pricing and bundled exams plus eyewear offers. Global brands benefit from scale, technology and brand equity, while local challengers gain traction through localization, lower operating costs and stronger understanding of price-sensitive consumer preferences.
Key Player Analysis
- Bausch + Lomb Corporation
- Zeiss Group
- Waridi Eyewear
- Wazi Vision
- CooperVision Limited
- De Rigo Vision S.p.A.
- Fielmann AG
- JINS Inc.
- Titan Company Limited
- EssilorLuxottica
- Lapaire
Recent Developments
In April 2025, the Clinton Health Access Initiative and the OneSight EssilorLuxottica Foundation announced a multi-year partnership to expand access to eyeglasses and build sustainable vision-care systems across Africa. The collaboration began implementation in April 2025 with an initial three-year horizon and was framed around health-equity goals, local system strengthening, and tackling the continent’s large burden of uncorrected poor vision. This development matters for the African eyewear market because it links a major global eyewear foundation with a health-access organization to improve both affordability and long-term distribution infrastructure across multiple countries.
In January 2025, pan-African eyewear company Lapaire entered a new growth phase with Creadev coming in as a new partner following Saviu Ventures’ exit. The article said Lapaire had already scaled to nearly 90 branches across six African countries and built its model around free eye tests and affordable glasses for low- and middle-income consumers, many of them first-time wearers. The partnership is significant because it gives Lapaire fresh backing to accelerate expansion in a category where organized optical retail is still underpenetrated across much of Africa.
In February 2025, Moroccan eyewear platform LNKO secured funding from Egypt-based Beltone Venture Capital to support expansion across Africa. The company said it offers direct-to-customer sunglasses and optical frames through a fully digitized value chain, and the new capital is intended to help it widen its continental footprint. This is a meaningful market development because it shows investor confidence in digitally enabled eyewear retail models that can combine fashion positioning with broader accessibility in African markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Africa Eyewear Market in 2024?
What are the main growth drivers in the Africa Eyewear Market?
What key trend is shaping the Africa Eyewear Market?
Which segment leads the Africa Eyewear Market by product?
Who are the top players in the Africa Eyewear Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 9,931.09 Million → 2032: USD 19,594.22 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Africa Eyewear Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Africa Eyewear Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Africa Eyewear Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Africa Eyewear Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Africa Eyewear Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Africa Eyewear Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Africa Eyewear Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Africa Eyewear Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 9,931.09 Million → 2032: USD 19,594.22 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Africa Eyewear Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Africa Eyewear Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Africa Eyewear Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Africa Eyewear Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

