
E-commerce Apparel Market Overview:
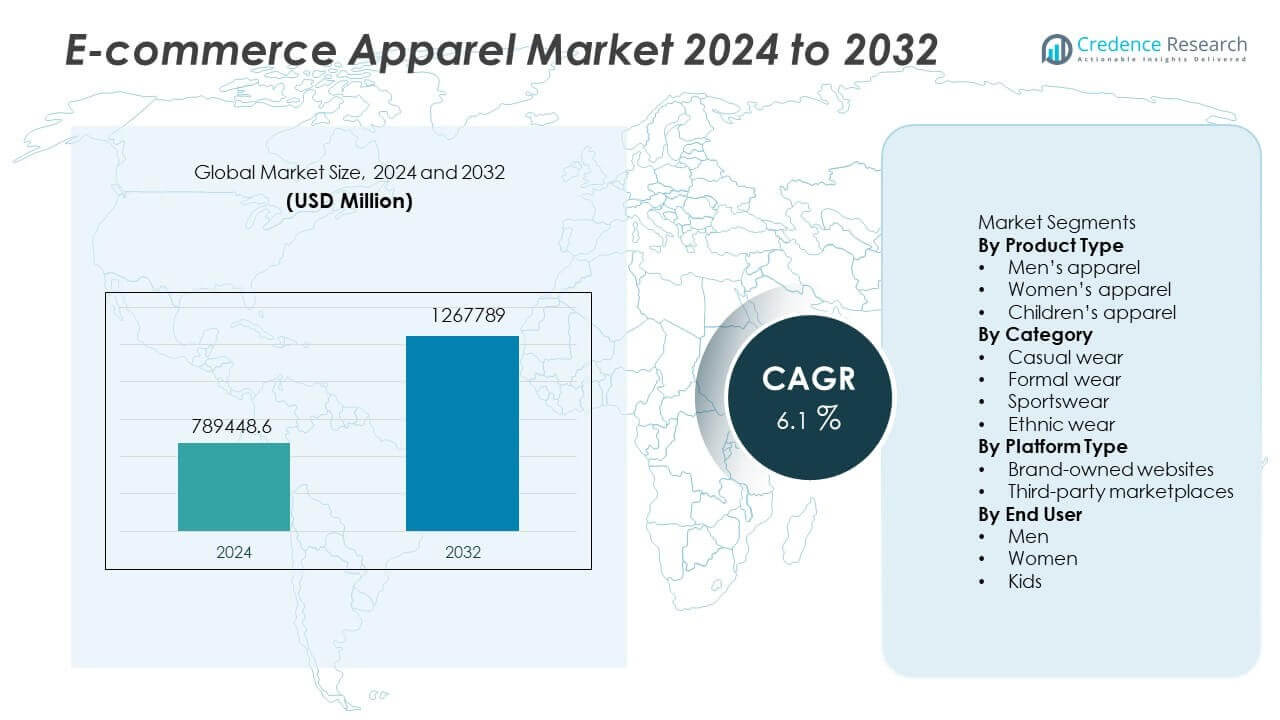
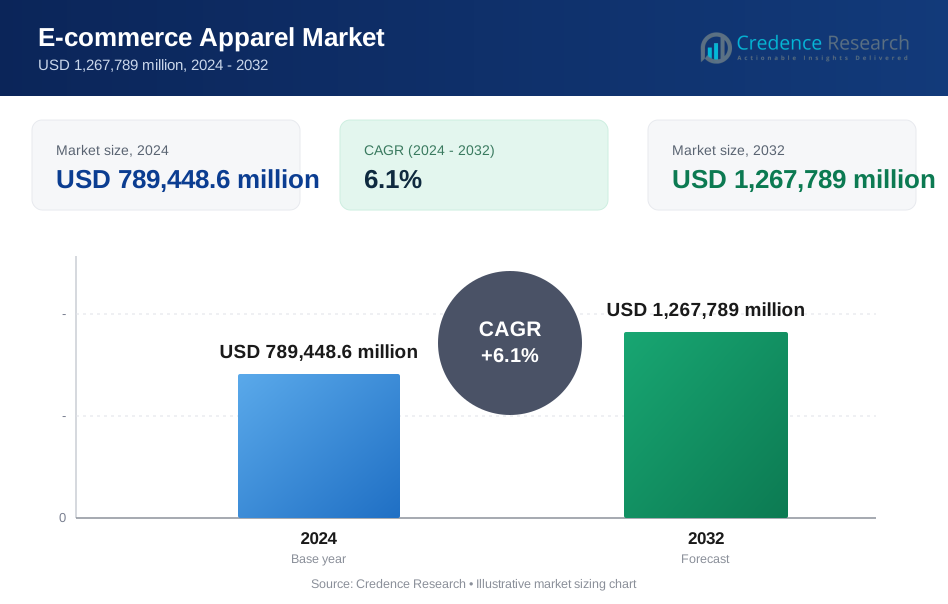
The e-commerce apparel market size was valued at USD 789,448.6 million in 2024 and is expected to reach USD 1,267,789 million by 2032, registering a CAGR of 6.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| E-commerce Apparel Market Size 2024 | USD 789,448.6 million |
| E-commerce Apparel Market, CAGR | 6.1% |
| E-commerce Apparel Market Size 2032 | USD 1,267,789 million |
E-commerce Apparel Market Insights
- Convenience, mobile shopping, and easy returns act as key growth drivers, while women’s apparel leads by product type with a 46.8% share due to higher purchase frequency and trend sensitivity.
- Casual wear dominates by category with a 52.3% share, supported by comfort-focused lifestyles, work-from-home culture, and frequent online promotions.
- Competition remains intense as major platforms focus on private labels, pricing strategies, logistics strength, and personalization to manage margin pressure and customer loyalty challenges.
- Asia Pacific leads regional demand with a 34.9% share, followed by North America at 28.6% and Europe at 23.4%, while Latin America and the Middle East & Africa show steady growth through improving digital infrastructure.
E-commerce Apparel Market Segmentation Analysis:
By Product Type
By product type, women’s apparel dominates the e-commerce apparel market with a market share of 46.8%. Strong demand comes from higher purchase frequency and faster fashion cycles. Women shoppers actively follow seasonal trends and influencer-driven styles. Online platforms offer wide size ranges and easy returns, which improves buyer confidence. Private labels and exclusive collections also support repeat purchases. Men’s apparel follows due to steady demand for casual and workwear. Children’s apparel shows consistent growth, supported by frequent replacement needs. Overall, variety, trend sensitivity, and flexible pricing drive women’s apparel leadership.
- For instance, a leading global fashion platform significantly expanded its catalog with thousands of new women’s styles in a single quarter and drastically reduced its average return processing time.
By Category
By category, casual wear leads the market with a share of 52.3%. Rising work-from-home adoption and lifestyle shifts support daily casual clothing demand. Consumers prefer comfort-focused designs for regular use. Online platforms offer frequent discounts and bundle deals, which boost volumes. Casual wear also benefits from faster style refresh cycles. Sportswear holds strong traction due to fitness awareness and athleisure trends. Ethnic wear gains demand during festivals and weddings. Formal wear remains stable but slower growing. Comfort, affordability, and high usage frequency drive casual wear dominance.
- For instance, a major e-commerce retailer like Flipkart, which is a dominant player in the apparel segment, expanded its casual wear catalog, and this expansion led to significant unit sales shortly after implementation.
By Platform Type
By platform type, third-party marketplaces dominate with a market share of 63.7%. These platforms offer broad brand access and price comparison benefits. High traffic volumes improve product visibility and conversion rates. Integrated logistics and easy return policies increase consumer trust. Flash sales and loyalty programs further support purchases. Brand-owned websites capture demand through exclusive launches and personalization. However, limited reach restricts scale. Marketplaces continue to lead due to convenience, assortment depth, and aggressive promotional strategies.
Key Growth Drivers
Rising Internet and Smartphone Penetration
Expanding internet access and smartphone usage strongly drive the e-commerce apparel market. Consumers increasingly shop through mobile apps and optimized websites. Affordable data plans support frequent browsing and impulse buying. Growth in Tier II and Tier III cities expands the online customer base. Digital payment adoption improves checkout ease and trust. Social media exposure further accelerates product discovery. Mobile-first strategies help brands engage younger consumers. Overall, wider digital access directly supports sustained growth in online apparel sales.
- For instance, Flipkart optimized its mobile app to support over 20 Indian languages and scaled infrastructure to handle more than 4 million concurrent users during peak events.
Convenience and Flexible Shopping Experience
Convenience remains a core driver of online apparel demand. Consumers value time savings and home delivery. Easy return and exchange policies reduce purchase hesitation. Wide brand availability improves product comparison. Multiple payment options enhance buyer confidence. Personalized recommendations improve relevance and engagement. Urban lifestyles increasingly favor online shopping over store visits. Subscription alerts and app notifications support repeat purchases. This shift toward convenience continues to strengthen e-commerce apparel adoption.
- For instance, Amazon deployed machine-learning models that generate over 100 million personalized product recommendations per day and cut average delivery promise times to two days across major cities.
Discounting and Private Label Expansion
Discount-led strategies play a major role in market growth. Seasonal sales and flash offers attract price-sensitive shoppers. Private labels provide trendy apparel at competitive prices. Platforms benefit from higher margins on owned brands. Data insights guide faster design and inventory cycles. Exclusive online collections reduce direct price comparison. Consumers increasingly trust platform-owned labels for value. Together, discounts and private labels drive volumes and improve customer retention.
Key Trends & Opportunities
Growth of Social Commerce
Social commerce is reshaping apparel sales channels. Influencers and short-form videos boost product visibility. Live shopping formats increase engagement and purchase confidence. Direct shopping links shorten the buyer journey. User-generated content improves authenticity and trust. Younger consumers prefer discovery through social platforms. Integrated checkout features simplify conversions. This trend creates new revenue opportunities and enhances brand reach.
- For instance, Shein runs live-stream sessions a few times each week and integrates one-click checkout supporting engaged real-time viewers.
Adoption of AI and Personalization
AI-driven personalization is transforming online apparel retail. Platforms analyze browsing and purchase behavior to tailor recommendations. Personalized feeds improve conversion and basket size. Virtual try-on tools help reduce fit-related returns. AI-based size guidance improves customer satisfaction. Dynamic pricing supports demand-based promotions. Chatbots provide instant support. Advanced personalization strengthens differentiation and long-term customer loyalty.
- For instance, Zalando uses AI sizing algorithms trained on more than 200 million body data points and supports virtual fitting across 23 markets.
Key Challenges
High Return Rates and Logistics Costs
High return rates challenge profitability in online apparel retail. Size and fit issues remain key return drivers. Reverse logistics increase handling and transportation costs. Inventory planning becomes complex due to frequent returns. Last-mile delivery adds further expense, especially in remote areas. Seasonal demand spikes strain logistics networks. Platforms invest in fit tools and policy controls. However, managing costs without hurting customer experience remains difficult.
Intense Competition and Margin Pressure
Strong competition creates continuous margin pressure across the market. Platforms compete aggressively on pricing and discounts. Customer loyalty remains limited due to easy switching. Marketing and acquisition costs continue to rise. Private labels increase internal competition for brands. Global players intensify competitive intensity. Sustaining profitability requires differentiation beyond price. Long-term competition remains a structural market challenge.
Regional Analysis
North America
North America holds a market share of 28.6% in the e-commerce apparel market. Strong digital infrastructure supports high online shopping penetration. Consumers prefer premium and branded apparel through online channels. Fast delivery options and advanced logistics strengthen customer satisfaction. High adoption of mobile shopping apps supports repeat purchases. Flexible return policies improve buyer confidence. Social media marketing strongly influences fashion choices. Private labels also gain traction across platforms. The presence of major e-commerce players and high disposable income continue to support steady regional demand growth.
Europe Europe accounts for a market share of 23.4% in the global e-commerce apparel market. Fashion-conscious consumers drive steady online apparel purchases. Strong demand comes from casual and sustainable clothing categories. Regulatory focus on data privacy improves platform trust. Cross-border e-commerce supports wider brand access. High smartphone usage supports mobile shopping growth. Seasonal sales and discount events boost volumes. Western Europe leads due to advanced logistics networks. Eastern Europe shows rising adoption supported by improving digital access and payment infrastructure.
Asia Pacific
Asia Pacific dominates the e-commerce apparel market with a market share of 34.9%. Large population size supports high transaction volumes. Rising middle-class income increases fashion spending. Mobile-first platforms drive strong engagement across urban and rural areas. Social commerce plays a major role in product discovery. Local brands and private labels attract price-sensitive consumers. High festival-driven sales boost demand spikes. Expanding logistics networks improve delivery reach. China and India remain key growth engines due to rapid digital adoption.
Latin America
Latin America holds a market share of 8.1% in the e-commerce apparel market. Improving internet penetration supports steady online adoption. Young consumers show strong interest in fashion trends. Mobile commerce grows faster than desktop shopping. Cashless payment adoption improves transaction ease. International brands expand regional presence through marketplaces. Logistics infrastructure continues to improve across major cities. Promotional campaigns drive customer acquisition. Brazil and Mexico lead regional demand due to higher urbanization and expanding digital ecosystems.
Middle East & Africa
The Middle East & Africa region accounts for a market share of 5.0%. Rising smartphone usage supports online apparel growth. Young demographics drive fashion-oriented purchases. International brands gain traction through digital platforms. Improved logistics and delivery services support market expansion. Social media influences buying decisions strongly. Cash-on-delivery remains important in several markets. Urban centers lead online adoption. Gulf countries show higher spending power, while African markets benefit from gradual digital infrastructure development.
E-commerce Apparel Market Segmentations:
By Product Type
- Men’s apparel
- Women’s apparel
- Children’s apparel
By Category
- Casual wear
- Formal wear
- Sportswear
- Ethnic wear
By Platform Type
- Brand-owned websites
- Third-party marketplaces
By End User
- Men
- Women
- Kids
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights strong competition among major players such as Amazon, Alibaba Group, JD.com, Zalando, ASOS, Shein, Flipkart, and Myntra. The market shows intense rivalry driven by pricing, assortment depth, and delivery speed. Players invest heavily in private labels to improve margins and control design cycles. Advanced data analytics supports demand forecasting and inventory efficiency. Mobile-first strategies and personalization tools strengthen customer engagement. Marketing spend remains high due to low switching costs. Logistics capability acts as a key differentiator, especially during peak sales events. Global players leverage scale, while regional platforms focus on local fashion preferences. Overall, innovation, brand partnerships, and operational efficiency shape competitive positioning.
Key Player Analysis
Recent Developments
- In December 2025, Amazon Fashion partnered with a celebrity to launch custom NBA-inspired apparel via its platform.
- In 2025, Amazon hosted major fashion discounts during global sales events and expanded fashion listings across Prime Day and holiday campaigns.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Category, Platform Type, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the E-commerce Apparel market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the E-commerce Apparel market projected to grow between 2024 and 2032?
Which E-commerce Apparel market segment held the largest share in 2024?
What are the primary factors fueling the growth of the E-commerce Apparel market?
Who are the leading companies in the E-commerce Apparel market?
Which region commanded the largest share of the E-commerce Apparel market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 789,448.6 million → 2032: USD 1,267,789 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global E-commerce Apparel Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global E-commerce Apparel Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global E-commerce Apparel Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global E-commerce Apparel Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global E-commerce Apparel Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global E-commerce Apparel Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global E-commerce Apparel Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global E-commerce Apparel Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 789,448.6 million → 2032: USD 1,267,789 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global E-commerce Apparel Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global E-commerce Apparel Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global E-commerce Apparel Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global E-commerce Apparel Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

