
Travel Toiletry Market Overview:
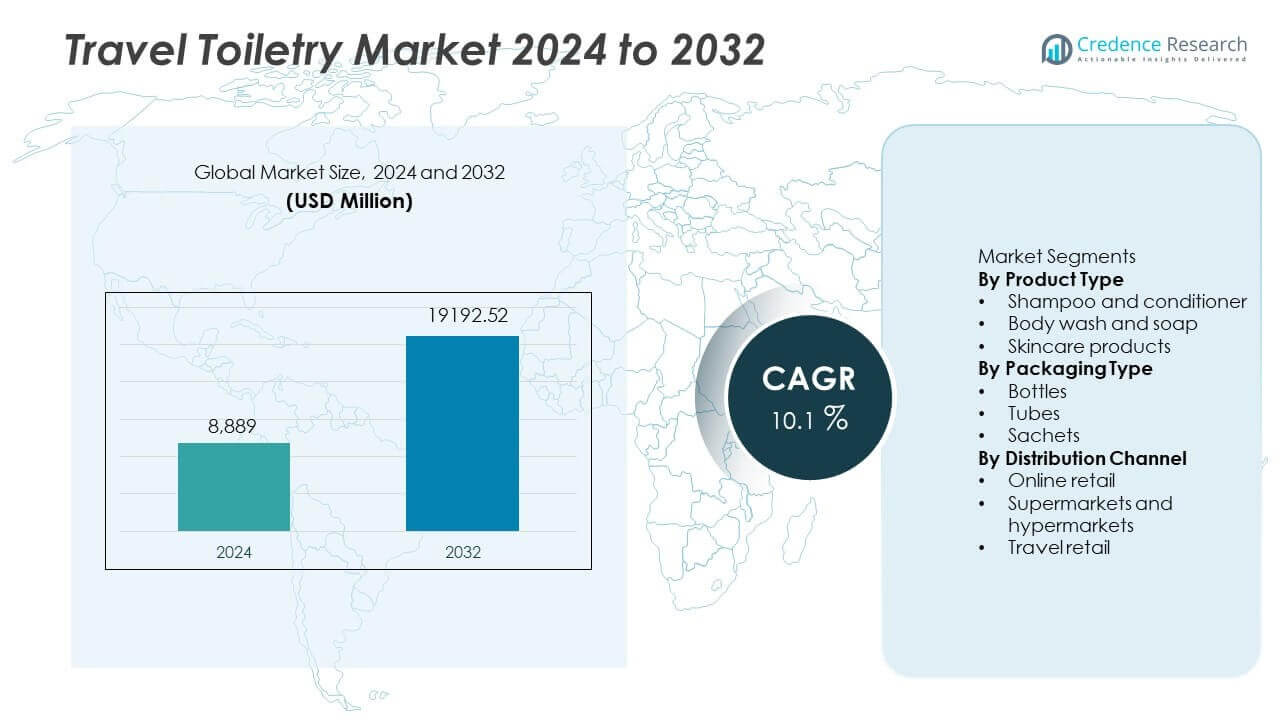
The travel toiletry market was valued at USD 8,889 million in 2024. The market is projected to reach USD 19,192.52 million by 2032. Growth is expected at a CAGR of 10.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Travel Toiletry Market Size 2024 | USD 8,889 million |
| Travel Toiletry Market, CAGR | 10.1% |
| Travel Toiletry Market Size 2032 | USD 19,192.52 million |
Travel Toiletry Market Insights
- Rising leisure and business travel, hygiene awareness, and demand for compact personal care products fuel travel toiletry market growth.
- Shampoo and conditioner lead with a 41% segment share, supported by frequent use and airline-compliant packaging formats.
- Intense competition focuses on compact designs, refillable packaging, and omni-channel distribution across retail and travel hubs.
- North America leads with a 34% regional share, followed by Europe at 28% and Asia Pacific at 27%, driven by travel frequency, sustainability focus, and online pre-trip purchasing.
Travel Toiletry Market Segmentation Analysis:
By Product Type
Shampoo and conditioner dominate the travel toiletry market with a 41% segment share. Frequent haircare needs during travel drive consistent demand. Travelers prefer compact formats that meet airline regulations. Body wash and soap hold a 34% share, supported by daily hygiene requirements and hotel travel habits. Skincare products account for a 25% share, driven by rising awareness of skin protection during travel. Shampoo and conditioner lead due to routine usage across all travel durations. Brand familiarity and convenience packs strengthen repeat purchases. Growing business and leisure travel continue supporting strong product turnover.
- For instance, Unilever sells travel shampoo bottles sized at 50 ml and 75 ml, below airline limits. The company reported distribution of more than 1.5 billion small-format haircare units globally in a year.
By Packaging Type
Bottles lead the packaging type segment with a 47% market share. Bottles offer leak resistance and ease of use. Consumers prefer bottles for liquid stability and durability. Tubes hold a 33% share, favored for creams and gels due to controlled dispensing. Sachets account for a 20% share, driven by cost sensitivity and single-use convenience. Bottles dominate due to reusability and premium perception. Refillable bottle trends further support demand. Compact and TSA-compliant designs reinforce bottle leadership across global travel markets.
- For instance, L’Oréal developed lightweight PET bottles that reduce plastic usage through eco-design principles. These durable containers are engineered to withstand impact stresses during transport and use without compromising structural integrity.
By Distribution Channel
Supermarkets and hypermarkets represent the largest distribution channel with a 39% segment share. Wide availability and bundled offers drive volume sales. Online retail holds a 36% share, supported by convenience and product variety. Travel retail accounts for a 25% share, driven by impulse purchases at airports and transit hubs. Supermarkets lead due to pre-travel purchasing behavior. Brand visibility and promotions influence buying decisions. Online channels benefit from subscription and value packs. Expanding travel activity continues strengthening multi-channel distribution strategies.
Key Growth Drivers
Rising Global Travel and Tourism Activity
Global travel activity continues expanding across leisure, business, and mixed-purpose trips. Increased airline capacity and hotel occupancy drive consistent demand for compact personal care products. Travelers prefer ready-to-use toiletries that simplify packing and comply with airline liquid restrictions. Short-duration trips boost demand for trial-size formats. Growth in international tourism increases the need for portable hygiene solutions across diverse climates. Frequent business travel supports recurring purchases of familiar brands. Hospitality growth also influences consumer habits before departure. This driver sustains high replacement cycles and volume demand for essential travel toiletry products worldwide.
- For instance, Reckitt supplies travel-size hygiene and personal care products in small-format bottles. The company operates automated filling lines to meet global demand for these portable units.
Growing Preference for Convenience and Portability
Modern travelers prioritize convenience and efficiency during trips. Compact toiletries reduce luggage weight and save space. Spill-proof and easy-dispense packaging improves user confidence. Pre-packed travel kits simplify purchase decisions for busy consumers. Multi-city trips increase reliance on portable personal care solutions. Business travelers prefer standardized kits for repeat usage. Parents value compact toiletries for family travel. Convenience-driven consumption supports impulse buying across channels. This driver accelerates adoption across shampoo, skincare, and hygiene categories while reinforcing demand for standardized travel-size packaging formats.
- For instance, Procter & Gamble utilizes advanced virtual packaging simulations and physical stress testing to ensure bottle integrity. These transport simulations evaluate performance under rigorous vibration and pressure conditions, significantly reducing the likelihood of leakage during the global distribution of their products.
Increasing Hygiene Awareness and Personal Care Spending
Hygiene awareness remains elevated across global travelers. Consumers increasingly avoid shared hotel toiletries. Personal travel kits ensure safety, comfort, and familiarity. Rising disposable income supports spending on branded personal care products. Skincare protection gains importance during travel exposure to pollution and climate changes. Wellness-focused consumers maintain routines while traveling. Parents prioritize hygiene for children during trips. Premium personal care adoption continues rising. This driver supports demand for functional, dermatologically tested, and skin-friendly travel toiletry products across both leisure and business travel segments.
Key Trends & Opportunities
Shift Toward Sustainable and Refillable Packaging
Sustainability influences purchasing decisions among frequent travelers. Refillable bottles and reusable containers gain strong preference. Brands introduce lightweight and recyclable materials to reduce waste. Eco-conscious packaging enhances brand credibility. Regulatory pressure supports plastic reduction initiatives. Refill packs encourage repeat purchases and brand loyalty. Sustainable packaging aligns with global environmental goals. Premium travelers show higher adoption rates. This trend creates opportunities for innovation in packaging design, materials, and refill systems while supporting long-term customer retention strategies.
- For instance, Beiersdorf AG developed refillable containers for skincare products to promote a circular economy. Internal durability tests verified the integrity of the packaging over multiple use cycles, ensuring the material remains robust and functional for repeated refills.
Growth of E-Commerce and Travel Retail Bundles
Online platforms reshape travel toiletry purchasing behavior. Consumers increasingly shop before departure through digital channels. Bundled travel kits simplify selection and offer better value. Personalization improves customer engagement online. Airport and travel retail benefit from impulse-driven purchases. Limited-edition travel packs attract frequent travelers. Subscription models support repeat buying. Omnichannel strategies improve brand reach. This trend creates scalable growth opportunities by combining digital convenience with travel retail visibility across global transit hubs.
- For instance, Henkel AG & Co. KGaA provides essential consumer products through digital platforms and retail partnerships. Their integrated supply chain utilizes automated order systems and smart logistics centers to process and distribute high volumes of consumer goods efficiently during periods of peak demand.
Key Challenges
Stringent Airline Liquid Regulations
Airline liquid restrictions impose strict volume limits on products. Compliance increases packaging design complexity. Different international regulations add operational challenges. Non-compliant packaging risks rejection during security checks. Brands must innovate within limited size constraints. Reduced volume affects formulation efficiency. Packaging cost increases impact margins. Frequent rule updates create uncertainty. This challenge requires continuous packaging optimization and regulatory awareness to maintain product acceptance across global travel markets.
Price Sensitivity and Brand Switching Behavior
Travel toiletries face high price sensitivity among consumers. Shoppers compare prices easily across brands. Private labels offer lower-cost alternatives. Frequent travelers switch brands based on convenience and availability. Premium pricing limits mass adoption in value-driven segments. Promotional offers influence buying decisions strongly. Brand loyalty remains moderate. Cost pressure affects margins for manufacturers. This challenge requires strong differentiation through quality, packaging, and convenience while maintaining competitive pricing strategies.
Regional Analysis
North America
North America holds a 34% market share in the travel toiletry market. High frequency of business and leisure travel drives consistent demand. Consumers prefer branded, TSA-compliant toiletry products. Strong hygiene awareness supports personal kit usage over hotel-provided items. E-commerce and supermarkets dominate pre-travel purchases. Premium skincare and haircare products see strong uptake. Refillable and sustainable packaging gains attention. High disposable income supports premium travel kits. Organized retail and strong brand presence sustain steady demand across the United States and Canada.
Europe
Europe accounts for a 28% market share in the travel toiletry market. Cross-border travel within the region supports frequent purchases. Sustainability-focused consumers favor eco-friendly and refillable packaging. Compact toiletries align with short-haul travel patterns. Supermarkets and drugstores remain key distribution channels. Skincare products see strong demand due to climate variation. Regulatory focus encourages sustainable packaging innovation. Brand loyalty remains high for trusted personal care names. Stable tourism activity ensures consistent demand across Western and Central Europe.
Asia Pacific
Asia Pacific represents a 27% market share in the travel toiletry market. Rapid growth in domestic and international travel drives demand. Rising middle-class income supports branded travel products. Online retail plays a major role in pre-trip shopping. Compact and affordable formats gain popularity. Skincare demand rises due to humidity and pollution exposure. Travel retail expands across major airports. Younger consumers favor convenience kits. Strong tourism recovery and urbanization support long-term market expansion across key Asian economies.
Rest of the World
The rest of the world holds an 11% market share in the travel toiletry market. Latin America and the Middle East lead regional demand. Growing tourism infrastructure supports product adoption. Price-sensitive consumers prefer value packs and sachets. Supermarkets remain the primary sales channel. Awareness of personal hygiene during travel continues improving. International travel growth supports gradual premium adoption. Brand penetration remains selective but expanding. The region offers emerging opportunities as travel frequency and disposable income increase.
Travel Toiletry Market Segmentations:
By Product Type
- Shampoo and conditioner
- Body wash and soap
- Skincare products
By Packaging Type
- Bottles
- Tubes
- Sachets
By Distribution Channel
- Online retail
- Supermarkets and hypermarkets
- Travel retail
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights Unilever, Procter & Gamble, L’Oréal, Johnson & Johnson, and Colgate-Palmolive as key participants in the travel toiletry market. These companies compete through strong brand recognition, broad product portfolios, and global distribution networks. Market leaders focus on compact, TSA-compliant packaging to meet airline regulations. Innovation centers on convenience kits, refillable formats, and skin-friendly formulations. Sustainability initiatives, including reduced plastic use, strengthen competitive positioning. E-commerce and travel retail partnerships improve visibility and impulse sales. Private-label competition increases pricing pressure, encouraging differentiation through quality and branding. Strategic marketing and retail collaborations remain critical for maintaining share in this fast-growing, travel-driven personal care segment.
Key Player Analysis
- Unilever
- Procter & Gamble
- L’Oréal
- Johnson & Johnson
- Reckitt
- Colgate-Palmolive
- Kao Corporation
- Beiersdorf AG
- Henkel AG & Co. KGaA
- Edgewell Personal Care
Recent Developments
- In January 2026, Emirates launched a new range of complimentary amenity kits for Premium Economy and Economy Class on long-haul flights globally, using reusable pouches made with bio-based materials and adding Aveda skincare items for Premium Economy travelers.
- In March 2026, China Airlines introduced an upgraded travel kit developed with Marc Jacobs and FRAMA, with rollout beginning on the Prague route and then expanding to long-haul services to the Americas, Europe, and Australia from May onward.
- In March 2026, ANA announced renewed First Class and Business Class amenity kits for international long-haul and selected medium-haul routes, featuring new partnerships with FRANZI for the pouch design and DECORTÉ or CULTI MILANO for onboard skincare products.
- In March 2026, these ANA kits were positioned as the first in-flight amenity-kit partnerships for both DECORTÉ and CULTI MILANO, making the update a notable premium travel-toiletry product launch.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Packaging Type, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Global travel growth will continue supporting demand for travel-sized toiletries.
- Compact and airline-compliant packaging will remain a core design focus.
- Hygiene awareness will sustain consistent personal toiletry purchases.
- Refillable and reusable containers will gain stronger consumer acceptance.
- E-commerce will play a larger role in pre-travel purchasing decisions.
- Travel retail will benefit from impulse buying at transit locations.
- Premium skincare products will see rising adoption among travelers.
- Emerging markets will contribute faster volume growth.
- Sustainable materials will influence packaging innovation strategies.
- Strategic partnerships will strengthen brand presence across travel channels.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Travel and Tourism Activity
Increasing leisure and business travel worldwide is driving demand for compact, airline-compliant toiletry products. Higher airline capacity and hotel occupancy rates support frequent purchases of travel-sized personal care items.
Growing Preference for Convenience and Portability
Modern travelers seek lightweight, easy-to-pack toiletries that simplify packing and comply with airline liquid restrictions. The popularity of pre-packed travel kits and spill-proof packaging is accelerating market growth.
Increasing Hygiene Awareness and Personal Care Spending
Travelers are more conscious of hygiene and prefer using their own branded toiletries over shared hotel amenities. Rising disposable incomes and wellness trends are boosting spending on premium and dermatologically tested travel toiletry products.
Shift Toward Sustainable and Refillable Packaging
Eco-conscious consumers are driving demand for refillable, reusable, and recyclable packaging. Brands are innovating with sustainable materials and refill systems, which enhances brand loyalty and aligns with global environmental goals.
Growth of E-Commerce and Travel Retail Bundles
Online platforms and travel retail outlets are reshaping purchasing behavior, with consumers increasingly buying travel toiletry kits before departure. Bundled offers, personalization, and omnichannel strategies are expanding market reach and supporting impulse purchases.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Travel Toiletry market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Travel Toiletry market projected to grow between 2024 and 2032?
Which Travel Toiletry market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Travel Toiletry market?
Who are the leading companies in the Travel Toiletry market?
Which region commanded the largest share of the Travel Toiletry market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Shampoo and conditioner
- 1.2.2 Body wash and soap
- 1.2.3 Skincare products
- 1.3 By Packaging Type
- 1.3.1 Bottles
- 1.3.2 Tubes
- 1.3.3 Sachets
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8,889 million → 2032: USD 19,192.52 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Travel Toiletry Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Travel Toiletry Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Travel Toiletry Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Travel Toiletry Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Travel Toiletry Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Travel Toiletry Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Travel Toiletry Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Travel Toiletry Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8,889 million → 2032: USD 19,192.52 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Travel Toiletry Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Shampoo and conditioner
- 12.3.7.2 Body wash and soap
- 12.3.7.3 Skincare products
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Packaging Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Bottles
- 12.4.7.2 Tubes
- 12.4.7.3 Sachets
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Travel Toiletry Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Travel Toiletry Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Travel Toiletry Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Unilever
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Procter & Gamble
- 17.4 L’Oréal
- 17.5 Johnson & Johnson
- 17.6 Reckitt
- 17.7 Colgate-Palmolive
- 17.8 Kao Corporation
- 17.9 Beiersdorf AG
- 17.10 Henkel AG & Co. KGaA
- 17.11 Edgewell Personal Care
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

