
Market overview
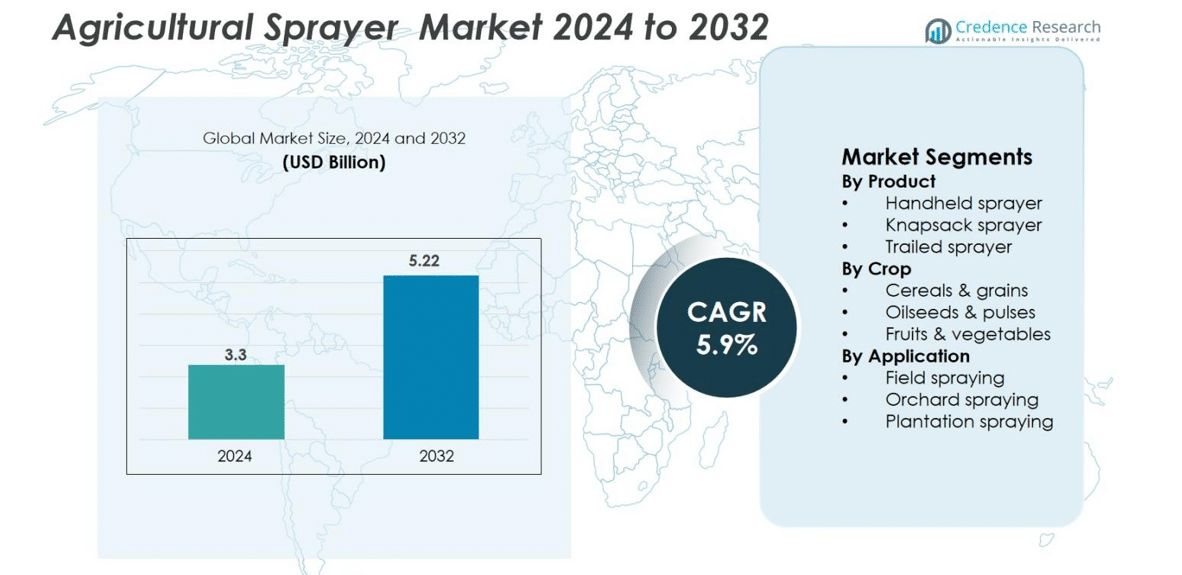
The Agricultural Sprayer market size was valued at USD 3.3 Billion in 2024 and is anticipated to reach USD 5.22 Billion by 2032, at a CAGR of 5.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Agricultural Sprayer Market Size 2024 | USD 3.3 Billion |
| Agricultural Sprayer Market, CAGR | 5.9% |
| Agricultural Sprayer Market Size 2032 | USD 5.22 Billion |
The Agricultural Sprayer market is increasingly driven by established global equipment manufacturers. Key players such as Deere & Company (holding about 12.1% of the market), CNH Industrial N.V. 8.1%, and AGCO Corporation 6.2% dominate the competitive landscape. Additionally, companies like Kubota Corporation, Mahindra & Mahindra Ltd. and Yamaha Motor Co., Ltd. play critical roles in regional markets, offering tailored solutions for small‑ and medium‑scale farming operations. Regionally, the Asia‑Pacific market leads with approximately 36.8% share, followed by North America at 23.9%, reflecting the strong mechanisation and adoption of precision‑spraying technology in these areas.
Market Insights
- The global Agricultural Sprayer market was valued at USD 3.3 billion in 2024 and is projected to reach USD 5.22 billion by 2032, growing at a CAGR of 5.9% during the forecast period.
- Key drivers include advancements in sprayer technology, increasing demand for food security, and the adoption of sustainable farming practices, all of which contribute to rising market demand.
- Growing trends in smart sprayers, precision agriculture, and the expansion of mechanisation in emerging markets are driving innovation and adoption, especially in regions like Asia-Pacific and North America.
- The market is highly competitive, with key players such as Deere & Company, CNH Industrial, and AGCO Corporation holding significant shares in the market, while regional players like Kubota and Mahindra focus on cost-effective solutions.
- Regional analysis shows that Asia-Pacific holds the largest market share at 36.8%, followed by North America at 23.9%, with strong growth expected in emerging markets in Latin America and the Middle East & Africa.
Market Segmentation Analysis
By Product
The agricultural sprayer market is segmented by product into handheld sprayers, knapsack sprayers, and trailed sprayers. The knapsack sprayer is the dominant sub-segment, holding the largest market share of 45%. This product is preferred due to its versatility, ease of use, and suitability for small to medium-scale farming operations. Additionally, knapsack sprayers are highly efficient in targeting precise application, making them essential in the cultivation of a variety of crops. The growing demand for efficient crop protection, combined with increasing adoption in emerging markets, drives the growth of this sub-segment.
- For instance, FARMIC offers a knapsack power sprayer model with a 25 litre tank capacity, engine suction value of 7‑9 litres, and pressure range of 20‑35 bars.
By Crop
In terms of crop segmentation, the market is divided into cereals & grains, oilseeds & pulses, and fruits & vegetables. The cereals & grains segment holds the largest market share at 50%, driven by the widespread cultivation of crops like wheat, rice, and corn globally. These crops require large-scale spraying for pest control and disease management. With increasing demand for food security and agricultural productivity, the adoption of sprayers for cereals and grains is expected to grow significantly. Additionally, the rising need for advanced farming practices to improve crop yields further propels this segment's growth.
- For instance, John Deere's ExactApply system is stated to achieve a chemical usage reduction of 2% to 5% compared to nozzles without the technology, primarily through features like individual nozzle control and reduced overlap.
By Application
The application segment of the agricultural sprayer market includes field spraying, orchard spraying, and plantation spraying. Field spraying dominates this segment, commanding a market share of 60%. The increasing adoption of large-scale farming operations and the growing need for efficient pest and weed control in open fields contribute to this dominance. Moreover, advancements in sprayer technology that enhance coverage and reduce chemical wastage further drive the field spraying sub-segment’s growth. As the demand for higher crop yields and sustainable farming practices rises, the field spraying application remains the leading choice for farmers worldwide.
Key Growth Drivers
Advancements in Sprayer Technology
Technological advancements in agricultural sprayers have significantly contributed to the market's growth. The development of precision sprayers that ensure targeted application of pesticides, fertilizers, and herbicides is a key driver. These innovations reduce chemical wastage, enhance spraying efficiency, and lower operational costs, which makes them attractive to farmers aiming for sustainability and increased productivity. Furthermore, the integration of GPS and IoT technology in sprayers has enabled real-time monitoring, mapping, and automation of spraying tasks. This technology also minimizes human error and improves overall operational efficiency.
- For instance, Deere & Company’s See & Spray™ system uses camera‑based computer vision and machine learning to identify weeds in corn, soybeans and cotton, and triggered individual nozzles for spot spraying.
Rising Demand for Food Security and Agricultural Productivity
The increasing global population and growing demand for food have driven the need for higher agricultural productivity. Sprayers play a vital role in improving crop yields by providing effective pest control, disease management, and nutrient application. With limited arable land and the need to maximize output, farmers are increasingly turning to modern sprayers to boost productivity while maintaining sustainability. Government initiatives promoting food security and encouraging the adoption of advanced farming techniques further bolster the demand for sprayers. As agricultural output continues to be a priority for governments and businesses alike, the need for efficient and reliable sprayers will remain a key growth driver in the agricultural sprayer market.
- For instance, the use of John Deere’s ExactApply™ nozzle control system in corn and soybean crops has reduced pesticide and fertilizer waste, improving productivity by accurately controlling spray patterns, allowing farmers to increase application efficiency on larger fields.
Adoption of Sustainable Farming Practices
The growing emphasis on sustainable farming practices has contributed to the expansion of the agricultural sprayer market. With increasing concerns over the environmental impact of conventional farming methods, farmers are turning to more eco-friendly alternatives, such as low-volume sprayers and organic pesticides. These innovations minimize chemical runoff, reduce environmental contamination, and ensure that crops are cultivated in a more sustainable manner. Additionally, the rising popularity of organic farming, which requires specific spraying equipment to handle organic pesticides and fertilizers, is expected to drive demand for specialized sprayers.
Key Trends & Opportunities
Integration of Smart Sprayers and Automation
The integration of smart technology in agricultural sprayers presents a significant opportunity for the market. With the adoption of IoT-enabled devices and AI-driven systems, sprayers are becoming more automated, efficient, and precise. Smart sprayers can detect variations in crop health and adjust the spraying process accordingly, ensuring optimal pesticide and nutrient application. This automation reduces labor costs and minimizes human error, making it an attractive solution for large-scale farms. Furthermore, farmers can track and monitor their sprayer performance remotely, which provides real-time insights and enhances decision-making.
- For instance, The DJI Agras T30 drone, when integrated into the wider DJI digital agriculture solution, can perform targeted, variable-rate applications of pesticides or fertilizers.
Growth in Emerging Markets
The agricultural sprayer market is witnessing rapid growth in emerging economies, particularly in Asia-Pacific, Latin America, and Africa. As these regions modernize their agricultural practices and adopt advanced technologies, the demand for efficient and reliable spraying equipment is increasing. Governments in these regions are offering subsidies and financial support to encourage farmers to upgrade their equipment to enhance productivity and reduce environmental impact. Additionally, the increasing awareness of crop protection and the need for better pest management is driving the demand for sprayers in these markets. The growing middle class in emerging economies also presents an opportunity for manufacturers to introduce cost-effective yet technologically advanced sprayer solutions to cater to this expanding market.
- · For instance, the Brazilian government's Plano Safra program, which provides financial incentives and subsidized credit for agricultural production, has increasingly offered lower interest rates for farmers who adopt sustainable and low-carbon practices, including precision agriculture technologies.
Key Challenges
High Initial Investment and Maintenance Costs
One of the primary challenges in the agricultural sprayer market is the high initial cost of advanced sprayer systems. While modern sprayers offer improved efficiency and precision, they can be prohibitively expensive for small-scale farmers. This high cost often includes not only the price of the sprayer itself but also ongoing maintenance and the need for skilled labor to operate the equipment effectively. As a result, many farmers in developing regions may be unable to afford or justify the investment in advanced sprayer technology. This cost barrier may limit the widespread adoption of modern sprayers, slowing the market's growth in certain areas, especially in lower-income regions.
Environmental Concerns and Regulatory Pressure
Despite the advancements in sprayer technology, environmental concerns remain a significant challenge. The overuse of pesticides and chemicals in farming can lead to soil degradation, water pollution, and harm to biodiversity. Governments worldwide are increasingly enacting stricter regulations on pesticide use, which can affect the demand for certain types of sprayers, especially those used for large-scale chemical applications. Furthermore, the pressure to adopt sustainable farming practices may require manufacturers to continuously innovate and offer environmentally friendly sprayers. While this opens up opportunities, it also poses a challenge as companies must balance innovation with regulatory compliance and environmental sustainability, which can increase operational costs.
Regional Analysis
Asia‑Pacific (APAC)
The Asia‑Pacific region held a dominant share of 36.8% of the global agricultural sprayer market in 2024. Driven by large agricultural land bases, increasing mechanisation in countries like China and India, and government subsidies promoting modern farming equipment, the region remains the largest contributor to global volume and growth. Farmers adopt sprayers to enhance productivity and overcome labour shortages, while rising demand for food security and efficient crop protection further supports uptake. As equipment manufacturers target APAC to scale operations, the region is poised to maintain its leadership through 2030 and beyond.
North America
In North America, the agricultural sprayer market accounted for 23.9% of the global market in 2024, thanks to advanced mechanised farming, high crop productivity levels and significant investment in precision‑agriculture technologies. Major farms in the U.S. and Canada increasingly deploy large‑capacity sprayers, such as tractor‑mounted and self‑propelled units, to service extensive acreages of cereals, grains and oilseeds. The region’s mature infrastructure and favourable regulatory environment supporting efficient and sustainable practices enable steady growth, even though incremental expansion is slower compared with emerging markets.
Europe
Europe’s agricultural sprayer market contributes 20% share of the global total, underpinned by strong farm consolidation, high regulatory standards concerning pesticide use and sustainability, and widespread adoption of precision spraying technologies. Farmers in countries such as Germany, France and Spain upgrade equipment to comply with stricter environmental mandates and to improve yields of fruits, vegetables and grains. As organic farming and low‑volume spraying gain traction, Europe is positioned for moderate growth with emphasis on quality and efficiency rather than scale.
Latin America
In Latin America, the agricultural sprayer market holds 10‑12% of the global share, supported by extensive commercial farms in Brazil, Argentina and Mexico seeking to modernise spraying operations. The region is characterised by large‑scale crop production of soybeans, corn and other row crops, which drives demand for high‑capacity and contraction‑resistant sprayer systems. Infrastructure limitations and after‑sales service constraints restrict full optimisation, but investment in mechanisation and crop protection presents significant growth potential over the coming years.
Middle East & Africa (MEA)
The Middle East & Africa region currently accounts for 8% of the global agricultural sprayer market. The region’s arid to semi‑arid climates, increasing emphasis on greenhouse and high‑value horticulture production, and efforts to modernise agriculture through government programmes contribute to rising demand. However, challenges such as fragmented farming structures, limited mechanisation and logistical hurdles temper growth. Still, MEA represents an emerging opportunity zone for suppliers offering cost‑effective, robust spraying equipment tailored for resource‑constrained agricultural systems
Market Segmentations
By Product
- Handheld sprayer
- Knapsack sprayer
- Trailed sprayer
By Crop
- Cereals & grains
- Oilseeds & pulses
- Fruits & vegetables
By Application
- Field spraying
- Orchard spraying
- Plantation spraying
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the global agricultural sprayer market is distinctly marked by a concentration of major players alongside a diversified base of regional specialists. Leading manufacturers such as Deere & Company (commonly known as John Deere) hold 12.1% of the market share, followed by CNH Industrial N.V. at 8.1%, and AGCO Corporation at around 6.2%. These companies leverage global distribution networks, significant R&D investment in precision-spraying technologies, and strong brand recognition to maintain their competitive advantage. Meanwhile, firms such as Kubota Corporation, Mahindra & Mahindra Ltd., and Yamaha Motor Co., Ltd. focus on cost-effective equipment and emerging-market penetration, ensuring dynamic competition. Innovations such as smart spraying systems, autonomous sprayers, and environmentally sustainable models are increasingly shaping competitive differentiation and driving strategic partnerships across the sector.
Key Player Analysis
- Yamaha Motor Co., Ltd.
- AGCO Corporation
- Househam
- John Deere
- Chafer Machinery Group
- Kubota Corporation
- CNH Industrial N.V.
- Mahindra & Mahindra
- Boston Crops Sprayers
- Jacto Inc.
Recent Developments
- In November 2025, Case IH, a brand of CNH Industrial, launched its new Patriot 50 Series sprayers the Patriot 2550 and 4050 designed with enhanced suspension, an improved drive system, and integrated precision spraying technology.
- In February 2025, Ecorobotix unveiled AI-driven “Plant-by-Plant™” software and advanced crop-specific algorithms, including beta versions for crops such as cotton and soybean.
- In June 2024, Kverneland Group entered a partnership with DAT to expand the adoption of precision spraying systems. Through this collaboration, the DAT Ecopatch system will be integrated into Kverneland sprayers across Norway, Germany, the Netherlands, and other European markets.
Report Coverage
The research report offers an in-depth analysis based on Product, Crop, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of precision‑spraying technologies will accelerate, enabling farmers to apply chemicals more efficiently and reduce input waste.
- Autonomous and drone‑based sprayers will gain traction as regulatory frameworks evolve, allowing for broader commercial use in varied terrains.
- Battery‑powered and electric sprayer models will become more prevalent as users seek lower operating costs and reduced environmental impact.
- Growth in emerging markets will outpace mature regions as mechanisation expands and small‑scale farmers upgrade equipment.
- Integration of IoT and data analytics in sprayer systems will provide real‑time field monitoring and adaptive spraying, enhancing operational performance.
- Demand for sustainable agriculture will push the development of low‑drift nozzles, eco‑friendly formulations, and equipment designed for minimal off‑target application.
- Suppliers will focus on modular and retrofit‑friendly sprayer units to address budget constraints among smaller farms.
- Partnerships between machinery OEMs and ag‑tech firms will drive innovation in smart spraying platforms and service ecosystems.
- After‑sales service networks and training programs will become key differentiators as sprayers become more complex and technology‑intensive.
- Fluctuating raw‑material prices and tightening regulations could pressure margins, prompting manufacturers to streamline designs and emphasise cost‑efficient manufacturing.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the agricultural sprayers market?
At what Compound Annual Growth Rate is the Agricultural Sprayer market projected to grow between 2025 and 2032?
What factors are driving the agricultural sprayers market?
who are the major players in the Agricultural Sprayers Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Agricultural Sprayers Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Agricultural Sprayers Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3.3 billion → 2032: USD 5.22 billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Agricultural Sprayers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Agricultural Sprayers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Agricultural Sprayers Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Agricultural Sprayers Market Drivers
- 3.3 Agricultural Sprayers Market Restraints & Challenges
- 3.4 Agricultural Sprayers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Agricultural Sprayers Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Agricultural Sprayers Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Agricultural Sprayers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Agricultural Sprayers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Agricultural Sprayers Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Agricultural Sprayers. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Agricultural Sprayers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Agricultural Sprayers Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Agricultural Sprayers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Agricultural Sprayers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Agricultural Sprayers
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Agricultural Sprayers Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Agricultural Sprayers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Agricultural Sprayers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Agricultural Sprayers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Agricultural Sprayers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Agricultural Sprayers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Agricultural Sprayers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Agricultural Sprayers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
