
AI in Clinical Trials Market Overview:
The AI in Clinical Trials Market is projected to grow from USD 2,538.43 million in 2025 to an estimated USD 12,240.4 million by 2032, registering a CAGR of 25.20% from 2025 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| AI in Clinical Trials Market Size 2025 | USD 2,538.43 million |
| AI in Clinical Trials Market, CAGR | 25.20% |
| AI in Clinical Trials Market Size 2032 | USD 12,240.4 million |
AI in Clinical Trials Market Insights:
- North America leads with 45% market share due to advanced AI infrastructure, strong regulatory frameworks, and early adoption across pharma and CROs.
- Europe holds 25% share, driven by GDPR-compliant AI platforms and strong academic–industry partnerships, followed by Asia Pacific with 18%, supported by digital health investments.
- Asia Pacific is the fastest-growing region, expanding rapidly due to rising clinical trial activity in China and India, cost-effective operations, and government-backed digital health initiatives.
- By phase, Phase III trials account for the highest share at 40%, while in application, Patient Recruitment leads with 35% share due to growing demand for faster, targeted enrollment.

AI in Clinical Trials Market Drivers:
Demand for Optimized Trial Efficiency Through Intelligent Protocol Design and Automation
The rising complexity of clinical protocols forces sponsors to seek smarter design tools. AI platforms analyze historical trial outcomes to recommend feasible protocol structures. It minimizes protocol amendments and boosts first-time approval rates. The AI in Clinical Trials Market grows as sponsors focus on design accuracy and automation. Adaptive algorithms reduce human error and repetitive tasks during planning. Automated workflows cut development time and resource strain. It enables quicker approvals and better alignment with trial endpoints. Efficiency gains make AI tools a key driver of market growth.
- For instance, ZS Associates implemented AI-driven protocol design solutions that reduced the time spent on clinical trial protocol development by 50% while decreasing the number of costly protocol amendments by 20%.
Integration of AI for Smarter Patient Stratification and Cohort Identification in Targeted Trials
Personalized medicine demands high-precision patient matching. AI supports this through natural language processing and multi-source data analysis. Tools match trial criteria with real-world patient data more accurately than manual methods. The AI in Clinical Trials Market benefits as pharma shifts toward niche indications and biomarker-based therapies. It helps sponsors build cleaner cohorts, reducing noise and protocol deviation risks. Smart matching also improves data quality across endpoints. AI allows earlier identification of high-risk or likely dropout participants. This leads to higher success rates and better trial economics.
- For instance, Deep 6 AI utilized its precision matching platform to analyze structured and unstructured data, successfully increasing the volume of eligible patients identified for clinical trials by 600% within minutes.
Real-Time Monitoring and Risk Detection for Higher Compliance and Regulatory Alignment
Compliance pressures require continuous monitoring across trial phases. AI models track deviations, safety events, and operational metrics in real time. The AI in Clinical Trials Market aligns with this need by offering anomaly detection and predictive dashboards. It identifies site-level performance issues early, enabling corrective actions. AI-driven alerts support risk-based monitoring strategies. Sponsors reduce reliance on manual site visits and static reports. It ensures readiness for audits and inspections. Regulatory bodies increasingly accept AI-generated data insights, reinforcing adoption.
Strong Industry Push to Mitigate Trial Failures by Enhancing Early-Stage Decision-Making
High late-stage failure rates challenge trial economics. AI supports better feasibility assessments, biomarker validation, and target selection. The AI in Clinical Trials Market grows as firms invest in front-loading success factors. It offers early indicators of outcome likelihood using preclinical and real-world datasets. These insights guide go/no-go decisions for candidate progression. AI tools cut avoidable costs from failed Phase II or III trials. They also support more focused R&D pipelines. Early-stage intelligence builds competitive advantage and sustains industry interest.
AI in Clinical Trials Market Trends:
Increased Use of Natural Language Processing to Analyze Unstructured Data in Clinical Records
Clinical trials generate vast volumes of physician notes, EMRs, and patient-reported outcomes. NLP tools extract insights from these unstructured sources. The AI in Clinical Trials Market gains momentum from improved data interpretation. NLP enables faster case matching, safety signal extraction, and endpoint tracking. It complements structured datasets like EDC or lab results. AI engines unlock value from legacy records that were previously underutilized. Sponsors make faster evidence-based decisions. This trend expands AI’s reach into new content layers within trials.
- For instance, IQVIA integrated NLP capabilities into its clinical workflows to process unstructured medical records, achieving reduction in the time required for data verification and medical coding.
Use of Federated Learning Models to Enable AI Adoption Without Compromising Patient Privacy
Federated learning supports multi-site AI training without centralizing patient data. It enhances privacy compliance while retaining model accuracy. The AI in Clinical Trials Market adopts this trend to overcome data-sharing roadblocks. Models train across decentralized systems and update in secure environments. This method satisfies GDPR and HIPAA constraints. Pharma firms partner with hospitals using federated platforms. It allows large-scale learning without regulatory friction. The approach strengthens AI integration across global trial networks.
- For instance, Owkin utilized its federated learning platform, MELLODDY, to train drug discovery models across 10 major pharmaceutical companies; the project successfully trained models on over 10 million chemical compounds without any participant having access to a partner’s proprietary data.
Adoption of Digital Twins for Virtual Trial Simulations and Patient Behavior Forecasting
AI now supports creation of digital twins-virtual models of individual patients. These twins simulate response patterns and trial journeys. The AI in Clinical Trials Market benefits from better prediction of drug efficacy and dropout risk. Simulated trials reduce the need for control groups. They also optimize dosing strategies before human enrollment. AI enables dynamic protocol adjustments using digital twin feedback. It increases trial adaptability and success probability. This trend transforms trial planning.
Focus on Generative AI to Accelerate Document Preparation, Consent Forms, and Trial Summaries
Generative AI streamlines document generation across regulatory and patient-facing assets. It reduces time spent on manual writing and formatting. The AI in Clinical Trials Market sees interest in trial summaries, protocol drafts, and consent form creation. AI platforms ensure compliance language and readability standards. Sponsors deliver faster and more accurate documentation packages. It supports multilingual trials and reduces administrative burdens. This trend improves operational scalability.
AI in Clinical Trials Market Challenges Analysis:
Lack of Standardized Validation Protocols and Limited Explainability of AI Algorithms in Regulated Environments
Many AI models lack formal validation frameworks accepted by regulatory agencies. Without clear guidelines, sponsors hesitate to submit AI-driven decisions. The AI in Clinical Trials Market faces adoption friction due to limited model explainability. Black-box systems reduce trust among clinicians and regulators. Stakeholders demand interpretable outputs and audit trails. Existing trial workflows resist integration with opaque algorithms. Inconsistent performance across sites complicates model benchmarking. Training and testing standards vary widely. These gaps delay full-scale adoption.
Data Silos, Integration Gaps, and Resistance to Digital Transition Among Trial Sites and CROs
Trial operations often rely on outdated systems and disconnected data streams. AI tools require unified data access across platforms. The AI in Clinical Trials Market struggles where data interoperability is weak. Legacy CROs and trial sites resist digital overhaul due to cost or skill gaps. Fragmented workflows hinder algorithm performance. Change management becomes a barrier in traditional organizations. Training and support investments remain low. These constraints limit speed of AI deployment.
AI in Clinical Trials Market Opportunities:
Rise in Cross-Border Trials Drives Need for Scalable AI Infrastructure With Multilingual Capabilities
Global trials create demand for language-agnostic AI tools. Sponsors seek platforms that handle regulatory and patient data in local formats. The AI in Clinical Trials Market benefits from demand for scalable, multilingual solutions. AI vendors expand into Asia, Latin America, and Eastern Europe. It supports diverse trial populations and document generation.
Push Toward Interoperable AI Systems That Integrate Seamlessly With EHR, CTMS, and eConsent Platforms Vendors develop modular AI tools that fit within existing trial stacks. This reduces implementation friction and speeds up adoption. The AI in Clinical Trials Market grows with tools compatible across platforms. Seamless integration allows real-time sync with patient records. It improves site-level efficiency and data quality.
AI in Clinical Trials Market Segmentation Analysis:
By Phase-Based Insights
The AI in Clinical Trials Market sees highest adoption during Phase II and Phase III trials, where risk and complexity increase. AI enables predictive analytics, improves protocol feasibility, and supports patient stratification during these costly stages. In Phase I, its role is growing as drug developers apply AI for early safety signal detection and cohort analysis. Phase IV applications focus on post-marketing surveillance using real-world data. AI streamlines observational studies and long-term safety tracking. Each phase integrates AI differently, reflecting evolving trial demands. It helps reduce delays and enhances data integrity. Sponsors rely on AI tools to adapt across all stages of drug development.
- For instance, Medidata (Dassault Systèmes) utilized its "Intelligent Trials" AI platform in Phase III studies to improve enrollment accuracy, successfully reducing trial cycle times by 40% through predictive site performance analytics.
By Indication-Based Insights
Oncology leads AI adoption due to high data volumes and the complexity of trial designs. AI enables personalized patient matching and improves response prediction models. Neurology follows, with tools addressing challenges in endpoint variability and cognitive assessment. Cardiology trials benefit from AI's ability to handle sensor and imaging data. Rare diseases see growing AI use in identifying micro-cohorts and enabling virtual controls. The market tailors AI deployment to indication-specific needs. It improves data interpretation and operational efficiency. Sponsors seek faster enrollment in hard-to-reach patient populations. Indications with high failure rates benefit most from AI-driven improvements.
- For instance, Insilico Medicine utilized its generative AI platform, Pharma.AI, to identify a novel target and design a new drug candidate for Idiopathic Pulmonary Fibrosis (IPF) in under 18 months, reaching Phase I clinical trials with a budget reduction of approximately 90% compared to traditional discovery methods.
By Technology-Based Insights
Machine learning dominates, offering broad applications across trial operations. Deep learning supports image analysis and predictive biomarker modeling. Natural language processing extracts insights from unstructured clinical texts. These technologies work together to enhance trial intelligence. Vendors invest in layered AI architectures. The AI in Clinical Trials Market evolves with hybrid models that offer greater accuracy. Each technology contributes to faster, smarter trial decisions. Innovation continues to strengthen technology versatility.
By Application-Based Insights
Patient recruitment remains the top AI use case, helping sponsors reach qualified participants faster. Biomarkers identification gains traction as AI refines target population definitions. Trial design optimization supports adaptive protocols and simulation. Data management tools ensure real-time validation and anomaly detection. It improves workflow efficiency and data reliability. AI enables tighter integration between trial components. Sponsors automate manual tasks across applications. These functions drive operational performance across trial ecosystems.
Segmentation:
By Phase
- Phase I
- Phase II
- Phase III
- Phase IV
By Indication
- Oncology
- Neurology
- Cardiology
- Rare Diseases
By Technology
- Machine Learning
- Deep Learning
- Natural Language Processing
By Application
- Patient Recruitment
- Biomarkers Identification
- Trial Design Optimization
- Data Management
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Leads with Strong Infrastructure and AI Adoption Rates
North America holds the largest share of the AI in Clinical Trials Market, accounting for approximately 45% of global revenue. The region benefits from a mature clinical trial ecosystem and early AI adoption among pharmaceutical firms and CROs. The U.S. drives growth with supportive regulatory frameworks, advanced EHR systems, and high R&D investment. Leading companies and AI startups operate from key hubs such as Boston and San Francisco. The presence of large patient databases improves trial precision and speeds up data analysis. It continues to lead global innovation in AI-powered trial execution and real-world data integration.
Europe Demonstrates Steady Growth Through Regulatory Support and Research Collaboration
Europe captures around 25% of the market share, supported by collaborative research networks and increasing investment in digital health. Countries like Germany, the UK, and France promote AI-driven trial platforms through public-private initiatives. The AI in Clinical Trials Market grows steadily here due to the region’s focus on ethical AI use and compliance with GDPR. National health systems offer structured clinical data that supports machine learning and NLP tools. Academic institutions and CROs adopt AI to enhance patient recruitment and reduce dropout rates. It benefits from rising acceptance of decentralized and hybrid trial models.
Asia Pacific Emerges as a High-Growth Region with Expanding Clinical Trial Footprint
Asia Pacific accounts for nearly 18% of the global market and is the fastest-growing region. China, India, South Korea, and Japan invest heavily in clinical research and digital infrastructure. The region attracts global trials due to large patient populations and cost-efficient operations. It supports AI deployment across Phase II and III trials in oncology and rare diseases. Local companies develop AI tools tailored for multilingual and diverse populations. Government initiatives encourage digital health innovation and trial modernization. The market sees significant expansion as AI integration improves trial scalability and data access.
Key Player Analysis:
Competitive Analysis:
The AI in Clinical Trials Market remains competitive with a mix of tech innovators, CROs, and pharma-integrated AI platforms. Key players such as IQVIA, Medidata (Dassault Systèmes), and Saama hold strong positions through integrated data platforms and global reach. Companies like Phesi and Deep6.ai focus on predictive analytics and patient matching. AiCure leverages AI for patient monitoring using computer vision, while NVIDIA supports AI infrastructure across trial pipelines. Tempus AI leads in molecular data-driven trial solutions. It helps companies address site selection, cohort design, and real-world evidence generation. Strategic collaborations and AI-centered R&D pipelines strengthen market presence. Vendors differentiate through technology scalability, regulatory readiness, and therapeutic specialization.
Recent Developments:
- In February 2026, IQVIA expanded its AI-driven clinical research solutions through new commercial collaborations and partnerships tied to advanced data, including work with Amazon Web Services on cloud-based capabilities and recent acquisitions strengthening oncology and Phase I trial services.
- In June 2025, Medidata (Dassault Systèmes) launched an upgraded version of its AI-enabled clinical data platform, integrating advanced analytics for protocol optimization and synthetic control arm development. The update aimed to improve trial efficiency and decision accuracy across late-stage studies, particularly in oncology and rare disease research.
- In April 2025, Saama introduced a new AI module designed to enhance risk-based monitoring and trial performance forecasting. The product focused on early detection of site-level issues and protocol deviations, helping sponsors improve compliance and operational oversight during Phase II and Phase III trials.
Report Coverage:
The research report offers an in-depth analysis based on Phase, Indication, Technology, and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- AI adoption will expand across early discovery, feasibility, and post-marketing trial phases, enabling continuous data analysis throughout the development cycle.
- NLP tools will become essential for extracting insights from clinical notes, discharge summaries, and adverse event reports, improving real-world evidence generation.
- AI-powered trial simulations and synthetic control arms will reduce the need for traditional control groups, improving patient retention and trial ethics.
- Regulatory agencies will publish formal guidelines for validating AI models, encouraging standardized use and boosting stakeholder confidence.
- Federated learning will play a critical role in training cross-institutional AI models without compromising patient privacy or data sovereignty.
- Integration with wearables and digital biomarkers will enhance real-time monitoring, supporting adaptive trial designs and faster interim decisions.
- Pharma companies will increase co-development deals with AI startups to gain access to niche technologies tailored to oncology, neurology, and rare diseases.
- Automation in protocol authoring, patient consent generation, and submission documentation will reduce administrative workloads and trial setup time.
- AI platforms will offer multilingual interfaces and local compliance modules to support expanding clinical trial activities in Asia Pacific, Latin America, and Africa.
- Investment in explainable AI will strengthen adoption among CROs and trial sponsors, improving transparency, reproducibility, and stakeholder trust in AI-driven decisions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for AI in Precision Medicine Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the AI in Precision Medicine Market projected to grow between 2025 and 2032?
Which AI in Precision Medicine Market segment held the largest share in 2025?
What are the primary factors fueling the growth of the AI in Precision Medicine Market?
Who are the leading companies in the AI in Precision Medicine Market?
Which region commanded the largest share of the AI in Precision Medicine Market in 2025?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
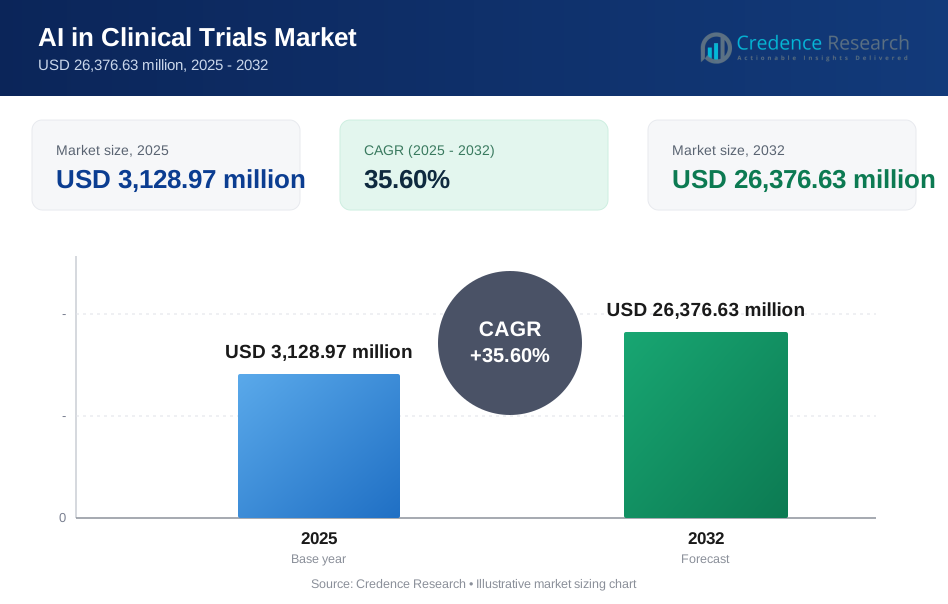
- 2.5.1 2025: USD 3,128.97 million → 2032: USD 26,376.63 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global AI in Clinical Trials Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global AI in Clinical Trials Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global AI in Clinical Trials Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global AI in Clinical Trials Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global AI in Clinical Trials Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global AI in Clinical Trials Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global AI in Clinical Trials Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global AI in Clinical Trials Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 3,128.97 million → 2032: USD 26,376.63 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global AI in Clinical Trials Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global AI in Clinical Trials Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global AI in Clinical Trials Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global AI in Clinical Trials Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

