
Anti-infectives market pivots to resistance and HIV care
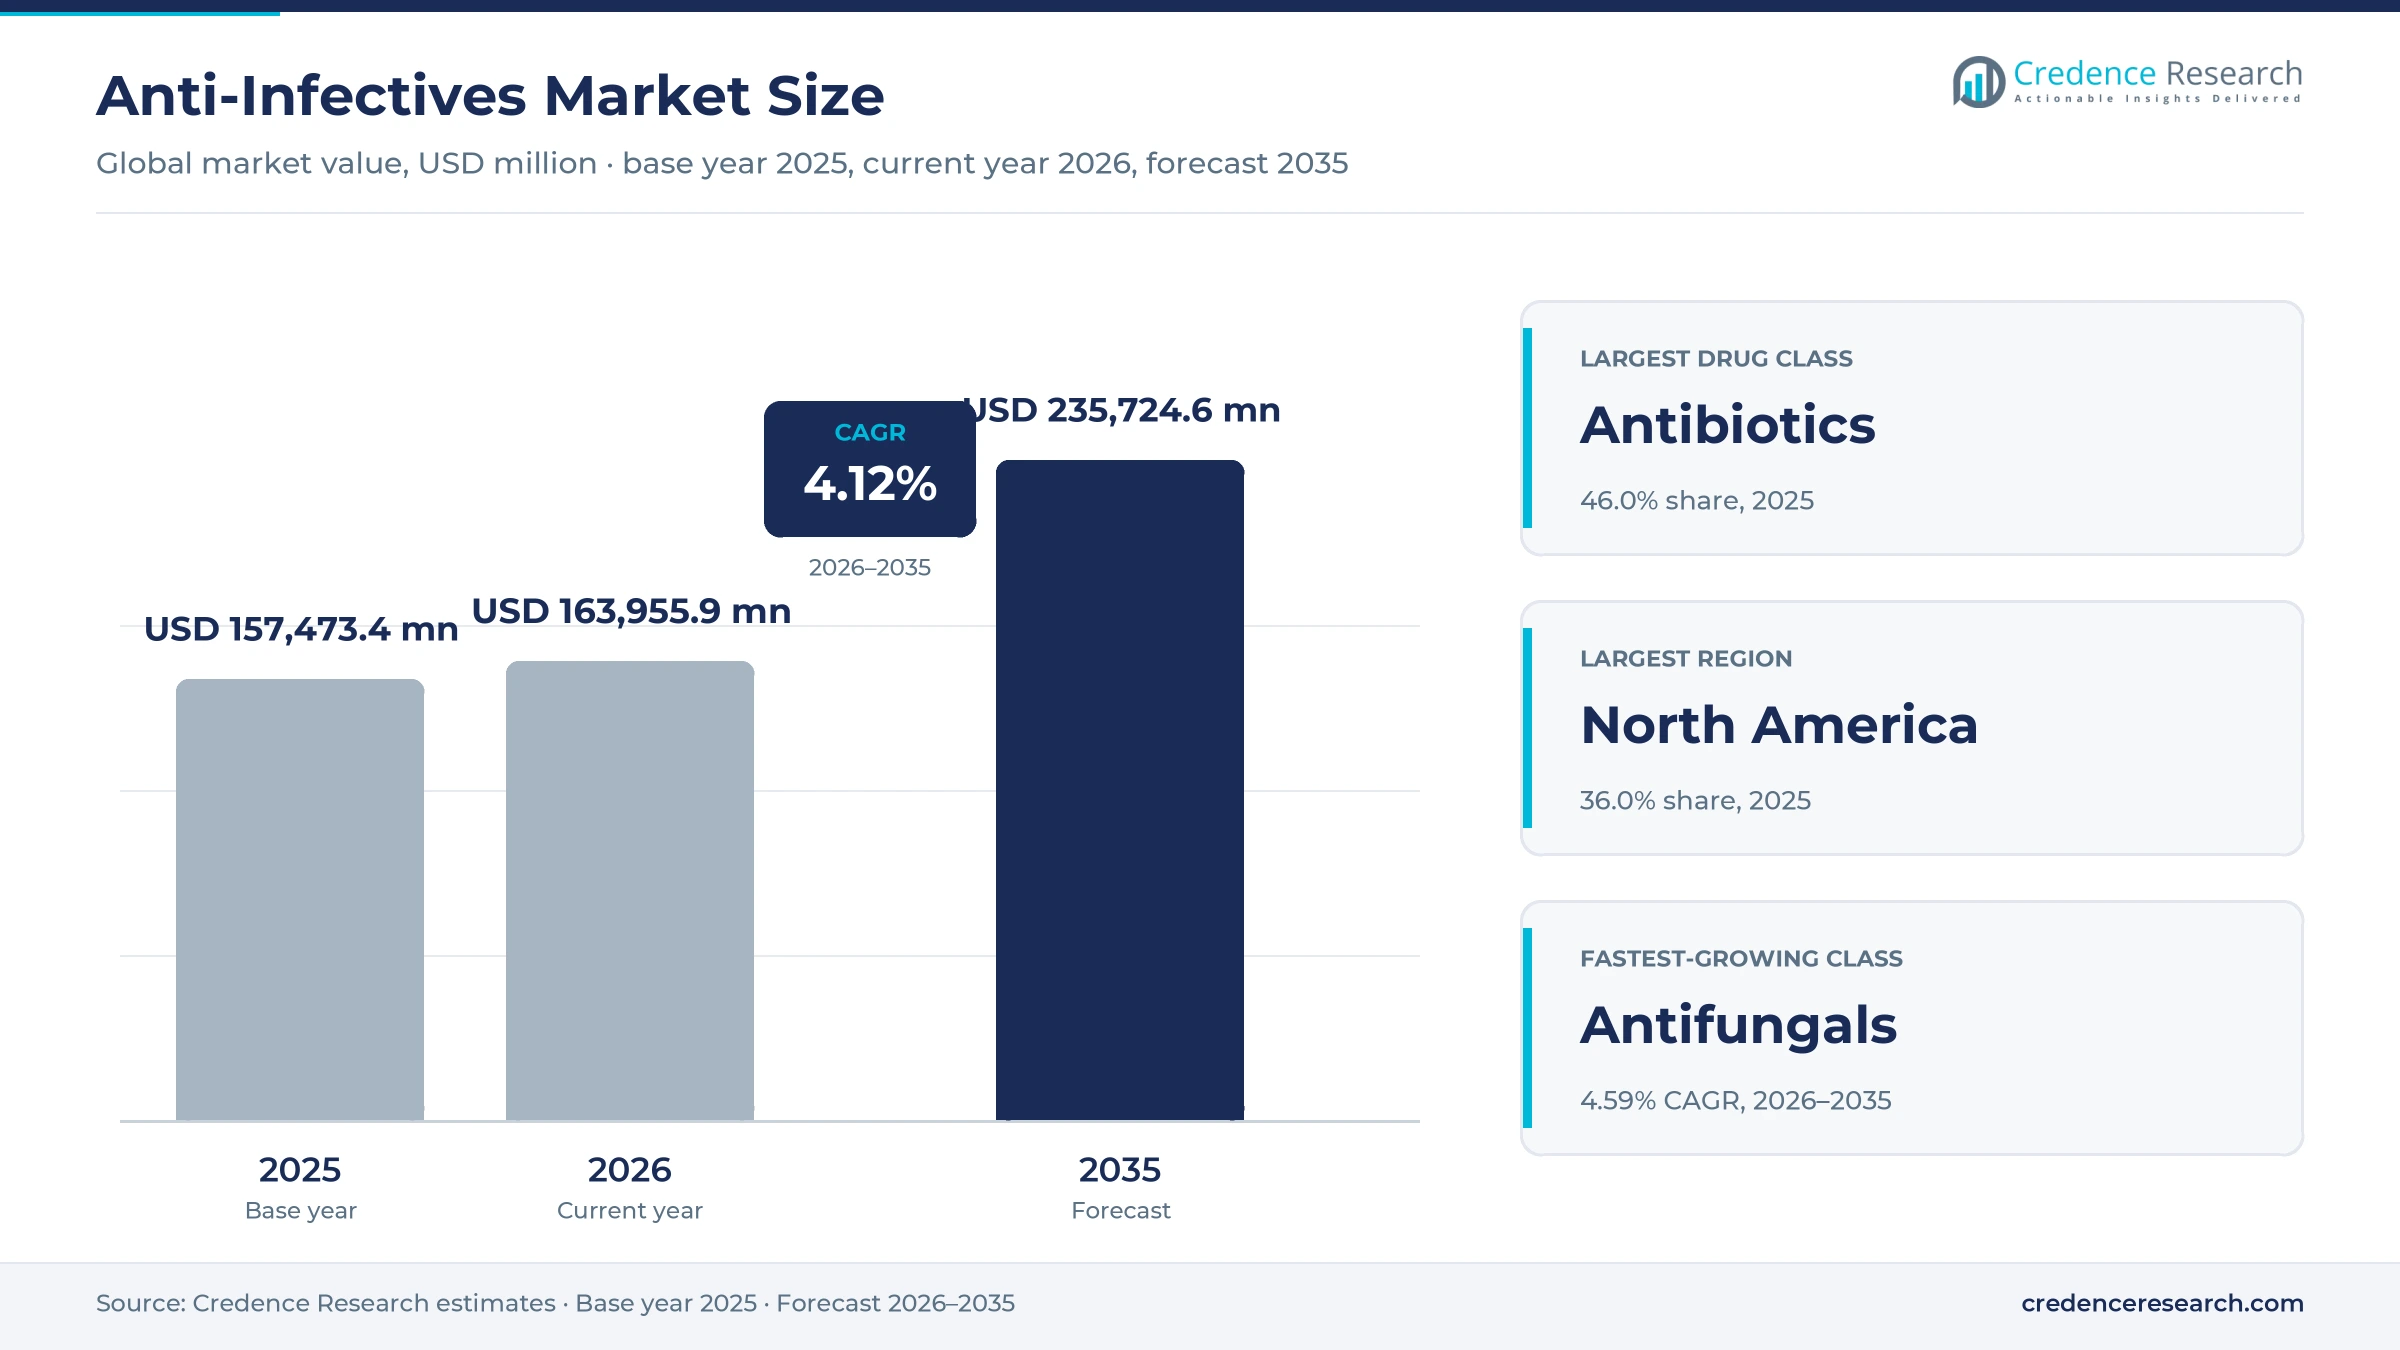
The global anti-infectives market was valued at USD 157.47 billion in 2025 and is projected to increase from USD 163.96 billion in 2026 to USD 235.72 billion by 2035, registering a CAGR of 4.12% during 2026–2035. Demand rests on a large base of bacterial infections treated in hospitals and clinics, lifelong antiretroviral therapy for HIV, and recurring respiratory virus seasons that keep antiviral stocks moving. North America held the largest regional share, 36.0% in 2025, because branded HIV regimens and hospital antibiotics command higher prices there than elsewhere. Asia Pacific is the fastest-growing region at 5.10% a year, as insurance coverage widens and generic makers in India and China expand supply. The commercial picture changed in 2025, when U.S. regulators cleared the first twice-yearly HIV prevention injection and a first-in-class oral antibiotic for urinary infections. As a result, value is tilting toward long-acting antivirals and novel antibacterials that address resistant pathogens.
Which medicines and buyers does this analysis cover?
The analysis counts prescription antibiotics, antivirals, antifungals and antiparasitics used to treat or prevent infections in people, valued at manufacturer selling prices. Hospitals buy most parenteral agents through tenders and group purchasing contracts, while retail and online pharmacies dispense oral courses against prescriptions written in primary care. HIV medicines are counted for both treatment and pre-exposure prophylaxis, because the same originators and generic suppliers serve both uses.
Vaccines, disinfectants, antiseptics and veterinary antimicrobials sit outside the scope of this analysis. The value chain runs from active ingredient producers in India and China through formulators and originator brands to wholesalers, hospital pharmacies and payers that set reimbursement and stewardship rules.
Anti-Infectives Market Insights
- The anti-infectives market grows from USD 157.47 billion in 2025 to USD 235.72 billion by 2035, a 4.12% CAGR built on resistant infections and long-acting HIV medicines.
- North America held 36.0% of global anti-infective value in 2025, supported by branded HIV regimens, hospital antibiotic use and higher net prices.
- Antibiotics led drug classes with 46.0% of 2025 value, although antifungals grow fastest at 4.59% a year as invasive fungal infections rise.
- In March 2025, U.S. regulators approved gepotidacin, the first new oral antibiotic class for uncomplicated urinary tract infections in nearly 30 years.
- Gilead's twice-yearly lenacapavir, approved for HIV prevention in June 2025 and licensed to six generic makers, pairs premium pricing with tiered global access.
Antibiotics lead while antifungals and UTI drugs gain pace
Why do antibiotics still hold the largest drug class share?
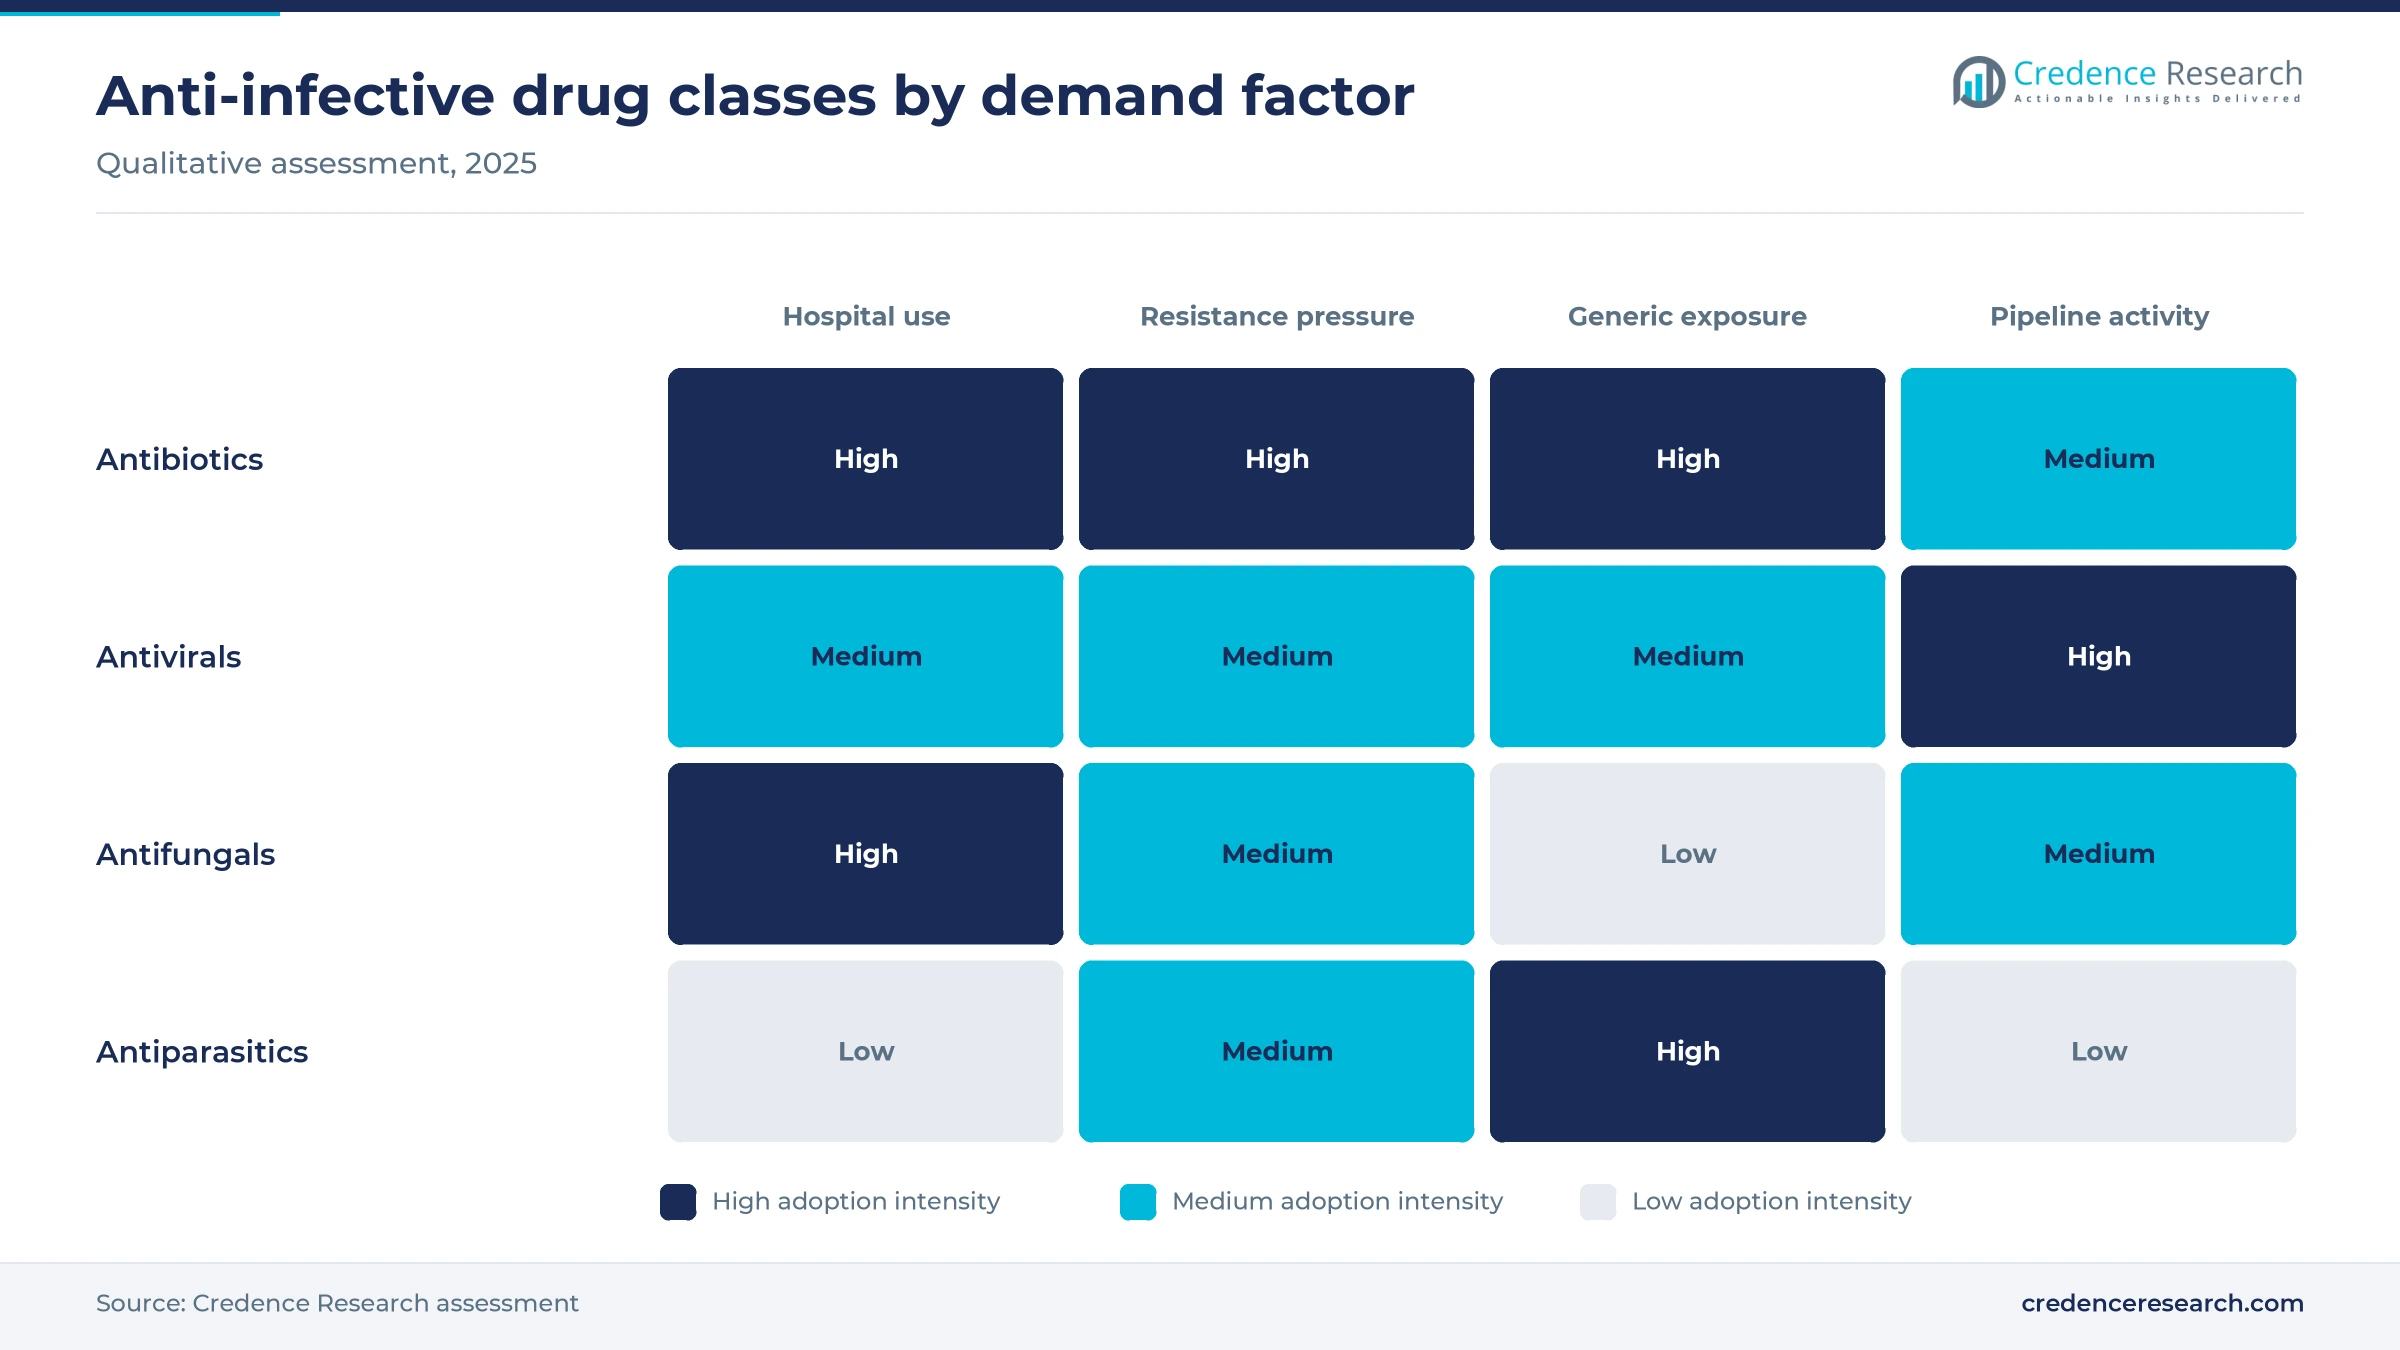
Based on drug class, the market is categorized into antibiotics, antivirals, antifungals and antiparasitics. Antibiotics led with a 46.0% share of 2025 value, because they treat the widest range of hospital and community infections. Antifungals grow fastest at 4.59% a year, since invasive fungal infections are rising among cancer, transplant and intensive care patients. Antivirals hold a large and steady base, anchored by lifelong HIV therapy and seasonal influenza treatment.
Which infections account for the most treatment spending?
Based on indication, the market is categorized into HIV infection, pneumonia, respiratory virus infection, sepsis, urinary tract infection, skin and soft-tissue infections and others. HIV Infection led with a 26.0% share of 2025 value, because patients stay on combination antiretroviral therapy for life. Urinary Tract Infection grows fastest at 4.67% a year, as new oral agents reach women with resistant or recurrent infections. Respiratory virus spending has normalized since the pandemic peak, so its growth trails the other indications.
How is long-acting dosing changing the route mix?
Based on route of administration, the market is categorized into oral, parenteral, topical, inhalation and other routes. Oral products led with a 52.0% share of 2025 value, because most community infections and HIV regimens are treated with tablets. Parenteral products grow fastest at 4.60% a year, helped by long-acting injectable antiretrovirals and intravenous reserve antibiotics. Topical and inhaled products serve narrower dermatology and respiratory niches with modest growth.
Where do patients and hospitals buy these medicines?
Based on distribution channel, the market is categorized into hospital pharmacies, retail pharmacies, online pharmacies and others. Hospital Pharmacies led with a 44.0% share of 2025 value, because intravenous antibiotics, antifungals and sepsis treatment start on the ward. Online Pharmacies grow fastest at 6.10% a year, as mail-order HIV refills and telehealth prescribing move volume away from store counters. Retail pharmacies remain the main outlet for short oral courses written in primary care.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Drug Class | Antibiotics | 46.0% | Antifungals | 4.59% |
| By Indication | HIV Infection | 26.0% | Urinary Tract Infection | 4.67% |
| By Route of Administration | Oral | 52.0% | Parenteral | 4.60% |
| By Distribution Channel | Hospital Pharmacies | 44.0% | Online Pharmacies | 6.10% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Resistance, HIV prevention and aging patients lift demand
How is antimicrobial resistance raising demand for newer agents?
Resistance is the strongest single driver of value, because resistant infections push prescribers from cheap generics toward newer branded agents. The World Health Organization announced in October 2025 that one in six laboratory-confirmed bacterial infections worldwide in 2023 were resistant to antibiotic treatment. More than 40% of E. coli and over 55% of K. pneumoniae isolates are now resistant to third-generation cephalosporins, the first-choice treatment. As a result, hospitals are adding reserve agents and new combinations that cost far more than first-line drugs, which raises spending per patient.
Why does lifelong HIV therapy keep antiviral demand stable?
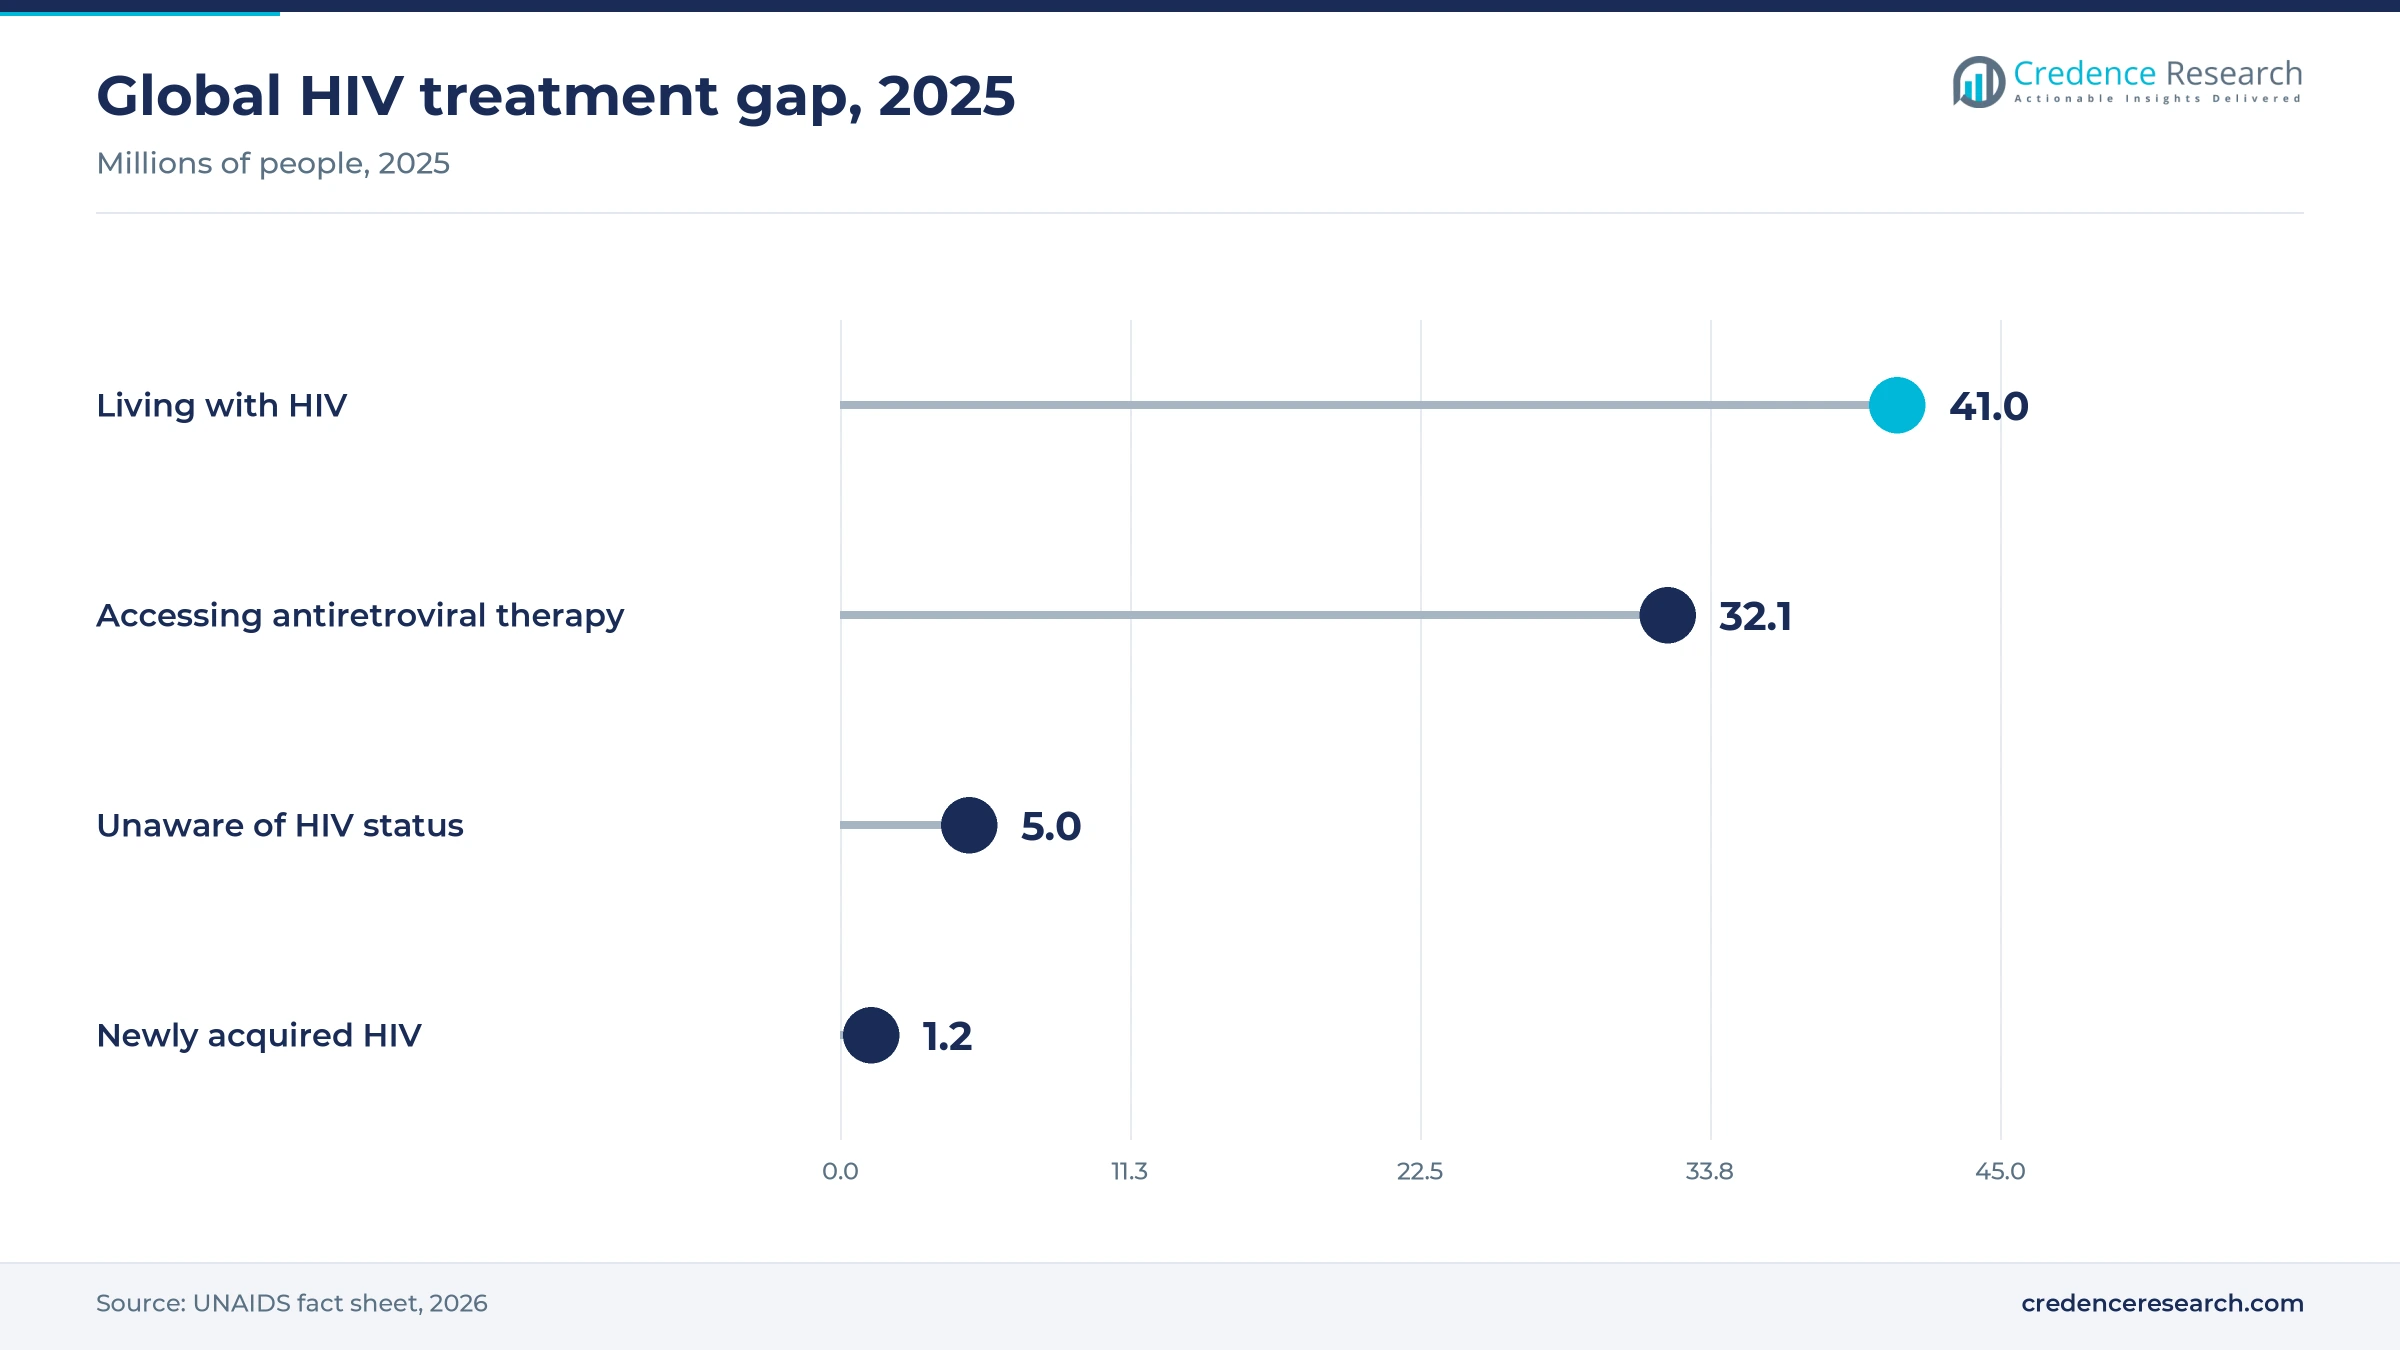
HIV treatment and prevention form a recurring demand base, because people living with HIV take antiretrovirals every day for life. According to the UNAIDS global HIV fact sheet, 41.0 million people were living with HIV in 2025 and 32.1 million were accessing antiretroviral therapy. This gap of roughly 8.9 million people, including about 5.0 million who did not know their status, is unmet demand that programs and donors aim to close. In turn, generic fixed-dose combinations expand volume in Africa and Asia, while branded regimens hold value in high-income countries.
How does an aging population lift infection treatment volumes?
Aging populations lift treatment volumes, because older adults face higher rates of pneumonia, urinary tract infections, sepsis and shingles. This demand is concentrated in Japan, Western Europe and North America, where adults aged 65 and over make up a growing share of hospital admissions. Older patients also carry more catheters, implants and chronic conditions that raise the risk of hospital-acquired infections. As a result, hospitals buy more intravenous antibiotics and antifungals per admission, a pattern that strengthens through the 2030s.
Why are new oral agents for urinary infections expanding the market?
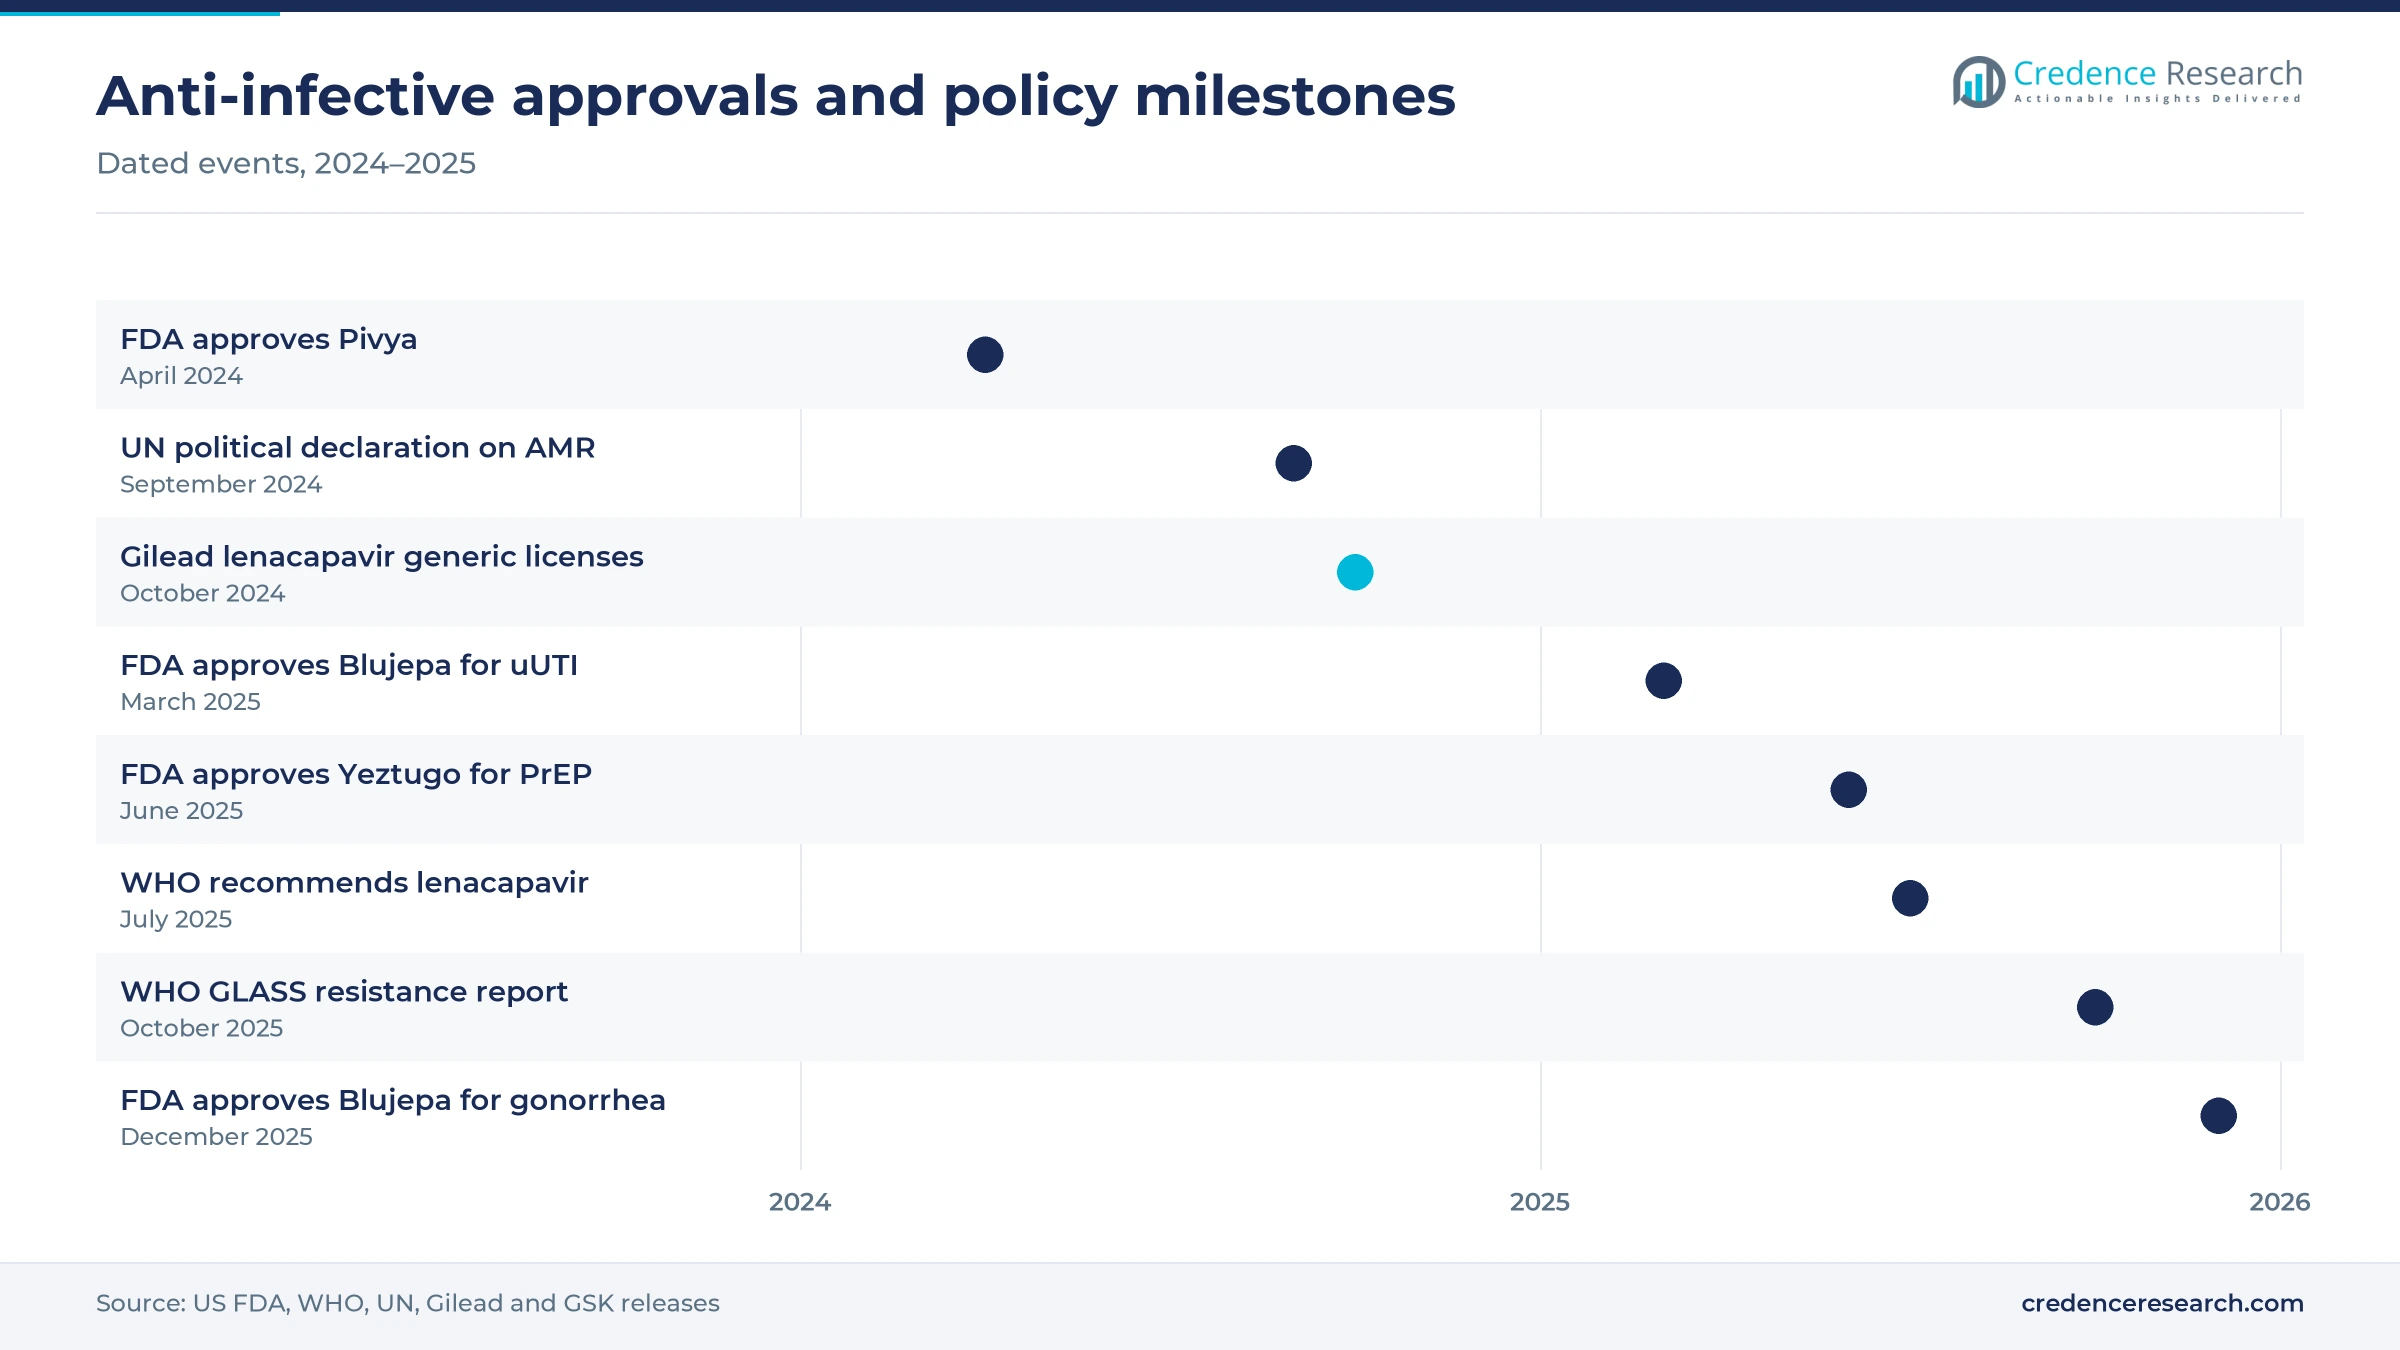
Urinary tract infections are a large outpatient indication, and GSK estimates that uncomplicated cases affect up to 16 million women in the U.S. each year. In April 2024, the U.S. Food and Drug Administration approved Pivya (pivmecillinam) tablets for uncomplicated urinary tract infections in adult women. Rising resistance to older oral drugs had created room for this kind of new branded option. Because these drugs keep patients at home, payers and prescribers in the United States are adopting them first, and growth follows in other regions.
Long-acting antivirals and new oral antibiotic classes rise
Is twice-yearly HIV prevention shifting the antiviral mix?
Long-acting dosing is the clearest shift in antiviral prescribing, because it removes the daily pill burden that limits adherence. In June 2025, the U.S. Food and Drug Administration approved Gilead's Yeztugo (lenacapavir) as the first twice-yearly injection for HIV pre-exposure prophylaxis in people weighing at least 35 kilograms. The World Health Organization then recommended injectable lenacapavir as an additional prevention option in July 2025. This shift moves value toward parenteral products and clinic-administered dosing, and it raises the share of spending that flows through specialty pharmacies.
Are first-in-class oral antibiotics returning to primary care?
New mechanisms of action are emerging in oral antibiotics after decades in which most launches targeted hospital use. GSK's Blujepa (gepotidacin) received U.S. approval in March 2025 as the first new oral class for uncomplicated urinary tract infections in nearly 30 years, and it was cleared again in December 2025 for uncomplicated urogenital gonorrhea. This rise of oral first-in-class agents matters, because primary care prescriptions reach far more patients than hospital formularies. As a result, branded antibiotic spending is increasing in retail and online channels as well as on wards.
Where can generic makers capture growth in HIV prevention access?
Generic manufacturers have a clear opening in high-incidence, resource-limited countries, where donors fund large volumes at low prices. In October 2024, Gilead signed royalty-free licenses with six generic makers, including Dr. Reddy's Laboratories, to supply lenacapavir in 120 primarily low- and lower-middle-income countries. This model gives Indian producers, which already supply a large share of donor-funded antiretrovirals, a route into long-acting products. In turn, volume growth in Africa and South Asia offsets lower prices for suppliers that win donor tenders.
Can antifungal pipelines open a premium hospital niche?
Antifungals offer an opening for companies with novel agents, because invasive fungal infections carry high mortality and few treatment options. Patients receiving chemotherapy, organ transplants or intensive care face the highest risk, and hospitals in North America, Europe and Japan pay premium prices for effective therapy. Astellas and Pfizer already hold established antifungal franchises, and newer agents are moving through late-stage trials. As a result, antifungals can grow faster than the overall market, provided developers secure formulary listings and stewardship approval.
Weak antibiotic returns and stewardship curb value
Why do new antibiotics struggle to earn a return?
Weak commercial returns remain the main barrier, because stewardship rules reserve new antibiotics for resistant cases and keep volumes low. In September 2024, world leaders at the UN General Assembly committed to cut the estimated 4.95 million deaths associated with bacterial resistance by 10% by 2030. The same declaration set a target that at least 70% of human antibiotic use should come from the WHO Access group, which carries a lower resistance risk. This goal protects public health, but it limits early volumes for new branded agents.
How does generic price erosion limit value growth?
Generic price erosion caps value growth across older antibiotics and antiretrovirals, because dozens of manufacturers compete in tenders for the same molecules. In India and China, active ingredient producers keep costs low, and buyers in Latin America and Africa award contracts mainly on price. This pressure means volume growth does not translate into proportional value growth. As a result, companies offset erosion by launching combination products, pediatric formulations and long-acting versions that carry better margins.
Do supply shortages put basic antibiotics at risk?
Supply concentration is a persistent risk, because a few active ingredient plants in China and India supply many essential antibiotics worldwide. Low prices leave little margin for redundant capacity, so a single plant failure can trigger shortages of amoxicillin or penicillin across several countries. Regulators in Europe and the United States have responded with shortage lists and stockpiling guidance for critical medicines. However, these measures add cost for manufacturers, and the pressure on margins is highest in pediatric formulations.
Why does access remain limited in high-burden regions?
Access gaps constrain growth where the burden is highest, because many patients in low-income countries cannot pay for newer agents. The World Health Organization estimates that one in three reported infections were resistant in its South-East Asia and Eastern Mediterranean regions in 2023. In the African Region, resistance to first-choice cephalosporins exceeds 70%, yet diagnostic networks and spending per patient remain the weakest. In turn, companies rely on tiered pricing, licensing and donor funding to reach these patients, which limits revenue per treatment course.
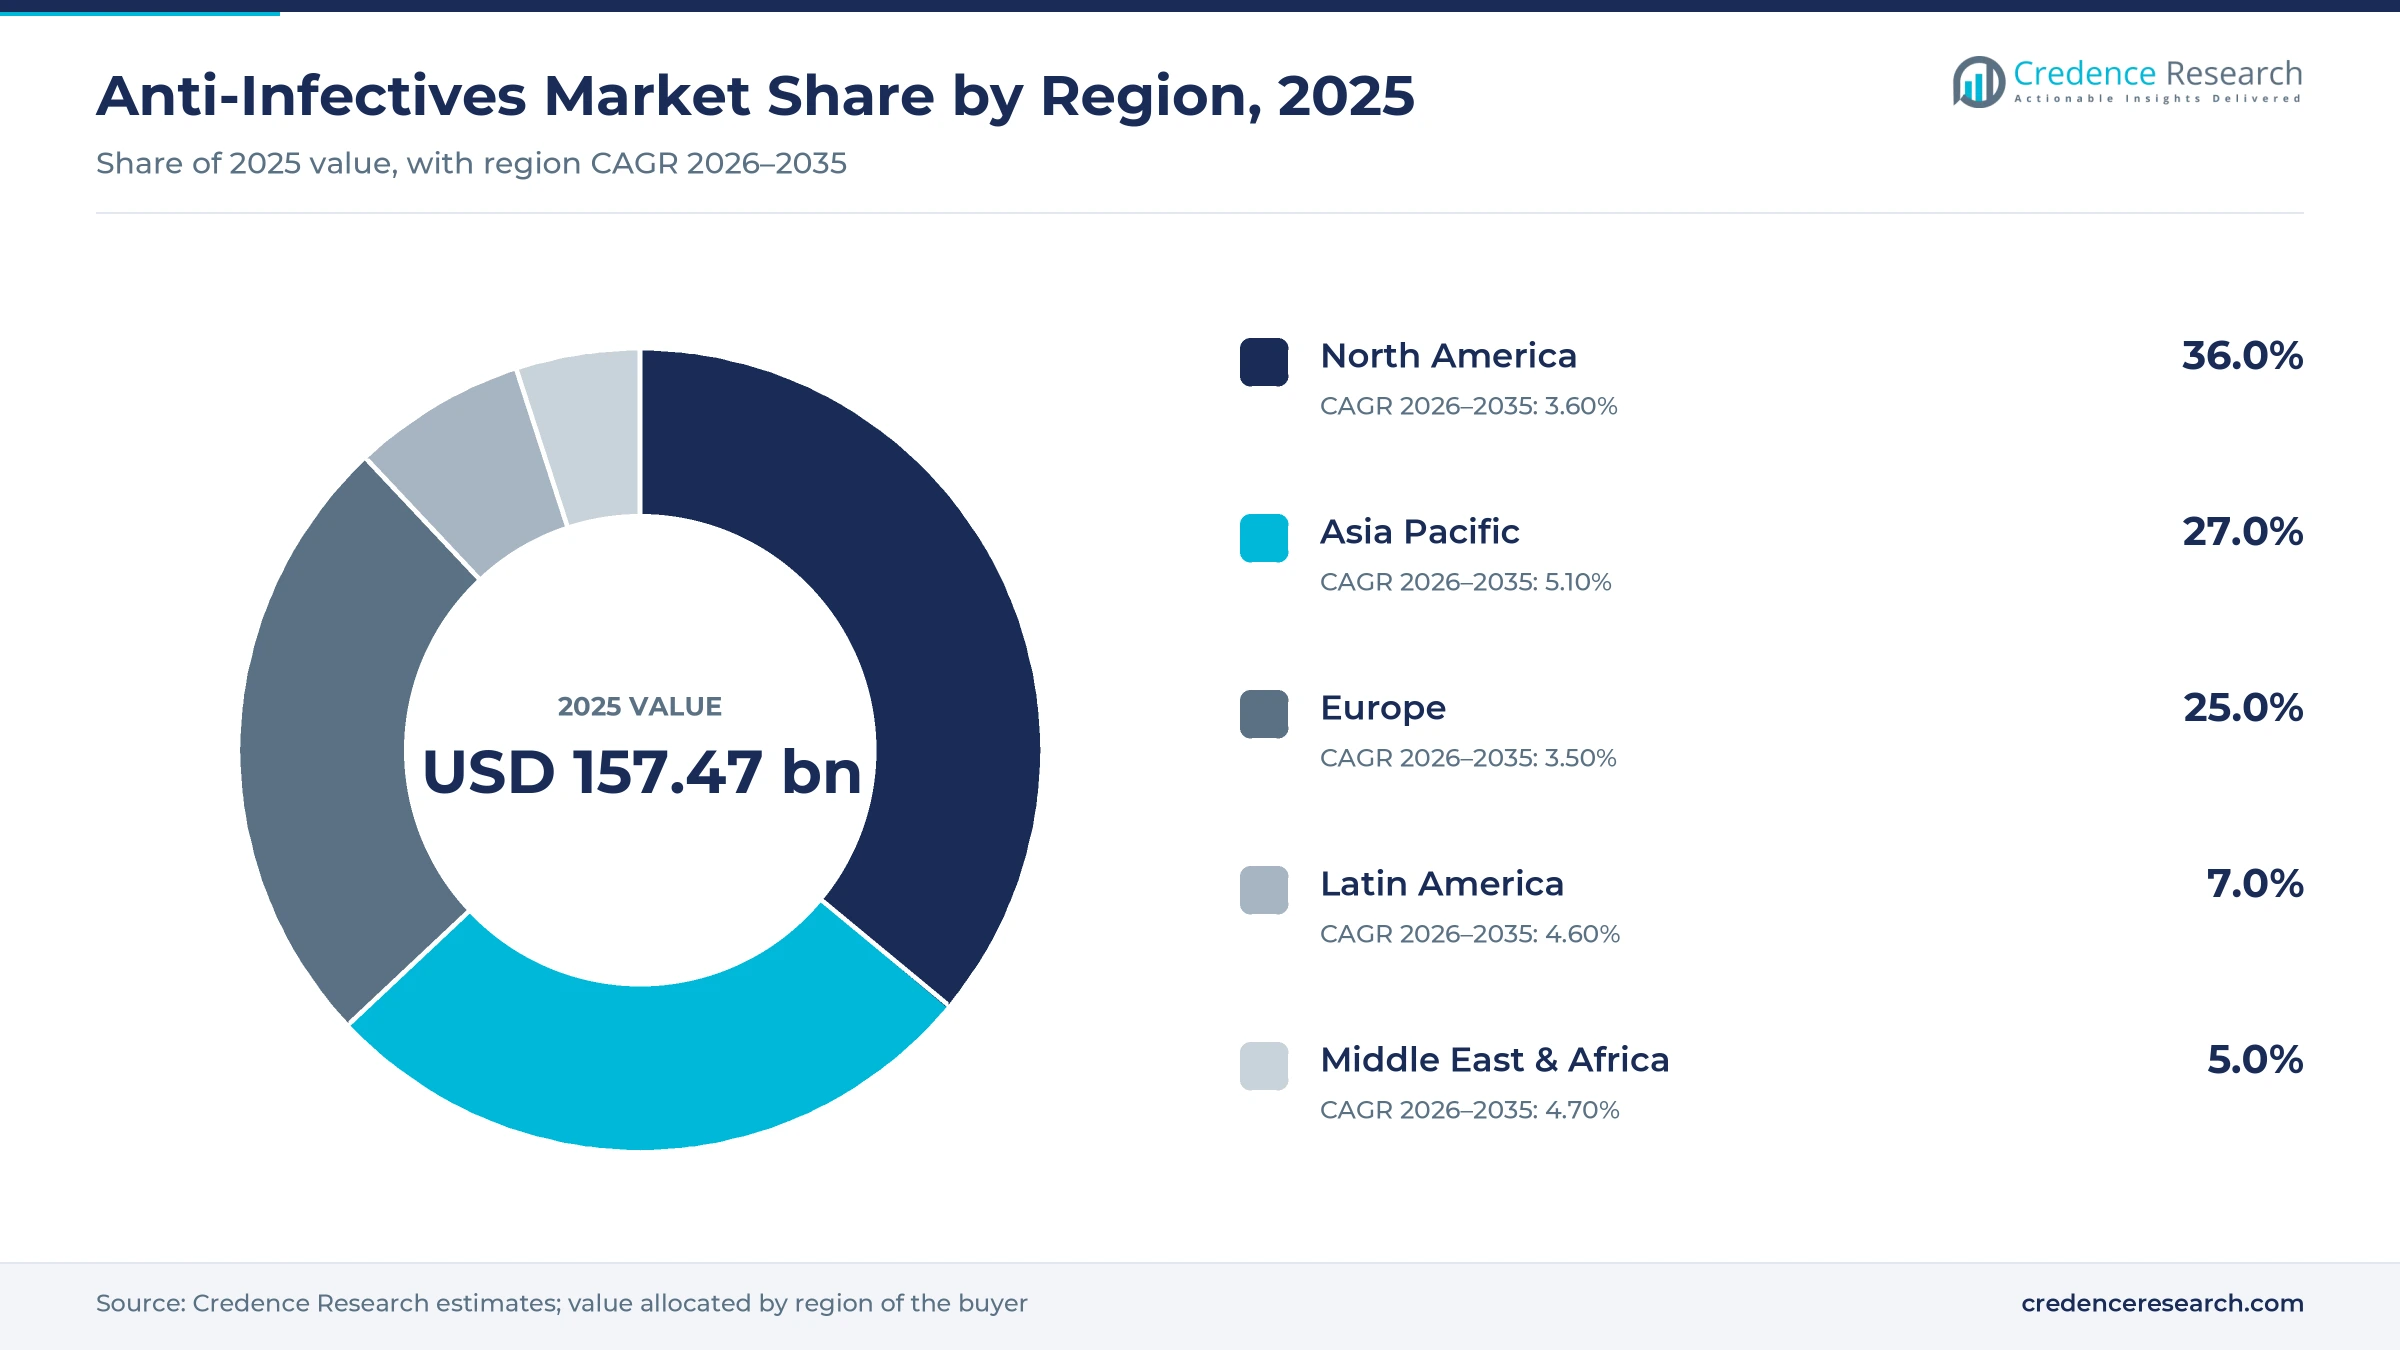
North America leads as Asia Pacific gains on access
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 56.69 | 36.0% | 3.60% |
| Asia Pacific | 42.52 | 27.0% | 5.10% |
| Europe | 39.37 | 25.0% | 3.50% |
| Latin America | 11.02 | 7.0% | 4.60% |
| Middle East & Africa | 7.87 | 5.0% | 4.70% |
Why does North America hold the largest regional share?
North America held a 36.0% share of 2025 value and grows at 3.60% a year through 2035. The United States drives this position, because branded HIV regimens, long-acting prevention and novel hospital antibiotics sell at the highest net prices in the world. Recent U.S. approvals for urinary tract infection and HIV prevention products reach this region first. However, generic substitution in older antibiotics and payer pressure on antiretroviral prices keep regional growth below the global rate.
How fast is Asia Pacific catching up?
Asia Pacific held a 27.0% share of 2025 value and is the fastest-growing region at 5.10% a year. China and India combine large infection burdens with expanding insurance coverage, which lifts the number of patients treated with branded and generic agents. India is also a leading supplier of generic antiretrovirals and antibiotics, giving companies such as Lupin, Dr. Reddy's and Glenmark scale at home and abroad. Japan adds a high-value hospital market for antifungals and reserve antibiotics.
What shapes demand across Europe?
Europe held a 25.0% share of 2025 value and grows at 3.50% a year, the slowest pace of the five regions. Strong stewardship programs and centralized tenders hold down antibiotic volumes and prices across Germany, France, the United Kingdom and the Nordic countries. However, the region leads on pull incentives, with subscription-style payments being tested to reward new antibiotics. HIV treatment remains a stable block of spending, as most diagnosed patients in Western Europe are already on therapy.
Where is Latin America adding demand?
Latin America held a 7.0% share of 2025 value and grows at 4.60% a year through 2035. Brazil and Mexico lead regional demand, supported by public HIV programs that buy antiretrovirals centrally and by rising hospital use of broad-spectrum antibiotics. Resistance in intensive care units is pushing hospitals toward newer combinations, although budget limits slow adoption.
What limits growth in the Middle East and Africa?
The Middle East and Africa held a 5.0% share of 2025 value and grows at 4.70% a year through 2035. Sub-Saharan Africa carries the largest HIV burden in the world, but donor-funded generics keep spending per patient low. Gulf states add higher-value hospital demand for reserve antibiotics and antifungals in modern tertiary care centers.
Approvals and access deals reshaping infection care
| Development | Status and market relevance |
|---|---|
| In October 2024, Gilead signed royalty-free voluntary licensing agreements with six generic manufacturers, including Dr. Reddy's Laboratories, for lenacapavir in 120 countries. | Licenses in place; sets the access model for long-acting HIV prevention in low- and lower-middle-income countries |
| In March 2025, GSK announced U.S. Food and Drug Administration approval of Blujepa (gepotidacin) for uncomplicated urinary tract infections in women and girls 12 and older. | Approved in the U.S.; first new oral antibiotic class for this use in nearly 30 years |
| In June 2025, Gilead announced U.S. Food and Drug Administration approval of Yeztugo (lenacapavir) for HIV pre-exposure prophylaxis. | Approved in the U.S.; first twice-yearly HIV prevention option |
| In July 2025, the World Health Organization announced guidelines recommending injectable lenacapavir as an additional HIV prevention option. | Guideline issued; supports procurement by national programs and donors |
| In December 2025, GSK announced a second U.S. approval for Blujepa, covering uncomplicated urogenital gonorrhea. | Approved in the U.S.; first new antibiotic class for gonorrhea in over three decades |
Novel mechanisms and twice-yearly dosing set the pipeline
- Capsid inhibitors such as lenacapavir allow dosing every six months, which reduces adherence gaps in both HIV treatment and prevention.
- Novel antibacterial mechanisms such as the triazaacenaphthylene class used in gepotidacin inhibit bacterial DNA replication at a distinct binding site, which helps against strains resistant to older drugs.
- Beta-lactamase inhibitor combinations pair established antibiotics with inhibitors that block resistance enzymes, which extends the useful life of proven molecules in intensive care.
- Rapid diagnostics that identify pathogens and resistance genes within hours let clinicians switch earlier from broad-spectrum to targeted therapy, which supports stewardship goals.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
HIV franchises and generic antibiotic makers split the field
Competition splits between originators that hold patented HIV, antifungal and novel antibacterial franchises and generic manufacturers that supply most volume. Gilead Sciences leads HIV treatment and prevention, while GlaxoSmithKline competes through ViiV Healthcare and its new oral antibiotic portfolio. Merck & Co. and Pfizer hold hospital antibiotic and antifungal brands, and Astellas Pharma remains strong in hospital antifungals. Bristol-Myers Squibb and Abbott Laboratories maintain legacy anti-infective lines, while Bayer, Novartis and Sanofi serve primary care antibiotic and antimalarial demand. Indian producers Lupin, Dr. Reddy's Laboratories and Glenmark Pharmaceuticals compete on price in generic antibiotics and antiretrovirals, and they increasingly win donor tenders in Africa and Asia. Companies compete through new mechanisms of action, long-acting formulations, voluntary licensing and tiered pricing. The 13 companies profiled below span originators, branded generics makers and generic specialists across three continents. However, stewardship rules limit how fast any new branded agent can gain volume.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Gilead Sciences Inc. | Originator | HIV treatment and twice-yearly lenacapavir prevention |
| GlaxoSmithKline plc | Originator | HIV through ViiV Healthcare and gepotidacin for urinary infections and gonorrhea |
| Merck & Co. Inc. | Originator | Hospital antibiotics, antifungals and HIV research |
| Pfizer Inc. | Originator | Hospital antibiotics, antifungals and COVID-19 antivirals |
| Astellas Pharma Inc. | Originator | Hospital antifungals |
| Bristol-Myers Squibb Co. | Originator | Legacy HIV and hepatitis B antivirals |
| Abbott Laboratories | Branded generics | Established antibiotics in emerging markets |
| Bayer AG | Originator | Fluoroquinolone antibiotics and anti-infective dermatology |
| Novartis AG | Originator and generics | Antimalarials and generic antibiotics |
| Sanofi SA | Originator | Antibiotics and antiparasitic treatments |
| Lupin Ltd. | Generics | Generic antibiotics, antituberculosis drugs and antiretrovirals |
| Dr. Reddy's Laboratories Ltd. | Generics | Generic antivirals and lenacapavir licensee |
| Glenmark Pharmaceuticals Ltd. | Generics | Generic antibiotics, antifungals and dermatology anti-infectives |
Value shifts to novel antibacterials and HIV prevention
Credence Research's view is that value in anti-infectives will concentrate in two places through 2035, novel agents for resistant bacterial infections and long-acting HIV medicines. Both segments command premium prices, because they solve problems that generics cannot solve, namely resistance and poor adherence. While the overall market grows at 4.12% a year, generic antibiotics will keep growing in volume, especially across Asia Pacific and Africa, but price erosion means their value share will drift lower. Companies that combine a differentiated product with a credible access plan, such as tiered pricing or voluntary licensing, are best placed to win both hospital formularies and donor tenders.
How Credence Research sized infection drug spending
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, which builds spending by drug class, indication, route of administration and distribution channel. Regional and segment splits are Credence Research estimates informed by regulator approvals, World Health Organization and UNAIDS surveillance data, and company press releases. No primary interviews or surveys were used in preparing this edition of the report.
Infection treatment spending outlook to 2035
By 2035, the anti-infectives market is projected to reach USD 235.72 billion, with growth tilted toward resistant bacterial infections, HIV prevention and invasive fungal disease. Long-acting injectables should take a larger share of antiviral spending as prevention programs scale in Africa, Asia and Latin America. New oral antibiotic classes are likely to widen branded use in primary care, although stewardship limits will keep volumes measured. Asia Pacific should add the largest number of new patients, while North America keeps the highest value per patient. As a result, advantage will depend on novel mechanisms, manufacturing scale and access partnerships.
Frequently Asked Questions
How big is the global anti-infectives market?
Which drug class leads the anti-infectives market?
Which region leads anti-infective spending?
How does antimicrobial resistance affect the market?
What is changing in HIV prevention?
Which indication accounts for the most spending?
Who are the leading anti-infective companies?
What restrains growth in anti-infectives?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Class
- 1.2.1 Antibiotics
- 1.2.2 Antivirals
- 1.2.3 Antifungals
- 1.2.4 Antiparasitics
- 1.3 By Indication
- 1.3.1 HIV Infection
- 1.3.2 Pneumonia
- 1.3.3 Respiratory Virus Infection
- 1.3.4 Sepsis
- 1.3.5 Urinary Tract Infection
- 1.3.6 Skin & Soft-Tissue Infections
- 1.3.7 Others
- 1.4 By Route of Administration
- 1.4.1 Oral
- 1.4.2 Parenteral
- 1.4.3 Topical
- 1.4.4 Inhalation
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 157.47 billion → 2035: USD 235.72 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Anti-Infectives Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Anti-Infectives Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Anti-Infectives Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Anti-Infectives Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Anti-Infectives Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Anti-Infectives Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Anti-Infectives Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Anti-Infectives Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 157.47 billion → 2035: USD 235.72 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Anti-Infectives Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Class - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Antibiotics
- 12.3.7.2 Antivirals
- 12.3.7.3 Antifungals
- 12.3.7.4 Antiparasitics
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Indication - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 HIV Infection
- 12.4.7.2 Pneumonia
- 12.4.7.3 Respiratory Virus Infection
- 12.4.7.4 Sepsis
- 12.4.7.5 Urinary Tract Infection
- 12.4.7.6 Skin & Soft-Tissue Infections
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Route of Administration - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oral
- 12.5.7.2 Parenteral
- 12.5.7.3 Topical
- 12.5.7.4 Inhalation
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Anti-Infectives Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2035
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Anti-Infectives Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Anti-Infectives Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Abbott Laboratories
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Astellas Pharma Inc.
- 17.4 Bayer AG
- 17.5 Bristol-Myers Squibb Co.
- 17.6 Gilead Sciences Inc.
- 17.7 GlaxoSmithKline plc
- 17.8 Merck & Co. Inc.
- 17.9 Novartis AG
- 17.10 Pfizer Inc.
- 17.11 Sanofi SA
- 17.12 Lupin Ltd.
- 17.13 Dr. Reddy's Laboratories Ltd.
- 17.14 Glenmark Pharmaceuticals Ltd.
- 17.15 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

