
Market Overview:
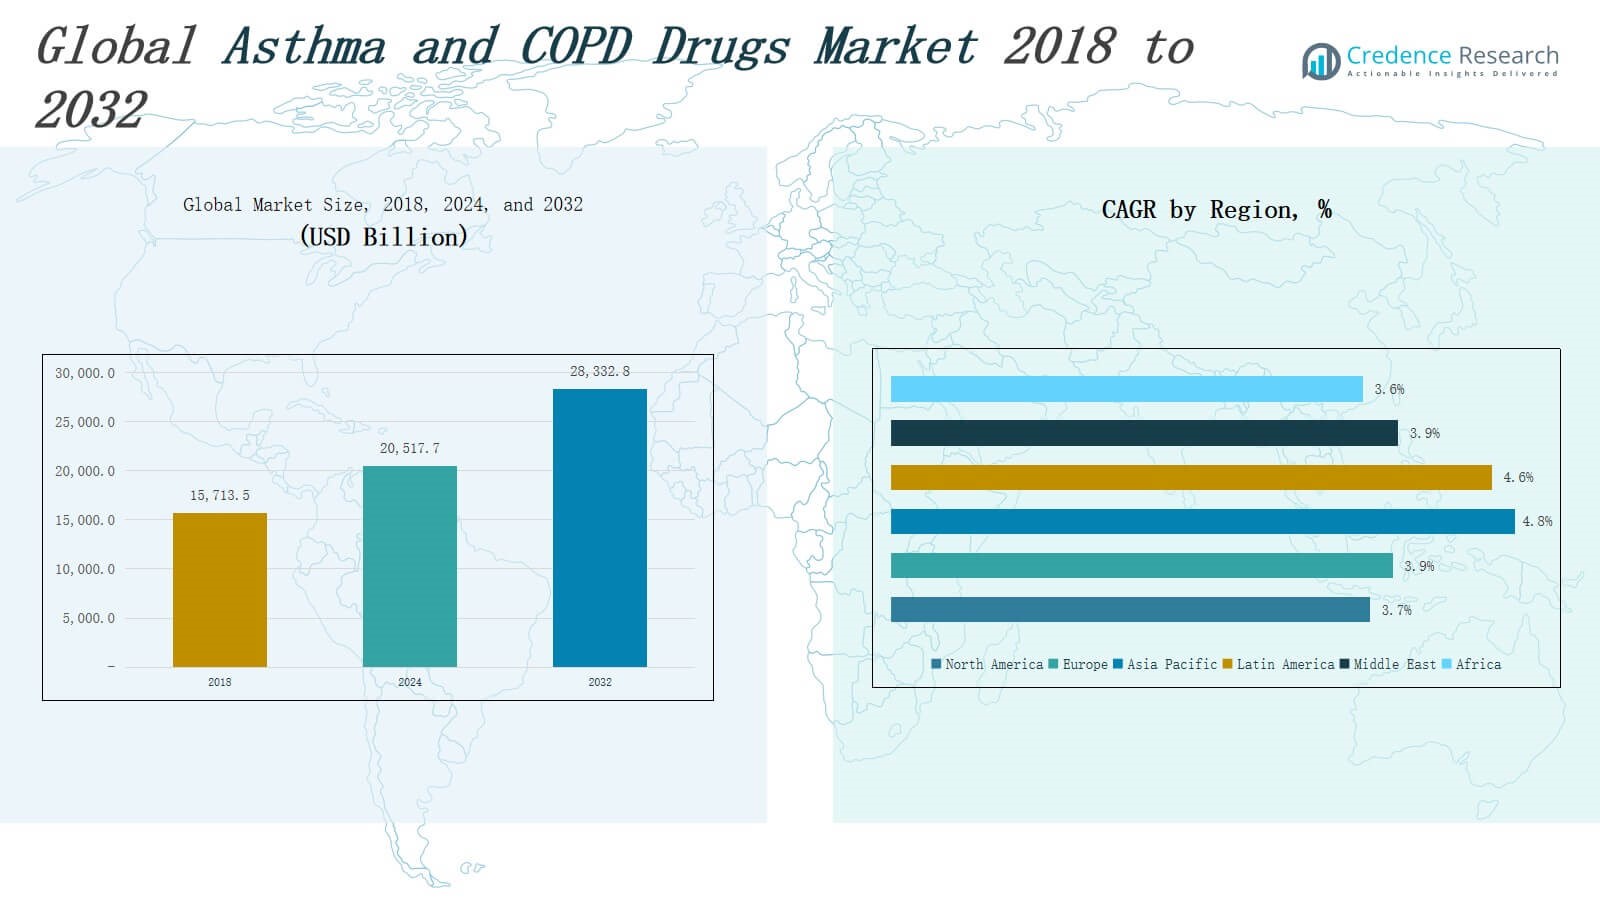
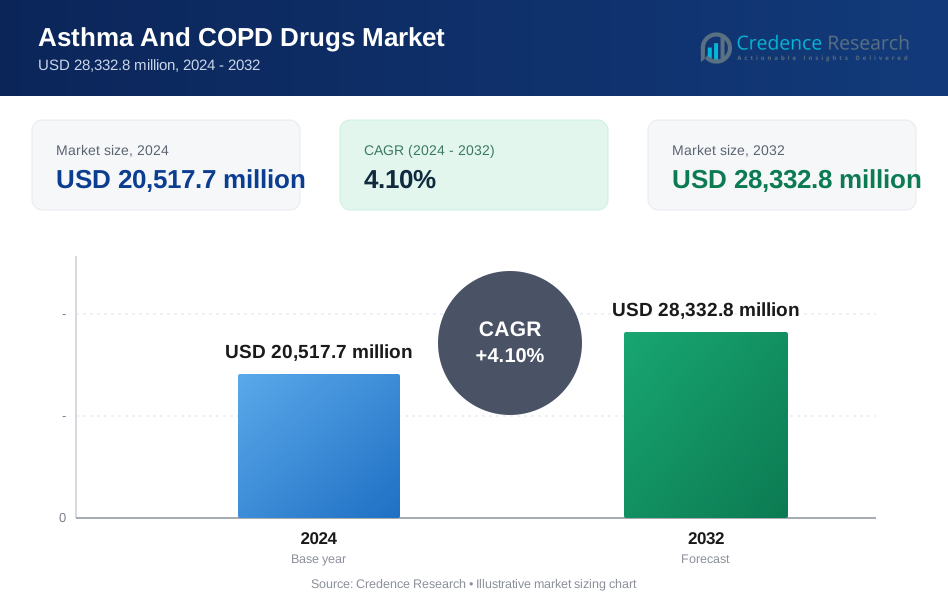
The Asthma and COPD Drugs Market size was valued at USD 15,713.5 million in 2018 to USD 20,517.7 million in 2024 and is anticipated to reach USD 28,332.8 million by 2032, at a CAGR of 4.10% during the forecast period.| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Asthma and COPD Drugs Market Size 2024 | USD 20,517.7 million |
| Asthma and COPD Drugs Market, CAGR | 4.10% |
| Asthma and COPD Drugs Market Size 2032 | USD 28,332.8 million |
Market Insights
- The Asthma and COPD Drugs Market was valued at USD 15,713.5 million in 2018, reached USD 20,517.7 million in 2024, and is projected to reach USD 28,332.8 million by 2032.
- Rising global prevalence of asthma and COPD, coupled with increasing pollution exposure and aging populations, is driving demand for both maintenance and rescue medications.
- Technological advancements such as smart inhalers and digital dose counters are improving treatment outcomes and enhancing patient adherence.
- The market is seeing strong investment in biologics and combination therapies offering targeted action with improved safety profiles.
- North America leads the market, followed by Europe, while Asia Pacific records the fastest growth due to urbanization, pollution, and expanding healthcare access.
- Major challenges include high treatment costs in low-income regions and regulatory delays that restrict access to novel drugs in emerging markets.
- Key players such as AstraZeneca, GSK, Boehringer Ingelheim, Novartis, Pfizer, and others are driving innovation and global market competition.
Market Drivers
Rising Prevalence of Chronic Respiratory Disorders The Asthma and COPD Drugs Market is primarily driven by the increasing global burden of chronic respiratory diseases. Growing air pollution levels, rising tobacco consumption, and occupational exposures are contributing to higher incidence rates, especially in urban areas. Asthma affects over 260 million people worldwide, while COPD remains a leading cause of death. The expanding patient population is fueling consistent demand for both maintenance and rescue medications. It presents substantial growth opportunities for pharmaceutical manufacturers.- For instance, AstraZeneca received regulatory approval to launch Breztri Aerosphere, a triple-combination inhaler containing budesonide, glycopyrronium, and formoterol, in India in January 2025, providing maintenance therapy to relieve symptoms and prevent exacerbations in COPD patients.
- For instance, GlaxoSmithKline’s Advair Diskus is widely prescribed for older adults with asthma and COPD, with millions of prescriptions annually in the United States, reflecting the high demand for combination inhaler therapies among the elderly.
Market Trends
Growing Adoption of Biologics and Targeted Therapies The Asthma and COPD Drugs Market is witnessing a shift toward biologics and targeted therapies, particularly for severe and treatment-resistant cases. Monoclonal antibodies such as mepolizumab, benralizumab, and dupilumab offer improved disease control by targeting specific inflammatory pathways. These therapies are expanding beyond asthma into subsets of COPD, showing promise in clinical trials. It is helping reduce exacerbation rates and steroid dependency. Market players are expanding pipelines to meet the rising demand for precision medicine.- For instance, GlaxoSmithKline’s mepolizumab (Nucala) has demonstrated a 53% reduction in annual exacerbation rates for severe eosinophilic asthma, according to Phase III clinical trials.
- For instance, Sanofi’s amlitelimab showed a reduction of more than 70% in asthma exacerbations at week 60 among patients with both high eosinophil and neutrophil counts in the TIDE-Asthma phase 2 study, with clinically meaningful improvements in lung function and asthma control.
Market Challenges Analysis
High Treatment Costs and Limited Access in Low-Income Regions The Asthma and COPD Drugs Market faces a major challenge in affordability and accessibility, particularly in low- and middle-income countries. Many advanced biologics and combination therapies remain unaffordable for a large portion of the global population. Limited healthcare infrastructure and lack of insurance coverage further restrict timely diagnosis and treatment. It creates a gap between innovation and equitable care delivery. Governments struggle to subsidize high-cost treatments, leading to under-treatment or reliance on outdated drugs. These barriers hinder long-term disease management and raise morbidity risks. Regulatory Complexities and Delayed Approvals for Novel Drugs Navigating diverse regulatory environments poses another significant challenge in the Asthma and COPD Drugs Market. New drug approvals require extensive clinical trials and post-marketing surveillance, often leading to long development timelines and high R&D expenditure. It delays the introduction of potentially life-saving therapies, especially in emerging markets with limited regulatory harmonization. Differences in labeling, pricing frameworks, and pharmacovigilance expectations add complexity for global market players. These hurdles impact the speed and efficiency of bringing innovative products to market.Market Opportunities
Expansion Potential in Emerging Markets and Underserved Populations The Asthma and COPD Drugs Market offers strong growth opportunities in emerging economies with large, untreated patient populations. Increasing awareness, expanding urbanization, and rising pollution levels are driving disease incidence in countries across Asia, Latin America, and Africa. Governments are improving healthcare infrastructure and encouraging public-private partnerships to enhance access. It creates a favorable environment for multinational pharmaceutical firms to introduce cost-effective therapies. Companies that tailor pricing strategies and localize manufacturing can gain significant market share. Addressing unmet needs in rural and peri-urban areas will further accelerate growth. Advancement in Personalized Medicine and Companion Diagnostics Personalized treatment strategies and biomarker-based diagnostics present long-term opportunities in the Asthma and COPD Drugs Market. With increasing understanding of inflammatory phenotypes and genetic predispositions, targeted therapies can deliver better outcomes with fewer adverse effects. It allows for optimized drug selection and dosage based on individual profiles. Companion diagnostic tools are gaining regulatory support, facilitating earlier intervention and patient stratification. Pharmaceutical companies can invest in R&D to develop niche therapies supported by real-time digital monitoring. This trend aligns with the growing shift toward precision healthcare across respiratory care pathways.Market Segmentation Analysis:
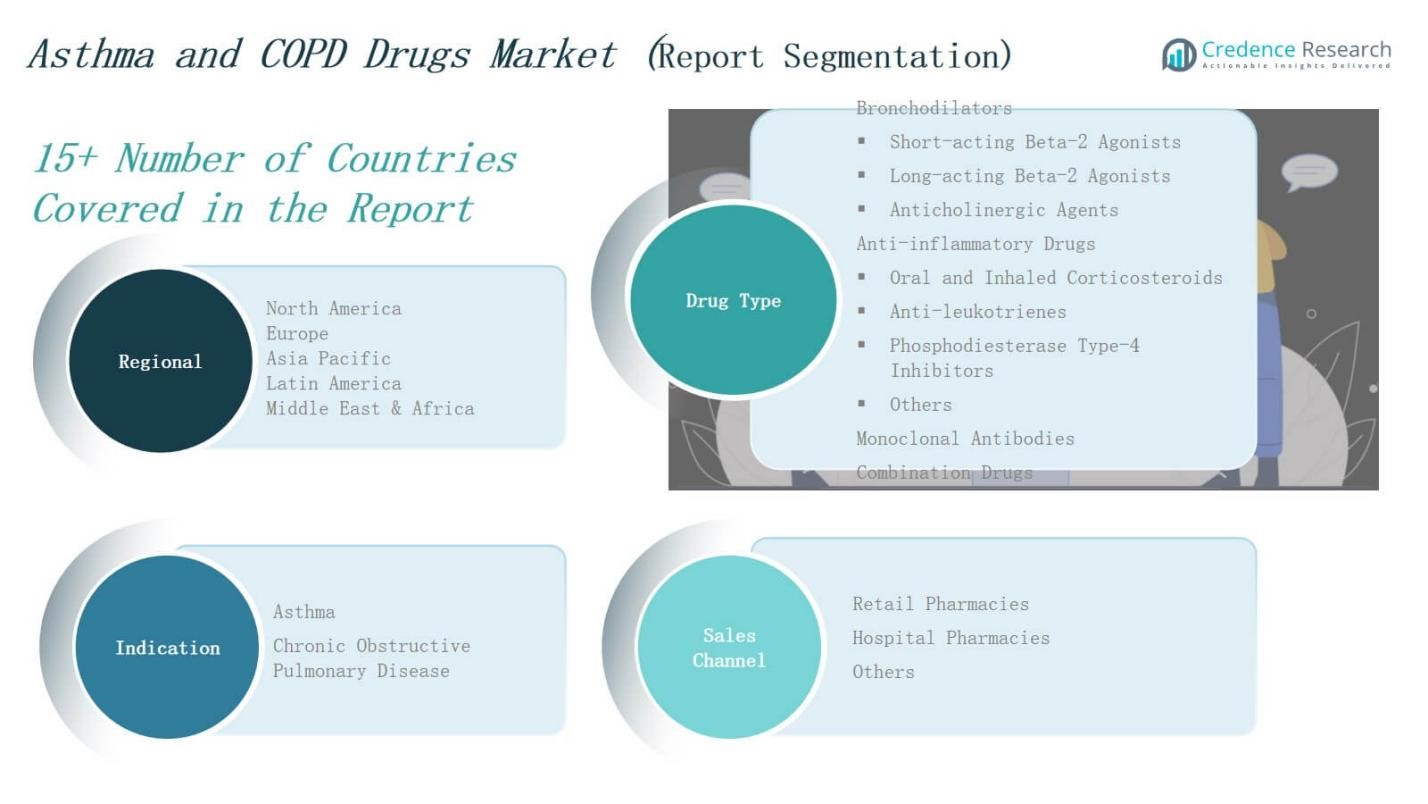
By Drug Type The Asthma and COPD Drugs Market is segmented into bronchodilators, anti-inflammatory drugs, monoclonal antibodies, and combination drugs. Bronchodilators, including short-acting beta-2 agonists, long-acting beta-2 agonists, and anticholinergic agents, dominate due to their rapid symptom relief. Anti-inflammatory drugs, such as oral and inhaled corticosteroids, anti-leukotrienes, and phosphodiesterase type-4 inhibitors, are critical for long-term disease control. Monoclonal antibodies are gaining traction for severe asthma cases. Combination drugs continue to expand their share due to convenience and clinical efficacy.- For instance, Glenmark Pharmaceuticals launched Indamet (Indacaterol plus Mometasone) in June 2022, a once-daily fixed-dose combination inhaler for asthma, available in three strengths to address varying patient needs.
- For instance, in March 2025, AstraZeneca announced a new phase 3 trial for its triple combination inhaled therapy, Breztri Aerosphere (budesonide/glycopyrrolate/formoterol fumarate), targeting COPD patients with elevated cardiopulmonary risk, demonstrating ongoing innovation in this therapeutic area.
Segments:
Based on Drug Type Bronchodilators- Short-acting Beta-2 Agonists
- Long-acting Beta-2 Agonists
- Anticholinergic Agents
- Oral and Inhaled Corticosteroids
- Anti-leukotrienes
- Phosphodiesterase Type-4 Inhibitors
- Others
- Asthma
- Chronic Obstructive Pulmonary Disease (COPD)
- Retail Pharmacies
- Hospital Pharmacies
- Others
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Regional Analysis
North America The North America Asthma and COPD Drugs Market size was valued at USD 5,150.88 million in 2018 to USD 6,569.18 million in 2024 and is anticipated to reach USD 8,783.17 million by 2032, at a CAGR of 3.7% during the forecast period. North America holds the largest share of the global Asthma and COPD Drugs Market, driven by high disease prevalence, advanced healthcare infrastructure, and widespread access to prescription medications. It benefits from strong regulatory frameworks and continuous R&D investment by leading pharmaceutical companies. The U.S. contributes significantly through the adoption of biologics and smart inhalers. Favorable reimbursement policies and high awareness levels support patient adherence. The region continues to lead in innovation and early adoption of advanced respiratory therapies. Europe The Europe Asthma and COPD Drugs Market size was valued at USD 4,347.92 million in 2018 to USD 5,598.99 million in 2024 and is anticipated to reach USD 7,587.53 million by 2032, at a CAGR of 3.9% during the forecast period. Europe ranks second in market share and shows consistent demand across major countries such as Germany, the UK, and France. It benefits from strong public health policies and emphasis on reducing air pollution. Government initiatives promote early diagnosis and subsidize essential respiratory drugs. Aging demographics and increasing smoking-related illnesses continue to drive COPD drug consumption. Companies are focusing on expanding access to combination therapies and biosimilars. Asia Pacific The Asia Pacific Asthma and COPD Drugs Market size was valued at USD 3,428.68 million in 2018 to USD 4,668.66 million in 2024 and is anticipated to reach USD 6,799.88 million by 2032, at a CAGR of 4.8% during the forecast period. Asia Pacific is the fastest-growing regional segment, supported by rising air pollution, rapid urbanization, and a growing middle-class population. Countries such as China, India, and Japan are investing in expanding healthcare access and modernizing hospital infrastructure. It witnesses increasing adoption of both branded and generic respiratory drugs. Awareness campaigns and mobile health platforms are improving patient education and adherence. Local manufacturers are gaining ground with cost-effective inhalers and oral medications. Latin America The Latin America Asthma and COPD Drugs Market size was valued at USD 1,676.63 million in 2018 to USD 2,257.83 million in 2024 and is anticipated to reach USD 3,244.11 million by 2032, at a CAGR of 4.6% during the forecast period. Latin America shows stable growth driven by an increasing burden of respiratory diseases, especially in urban and industrial regions. Brazil and Mexico dominate the market through public health initiatives and improved pharmaceutical supply chains. It faces challenges in affordability and uneven access, but ongoing reforms are expanding healthcare coverage. Global and regional firms are introducing generic versions to meet rising demand. Investment in community clinics and patient outreach programs supports market expansion. Middle East The Middle East Asthma and COPD Drugs Market size was valued at USD 645.82 million in 2018 to USD 833.60 million in 2024 and is anticipated to reach USD 1,133.31 million by 2032, at a CAGR of 3.9% during the forecast period. The Middle East market is driven by rising rates of asthma linked to sandstorms, allergens, and industrial emissions. Countries like Saudi Arabia and the UAE are enhancing respiratory care services through digital health systems and specialized centers. It benefits from government-funded healthcare and high pharmaceutical import rates. Multinational companies are forming partnerships to distribute advanced therapies. Public awareness campaigns and school-based asthma screening are increasing diagnosis rates across the region. Africa The Africa Asthma and COPD Drugs Market size was valued at USD 463.55 million in 2018 to USD 589.44 million in 2024 and is anticipated to reach USD 784.82 million by 2032, at a CAGR of 3.6% during the forecast period. Africa holds the smallest market share but presents long-term growth opportunities due to rising population and increasing urban pollution. Many regions face underdiagnosis and limited access to consistent treatment. It is slowly adopting affordable generics through support from NGOs and international health agencies. South Africa leads the market through better healthcare infrastructure. Investment in public health education and mobile clinics is expected to drive gradual improvement in asthma and COPD management.Key Player Analysis
- Grifols SA
- AstraZeneca PLC
- Sanofi SA
- Sun Pharmaceutical Industries Ltd
- Pfizer Inc.
- Boehringer Ingelheim GmbH
- Novartis AG
- Merck & Co., Inc.
- Sumitomo Dainippon Pharma Co., Ltd.
- GlaxoSmithKline PLC
- Hoffmann-La Roche Ltd
Competitive Analysis
The Asthma and COPD Drugs Market features a competitive landscape dominated by global pharmaceutical companies focused on respiratory care innovation. Key players include AstraZeneca PLC, GlaxoSmithKline PLC, Boehringer Ingelheim GmbH, Novartis AG, and Pfizer Inc., each maintaining extensive portfolios across bronchodilators, anti-inflammatory drugs, and biologics. It reflects strong investment in R&D, pipeline expansion, and regulatory approvals for targeted therapies. Companies are leveraging strategic collaborations, regional expansions, and lifecycle management to retain market share. Biologics and combination therapies are central to competition, supported by rising demand for personalized treatments. Generic drug manufacturers and regional firms are intensifying price competition, especially in emerging markets. Technological integration into inhaler devices and real-world evidence generation are differentiating factors in market positioning. The Asthma and COPD Drugs Market continues to evolve as firms prioritize advanced drug delivery systems, biosimilars, and sustainable pricing strategies to strengthen their presence across both developed and developing regions.Recent Developments
- In July 2025, Merck & Co. acquired Verona Pharma for $10 billion to expand its respiratory portfolio, gaining rights to the FDA-approved COPD drug Ohtuvayre (ensifentrine).
- In May 2025, GSK received U.S. FDA approval for Nucala (mepolizumab) as an add-on maintenance treatment for adult patients with eosinophilic COPD.
- In March 2025, Sanofi secured regulatory approval in Japan for Dupixent to treat COPD, marking its sixth approved indication for chronic diseases.
- In May 2025, AstraZeneca gained UK approval for Trixeo Aerosphere, a triple-combination inhaler using a near-zero global warming potential propellant.
- In July 2025, Upstream Bio initiated a Phase 2 clinical trial for Verekitug, dosing the first patient for its investigational COPD treatment.
Market Concentration & Characteristics
The Asthma and COPD Drugs Market exhibits moderate to high market concentration, with a few global pharmaceutical giants accounting for a significant share of total revenue. It is characterized by strong brand loyalty, high regulatory compliance, and consistent innovation in both drug formulation and delivery technologies. Leading companies focus on biologics, fixed-dose combinations, and inhalation therapies to maintain competitive advantage. Entry barriers are substantial due to complex clinical trial requirements, patent protections, and high R&D costs. The market favors firms with global distribution networks, diverse respiratory portfolios, and the ability to secure regulatory approvals across multiple regions. It responds actively to shifting healthcare demands, including the growing need for personalized medicine and digital health integration. Generic drug manufacturers are expanding in emerging markets, intensifying price competition. The Asthma and COPD Drugs Market continues to evolve with advancements in patient-centric care models, increasing emphasis on treatment adherence, and the global burden of chronic respiratory diseases.Report Coverage
The research report offers an in-depth analysis based on Drug Type, Indication, Sales Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook
- Demand for biologics will continue to rise, especially for patients with severe asthma and steroid-resistant COPD.
- Smart inhalers and digital health tools will gain traction for improving adherence and tracking treatment outcomes.
- Pharmaceutical companies will focus on developing once-daily and long-acting formulations to enhance convenience.
- Personalized therapies based on genetic markers and inflammatory phenotypes will see increased adoption.
- Generic drug availability will expand in emerging markets, improving access and affordability.
- Collaborations between biotech firms and major pharmaceutical companies will drive innovation in drug delivery.
- Governments will introduce new guidelines and reimbursement policies to support chronic respiratory disease management.
- Environmental regulations aimed at air quality improvement may influence disease prevalence and treatment trends.
- Investments in pediatric asthma care will rise, supported by early diagnosis and targeted therapies.
- Companies will prioritize sustainability in manufacturing and packaging of respiratory drug products.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Chronic Respiratory Disorders
Increasing global incidence of asthma and COPD, driven by factors such as air pollution, tobacco use, and aging populations, is expanding the patient base and fueling demand for both maintenance and rescue medications.
Technological Advancements in Drug Delivery and Devices
Innovations like smart inhalers, digital dose counters, and user-friendly inhalation devices are improving patient adherence and treatment outcomes, making therapies more effective and accessible.
Expanding Geriatric Population and Lifestyle Changes
The growing elderly demographic, coupled with sedentary lifestyles and poor air quality, is increasing susceptibility to chronic respiratory diseases, thereby boosting the need for long-term therapeutic solutions.
Government Initiatives and Improved Healthcare Access
Supportive healthcare policies, reimbursement reforms, and public awareness campaigns are enhancing access to asthma and COPD treatments, especially in emerging markets, driving broader adoption of advanced therapies.
Shift Toward Biologics and Personalized Medicine
The development and adoption of biologics and targeted therapies for severe and treatment-resistant cases are addressing unmet clinical needs, reducing exacerbation rates, and supporting the trend toward precision medicine in respiratory care.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Asthma and COPD Drugs Market?
What are the key segments within the Asthma and COPD Drugs Market?
What are some challenges faced by the Asthma and COPD Drugs Market?
Who are the major players in the Asthma and COPD Drugs Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Type
- 1.2.1 Bronchodilators
- 1.2.2 Anti-inflammatory Drugs
- 1.2.3 Monoclonal Antibodies
- 1.2.4 Combination Drugs
- 1.3 By Indication
- 1.3.1 Asthma
- 1.3.2 Chronic Obstructive Pulmonary Disease (COPD)
- 1.4 By Sales Channel
- 1.4.1 Retail Pharmacies
- 1.4.2 Hospital Pharmacies
- 1.4.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 20,517.7 million → 2032: USD 28,332.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Asthma And COPD Drugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Asthma And COPD Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Asthma And COPD Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Asthma And COPD Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Asthma And COPD Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Asthma And COPD Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Asthma And COPD Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Asthma And COPD Drugs Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 20,517.7 million → 2032: USD 28,332.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Asthma And COPD Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Bronchodilators
- 12.3.7.2 Anti-inflammatory Drugs
- 12.3.7.3 Monoclonal Antibodies
- 12.3.7.4 Combination Drugs
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Indication - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Asthma
- 12.4.7.2 Chronic Obstructive Pulmonary Disease (COPD)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Retail Pharmacies
- 12.5.7.2 Hospital Pharmacies
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Asthma And COPD Drugs Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Asthma And COPD Drugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Asthma And COPD Drugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 AstraZeneca PLC
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 GlaxoSmithKline PLC
- 17.4 Boehringer Ingelheim GmbH
- 17.5 Novartis AG
- 17.6 Pfizer Inc.
- 17.7 Sanofi SA
- 17.8 F. Hoffmann-La Roche Ltd
- 17.9 Grifols SA
- 17.10 Sun Pharmaceutical Industries Ltd
- 17.11 Merck & Co., Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

