
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Asthma Spacers Market Size 2024 | USD 1,936.38 million |
| Asthma Spacers Market, CAGR | 4.36% |
| Asthma Spacers Market Size 2032 | USD 2,709.66 million |
Market Overview
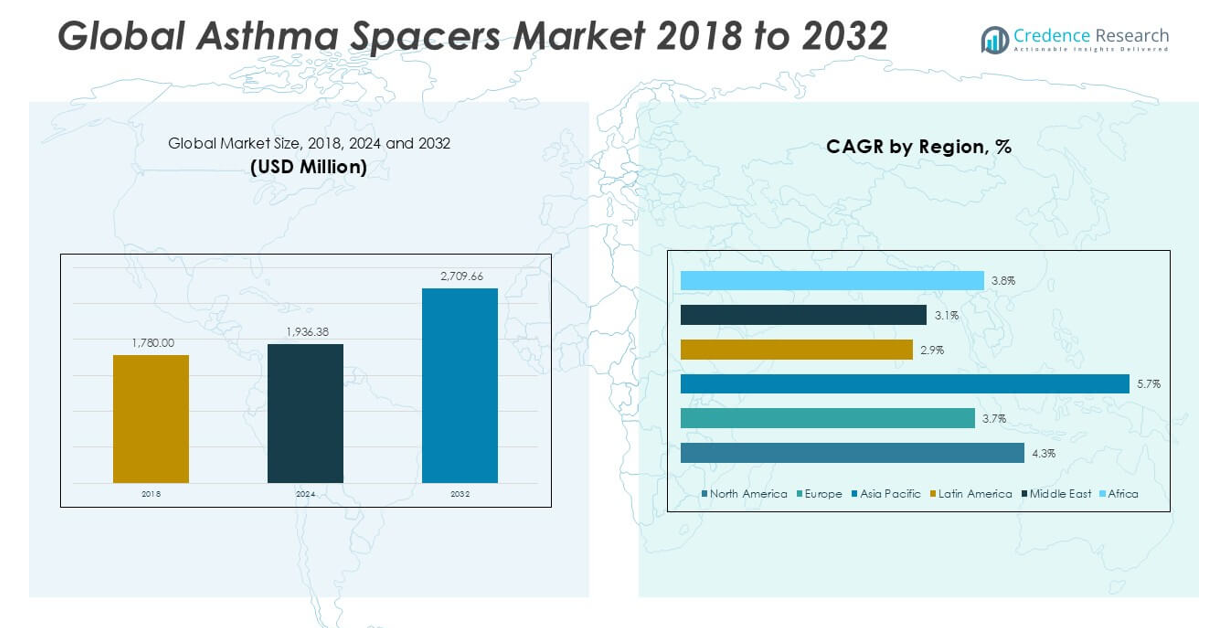
The Asthma Spacers market size was valued at USD 1,780.00 million in 2018, reached USD 1,936.38 million in 2024, and is anticipated to reach USD 2,709.66 million by 2032, at a CAGR of 4.36% during the forecast period.
The Asthma Spacers market is led by key players such as Trudell Medical International, PARI GmbH, Koninklijke Philips N.V., GlaxoSmithKline plc, Cipla Inc., HAAG-STREIT Group, Lupin Limited, Medical Developments International, Visiomed Group Ltd., Rossmax International Ltd., Teleflex Incorporated, Monaghan Medical Corporation, Asia Connection Co., Ltd., AstraZeneca plc, and Mediacare Equipments (India) Pvt. Ltd. These companies focus on product innovation, global expansion, and strategic partnerships to strengthen their market presence. North America dominates the Asthma Spacers market, holding a leading market share of 37.95% in 2024, supported by advanced healthcare infrastructure, high asthma prevalence, and strong patient awareness. Europe follows as a significant region, driven by increasing asthma diagnoses and supportive healthcare policies.
Market Insights
- The Asthma Spacers market was valued at USD 1,780.00 million in 2018, reached USD 1,936.38 million in 2024, and is expected to reach USD 2,709.66 million by 2032, growing at a CAGR of 4.36%.
- The market is driven by the increasing prevalence of asthma globally, rising pollution levels, and the growing adoption of inhalation therapies among pediatric and geriatric patients.
- Bronchodilators hold the largest share in the drug class segment, while Aero Chambers dominate the spacer type segment due to ease of use and better drug delivery efficiency.
- North America leads the market with a 37.95% share in 2024, followed by Europe at 28.48%, while Asia Pacific is expected to grow fastest with a 5.7% CAGR due to rising asthma cases and improving healthcare access.
- Low awareness in developing countries and cost sensitivity among patients remain key restraints, limiting wider adoption in price-sensitive regions.
Market Segmentation Analysis:
By Drug Class:
In the Asthma Spacers market, the Bronchodilators segment holds the largest market share within the drug class category. This dominance is driven by the widespread use of bronchodilators for rapid asthma symptom relief and their essential role in managing acute asthma attacks. Bronchodilators are frequently prescribed due to their effectiveness in relaxing airway muscles, improving airflow, and providing quick symptom control. Increasing asthma prevalence, coupled with the rising preference for immediate symptom management, continues to bolster the demand for bronchodilators, supporting their significant position in the global asthma spacers market.
- For instance, GlaxoSmithKline’s Ventolin (salbutamol) has been prescribed over 50 million times globally in a single year, highlighting the high demand and wide usage of bronchodilators compatible with spacers.
By Type
The Aero Chamber segment dominates the market, accounting for the largest share among spacer types. Aero chambers are widely adopted due to their compatibility with most metered-dose inhalers and their proven ability to enhance drug delivery efficiency. They minimize medication loss during inhalation and improve deposition in the lungs, particularly benefiting pediatric and geriatric patients. The segment's growth is fueled by increasing physician recommendations, patient preference for ease of use, and growing awareness regarding the effectiveness of aero chambers in managing asthma across diverse age groups.
- For instance, Trudell Medical International’s AeroChamber Plus Flow-Vu Spacer has over 500 clinical studies supporting its performance, with proven reduction in oropharyngeal deposition by up to 80%, significantly improving drug delivery efficiency.
By Product Type
Within the product type segmentation, Metered Dose Inhalers (MDIs) represent the largest market share. MDIs are widely preferred for their portability, ease of use, and precise medication delivery, which align with patient needs for on-the-go asthma management. The integration of spacers with MDIs enhances medication delivery and reduces oropharyngeal deposition, making them the preferred choice among healthcare providers. The Nebulizers segment also holds a significant position but trails behind MDIs in market share. Nebulizers are primarily used for severe asthma cases or in patients, such as young children and the elderly, who may have difficulty using handheld inhalers. The growing demand for home-based asthma management and the increasing availability of compact, portable nebulizers are key drivers for this segment.
Market Overview
Rising Prevalence of Asthma
The increasing global prevalence of asthma significantly drives the demand for asthma spacers. Rising pollution levels, sedentary lifestyles, and growing exposure to allergens have contributed to a higher incidence of asthma across all age groups. According to the World Health Organization, asthma affects millions worldwide, creating a sustained need for effective treatment options. Spacers enhance inhaler efficiency, making them a critical component in asthma management. This growing patient pool continuously fuels market expansion, as spacers are widely recommended for both pediatric and adult populations.
- For instance, Philips Respironics has distributed over 4 million OptiChamber Diamond spacers globally, directly supporting increasing asthma management needs and the growing patient base.
Growing Adoption Among Pediatric and Geriatric Populations
Asthma spacers are increasingly favored for pediatric and geriatric patients who often face challenges with direct inhaler usage. These devices simplify medication administration and improve drug deposition in the lungs, which is especially beneficial for individuals with poor inhalation coordination. The rising emphasis on patient-centric treatment and growing awareness among healthcare providers about the benefits of spacers for vulnerable age groups further accelerate market growth. Pediatricians and geriatric specialists frequently recommend spacers, strengthening their presence in asthma care protocols worldwide.
- For instance, Monaghan Medical Corporation’s AeroChamber Plus has been adopted in over 75% of U.S. pediatric clinics, reflecting strong clinical preference and widespread use in young patient populations.
Technological Advancements in Spacer Design
Ongoing technological advancements in spacer design contribute significantly to market growth. Manufacturers are focusing on developing user-friendly, portable, and cost-effective spacers with features like antistatic materials and feedback mechanisms to ensure optimal drug delivery. Innovations that enhance convenience and improve treatment adherence have increased the appeal of modern spacers among healthcare professionals and patients. These technological improvements not only improve clinical outcomes but also encourage wider adoption, positioning spacers as a preferred solution in comprehensive asthma management strategies.
Key Trends & Opportunities
Increasing Preference for Combination Therapies
The growing trend of combination therapies in asthma treatment presents a strong opportunity for spacer manufacturers. Combination therapies, which integrate bronchodilators and anti-inflammatory agents, are becoming the standard of care, particularly for moderate to severe asthma. Spacers improve the delivery of these combined medications, enhancing therapeutic efficiency and patient compliance. As physicians increasingly recommend combination treatments, the demand for spacers compatible with various inhalers is expected to rise, offering a valuable market expansion pathway for manufacturers focusing on integrated asthma solutions.
- For instance, Cipla’s Seroflo inhaler, a leading combination therapy product, reached over 10 million units sold globally, with most units prescribed alongside spacer devices to optimize medication delivery.
Expansion of Online and Home Healthcare Distribution Channels
The rapid growth of online pharmacies and home healthcare solutions offers notable opportunities in the asthma spacers market. Consumers are showing a strong preference for purchasing medical devices through online platforms due to convenience, wider product availability, and competitive pricing. Additionally, the increasing trend of home-based asthma management, driven by cost-efficiency and patient comfort, further supports this channel's growth. Companies that strengthen their e-commerce presence and develop spacer products optimized for home use stand to capture a significant portion of this emerging demand.
- For instance, Teleflex Incorporated reported over 300,000 asthma spacer units sold through online channels in a single year, underscoring the accelerating shift toward e-commerce and home-based respiratory care.
Key Challenges
Low Awareness in Developing Regions
A major challenge in the asthma spacers market is the low awareness regarding spacer benefits in developing countries. Many patients and healthcare providers in low- and middle-income regions remain unfamiliar with the proper use and advantages of spacers, leading to underutilization. Limited educational initiatives, coupled with weaker healthcare infrastructure, hinder the widespread adoption of these devices. Addressing this gap requires targeted awareness campaigns, healthcare training programs, and partnerships to improve patient outcomes and unlock growth potential in these underserved markets.
Cost Sensitivity and Limited Reimbursement
The cost of asthma spacers can pose a barrier, particularly in price-sensitive markets and among uninsured populations. Although spacers are essential for effective asthma management, limited reimbursement coverage in several healthcare systems reduces patient access. High out-of-pocket expenses may discourage regular use, especially when patients perceive spacers as optional rather than necessary. This challenge prompts manufacturers to explore cost-reduction strategies and advocate for broader insurance coverage to improve affordability and market penetration.
Device Misuse and Compliance Issues
Improper spacer usage and low patient compliance present persistent challenges in achieving optimal asthma control. Despite their clinical benefits, many patients, especially children and the elderly, may not use spacers correctly, leading to ineffective drug delivery. Additionally, the perception of spacers as cumbersome can reduce adherence over time. Addressing this issue requires continuous patient education, improvements in spacer design for ease of use, and the incorporation of feedback mechanisms to promote correct inhalation techniques and sustained compliance.
Regional Analysis
North America
North America held the largest share in the Asthma Spacers market in 2024, accounting for approximately 37.95% of the global market. The market in this region was valued at USD 683.52 million in 2018 and reached USD 735.04 million in 2024, with projections to grow to USD 1,025.31 million by 2032 at a CAGR of 4.3%. The growth is driven by high asthma prevalence, advanced healthcare infrastructure, and strong adoption of inhalation therapies. Increased awareness and supportive reimbursement policies further contribute to North America’s leading position in the global market.
Europe
Europe captured approximately 28.48% of the global Asthma Spacers market share in 2024. The market was valued at USD 525.10 million in 2018, increased to USD 551.43 million in 2024, and is expected to reach USD 733.65 million by 2032, expanding at a CAGR of 3.7%. Growth in this region is supported by rising asthma cases, especially in urban populations, along with established healthcare systems promoting effective inhalation therapies. Government initiatives to improve asthma management and growing patient preference for user-friendly spacer devices continue to support steady market growth across Europe.
Asia Pacific
Asia Pacific accounted for around 22.37% of the global Asthma Spacers market share in 2024 and is anticipated to exhibit the fastest growth with a CAGR of 5.7% during the forecast period. The market size increased from USD 379.14 million in 2018 to USD 433.45 million in 2024, and it is projected to reach USD 671.78 million by 2032. Rapid urbanization, increasing pollution, and a growing patient base drive demand in the region. Expanding healthcare access, rising asthma awareness, and improvements in diagnosis and treatment are contributing to the strong growth potential in Asia Pacific.
Latin America
Latin America held approximately 4.26% of the global Asthma Spacers market share in 2024. The market grew from USD 76.90 million in 2018 to USD 82.47 million in 2024 and is projected to reach USD 103.16 million by 2032, registering a CAGR of 2.9%. Growth in this region is supported by gradually improving healthcare infrastructure and increasing awareness of asthma management. However, the market faces challenges such as limited patient access to advanced devices and lower affordability compared to developed regions, which may moderate growth despite rising demand.
Middle East
The Middle East represented about 3.74% of the global Asthma Spacers market share in 2024. The market value progressed from USD 70.84 million in 2018 to USD 72.41 million in 2024, and it is forecast to reach USD 91.87 million by 2032, expanding at a CAGR of 3.1%. Market growth in the region is driven by increasing asthma prevalence and gradual improvements in healthcare delivery. However, the adoption rate of advanced spacer devices remains limited in some countries due to economic constraints. Efforts to improve patient education and access to affordable asthma management solutions are expected to support future growth.
Africa
Africa accounted for approximately 3.18% of the global Asthma Spacers market share in 2024. The market size rose from USD 44.50 million in 2018 to USD 61.58 million in 2024, and it is anticipated to reach USD 83.90 million by 2032, growing at a CAGR of 3.8%. Growth in Africa is primarily driven by increasing asthma awareness and the rising burden of respiratory diseases. However, limited healthcare access and low penetration of advanced inhalation devices continue to challenge market expansion. Ongoing public health initiatives and improved healthcare infrastructure are likely to foster moderate growth across the region.
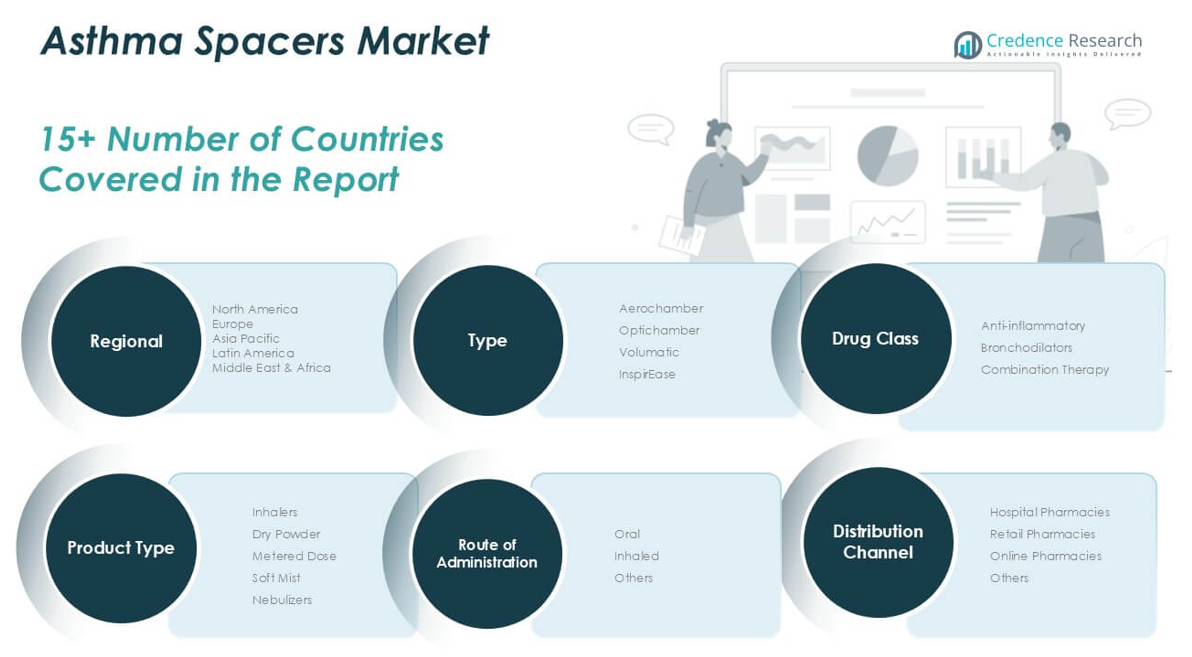
Market Segmentations:
By Drug Class
- Anti-inflammatory
- Bronchodilators
- Combination Therapy
By Type
- Aero Chamber
- Opti Chamber
- Volumatic
- InspirEase
By Product Type
- Inhalers
- Dry Powder
- Metered Dose
- Soft Mist
- Nebulizers
By Route of Administration
- Oral
- Inhaled
- Others
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Asthma Spacers market is moderately fragmented, with several global and regional players actively competing to strengthen their market positions. Key companies such as Trudell Medical International, PARI GmbH, Koninklijke Philips N.V., and Monaghan Medical Corporation lead the market with extensive product portfolios and strong distribution networks. These companies focus on continuous innovation, developing user-friendly and cost-effective spacer devices with advanced features like antistatic properties and visual feedback mechanisms to enhance patient compliance. Strategic collaborations, new product launches, and geographical expansions are common growth strategies among leading players. Additionally, pharmaceutical companies like GlaxoSmithKline plc, Cipla Inc., and AstraZeneca plc contribute to market growth by integrating spacer-compatible inhalers into their respiratory treatment solutions. Emerging players from Asia-Pacific and other developing regions are also gaining traction by offering affordable alternatives, intensifying competition. Overall, companies are prioritizing product differentiation, technological advancements, and patient-centric designs to capture a larger share of this growing market.
Key Player Analysis
- Trudell Medical International
- PARI GmbH
- Koninklijke Philips N.V.
- GlaxoSmithKline plc
- Cipla Inc.
- HAAG-STREIT Group
- Lupin Limited
- Medical Developments International
- Visiomed Group Ltd.
- Rossmax International Ltd.
- Teleflex Incorporated
- Monaghan Medical Corporation
- Asia Connection Co., Ltd.
- AstraZeneca plc
- Mediacare Equipments (India) Pvt. Ltd.
Recent Developments
- In February 2024, GlaxoSmithKline plc announced the completion of its acquisition of Aiolos Bio (Aiolos), a clinical-stage biopharmaceutical company dedicated to addressing the unmet treatment needs of patients with respiratory and inflammatory conditions. This acquisition provided GSK with access to Aiolos' innovative pipeline and expertise, strengthening its portfolio in respiratory and inflammatory diseases.
- In July 2023, Hormosan Pharma GmbH (Hormosan), a subsidiary wholly owned by Lupin in Germany, introduced Luforbec 100/6 (beclometasone 100µg / for moterol 6µg), a fixed combination available in a pressurized metered dose inhaler (pMDI) for managing adult asthma and chronic obstructive pulmonary disease (COPD) in Germany. This unveiling is intended to enhance the company's product range and solidify its competitive edge within the market.
- In November 2023, The Faculty of Medicine at the National University of Science and Technology (NUST) in Zimbabwe announced the development of an inexpensive spacer specifically for children. The spacers are to be sold all around Africa at an affordable cost saving thousands of lives.
- In January 2022, Monaghan Medical Corporation (MMC) received the 2021 Zenith Award from the American Association for Respiratory Care (AARC) for the seventh consecutive year. The award was given to the firm for the development of therapeutic devices for patients suffering from chronic respiratory conditions.
Market Concentration & Characteristics
The Asthma Spacers Market shows a moderately fragmented structure with the presence of several global and regional players competing across product types and distribution channels. It is characterized by a steady demand driven by the growing prevalence of asthma and the increasing need for improved drug delivery solutions. The market features a mix of well-established companies offering advanced, user-friendly spacers and emerging players focusing on cost-effective alternatives. Product innovation, affordability, and ease of use strongly influence competitive positioning. The market sees a significant concentration of activity in North America and Europe, where established healthcare systems and high awareness levels support strong adoption. Asia Pacific holds high growth potential with expanding healthcare access and a large patient base. Pricing pressure and limited awareness in developing regions challenge market penetration. Companies aim to differentiate through technological advancements, partnerships, and targeted regional strategies to expand their presence and address the unmet needs in under-served markets.
Report Coverage
The research report offers an in-depth analysis based on Drug Class, Type, Product Type, Route of Administration, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Asthma Spacers Market is expected to experience steady growth driven by the rising global asthma prevalence.
- Increasing adoption of spacers among pediatric and geriatric patients will continue to support market expansion.
- Technological advancements in spacer design will improve drug delivery efficiency and patient convenience.
- The demand for portable, user-friendly spacers will grow with the increasing preference for home-based asthma management.
- North America will likely maintain its market leadership due to established healthcare infrastructure and strong patient awareness.
- Asia Pacific is projected to witness the fastest growth supported by rising asthma cases and improving healthcare access.
- Companies will focus on cost-effective solutions to penetrate price-sensitive markets in developing regions.
- The integration of combination therapies with spacer-compatible inhalers will become more common in treatment protocols.
- Online pharmacies and home healthcare channels will play a growing role in spacer distribution.
- Continuous patient education and targeted awareness programs will remain essential to improve spacer adoption rates globally.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Asthma
The increasing global incidence of asthma, driven by factors such as pollution, urbanization, and changing lifestyles, is expanding the patient pool and fueling demand for effective management tools like spacers.
Growing Adoption Among Pediatric and Geriatric Populations
Spacers are particularly beneficial for children and elderly patients who struggle with proper inhaler technique, leading to increased recommendations by healthcare providers and higher adoption rates in these age groups.
Technological Advancements in Spacer Design
Innovations such as antistatic materials, visual feedback mechanisms, and user-friendly designs are improving drug delivery efficiency and patient compliance, making spacers more attractive to both clinicians and patients.
Expansion of Online and Home Healthcare Channels
The rise of online pharmacies and home-based asthma management is making spacers more accessible, supporting market growth by catering to consumer preferences for convenience and at-home care.
Increasing Preference for Combination Therapies
The trend toward combination therapies in asthma treatment, which require precise and efficient drug delivery, is boosting demand for spacers that can optimize the administration of multiple medications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Asthma Spacers Market?
What are the key segments within the Asthma Spacers Market?
What are some challenges faced by the Asthma Spacers Market?
Who are the major players in the Asthma Spacers Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Aero Chamber
- 1.2.2 Opti Chamber
- 1.2.3 Volumatic
- 1.2.4 InspirEase
- 1.3 By Drug Class
- 1.3.1 Anti-inflammatory
- 1.3.2 Bronchodilators
- 1.3.3 Combination Therapy
- 1.4 By Product Type
- 1.4.1 Inhalers - Dry Powder
- 1.4.2 Inhalers - Metered Dose
- 1.4.3 Inhalers - Soft Mist
- 1.4.4 Nebulizers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,936.38 million → 2032: USD 2,709.66 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Asthma Spacers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Asthma Spacers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Asthma Spacers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Asthma Spacers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Asthma Spacers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Asthma Spacers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Asthma Spacers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Asthma Spacers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,936.38 million → 2032: USD 2,709.66 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Asthma Spacers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Aero Chamber
- 12.3.7.2 Opti Chamber
- 12.3.7.3 Volumatic
- 12.3.7.4 InspirEase
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Drug Class - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Anti-inflammatory
- 12.4.7.2 Bronchodilators
- 12.4.7.3 Combination Therapy
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Inhalers - Dry Powder
- 12.5.7.2 Inhalers - Metered Dose
- 12.5.7.3 Inhalers - Soft Mist
- 12.5.7.4 Nebulizers
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Asthma Spacers Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Asthma Spacers Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Asthma Spacers Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Trudell Medical International
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 PARI GmbH
- 17.4 Koninklijke Philips N.V.
- 17.5 GlaxoSmithKline plc
- 17.6 Cipla Inc.
- 17.7 Monaghan Medical Corporation
- 17.8 AstraZeneca plc
- 17.9 Teleflex Incorporated
- 17.10 Lupin Limited
- 17.11 Medical Developments International
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

