
Airway Stent/Lung Stent Market Overview:
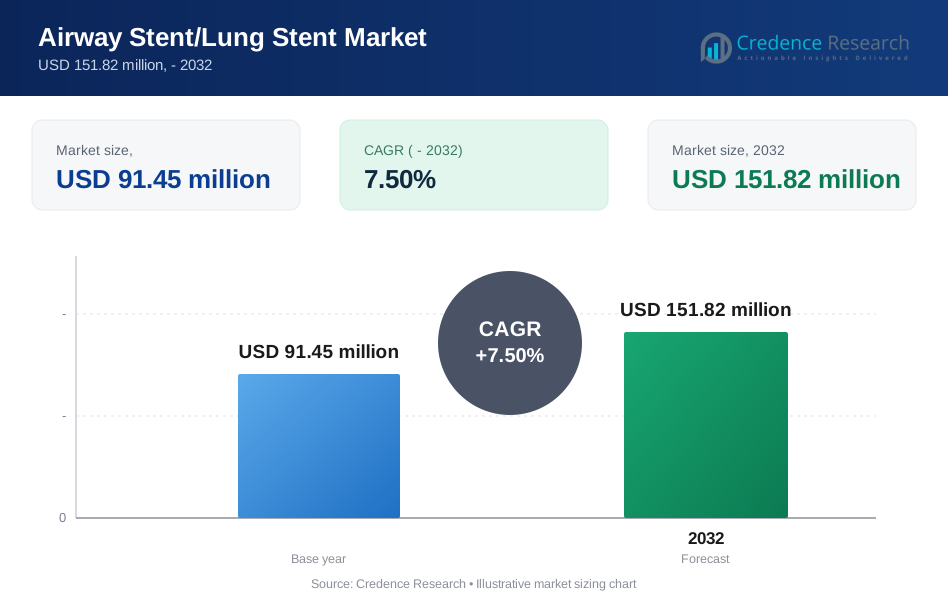
The Airway Stent / Lung Stent Market is projected to grow from USD 91.45 million in 2025 to an estimated USD 151.82 million by 2032, with a compound annual growth rate (CAGR) of 7.5% from 2025 to 2032.
| EPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Airway Stent/Lung Stent Market Size 2025 | USD 91.45 million |
| Airway Stent/Lung Stent Market, CAGR | 7.5% |
| Airway Stent/Lung Stent Market Size 2032 | USD 151.82 million |
Strong market drivers include rising incidence of airway obstruction disorders and increased use of interventional pulmonology techniques for both malignant and benign conditions. Clinicians prefer minimally invasive approaches that reduce recovery time and support rapid airflow restoration. Manufacturers introduce hybrid materials, improved coatings, and device designs that lower migration risk and improve durability. Hospitals expand bronchoscopy units to handle complex cases, and growing clinical evidence strengthens physician confidence, encouraging wider adoption across global healthcare systems.
Regional growth patterns show North America leading due to advanced healthcare infrastructure, strong procedural expertise, and widespread access to modern airway stent technologies. Europe follows with steady adoption supported by improved pulmonology training and rising chronic respiratory disease cases. Asia Pacific emerges as the fastest-expanding region due to increasing investment in tertiary care hospitals and broader awareness of minimally invasive airway treatments. Other regions gain traction as healthcare modernization accelerates, expanding clinical access to structured airway management.

Airway Stent/Lung Stent Market Insights:
- The Airway Stent / Lung Stent Market is set to grow from USD 91.45 million in 2025 to USD 151.82 million by 2032, driven by a strong 7.5% CAGR supported by rising adoption of minimally invasive airway stabilization.
- Market drivers include higher incidence of malignant and benign obstructions, expanding bronchoscopy capabilities, and strong clinical preference for advanced stent materials that improve airway patency.
- Key restraints involve migration risks, regulatory complexity, limited standardization, and the need for skilled pulmonology teams to ensure accurate placement and long-term safety.
- North America leads due to superior infrastructure and high procedure volumes, while Europe maintains steady growth supported by structured respiratory care programs.
- Asia Pacific emerges as the fastest-growing region due to rising investment in tertiary hospitals, improved pulmonology access, and expanding awareness of minimally invasive airway interventions.
Airway Stent/Lung Stent Market Drivers
Rising Prevalence of Airway Obstruction Disorders and Higher Need for Interventional Pulmonology Procedures
A steady rise in chronic airway diseases increases demand for advanced stent solutions. Patients present with complex obstructions that require structured support to restore airflow. Clinics adopt minimally invasive procedures to reduce recovery time. Interventional pulmonology teams expand their use of silicone, metallic, and hybrid stents. New clinical guidelines encourage timely stent placement to stabilize compromised airways. Hospitals upgrade bronchoscopy units to handle diverse patient needs. The Airway Stent / Lung Stent Market gains traction through wider clinical acceptance. Growing awareness among patients encourages faster diagnosis and timely treatment decisions.
Growing Preference for Minimally Invasive Airway Stabilization and Reduced Surgical Burden
Healthcare providers prefer techniques that lower procedural risk and shorten hospital stays. Stent placement offers a direct method to reopen obstructed passages. Doctors rely on improved materials that support flexibility and strength. Patients benefit from less trauma and shorter recovery periods. It helps reduce repeat interventions in many high-risk cases. Pulmonologists report rising demand for bronchoscopy-based stenting in emergency care. The Airway Stent / Lung Stent Market secures growth with strong adoption in critical settings. Advancements in device design support higher use across varied disease profiles.
Technological Advancements in Stent Materials, Customization, and Bronchoscopic Delivery Systems
Device makers invest in stronger alloys, improved polymers, and tailored shapes. New delivery systems support precise placement under challenging conditions. It enhances operator confidence during complex airway reconstruction. Computer models help refine sizing for difficult anatomies. Custom solutions reduce migration risk and improve long-term outcomes. Hospitals adopt advanced imaging tools to support accurate deployment. The Airway Stent / Lung Stent Market strengthens through innovation that improves safety and reliability. Production teams also test coatings that reduce infection risk and enhance durability.
- For instance, Micro-Tech (Nanjing) Co., Ltd. manufactures globally distributed nitinol airway stents and holds multiple FDA 510(k) clearances across its minimally invasive product portfolio, demonstrating validated manufacturing quality and regulatory-compliant device development.
Expanding Applications in Malignant and Benign Airway Diseases with Broader Clinical Evidence
Oncologists rely on airway stents to manage tumor-related obstruction. Patients with benign strictures also require durable solutions for sustained relief. Clinical trials report improved breathing outcomes following structured stenting. It increases physician confidence and drives inclusion in treatment plans. Hospitals see higher referrals for airway reconstruction services. Multidisciplinary teams collaborate to optimize placement strategies. The Airway Stent / Lung Stent Market benefits from broader use across complex lung conditions. Growth stems from expanded clinical training and rising demand for standardized protocols.
- For instance, the FDA granted De Novo clearance in October 2024, for Peytant Solutions’ AMStent Tracheobronchial Covered Stent System, authorizing it specifically for the treatment of tracheobronchial strictures caused by malignant neoplasms in adult patients, and recognizing it as the first airway stent to use a decellularized human amniotic membrane (DCAM) covering.
Airway Stent/Lung Stent Market Trends
Increasing Use of 3D-Printed and Patient-Specific Stent Designs for Complex Anatomical Cases
Clinics now explore 3D-printed stents for rare airway deformities. Tailored geometry helps improve fit and stability in difficult cases. It strengthens outcomes by reducing pressure points and migration events. Engineers refine polymers that support long-term tolerance. Surgeons request custom models when conventional designs fail. Digital planning tools improve placement accuracy before procedures. The Airway Stent / Lung Stent Market evolves toward a personalized treatment approach. Hospitals invest in rapid-prototype workflows to shorten preparation time.
- For instance, VisionAir Solutions reported developing more than 600 patient-specific, AI-assisted 3D-printed airway stents, supported by its proprietary design platform and collaborations with major U.S. medical centers.
Growing Adoption of Bioabsorbable Stents that Support Temporary Airway Relief Without Removal Needs
Research teams progress toward dissolvable implants that reduce follow-up procedures. Bioabsorbable solutions support healing without permanent placement. It lowers complications linked to long-term device retention. Trials explore controlled-degradation materials for predictable performance. Doctors monitor patient outcomes to confirm safety in varied conditions. These devices appeal to cases requiring short-term airway support. The Airway Stent / Lung Stent Market shifts toward solutions that reduce patient burden. Manufacturers refine degradation rates for more precise therapeutic windows.
Integration of Advanced Imaging and Navigation Tools to Improve Placement Accuracy and Reduce Complications
Hospitals deploy navigation software for real-time airway mapping. Enhanced imaging reduces uncertainty during bronchoscopy. It supports smoother delivery of rigid or flexible stents. Doctors value guided pathways for complex tumors or strictures. Navigation helps reduce misplacement events and lowers post-procedure adjustments. Clinics expand training to handle these digital tools. The Airway Stent / Lung Stent Market grows through alignment with next-generation visualization systems. Providers prioritize platforms that improve safety and procedural speed.
Rising Focus on Hybrid Stents with Improved Flexibility, Anti-Migration Features, and Stronger Radial Force
Manufacturers test hybrid structures that combine silicone and metal performance. These designs help balance comfort with stronger support. It reduces risk of collapse in high-compression zones. Anti-migration patterns keep the stent stable under airflow pressure. Clinics require devices that resist mucus buildup and maintain patency longer. Engineers refine coatings for smoother inner surfaces. The Airway Stent / Lung Stent Market moves toward multifunction stents that support varied disease needs. Hospitals expand inventories to match complex treatment demands.
- For instance, Taewoong Medical’s Niti-S™ Conical Stent and other hybrid configurations are widely documented in pulmonary procedure registries and supported by CE-mark certifications across multiple international markets.
Airway Stent/Lung Stent Market Challenges Analysis
Regulatory Constraints, Limited Standardization, and Rising Concern Over Device-Related Complications
Regulators enforce strict review processes that extend approval timelines. Manufacturers face barriers when evidence varies across patient groups. It creates delays that impact product launches in major regions. Hospitals report concerns linked to migration, infection, or granulation tissue. Doctors require clearer guidelines to support consistent placement decisions. Variability across stent types complicates training and procurement efforts. The Airway Stent / Lung Stent Market must navigate safety expectations while expanding innovation. Companies invest in risk-reduction studies to strengthen clinical acceptance.
High Cost Burden, Limited Skilled Workforce, and Uneven Access to Advanced Pulmonology Infrastructure
Treatment expenses increase due to specialized equipment and procedural needs. Patients in low-resource regions struggle to secure advanced care. It restricts adoption where reimbursement remains weak. Hospitals need trained teams to perform challenging stent placements. A shortage of skilled pulmonologists reduces procedure volumes in many regions. Infrastructure gaps limit access to high-quality bronchoscopy systems. The Airway Stent / Lung Stent Market faces pressure to balance affordability with performance. Providers push for training programs to close capability gaps.
Airway Stent/Lung Stent Market Opportunities
Expansion of Customizable Stent Platforms, AI-Based Planning Tools, and Rapid Design Technologies
Custom platforms support better alignment with unique airway structures. Engineers partner with clinicians to refine patient-specific profiles. It encourages wider adoption of tailored treatment pathways. AI planning tools suggest precise stent sizes using imaging data. Hospitals value predictive insights that support smoother procedures. Manufacturers gain growth potential through modular design models. The Airway Stent / Lung Stent Market enters a phase that rewards customization and precision. Clinics upgrade workflows to integrate automated planning steps.
Growing Investment in Pulmonology Care, Emerging-Region Infrastructure, and Multidisciplinary Airway Centers Governments fund advanced respiratory care units across developing regions. New centers focus on minimally invasive lung procedures. It drives volume growth through improved access to stent services. Training partnerships strengthen clinical expertise in complex airway management. Hospitals adopt standardized pathways that reduce complication rates. Investors support networks that expand high-quality bronchoscopic care. The Airway Stent / Lung Stent Market benefits from strong demand in rapidly modernizing healthcare systems. Upgraded infrastructure supports wider adoption across diverse patient populations.
Airway Stent/Lung Stent Market Segmentation Analysis:
By Product Type
Tracheal, bronchial, laryngeal, and tracheobronchial stents hold distinct roles across routine and complex airway disorders. Tracheal stents support patients with central airway collapse and severe obstruction linked to trauma or tumors. Bronchial stents serve segmental pathways where targeted stabilization helps restore airflow. Laryngeal stents help surgeons manage post-operative swelling and structural deformities. Tracheobronchial stents help address extended disease spread across multiple airway zones. Doctors choose each type based on pathology, stability needs, and long-term tolerance. Strong demand for precision devices strengthens the Airway Stent / Lung Stent Market through expanded treatment planning. It creates opportunities for specialized shapes and designs that improve patient outcomes.
By Material
Metal, silicone, hybrid, and other materials influence durability, comfort, and performance across diverse airway conditions. Metal stents offer high radial strength for tight obstructions and complex malignant cases. Silicone stents help reduce tissue irritation and support easier removal during follow-up care. Hybrid stents balance flexibility with structural integrity to improve placement stability. Other emerging materials explore coatings that lower infection risk and mucus buildup. Doctors evaluate each option based on patient tolerance and disease severity. The Airway Stent / Lung Stent Market gains momentum through material advances that boost reliability. It supports broader clinical adoption across both short-term and long-term therapy needs.
- For instance, Novatech SA’s Dumon™ silicone stent has been commercially used for more than 30 years, with thousands of documented clinical implantations across international pulmonology centers.
By Device Type
Self-expandable and balloon-expandable stents address different procedural needs within interventional pulmonology. Self-expandable designs adjust to airway contours and help maintain continuous pressure on obstructed tissue. These devices support smoother placement in tight or irregular passages. Balloon-expandable options offer controlled expansion during deployment, which benefits anatomies requiring exact sizing. Doctors weigh ease of placement, reposition capability, and long-term patency before selecting a device. Product diversity strengthens the Airway Stent / Lung Stent Market by supporting case-specific decision pathways. It encourages device makers to refine expansion mechanisms that elevate procedural accuracy.
- For instance, Medtronic’s superDimension™ Navigation System, which supports accurate deployment of self-expandable devices, has been utilized in more than 300,000 electromagnetic navigation bronchoscopy procedures globally.
By End Use / Application
Hospitals and ambulatory surgery centers rely on structured airway interventions to manage critical obstruction cases. Hospitals handle complex emergencies, malignant obstructions, and high-risk patients who need advanced imaging and bronchoscopy support. These settings manage multidisciplinary workflows that require dedicated pulmonology teams. Ambulatory surgery centers focus on stable patients needing short-procedure interventions with fast discharge. Their efficiency strengthens access to minimally invasive care across urban regions. Decision makers assess throughput, equipment availability, and staff expertise when selecting stent platforms. The Airway Stent / Lung Stent Market expands through rising procedure volumes across both facility types. It enables broader adoption of standardized care models that enhance patient recovery.
Segmentation:
By Product Type
- Tracheal Stents
- Bronchial Stents
- Laryngeal Stents
- Tracheobronchial Stents
By Material
- Metal Stents (Nitinol, Stainless Steel)
- Silicone Stents
- Hybrid Stents
- Others
By Device Type
- Self-Expandable Stents
- Balloon-Expandable Stents
By End Use / Application
- Hospitals
- Ambulatory Surgery Centers
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America holds the leading share of the global landscape with roughly 38% of the market. Strong pulmonology infrastructure and high adoption of minimally invasive procedures support this position. Hospitals invest in advanced bronchoscopy suites and structured airway programs. It drives higher use of tracheal and bronchial stents in both malignant and benign conditions. Clinical guidelines reinforce early intervention for complex airway diseases. The Airway Stent / Lung Stent Market gains steady momentum from strong reimbursement pathways and robust product availability.
Europe accounts for close to 30% of the global share, supported by rising adoption of hybrid stents and expanded use of navigation-assisted bronchoscopy. Leading countries introduce enhanced respiratory care protocols that encourage structured airway stabilization. Healthcare systems focus on precision-based treatment and improved training for interventional pulmonology teams. It raises demand for self-expandable and silicone stents across major clinics. Hospitals align procurement with quality standards that support long-term airway management. The region strengthens the Airway Stent / Lung Stent Market through rising chronic disease incidence and aging populations.
Asia Pacific holds nearly 22% of the market and records the fastest expansion due to large patient populations with obstructive airway disorders. Investments in tertiary care hospitals and cancer centers improve access to advanced procedures. Regional demand increases with rising awareness of minimally invasive therapy. It encourages health systems to introduce new pulmonology units and adopt updated bronchoscopy platforms. Training programs expand as clinicians integrate modern stent technologies into routine practice. The Airway Stent / Lung Stent Market gains traction through rapid healthcare modernization across major economies.
Key Player Analysis:
- Boston Scientific Corporation
- Taewoong Medical Co., Ltd.
- Cook Group / Cook Medical
- Micro-Tech (Nanjing) Co., Ltd.
- Merit Medical Systems, Inc.
- Novatech SA
- Endo-Flex GmbH
Competitive Analysis:
The competitive landscape includes global device companies, specialized stent manufacturers, and regional firms focused on airway reconstruction products. Leaders compete through design precision, material innovation, and strong clinical support programs. It raises expectations for durability, flexibility, and safe deployment across varied airway anatomies. Companies expand portfolios with hybrid stents and enhanced anti-migration features to improve long-term outcomes. Mid-sized manufacturers grow by offering cost-effective systems for hospitals in emerging regions. The Airway Stent / Lung Stent Market remains dynamic due to continuous design upgrades, strategic distribution partnerships, and increased focus on personalized airway solutions. Firms strengthen their position through regulatory compliance, clinician training, and broader geographic reach.
Recent Developments:
- In February 2025, Micro-Tech (Nanjing) Co., Ltd. completed the strategic acquisition of a 51% stake in Creo Medical S.L.U. (CME), enhancing its global expansion in minimally invasive medical technologies including pulmonology products like airway stents.
- In October 2024, Peytant Solutions received FDA de novo clearance for its AMStent system, a novel airway stent featuring a metal frame covered with human amnion tissue to manage tracheobronchial obstructions from malignant tumors marking a significant advancement in minimally invasive palliative care for respiratory patients.
- In July 2024, VisionAir Solutions announced a strategic partnership with Lazzaro Medical to expand its patient-specific 3D-printed airway stents, building on over 600 custom stents developed using AI software. supports upcoming launches of off-the-shelf patient-matched stents expected late 2024 to early 2025.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Material, Device Type, End Use / Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing adoption of minimally invasive airway stabilization will strengthen clinical demand across high-volume centers.
- Rising cases of malignant obstruction will expand placement needs for advanced stent platforms.
- Hybrid stents with stronger flexibility and low migration risk will gain wider acceptance among pulmonologists.
- Broader integration of navigation tools and imaging support will improve deployment accuracy in complex pathways.
- Custom and 3D-printed designs will support tailored care for patients with unusual airway geometries.
- Hospitals will expand bronchoscopy units to meet increased patient load for airway reconstruction procedures.
- Emerging markets will record faster uptake as healthcare infrastructure improves across major regions.
- Material innovation will push manufacturers to create safer, more durable devices for varied disease severity.
- Training programs for interventional pulmonology will raise procedure accuracy and reduce complication rates.
- Strategic partnerships will help companies expand distribution and strengthen the Airway Stent / Lung Stent Market footprint globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Airway Stent / Lung Stent Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Airway Stent / Lung Stent Market projected to grow between 2025 and 2032?
Which Airway Stent / Lung Stent Market segment held the largest share in 2025?
What are the primary factors fueling the growth of the Airway Stent / Lung Stent Market?
Who are the leading companies in the Airway Stent / Lung Stent Market?
Which region commanded the largest share of the Airway Stent / Lung Stent Market in 2025?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Airway Stent/Lung Stent Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Airway Stent/Lung Stent Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 91.45 million → 2032: USD 151.82 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Airway Stent/Lung Stent Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Airway Stent/Lung Stent Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Airway Stent/Lung Stent Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Airway Stent/Lung Stent Market Drivers
- 3.3 Airway Stent/Lung Stent Market Restraints & Challenges
- 3.4 Airway Stent/Lung Stent Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Airway Stent/Lung Stent Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Airway Stent/Lung Stent Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Airway Stent/Lung Stent category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Airway Stent/Lung Stent Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Airway Stent/Lung Stent Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Airway Stent/Lung Stent market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Airway Stent/Lung Stent Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Airway Stent/Lung Stent Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Airway Stent/Lung Stent Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Airway Stent/Lung Stent (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Airway Stent/Lung Stent Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Airway Stent/Lung Stent Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Airway Stent/Lung Stent Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Airway Stent/Lung Stent Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Airway Stent/Lung Stent Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Airway Stent/Lung Stent Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Airway Stent/Lung Stent Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Airway Stent/Lung Stent Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Airway Stent/Lung Stent Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
