
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Blood Clot Retrieval Devices Market Size 2024 | USD 7725 Million |
| Blood Clot Retrieval Devices Market, CAGR | 6.9% |
| Blood Clot Retrieval Devices Market Size 2032 | USD 13174.07 Million |
Market Overview:
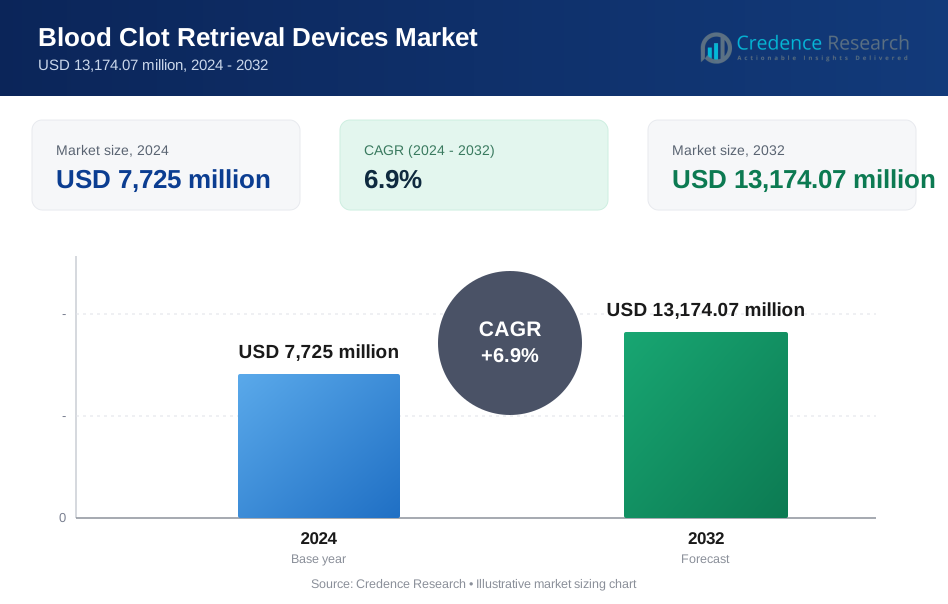
The Blood Clot Retrieval Devices Market is projected to grow from USD 7725 million in 2024 to an estimated USD 13174.07 million by 2032, with a compound annual growth rate (CAGR) of 6.9% from 2024 to 2032.
The market growth is primarily driven by several key factors, including the rising incidence of cardiovascular diseases, the growing awareness of stroke treatment options, and the technological advancements in blood clot retrieval devices. Innovations in device designs, such as the introduction of thrombectomy catheters, stent retrievers, and aspiration catheters, are significantly improving the success rates of clot retrieval procedures. Additionally, the increasing emphasis on stroke prevention and early intervention strategies is contributing to the market's positive trajectory. Favorable reimbursement policies and expanding healthcare infrastructure are also supporting the widespread use of blood clot retrieval devices.
Regionally, North America dominates the blood clot retrieval devices market, owing to the presence of advanced healthcare infrastructure, high adoption rates of innovative technologies, and a well-established healthcare system. The United States, in particular, is a major contributor due to its large patient pool and strong emphasis on stroke management. Europe holds a significant share, with increasing awareness about stroke treatment and improvements in healthcare access. The Asia Pacific region is expected to witness the fastest growth, driven by rising healthcare investments, a growing elderly population, and the expanding healthcare infrastructure in countries like China and India.
Market Drivers:
Rising Incidence of Cardiovascular Diseases:
The increasing prevalence of cardiovascular diseases, particularly ischemic stroke, is a major driver for the blood clot retrieval devices market. With cardiovascular conditions becoming more common due to factors such as an aging population, sedentary lifestyles, and unhealthy diets, the need for effective and advanced treatment options to manage blood clots is escalating. The rising number of patients requiring thrombectomy procedures significantly contributes to the demand for innovative clot retrieval devices that can provide rapid and efficient solutions. For instance, the Solitaire stent retriever and the Penumbra System are among the advanced devices used in thrombectomy procedures, offering rapid and effective clot removal.
Technological Advancements in Retrieval Devices:
Technological innovation is transforming the landscape of blood clot retrieval devices. Significant improvements in the design and functionality of thrombectomy catheters, stent retrievers, and aspiration catheters have enhanced the effectiveness of clot retrieval procedures. For instance, the Solitaire stent retriever device has shown to significantly improve outcomes for people with acute ischemic stroke compared to clot-busting drugs alone. These advancements have made procedures less invasive, reduced complications, and improved recovery times, which have contributed to better patient outcomes. The continuous development of next-generation devices with superior capabilities, such as enhanced clot penetration and retrieval efficiency, is driving market growth.
Increased Awareness and Early Diagnosis:
Growing awareness about stroke prevention and early diagnosis is playing a pivotal role in the adoption of blood clot retrieval devices. Public education campaigns, along with enhanced training for healthcare professionals, have increased the recognition of stroke symptoms and the importance of early intervention. The prompt use of clot retrieval devices following a stroke has shown to improve survival rates and reduce disabilities, thereby boosting their adoption and utilization across healthcare systems. For example, the Indian Stroke Association's Mission Brain Attack initiative focuses on spreading critical awareness about the urgency of stroke treatment and the devastating impact delays can have on recovery.
Improved Healthcare Infrastructure and Reimbursement Policies:
Improved healthcare infrastructure, particularly in emerging markets, is supporting the growth of the blood clot retrieval devices market. Expanding access to medical care, along with favorable reimbursement policies in developed regions, is enhancing the accessibility and affordability of these devices. This has made advanced clot retrieval treatments more widely available, encouraging their use in clinical settings and leading to a broader market adoption. For instance, the World Stroke Campaign aims to improve public awareness and understanding of stroke, highlighting the importance of stroke prevention and early treatment.
Market Trends:
Minimally Invasive Procedures:
One of the most prominent trends in the blood clot retrieval devices market is the growing preference for minimally invasive procedures. Thrombectomy, a key treatment for ischemic stroke, has evolved into a highly effective procedure, reducing the need for traditional open surgeries. This trend is driven by patient demand for less traumatic, quicker recovery treatments, as well as advancements in device design that allow for more precise and efficient clot removal. For instance, the ClotTriever system by Inari Medical is a minimally invasive device FDA cleared for the treatment of deep vein thrombosis (DVT), allowing patients to achieve rapid relief from DVT symptoms by physically capturing and removing blood clots from the body. As minimally invasive procedures gain prominence, the market for blood clot retrieval devices continues to expand.
Advancements in Device Technology:
Another significant trend is the continuous technological advancements in blood clot retrieval devices. Manufacturers are focusing on improving device designs, materials, and functionality to enhance treatment outcomes. Innovations such as stent retrievers, aspiration catheters, and mechanical thrombectomy devices have increased the success rate of clot retrieval and reduced the time needed for intervention. For example, the Solitaire stent retriever has shown to significantly improve outcomes for people with acute ischemic stroke, with 60% of patients treated with the device being functionally independent and free from disability three months after having a stroke. Additionally, the development of devices with improved clot capture and extraction capabilities is leading to more effective and streamlined procedures, further boosting their adoption in clinical practice.
Rise of Thrombectomy Centers of Excellence:
The establishment of thrombectomy centers of excellence is another growing trend in the blood clot retrieval devices market. These specialized centers are dedicated to providing comprehensive stroke care, including advanced clot retrieval interventions. As healthcare providers increasingly focus on improving stroke care outcomes, these centers are becoming essential in ensuring optimal patient treatment. For instance, Apollo Hospitals in India offers comprehensive stroke treatment, including mechanical thrombectomy, which can help patients up to 12 hours from the onset of stroke. The consolidation of resources and expertise within these centers allows for the application of cutting-edge clot retrieval devices, contributing to better clinical results and faster recovery times.
Regulatory Approvals and Clinical Evidence:
The increasing number of regulatory approvals for new blood clot retrieval devices is helping drive market growth. As clinical evidence supporting the efficacy of these devices continues to emerge, regulatory agencies such as the FDA are approving advanced devices for clinical use. For example, the Trevo clot retrieval device was cleared by the FDA for use up to 24 hours after stroke symptom onset, significantly expanding its indication. This trend is fostering greater trust among healthcare providers, thereby accelerating the adoption of these technologies in hospitals and medical centers worldwide. Enhanced clinical outcomes, supported by robust data, are fueling broader acceptance of these devices.
Market Challenges Analysis:
High Cost of Devices:
One of the major challenges facing the blood clot retrieval devices market is the high cost associated with these advanced medical technologies. Devices such as thrombectomy catheters, stent retrievers, and aspiration catheters are expensive due to their sophisticated design and cutting-edge technology. This high cost can create barriers to adoption, particularly in low- and middle-income countries with limited healthcare budgets. Hospitals and healthcare providers in these regions may struggle to justify the expense, limiting the widespread use of these devices.
Limited Access in Emerging Markets:
Access to blood clot retrieval devices remains limited in many emerging markets due to factors such as insufficient healthcare infrastructure, a lack of trained medical professionals, and inadequate reimbursement policies. Regions like Africa, parts of Asia, and Latin America face significant challenges in providing advanced stroke care, which results in slower adoption of these technologies. The disparity in access to high-quality stroke treatment between developed and developing regions further restricts the market potential in these areas.
Regulatory and Reimbursement Issues:
The regulatory approval process for blood clot retrieval devices is often lengthy and complex, which can delay the introduction of new products to the market. Additionally, inconsistent reimbursement policies across regions can create uncertainty for healthcare providers. In some regions, lack of reimbursement or insufficient coverage for thrombectomy procedures discourages hospitals from investing in these advanced devices, thereby hindering their adoption and use in clinical practice.
Risk of Complications and Procedural Challenges:
Despite their effectiveness, blood clot retrieval procedures carry inherent risks, such as vessel injury, hemorrhage, or incomplete clot retrieval. These procedures require a high level of skill and expertise, and in less specialized medical settings, the potential for complications increases. The need for highly trained professionals limits the adoption of these devices, particularly in hospitals with fewer resources or less experience in performing these complex procedures.
Market Segmentation Analysis:
By Stroke
The blood clot retrieval devices market is primarily segmented by stroke type, including ischemic stroke and hemorrhagic stroke. Ischemic stroke, which occurs due to a blockage in blood vessels, accounts for the largest share of the market, as clot retrieval devices are primarily used in these cases. With the growing incidence of ischemic stroke, the demand for thrombectomy procedures is increasing, driving the adoption of blood clot retrieval devices. Hemorrhagic strokes, though less common, are also a consideration in the broader stroke care landscape, contributing to market growth through advancements in device designs to address various types of stroke-related clots.
By Device
The market is further segmented by device type, including thrombectomy catheters, stent retrievers, aspiration catheters, and other mechanical thrombectomy devices. Thrombectomy catheters and stent retrievers are the most widely used devices for clot retrieval, providing effective solutions for removing blood clots in ischemic stroke patients. Aspiration catheters are gaining traction due to their simplicity and efficiency, offering a non-invasive method for clot removal. Each device type has its unique advantages, and their adoption is influenced by clinical needs and advancements in technology.
By Application
The primary application of blood clot retrieval devices is in the treatment of ischemic stroke. However, these devices are also used in other applications such as acute myocardial infarction (heart attacks) and pulmonary embolism. The stroke application segment dominates the market, as the incidence of stroke continues to rise globally. However, the growing application of these devices in other cardiovascular conditions is expected to contribute to the overall market growth.
Segmentations:
By Stroke
- Ischemic Stroke
- Hemorrhagic Stroke
By Device
- Thrombectomy Catheters
- Stent Retrievers
- Aspiration Catheters
- Mechanical Thrombectomy Devices
By Application
- Ischemic Stroke
- Acute Myocardial Infarction
- Pulmonary Embolism
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share in the blood clot retrieval devices market, accounting for over 40% of the global share. This is largely due to the region's advanced healthcare infrastructure, high adoption of innovative technologies, and favorable reimbursement policies. The United States plays a significant role, with a large patient population and widespread access to advanced medical treatments. The increasing prevalence of cardiovascular diseases and stroke further drives demand for blood clot retrieval devices, supported by strong research and development initiatives in the region.
Europe
Europe holds the second-largest market share, contributing 30% to the global market. The region benefits from well-established healthcare systems, growing awareness about stroke prevention and treatment, and increasing clinical evidence supporting the effectiveness of thrombectomy procedures. Key markets such as Germany, the United Kingdom, and France are driving this growth, with a rising incidence of stroke and a strong need for effective clot retrieval solutions. Europe’s robust healthcare policies and infrastructure continue to support the adoption of blood clot retrieval devices.
Asia Pacific
Asia Pacific is the fastest-growing region in the blood clot retrieval devices market, with a share 20%. This growth is fueled by improving healthcare infrastructure, an aging population, and growing awareness of stroke and its treatments, particularly in countries like China and India. As healthcare systems in the region continue to evolve and access to advanced treatments improves, demand for blood clot retrieval devices is expected to increase. Rising disposable incomes and expanding medical technologies are anticipated to further boost market growth.
Latin America
Latin America accounts for a smaller market share, 5%, but continues to show steady growth. Factors contributing to this growth include the increasing prevalence of cardiovascular diseases, expanding healthcare access, and growing awareness of stroke treatment options. Brazil, Mexico, and Argentina are the key markets driving the adoption of blood clot retrieval devices. As healthcare infrastructure improves, demand for these devices is expected to rise in the region.
Middle East & Africa
The Middle East and Africa account for the smallest share of the market, estimated at 4%. Challenges such as limited healthcare resources and economic constraints impact the widespread adoption of blood clot retrieval devices. However, improvements in healthcare infrastructure, coupled with increasing awareness of stroke treatment, are expected to gradually drive market growth in the region. Key markets, such as Saudi Arabia and South Africa, are seeing growing access to advanced medical technologies, which will contribute to future market expansion.
Key Player Analysis:
- Abbott
- Medtronic
- Boston Scientific Corporation
- Penumbra
- Terumo Corporation
- NeuroVasc Technologies
- Stryker Corporation
- Johnson & Johnson
- Philips Healthcare
- Microvention, Inc.
Competitive Analysis:
The blood clot retrieval devices market is highly competitive, with several key players striving to innovate and capture market share. Leading companies such as Medtronic, Boston Scientific, and Stryker hold significant positions, driven by their strong product portfolios and continuous advancements in technology. For instance, Medtronic's Solitaire™ X Revascularization Device has demonstrated a first pass effect (FPE) rate of 40.5% and a modified FPE (mFPE) rate of 58.9% across patients treated with the device. These companies invest heavily in research and development to improve the efficacy, safety, and ease of use of their devices, which has resulted in the introduction of next-generation thrombectomy products. In addition to large corporations, smaller players like Penumbra and Terumo also play a crucial role, often focusing on niche innovations such as aspiration thrombectomy systems and catheter technologies. The market is also characterized by strategic partnerships, acquisitions, and collaborations to expand product offerings and enhance market presence. To remain competitive, companies must navigate regulatory hurdles, ensure consistent product performance, and respond to rising demand for minimally invasive stroke treatments while maintaining a focus on cost-effectiveness and patient outcomes.
Recent Developments:
- In September 2023, Boston Scientific received FDA approval for the latest-generation WATCHMAN FLX™ Pro Left Atrial Appendage Closure Device, which is designed to reduce stroke risk in patients with atrial fibrillation.
- In April 2024, Penumbra's Lightning Flash 2.0 system received FDA clearance. This advanced computer-assisted vacuum thrombectomy system is designed to improve clot removal procedures in the vascular system.
- In November 2024, Boston Scientific demonstrated superior bleeding risk reduction with its WATCHMAN FLX™ device compared to oral anticoagulation in patients undergoing cardiac ablation procedures.
Market Concentration & Characteristics:
The blood clot retrieval devices market is moderately concentrated, with a few key players dominating the landscape, including Medtronic, Boston Scientific, and Stryker. These leading companies hold substantial market shares due to their advanced product offerings, strong R&D capabilities, and extensive distribution networks. However, the market also features several smaller, innovative players like Penumbra and Terumo, which contribute to a dynamic competitive environment. The market is characterized by continuous technological advancements, with companies focusing on improving device efficacy, safety, and ease of use. The growing demand for minimally invasive stroke treatments drives innovation, while regulatory and reimbursement challenges remain prominent factors shaping market dynamics. Strategic partnerships, mergers, and acquisitions are common as companies seek to expand their product portfolios and market reach. This competitive landscape emphasizes both technological innovation and market expansion as key elements for success.
Report Coverage:
The research report offers an in-depth analysis based on strock, device, application, region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Continued advancements in thrombectomy technology will drive the development of more efficient and effective blood clot retrieval devices.
- Increasing awareness and education about stroke prevention and treatment will lead to higher demand for blood clot retrieval devices.
- The adoption of minimally invasive procedures will continue to grow as patients and healthcare providers seek less traumatic treatment options.
- Emerging markets, particularly in Asia Pacific and Latin America, will experience accelerated growth due to improved healthcare infrastructure and rising patient populations.
- The aging global population will contribute to the increasing incidence of ischemic stroke, thereby expanding the market for clot retrieval devices.
- Ongoing research and clinical trials will lead to the introduction of next-generation devices, offering improved clot retrieval capabilities and reduced complication rates.
- Regulatory bodies will play a significant role in ensuring the safety and efficacy of new blood clot retrieval technologies, shaping the market's growth trajectory.
- Increased healthcare investments and government initiatives will improve access to advanced medical treatments, driving market expansion in developing regions.
- The trend of specialized stroke centers and thrombectomy units will continue to grow, enhancing the adoption of blood clot retrieval devices.
- Collaboration between key players, startups, and research institutions will foster innovation and the development of cutting-edge solutions in the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the blood clot retrieval devices market?
What factors are driving the growth of the blood clot retrieval devices market?
What types of devices are improving clot retrieval procedures?
Which region holds the largest share in the blood clot retrieval devices market?
Which region is expected to experience the fastest market growth?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Blood Clot Retrieval Devices Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Blood Clot Retrieval Devices Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 7,725 million → 2032: USD 13,174.07 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Blood Clot Retrieval Devices Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Blood Clot Retrieval Devices Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Blood Clot Retrieval Devices Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Blood Clot Retrieval Devices Market Drivers
- 3.3 Blood Clot Retrieval Devices Market Restraints & Challenges
- 3.4 Blood Clot Retrieval Devices Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Blood Clot Retrieval Devices Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Blood Clot Retrieval Devices Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Blood Clot Retrieval Devices category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Blood Clot Retrieval Devices Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Blood Clot Retrieval Devices Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Blood Clot Retrieval Devices market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Blood Clot Retrieval Devices Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Blood Clot Retrieval Devices Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Blood Clot Retrieval Devices Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Blood Clot Retrieval Devices (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Blood Clot Retrieval Devices Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Blood Clot Retrieval Devices Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Blood Clot Retrieval Devices Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Blood Clot Retrieval Devices Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Blood Clot Retrieval Devices Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Blood Clot Retrieval Devices Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Blood Clot Retrieval Devices Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Blood Clot Retrieval Devices Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Blood Clot Retrieval Devices Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
