
Low-price chains are widening access beyond big cities
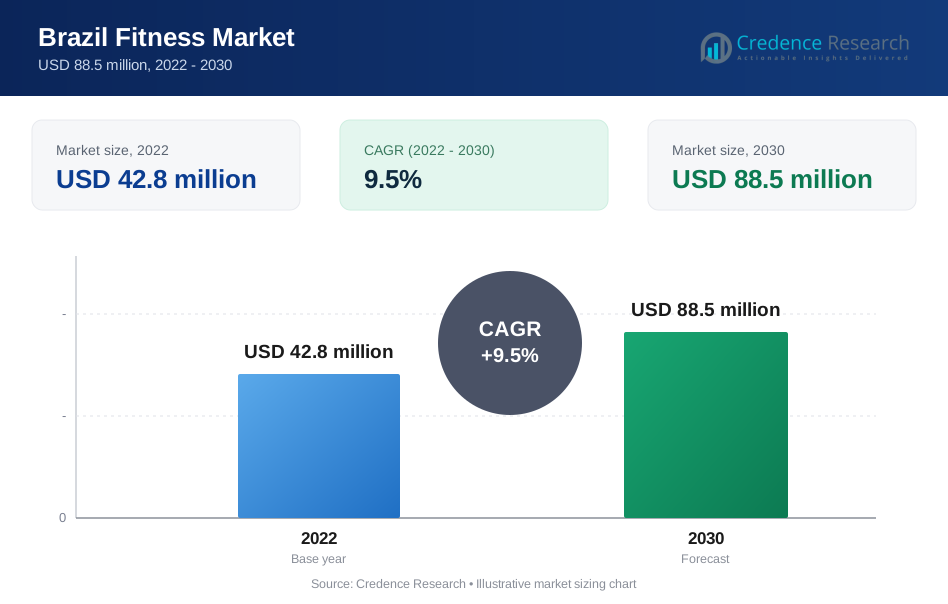
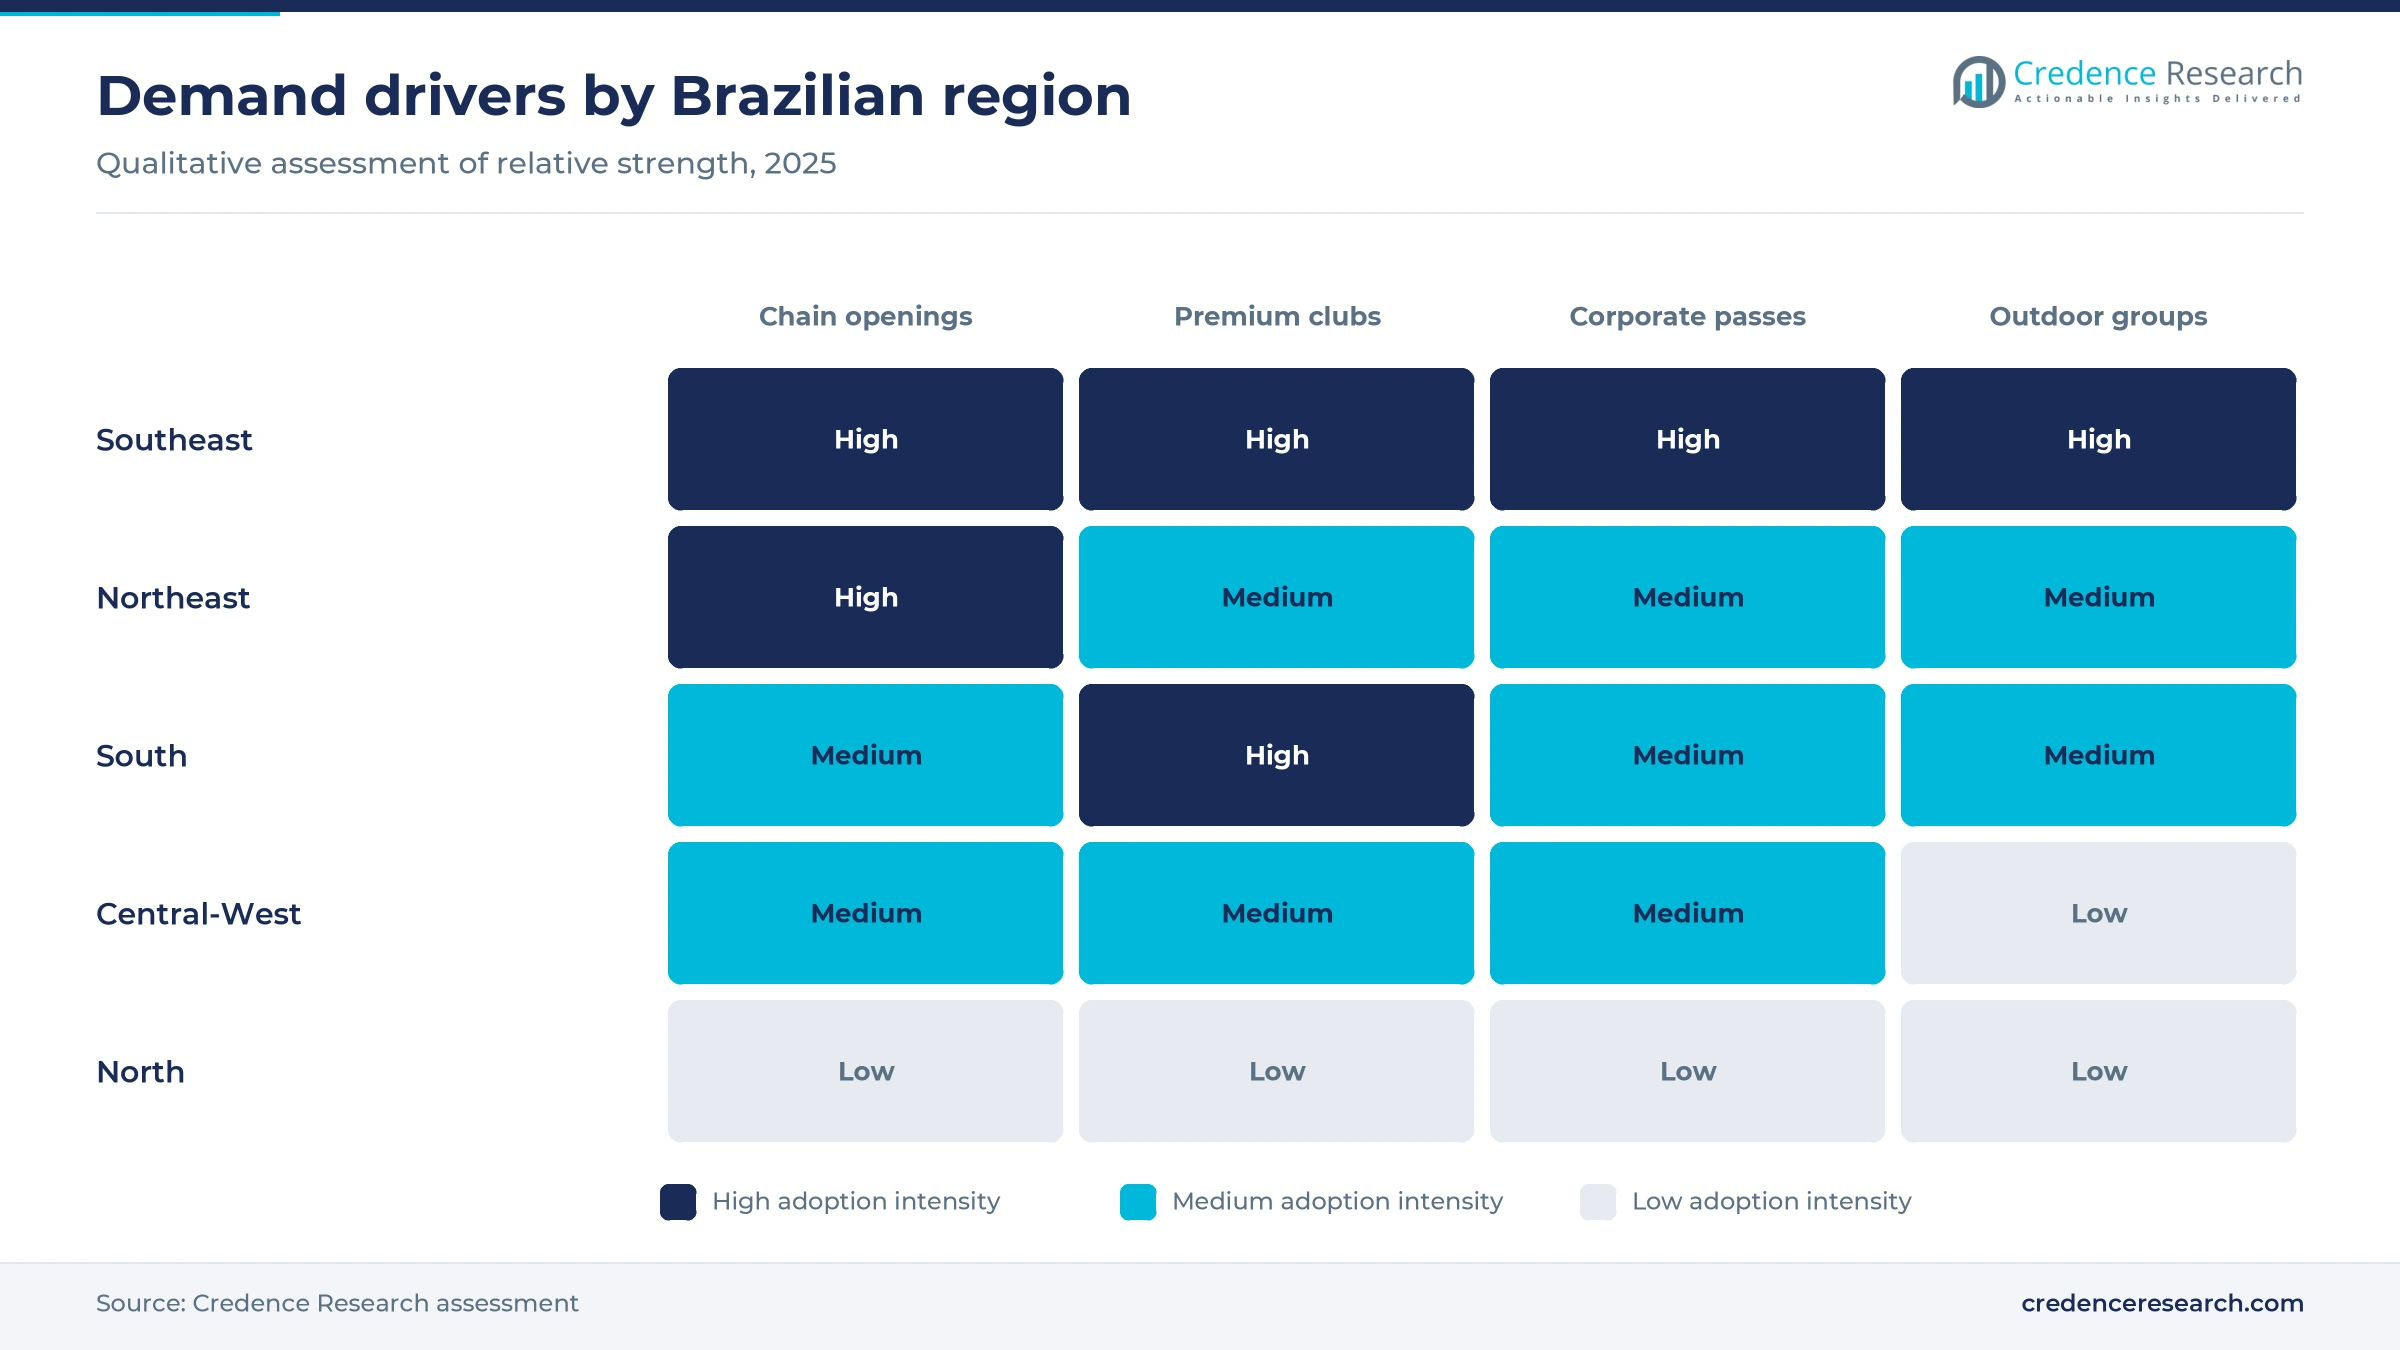
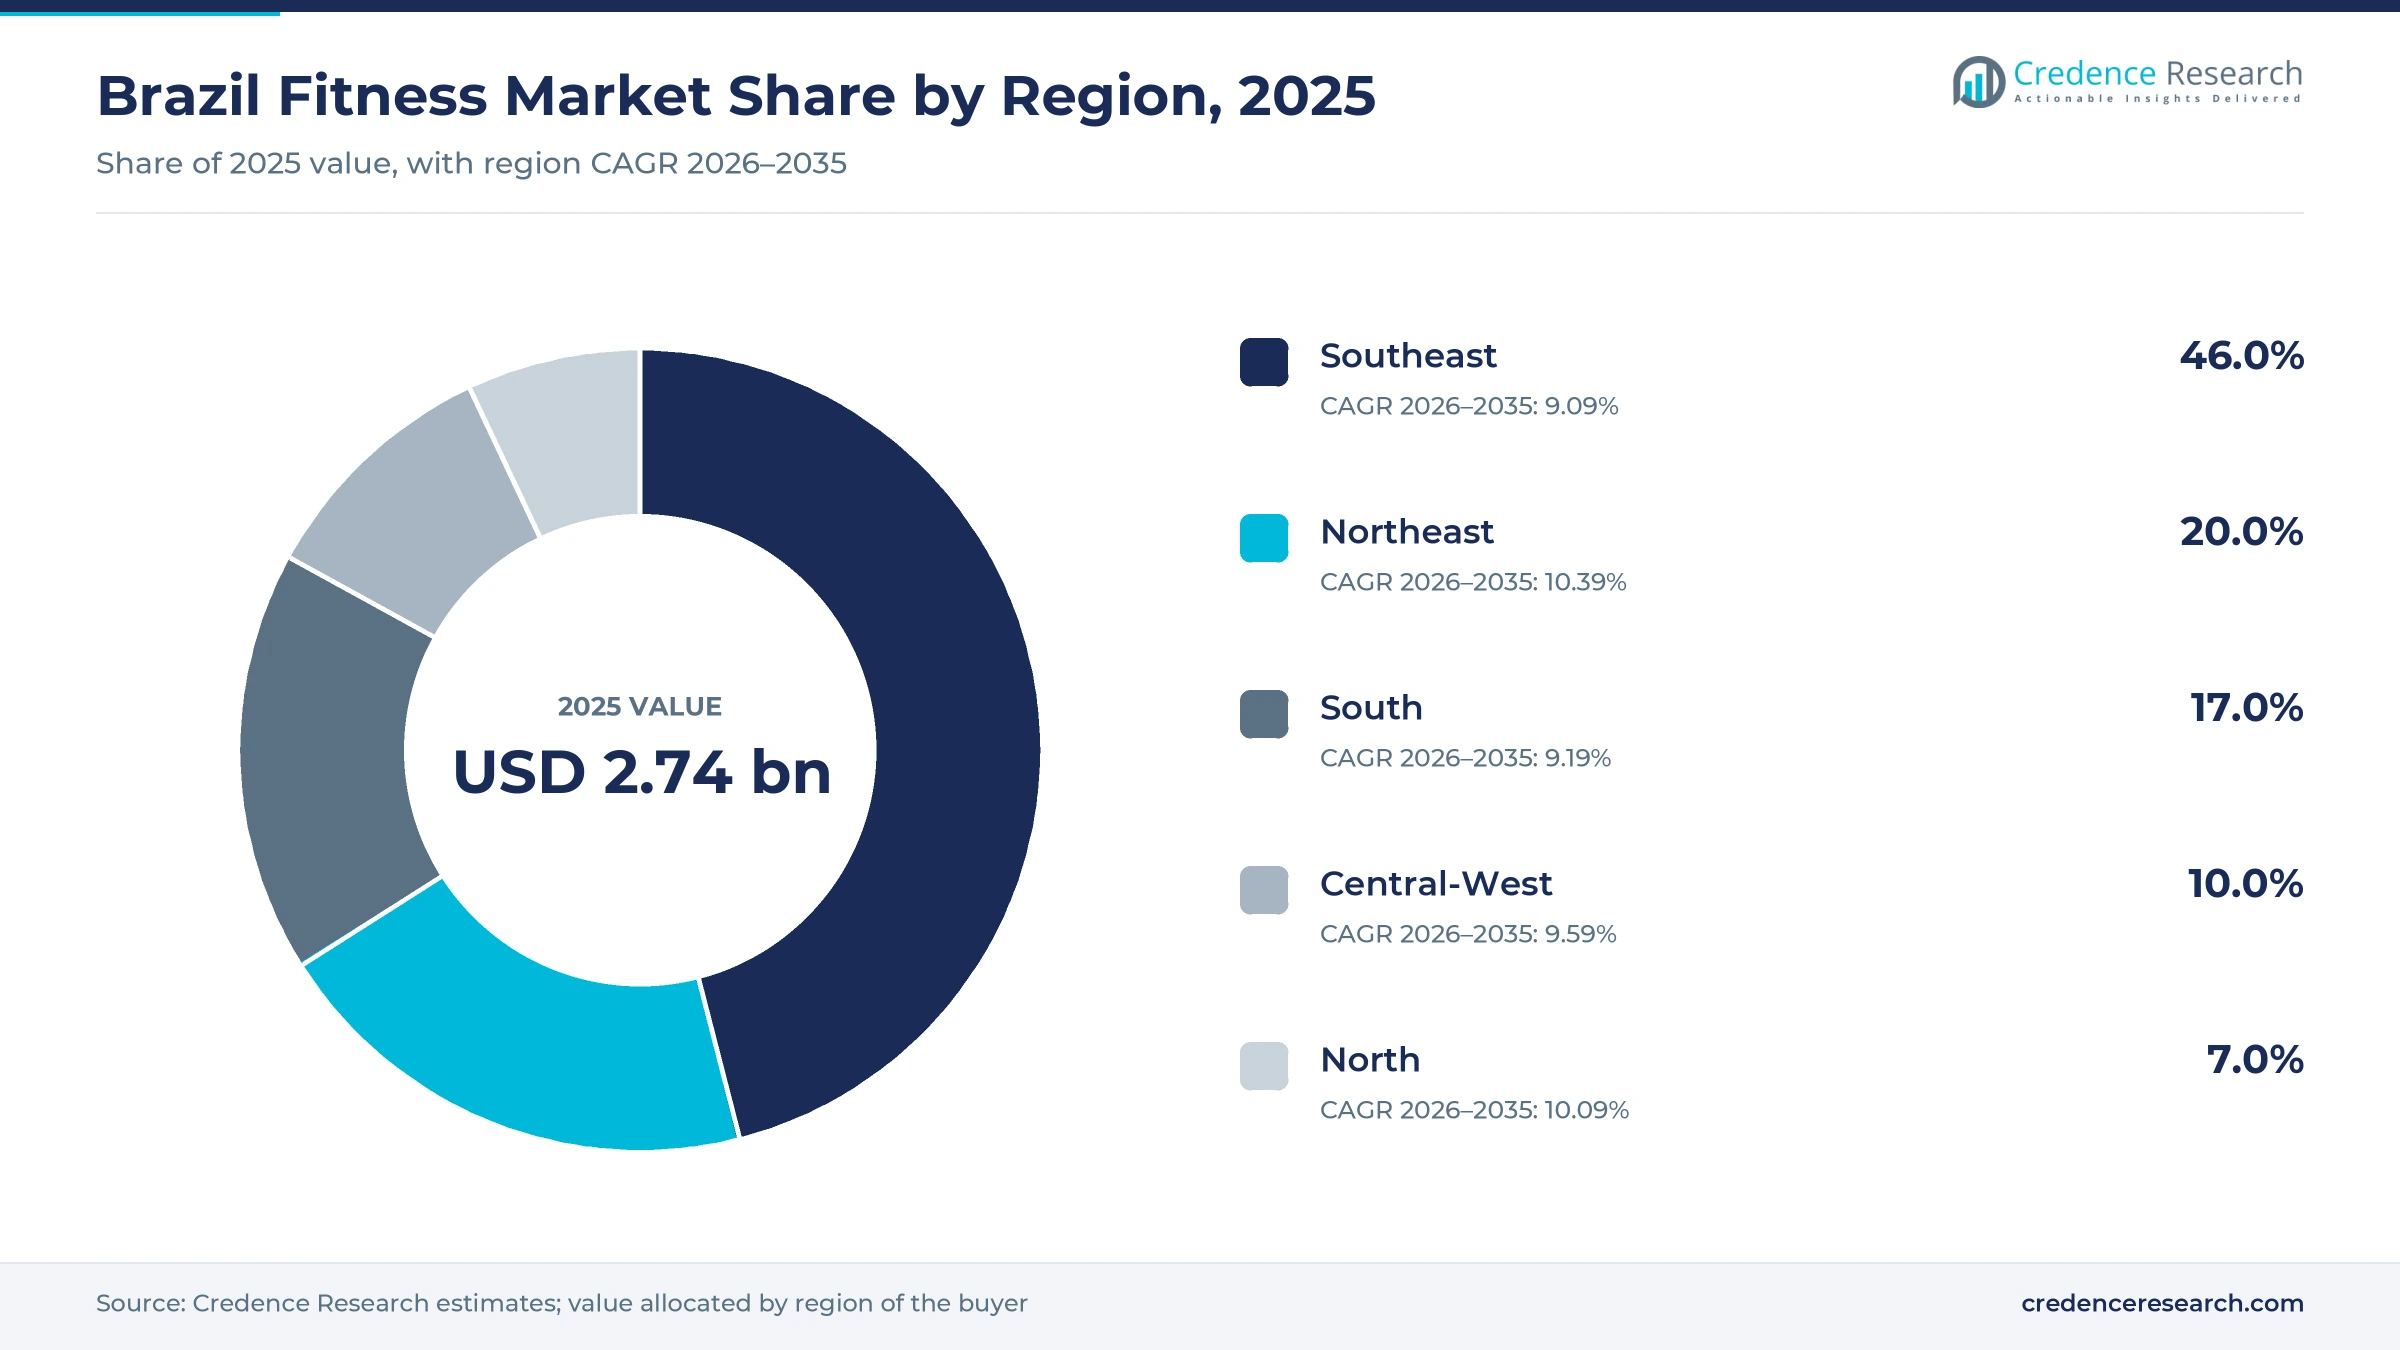
The Brazil fitness market was valued at USD 2.74 billion in 2025 and is projected to increase from USD 3.00 billion in 2026 to USD 6.79 billion by 2035, registering a CAGR of 9.50% during 2026–2035. Demand comes from adults joining low-price gyms, Pilates franchises, martial arts schools and running clubs as obesity rises and employers fund access passes. The Southeast held the largest regional share, 46.0% in 2025, because São Paulo, Minas Gerais and Rio de Janeiro hold the densest networks of clubs and the highest-priced memberships. The Northeast is the fastest-growing region at 10.39% a year, as chains such as Selfit open units across its capitals and interior cities. Commercially, the largest change is the corporate access pass, which sends subsidized members into thousands of partner gyms and has altered how operators fill off-peak capacity and plan new sites.
How many gyms are there in Brazil and what does the market count?
Brazil had 62,718 active physical activity centers in 2025, up from 22,581 in 2015, according to the Panorama Setorial Fitness Brasil reported by Correio in July 2026, and gyms made up about 72% of them. The narrower Health & Fitness Association count puts clubs at 41,332, the third-largest total worldwide. This market counts monthly membership and plan fees paid to gyms, health clubs, studios and organized training groups, including fees routed through employer access platforms.
Equipment sales, supplements, sportswear, one-off race entries, pay-per-session personal training and free public programs sit outside the market value, although they share the same customers. Revenue moves from members and employers to club operators, either directly through monthly plans or indirectly through access platforms that pay gyms per visit or per user. Fitness culture in Brazil is strongly social, so group classes, running crews and combat sports schools carry more weight here than in many club markets.
Brazil Fitness Market Insights
- The market grows from USD 2.74 billion in 2025 to USD 6.79 billion by 2035, a CAGR of 9.50%, as paying participation rises from a low base of about 8% of the population.
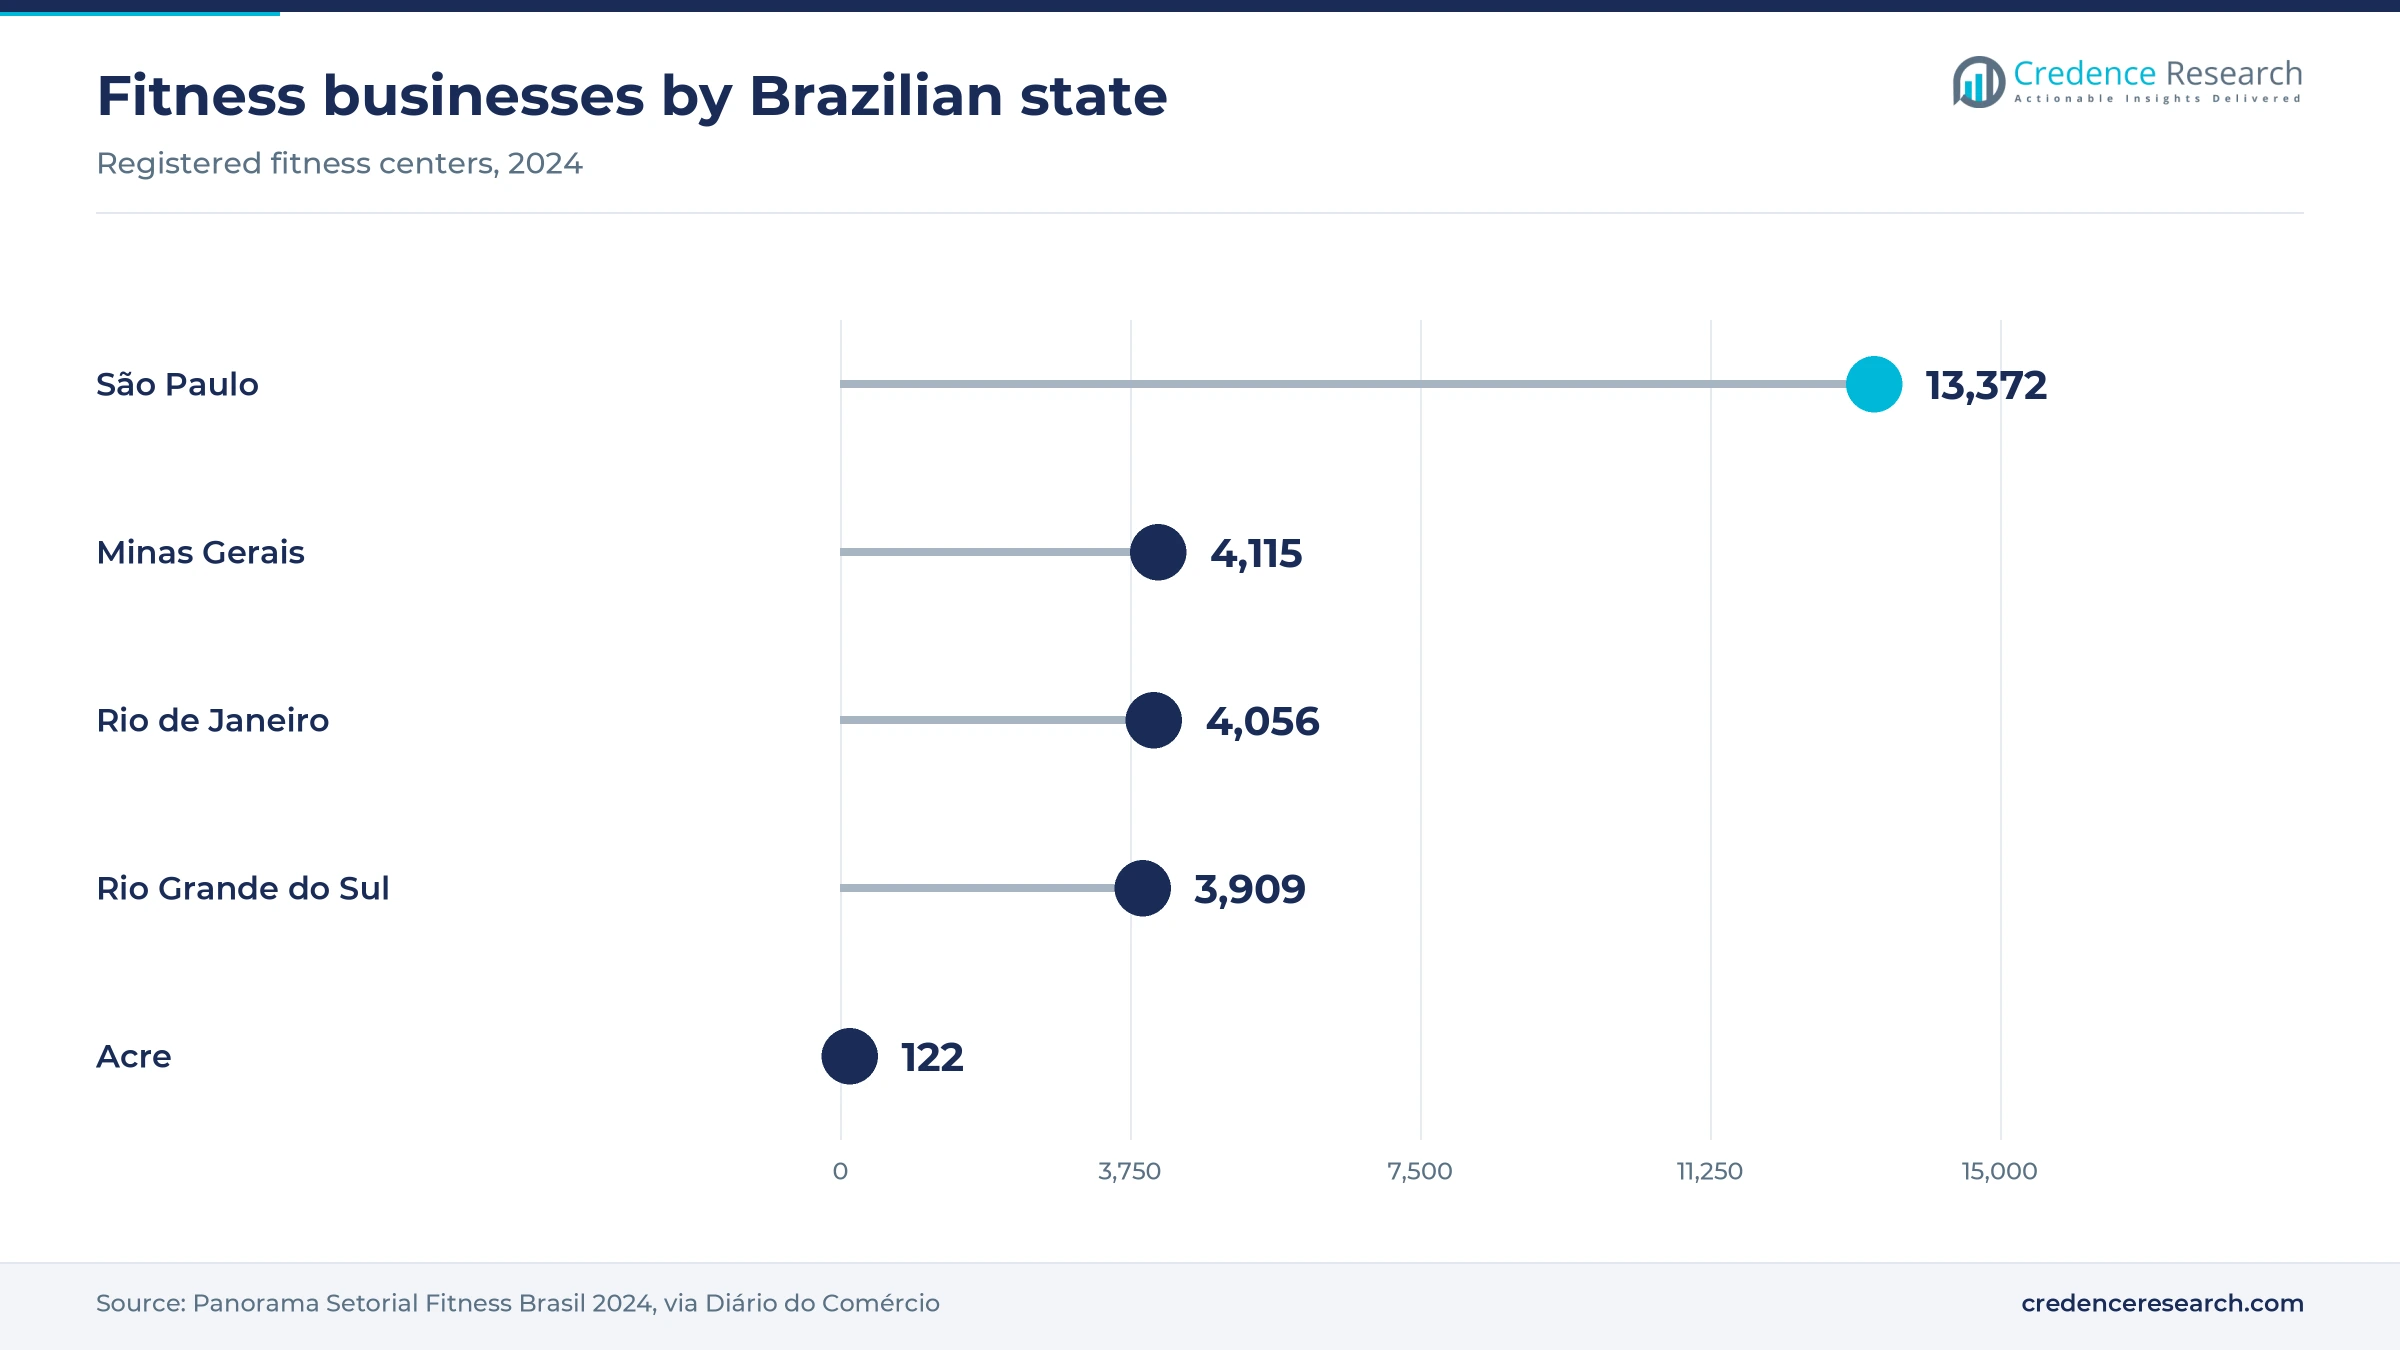
- The Southeast held 46.0% of 2025 value, and São Paulo state alone counted 13,372 fitness businesses in the Panorama Setorial Fitness Brasil 2024.
- Chain Gyms led gym and club formats with 42.0% of 2025 gym and club value, helped by Smart Fit adding 161 units in Brazil during 2025.
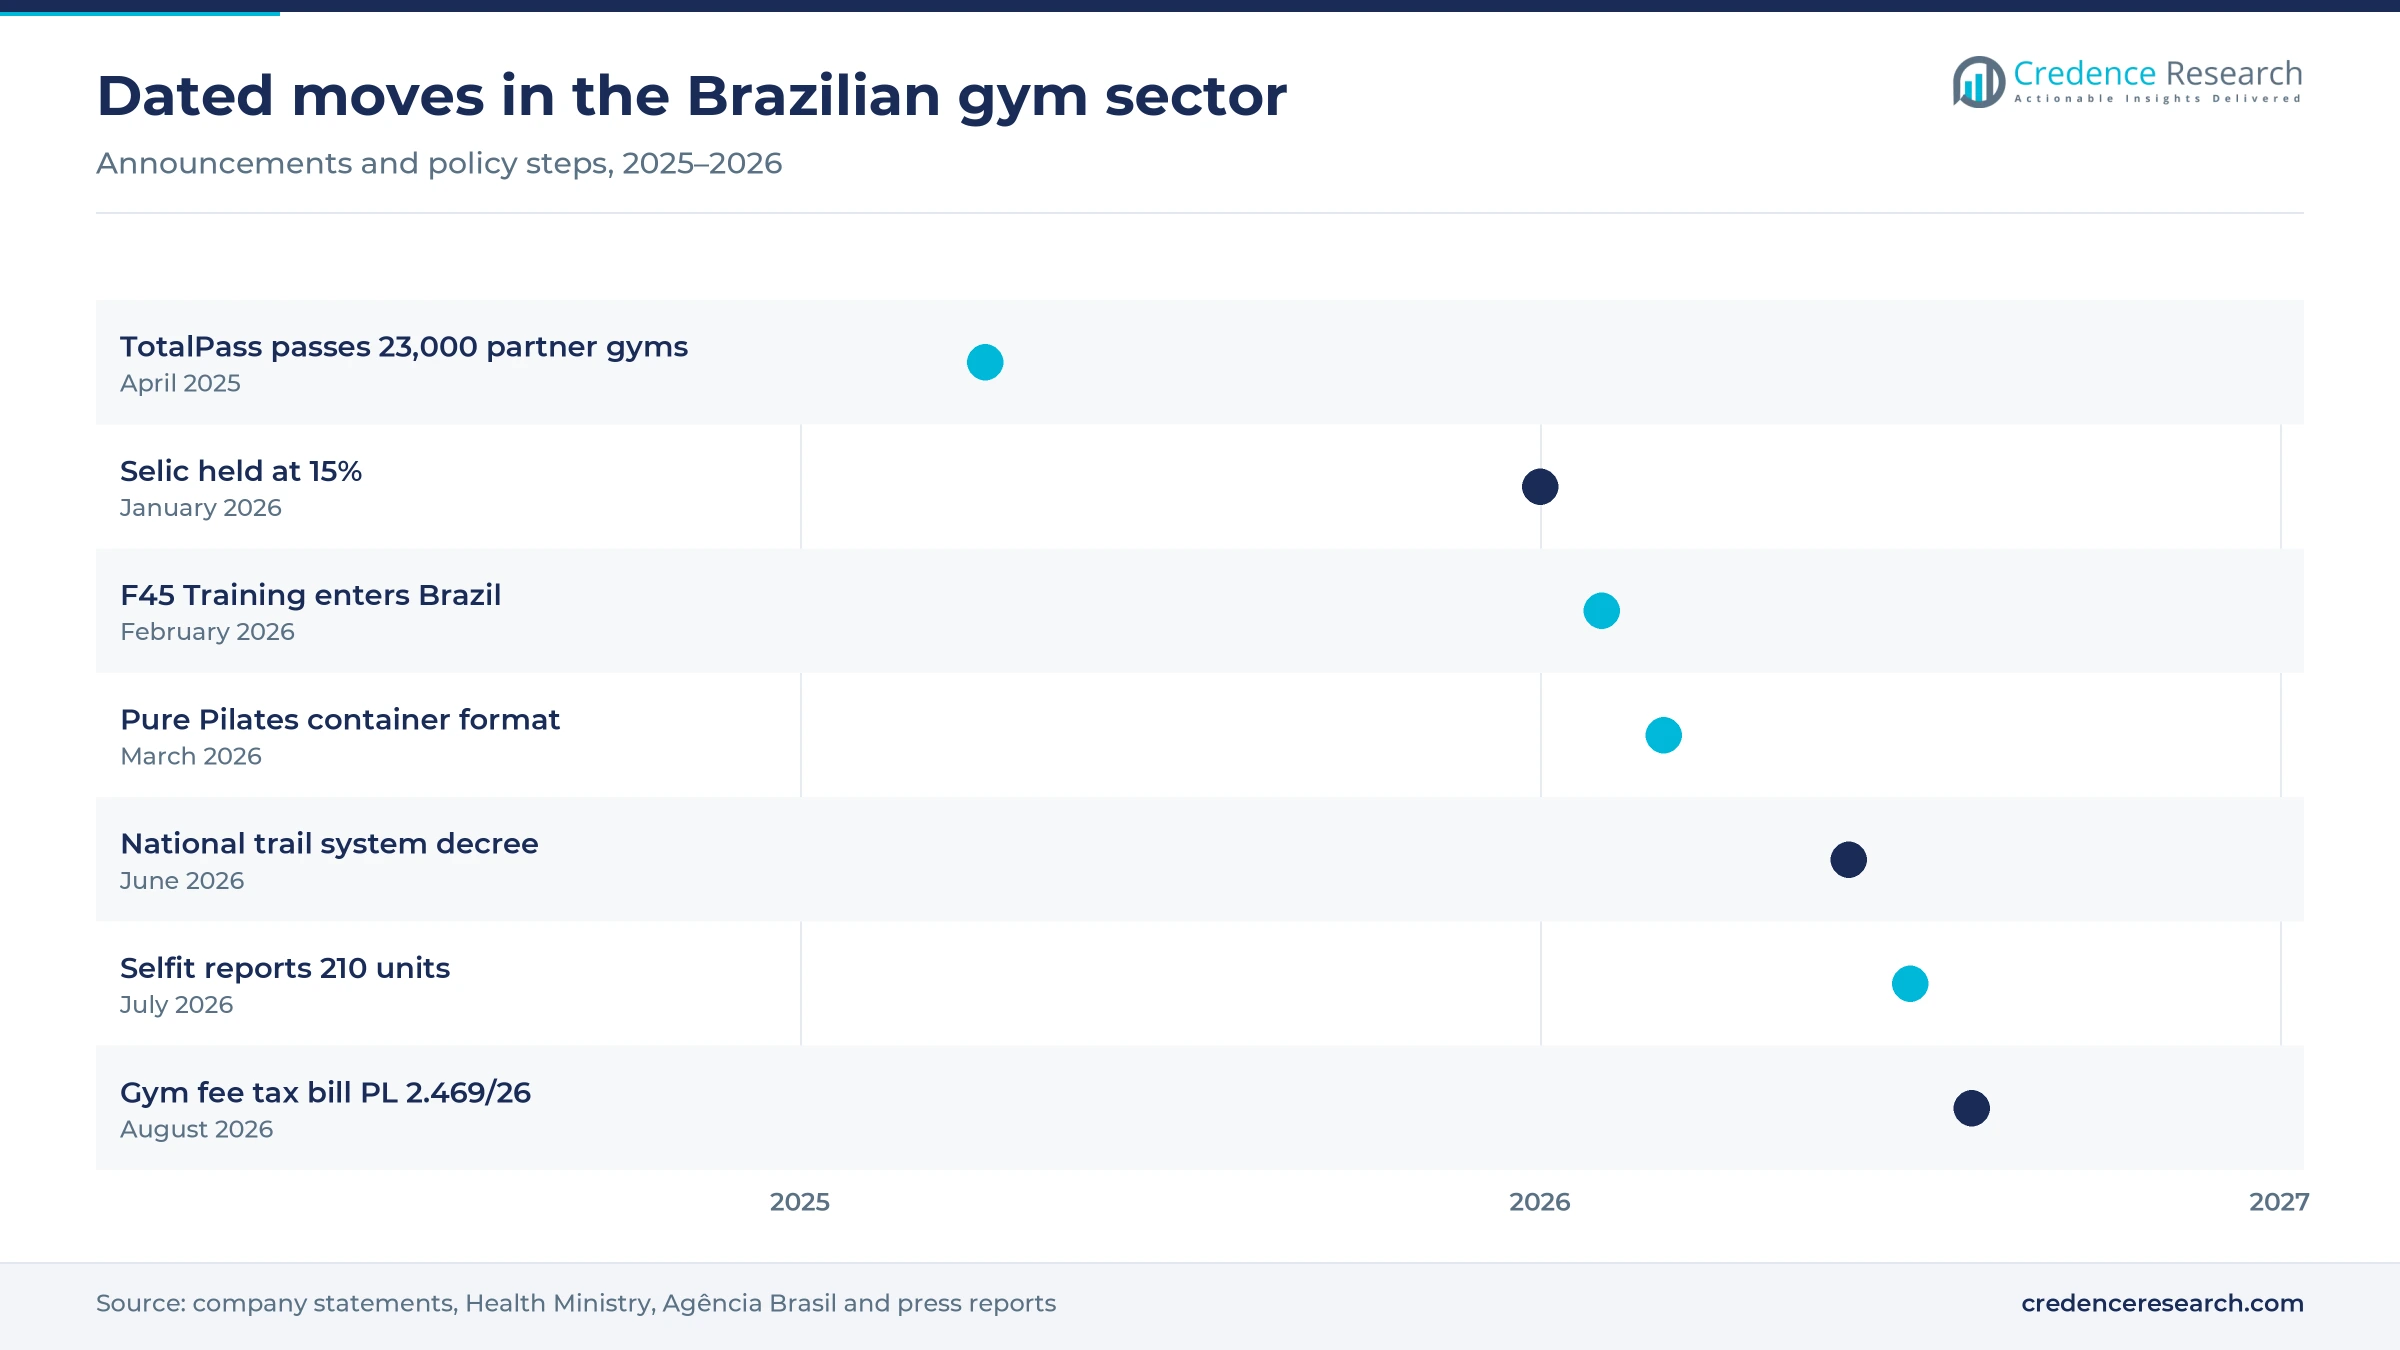
- Corporate passes changed the industry, as TotalPass reached more than 23,000 partner gyms by April 2025 and supplied about 15% of attendance at owned Smart Fit gyms in Brazil.
- Competition is moving toward capital and locations, with Selfit planning up to 300 units by the end of 2026 and F45 Training targeting 1,000 franchised studios.
Chains and Pilates networks set the segment pace
Why chains lead while boutique clubs grow fastest
Based on gym and health club format, the market is categorized into chain gyms, independent gyms, commercial gyms and boutique gyms. Chain Gyms led with 42.0% of 2025 gym and club value because scale operators are opening sites at a pace independents cannot match, and Smart Fit alone added 161 gyms in Brazil during 2025. Boutique Gyms grow fastest at 10.32% a year as premium brands push into new neighborhoods. Diário do Rio reported in September 2026 that Bodytech, with more than 30 units in Rio de Janeiro state, was converting an 11-year-old Fórmula gym in Vila da Penha into a premium club.
Pilates networks anchor studios as functional formats accelerate
Based on fitness classes and studio type, the market is categorized into yoga and Pilates studios, martial arts studios, functional training studios, CrossFit boxes and dance studios. Yoga and Pilates Studios led with 38.0% of 2025 studio and class value because franchising has given the format national reach, and Pure Pilates listed 414 units on the Portal do Franchising in September 2026. Functional Training Studios grow fastest at 10.33% a year as international brands enter the country. O Povo reported that F45 Training arrived in February 2026, targeting 1,000 franchised sites. The Brazilian jiu-jitsu championship also drew a record 7,200 athletes in 2025, according to its national confederation.
Running clubs carry most outdoor training spending
Based on outdoor fitness and bootcamp type, the market is categorized into trail running and hiking clubs, bootcamps and parkour and calisthenics. Trail Running and Hiking Clubs led with 56.0% of 2025 outdoor program value and are also the fastest-growing type at 9.87% a year, as federal policy widens the terrain these groups use. A decree signed June 10, 2026, aims to extend the marked national trail network from 7,000 km to more than 16,000 km, according to Itatiaia. Organized groups add to this base, since Ticket Sports counted 3,500 street running events in 2025, with 1,408 using its group registration module, according to O Liberal.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Gym and Health Clubs | Chain Gyms | 42.0% | Boutique Gyms | 10.32% |
| By Fitness Classes and Studios | Yoga and Pilates Studios | 38.0% | Functional Training Studios | 10.33% |
| By Outdoor Fitness and Bootcamps | Trail Running and Hiking Clubs | 56.0% | Trail Running and Hiking Clubs | 9.87% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Obesity, corporate passes and cheap gyms lift memberships
Rising obesity pushes adults toward supervised exercise
Health data gives the clearest reason for adults to pay for structured exercise in Brazil. The share of adults with obesity climbed from 11.8% in 2006 to 25.7% in 2024, and excess weight reached 62.6%, according to the Health Ministry Vigitel survey. Leisure activity is responding, since adults meeting the 150-minute weekly benchmark rose from 30.3% in 2009 to 42.3% in 2024. Commuting exercise fell from 17.0% to 11.3% over the same period, so more of that activity must be planned and often paid for. As a result, gyms gain members who join for medical reasons, and those members tend to value trainers and supervised classes over bare access.
Corporate access passes bring new members into gyms
Employer-funded passes have become a major channel for filling gyms, particularly among workers who never held a membership. TotalPass counted more than 23,000 partner gyms in Brazil by April 2025, according to Portal IN, and it supplied about 15% of attendance at owned Smart Fit gyms in Brazil during 2025. Wellhub published a commissioned study in March 2026 attributing BRL 13.2 billion of GDP and 202,000 jobs to its 2025 activity in the country. Wellhub's own data in the same release show about 80% of the students it refers are new to their gym. Because employers carry part of the cost, these users add volume that price cuts alone would not reach.
Low-price chains extend gyms into new municipalities
Low-price chains are the main reason access now stretches beyond state capitals and wealthy neighborhoods. Smart Fit ended 2025 with 2,084 gyms in 16 countries and opened 161 in Brazil that year, according to The Rio Times in March 2026, while it guided to 330 to 350 openings for 2026. Bluefit reached 224 units by August 2026, and Selfit had 210 in July 2026, with about 90 more planned by year end. Their growth meets a large gap, since active centers exist in only about 46% of Brazilian municipalities, according to the Panorama Setorial Fitness Brasil. In turn, each new low-price site lowers the distance and price barriers for nearby residents.
A wider supply of trained staff supports premium services
Growth in qualified instructors allows operators to sell services beyond floor access, such as personal training and small group classes. The Federal Council of Physical Education counted 21,100 registered professionals in Ceará alone in 2025, and registrations in Fortaleza rose 14% that year, according to the Diário do Nordeste in January 2026. The Panorama Setorial Fitness 2025 also counted about 1.27 million professionals working across the sector, according to Correio Braziliense in June 2026. This pool supports class-based income at chains such as Bluefit, which bundles group activities into its plans. Consequently, operators can raise income per member without relying only on higher monthly fees, while buyers also pair sessions with activity trackers to follow results.
Running clubs and 24-hour formats reshape participation
The shift toward running clubs and paid group events
Group running is moving outdoor exercise from a free habit into a paid activity with regular fees. Strava said the number of new running clubs in Brazil tripled from a year earlier, according to MKT Esportivo in August 2025. Ticket Sports reported that street race registrations rose 45% in 2024 and projected 25% growth for 2025, according to its chief executive at a June 2025 industry event. The platform also expected 11,240 sporting events in 2025, up 32.24%, with average entries between BRL 130 and BRL 140, and said 49.6% of registrants were first-time participants. Gyms are responding, since this crowd also buys strength plans, coaching and training apps to support their race goals.
The rise of 24-hour gyms and compact studio formats
Operators are redesigning sites around irregular schedules and smaller footprints instead of the traditional large club. Bluefit is betting on 24-hour operation in units of more than 1,000 square meters at a build cost of BRL 3 million to BRL 6 million each, according to the Diário do Comércio in August 2026. O Povo reported in February 2026 that São Paulo chain Gaviões is part of a wider 24-hour wave reaching Fortaleza. Pure Pilates moved in the opposite size direction, launching a container studio format in March 2026 that removes the search for a retail site and targets partnerships with large retailers. These formats spread fixed cost across more usage hours, or across fewer square meters, which suits mid-size cities.
Opening in mid-size cities and underserved municipalities
The clearest opening for new capacity lies outside the largest metropolitan areas, where competition is thinner. More than half of Brazilian municipalities had no active center, according to the Panorama Setorial Fitness Brasil reported by Correio in July 2026. The same industry review projects more than 70,000 registered businesses by 2027, according to the Diário do Nordeste. Fortaleza shows what density can look like, with 1,097 units and 4.3 establishments for every 10,000 residents. Safra analysts estimated room for about 1,780 additional Smart Fit gyms in Brazil, as The Rio Times reported in March 2026. Operators able to fund sites in mid-size cities can therefore secure locations before national chains arrive.
Opening in preventive care and public health partnerships
Preventive health is an opening for gyms and studios that can show measurable results to employers and public bodies. The federal Viver Mais Brasil plan includes BRL 300 million of investment, with BRL 109 million for incentives to physical activity, according to a 2026 Health Ministry presentation. The same plan adds BRL 40 million of operating funds for Academia da Saúde sites and raises funding for sites with one or more professionals from BRL 3,000 to BRL 5,000. Separately, bill PL 2.469/26 would allow an income tax deduction of up to BRL 3,000 a year for gym fees, according to O Povo in August 2026. Operators that report attendance and health outcomes are better placed to win corporate and municipal contracts.
Dropout and costly credit hold operators back
High member dropout erodes the value of each sale
Member churn is the industry's most persistent problem, and ACAD Brasil puts average annual dropout between 40% and 60%, according to Estado de Minas in July 2026. Smaller independent gyms feel this most because they spend heavily to replace lost members. The consequence is lower lifetime value and constant sales spending. Operators are responding with onboarding programs, trainer check-ins and community classes, although few publish audited retention results that would let buyers compare them.
Expensive credit raises the cost of every new gym
Credit costs weigh on an industry that funds openings ahead of member income, since the benchmark Selic rate stood at 15% in January 2026, its highest level since July 2006. A new Bluefit unit needs BRL 3 million to BRL 6 million, according to the Diário do Comércio. Independent owners and small franchisees are hit hardest because they lack the equity backing of large chains. Many therefore delay refits, lease equipment or sell to consolidators rather than expand on bank debt.
Low fees leave thin room to absorb rising costs
Brazilian gym prices are low by international standards, which limits how quickly operators can pass through costs. A CupomValido study published in January 2023 put the average monthly fee at BRL 110.85 against a world average of BRL 196.37. Official inflation closed 2025 at 4.26%, according to Agência Brasil, so rent and wages keep rising against those fees. Low-price entrants deepen this pressure on independents, and O Povo reported in February 2026 that many local Fortaleza gyms closed as Smart Fit expanded there.
Uneven coverage keeps much of the population out of reach
Supply remains heavily concentrated, with the Southeast holding about two in five establishments, according to the Diário do Nordeste in January 2026. Acre counted just 122 fitness businesses in the Panorama Setorial Fitness Brasil 2024, against 13,372 in São Paulo state. Even national chains leave gaps, since Selfit reported no units in Rondônia, Acre, Paraná or the Federal District in July 2026. Lower incomes and smaller catchments in those areas make payback slower, so operators need lighter formats there.
Southeast leads as the Northeast adds gyms fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Southeast | 1.26 | 46.0% | 9.09% |
| Northeast | 0.55 | 20.0% | 10.39% |
| South | 0.47 | 17.0% | 9.19% |
| Central-West | 0.27 | 10.0% | 9.59% |
| North | 0.19 | 7.0% | 10.09% |
Southeast holds the densest and highest-priced club base
The Southeast held 46.0% of 2025 value and grows at 9.09% a year. São Paulo state counted 13,372 fitness businesses, Minas Gerais 4,115 and Rio de Janeiro 4,056 in the Panorama Setorial Fitness Brasil 2024, according to the Diário do Comércio in March 2025. São Paulo city alone had 3,945 and Rio de Janeiro 1,869, the two highest municipal totals. Premium brands such as Bodytech concentrate here, which lifts value above the region's two-in-five share of establishments.
Northeast adds gyms fastest behind regional chains
The Northeast held 20.0% of 2025 value and is the fastest-growing region at 10.39% a year. Ceará reached 2,490 establishments by July 2025, up about 93% from 2019, and Fortaleza ranked fifth among Brazilian cities with 1,097 units. Selfit operates 50 units in Pernambuco alone and reports more than 5,000 students at its Piedade site. Selfit chief executive Fernando Menezes wrote in April 2026 that growth in Alagoas, Pernambuco, Maranhão, Piauí and Bahia topped 70%.
South combines mature clubs with premium equipment demand
The South held 17.0% of 2025 value and grows at 9.19% a year. Rio Grande do Sul counted 3,909 fitness businesses in the Panorama Setorial Fitness Brasil 2024, the fourth-highest state total. Higher incomes support well-equipped clubs and residential gyms, and Life Fitness chose Balneário Camboriú for one of four new Brazilian stores in July 2026 because of its high-end real estate market. Selfit has no units in Paraná, which leaves room for low-price competition in that state.
Central-West grows around Brasília and its premium clubs
The Central-West held 10.0% of 2025 value and grows at 9.59% a year. Life Fitness opened a 1,300-square-meter space in Brasília during July 2026 as a business center for the surrounding region, according to the Jornal de Brasília. Selfit reported no units in the Federal District that same month, which shows how unevenly low-price chains have covered the capital. Income levels in Brasília support premium clubs, while smaller cities in the region rely on independent gyms.
North stays smallest as coverage remains thin
The North held 7.0% of 2025 value and grows at 10.09% a year from the smallest base. Acre recorded 122 fitness businesses in the Panorama Setorial Fitness Brasil 2024, the lowest count of any state. Selfit reported no units in Rondônia or Acre in July 2026, so independents still serve most of the demand in those states. Long distances and smaller catchments slow chain entry, so lighter formats are the likely route into these states.
Brazil gym industry news and dated moves, 2025–2026
| Development | Status and market relevance |
|---|---|
| In April 2025, TotalPass said it had more than 23,000 partner gyms across Brazil and named Fortaleza a priority market. | Active; shows the reach of employer-funded access |
| In February 2026, F45 Training arrived in Brazil with units in Barra da Tijuca and Moema, targeting 1,000 franchised sites. | Early rollout; adds an international functional format |
| In March 2026, Smart Fit reported 2,084 gyms at the end of 2025 and guided to 330 to 350 openings for 2026. | Guidance in progress; sets the pace for chain expansion |
| In July 2026, Selfit reported 210 units and said it could reach up to 300 by the end of the year. | In progress; deepens low-price coverage |
| In August 2026, bill PL 2.469/26 proposed an income tax deduction of up to BRL 3,000 a year for gym fees. | Under analysis in Congress; not yet law |
Platforms and connected gear change how members train
- Access platforms route employer-funded users to partner gyms, and TotalPass supplied about 15% of attendance at owned Smart Fit gyms in Brazil during 2025.
- Connected equipment gives premium clubs a way to track sessions, and Technogym described Brazil in October 2025 as one of its five main geographies.
- Round-the-clock access lets chains such as Bluefit keep sites open 24 hours, and its chief executive positions the chain around technology and convenience.
- Community running apps organize outdoor groups at low cost, and Strava reported in August 2025 that new running clubs in Brazil had tripled in a year.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Scale chains and access platforms shape competition
Competition splits between scale chains, premium clubs, specialist franchises and access platforms. Smart Fit sets the pace on openings and members, with 5.2 million members across its network at the end of 2025, and its controlling group is linked to TotalPass. Bluefit and Selfit compete in the low-price tier, with Bluefit favoring street locations and 24-hour operation, and Selfit building density in the Northeast. Bodytech defends the premium tier and uses Fórmula sites as an entry point that can later convert into its main brand. Pure Pilates and F45 Training compete through franchising, which spreads capital among local owners. Wellhub and TotalPass compete for employers and gym supply at once. Suppliers such as Life Fitness and Technogym sell to all of these operators and also to homeowners who buy home workout equipment for private spaces.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Smart Fit | Low-price chain | Added 161 gyms in Brazil in 2025; largest network in Latin America |
| Bluefit | Low-price chain | 224 units by August 2026, with 24-hour street locations |
| Selfit | Low-price chain | 210 units in July 2026, with 50 in Pernambuco |
| Bodytech | Premium chain | More than 30 units in Rio de Janeiro state; converts Fórmula sites |
| Pure Pilates | Studio franchise | 414 units listed in September 2026; container format launched in March 2026 |
| F45 Training | Studio franchise | Entered in February 2026 with a target of 1,000 franchised units |
| TotalPass | Access platform | More than 23,000 partner gyms in Brazil by April 2025 |
| Wellhub | Access platform | Corporate wellness platform; published its Brazil impact study in March 2026 |
| Life Fitness | Equipment supplier | Opened four Brazilian stores by July 2026 |
| Technogym | Equipment supplier | Counts Brazil among its five main geographies |
Penetration, not gym count, decides the next decade
Credence Research's view is that the next decade depends on penetration rather than on the headline count of gyms. About 8% of Brazilians attended gyms in 2025, according to Selfit founder Leonardo Pereira, against 24.9% in the United States in Health & Fitness Association data, the Diario de Pernambuco reported. Yet establishment numbers have nearly tripled in a decade, so the sector can no longer rely on new sites alone to win members. Operators that lower the dropout rates reported by ACAD Brasil will gain more than those that only add locations.
How Credence Research built the estimates
The report uses 2025 as the base year, 2026 as the first forecast year and 2035 as the end of the forecast. Market values come from the Credence Research model, built bottom up from member counts, average fees and establishment data, then checked against public information. Segment and regional splits in this report are Credence Research estimates. Sources are government statistics, trade body data, company disclosures and press reports named in the text. No interviews or surveys were conducted for this edition of the report.
Mid-size cities and corporate access drive 2035 value
The Brazil fitness market is forecast to reach USD 6.79 billion by 2035, with growth of 9.50% a year over 2026–2035. Most of the added value should come from mid-size cities, corporate access users and studio formats that fit smaller sites. Chain expansion will likely slow in the largest capitals, where density is already high, and shift toward the Northeast and interior municipalities. Lower interest rates would speed openings, while the outcome of bill PL 2.469/26 could lift consumer demand if Congress approves it. Providers of functional training equipment should benefit as studio formats multiply.
Frequently Asked Questions
How big is the Brazil fitness market?
How many gyms are there in Brazil?
What share of Brazilians go to the gym?
What is the latest news in the Brazil fitness industry?
Which are the largest gym chains in Brazil?
Which region leads the Brazil fitness market?
How popular is Brazilian jiu-jitsu as a paid activity?
How does corporate wellness affect Brazilian gyms?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Gym and Health Clubs
- 1.2.1 Chain Gyms
- 1.2.2 Independent Gyms
- 1.2.3 Commercial Gyms
- 1.2.4 Boutique Gyms
- 1.3 By Fitness Classes and Studios
- 1.3.1 Yoga and Pilates Studios
- 1.3.2 Martial Arts Studios
- 1.3.3 Functional Training Studios
- 1.3.4 CrossFit Boxes
- 1.3.5 Dance Studios
- 1.4 By Outdoor Fitness and Bootcamps
- 1.4.1 Trail Running and Hiking Clubs
- 1.4.2 Bootcamps
- 1.4.3 Parkour and Calisthenics
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 2.74 billion → 2035: USD 6.79 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Brazil Fitness Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Brazil Fitness Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Brazil Fitness Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Brazil Fitness Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Brazil Fitness Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Brazil Fitness Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Brazil Fitness Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Brazil Fitness Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 2.74 billion → 2035: USD 6.79 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Brazil Fitness Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Gym and Health Clubs - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Chain Gyms
- 12.3.7.2 Independent Gyms
- 12.3.7.3 Commercial Gyms
- 12.3.7.4 Boutique Gyms
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Fitness Classes and Studios - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Yoga and Pilates Studios
- 12.4.7.2 Martial Arts Studios
- 12.4.7.3 Functional Training Studios
- 12.4.7.4 CrossFit Boxes
- 12.4.7.5 Dance Studios
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Outdoor Fitness and Bootcamps - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Trail Running and Hiking Clubs
- 12.5.7.2 Bootcamps
- 12.5.7.3 Parkour and Calisthenics
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Brazil Fitness Geographic Market Outlook, 2025-2035
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Brazil Fitness Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Brazil Fitness Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Smart Fit
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Bluefit
- 17.4 Selfit
- 17.5 Bodytech
- 17.6 Pure Pilates
- 17.7 F45 Training
- 17.8 TotalPass
- 17.9 Wellhub
- 17.10 Life Fitness
- 17.11 Technogym
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

