
Market Overview
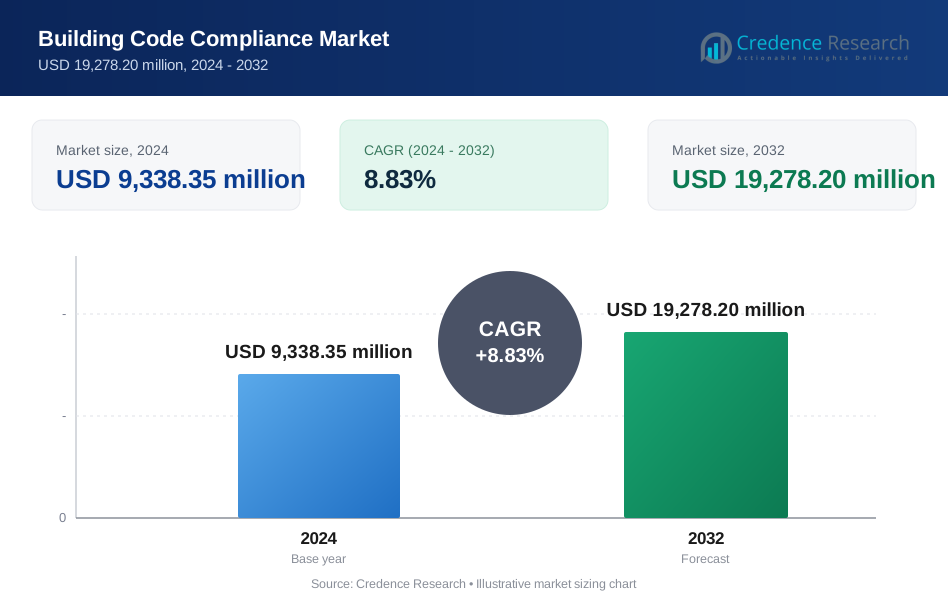
The Building Code Compliance market is projected to grow from USD 9,338.35 million in 2024 to USD 19,278.20 million by 2032, reflecting a compound annual growth rate (CAGR) of 8.83%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Building Code Compliance Market Size 2024 | USD 9,338.35 million |
| Building Code Compliance Market, CAGR | 8.05% |
| Building Code Compliance Market Size 2032 | USD 19,278.20 million |
The Building Code Compliance market is driven by increasing regulatory requirements and the growing emphasis on safety and sustainability in construction. As urbanization accelerates, governments worldwide are enforcing stricter building codes to enhance structural integrity and environmental performance. Additionally, advancements in technology, such as Building Information Modeling (BIM) and automated compliance checking tools, streamline adherence to regulations. These innovations not only improve efficiency but also reduce the risk of costly non-compliance penalties. Furthermore, the rising demand for green buildings is pushing developers to adopt comprehensive compliance strategies that align with evolving standards.
The Building Code Compliance Market is prominently driven by key regions such as North America and Europe, where stringent regulations and a strong focus on safety standards prevail. In North America, major players like Intertek, SGS, and Bureau Veritas lead the market by providing comprehensive compliance services. Meanwhile, Europe sees significant contributions from companies like TUV Rheinland and DEKRA, which enhance compliance through rigorous testing and certification processes. These regions are characterized by a robust construction sector, increasing investments in infrastructure, and a growing emphasis on sustainability, collectively fostering a dynamic environment for building code compliance services.
Market Drivers
Rising Adoption of Building Information Modeling (BIM)
The adoption of Building Information Modeling (BIM) is transforming the construction landscape by enabling architects, engineers, and contractors to collaborate effectively on compliance matters. BIM serves as a digital representation of a building, allowing stakeholders to visualize and assess the design against building codes early in the process. For instance, a study published in the American Journal of Civil Engineering and Architecture highlighted that BIM improves design quality, reduces construction costs, and enhances energy efficiency. By identifying potential code violations at the design stage, BIM minimizes the need for costly modifications later, thus streamlining the compliance process and enhancing overall project efficiency.
Focus on Sustainable and Green Buildings
Environmental awareness is driving a significant focus on sustainable and green building practices within the industry. Many building codes now incorporate requirements related to energy efficiency, water conservation, and the use of sustainable materials. For instance, the World Green Building Council emphasizes that sustainable built environments play a critical role in decarbonizing the global economy and creating resilient, thriving communities. As consumers, investors, and tenants increasingly seek buildings that meet these sustainability standards, the demand for compliance services rises. This trend underscores the importance of adherence to evolving regulations, which not only benefits the environment but also enhances the marketability of construction projects.
Government Regulations and Stringent Building Codes
Governments worldwide are implementing and enforcing stricter building codes to ensure the safety and well-being of occupants. These regulations encompass various aspects, including structural integrity, fire safety, accessibility, and energy efficiency. By mandating compliance with these codes, authorities aim to enhance the overall safety of buildings. Additionally, sustainability has become a crucial focus, with building codes often incorporating provisions for energy efficiency, water conservation, and the use of environmentally friendly materials. This shift drives demand for compliance services as stakeholders seek to align their projects with these evolving standards.
Increasing Investments in Construction Projects
As economies grow and urbanization accelerates, the construction sector is experiencing a significant surge in activity, leading to increased demand for building code compliance services. Government initiatives aimed at improving infrastructure such as constructing new roads, bridges, and public facilities further fuel this growth. These investments create a robust market for compliance services, as developers and contractors recognize the necessity of adhering to regulatory frameworks to ensure successful project completion and avoid potential penalties.
Market Trends
Increasing Focus on Sustainability and Green Building
The construction industry is witnessing an intensified focus on sustainability and green building practices, primarily driven by the global push for environmental responsibility. A notable trend is the rise of net-zero buildings, which are designed to produce as much energy as they consume. Achieving this ambitious goal necessitates rigorous compliance with energy efficiency codes and standards, fostering demand for specialized compliance services. For instance, LEED projects have diverted more than 80 million tons of waste from landfills, and by 2030, this number is expected to grow to 540 million tons. In tandem with this, building codes are increasingly incorporating requirements for sustainable materials, which drives the need for thorough material certification and sourcing processes. As stakeholders prioritize sustainable practices, compliance services that facilitate adherence to these evolving regulations become essential, supporting the broader objective of reducing the environmental impact of construction.
Advancements in Building Information Modeling (BIM) and Digitalization
The adoption of Building Information Modeling (BIM) is reshaping the landscape of construction by integrating compliance checks directly into the design and construction processes. This approach significantly reduces errors and enhances efficiency, allowing stakeholders to visualize and validate their designs against building codes before physical construction begins. Moreover, BIM facilitates data-driven compliance, providing accurate and efficient verification of code requirements. Complementing these advancements is the growing trend of digitalization and automation in the compliance process. Cloud-based platforms streamline compliance workflows by offering access to extensive code databases, online permitting, and inspection scheduling. Additionally, automation tools are emerging to handle various compliance checks, such as energy modeling and accessibility verification. This combination of digital solutions not only accelerates compliance processes but also enhances accuracy, positioning the construction industry for future innovations that align with modern building standards. As these trends continue to evolve, they underscore the industry's commitment to integrating advanced technologies that promote sustainable and efficient building practices.
Market Challenges Analysis
Complexity and Constantly Evolving Codes
The building code landscape presents significant challenges due to its inherent complexity and continuous evolution. Stakeholders often grapple with navigating multiple codes that vary across jurisdictions, making it difficult to stay current with the latest requirements. For instance, a survey by the National Multifamily Housing Council (NMHC) found that a significant number of respondents reported challenges due to variations in code requirements and interpretations between jurisdictions. This situation is exacerbated by the frequent updates to codes, which are implemented to accommodate new technologies, safety standards, and sustainability objectives. As a result, ensuring compliance becomes increasingly intricate, requiring ongoing education and adaptation. The dynamic nature of these regulations demands that architects, engineers, and contractors invest considerable time and resources to remain informed, which can strain project timelines and budgets.
Interpretation, Enforcement, and Cost Implications
Interpretation and enforcement of building codes add another layer of complexity to compliance efforts. Due to the often subjective nature of building codes, inconsistencies can arise, leading to disputes among stakeholders regarding compliance interpretations. This challenge is further compounded by limited resources within enforcement agencies, which may struggle to effectively monitor and enforce compliance, particularly for smaller or more complex projects. Additionally, the financial implications of ensuring compliance can be substantial. The costs associated with adhering to building codes, especially in complex or retrofitting projects, can significantly inflate construction budgets. Delays caused by non-compliance issues can further disrupt project schedules, leading to missed deadlines and increased costs. Furthermore, the lack of awareness and training among stakeholders regarding building codes can hinder effective implementation. Many professionals, including architects and contractors, may not possess the necessary knowledge or resources to navigate compliance effectively. Addressing these challenges requires a multifaceted approach, including increased education, streamlined enforcement processes, and a commitment to leveraging technology for improved compliance.
Market Segmentation Analysis:
By Service Type:
The Building Code Compliance market is segmented primarily by service type, encompassing testing and inspection, certification, project management, consulting, and others. Testing and inspection services are crucial as they ensure that structures meet all relevant codes and regulations before occupancy. This segment is increasingly important due to heightened safety standards and the need for compliance with ever-evolving regulations. Certification services validate that materials and processes adhere to specified codes, fostering trust among stakeholders and enhancing market competitiveness. Project management and consulting services are also pivotal, offering expertise to navigate complex regulatory landscapes and ensuring timely completion of construction projects while meeting compliance requirements. Other services may include training and technological support, further facilitating adherence to building codes.
By End-User:
The market is segmented by end-user, including residential, commercial, and industrial sectors. The residential segment is driven by the increasing demand for safe and sustainable housing, prompting homeowners and builders to seek compliance with stringent codes. The commercial sector is experiencing growth due to investments in infrastructure and office space, necessitating adherence to building regulations. In the industrial sector, compliance is crucial for operational efficiency and safety, influencing the adoption of comprehensive compliance services across various industries. This multifaceted approach to segmentation enhances the overall robustness and adaptability of the Building Code Compliance market.
Segments:
Based on Service Type:
- Testing & Inspection
- Certification
- Project Management
- Consulting
- Others
Based on End-User:
- Residential
- Commercial
- Industrial
Based on Sourcing Type:
- In-house
- Outsourced
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the Building Code Compliance market, accounting for approximately 35% of the total market. This dominance is primarily attributed to the region's stringent regulatory environment and a strong focus on safety standards. The presence of established construction firms and a robust infrastructure development agenda further bolster demand for compliance services. The U.S. government continually updates building codes to enhance safety, energy efficiency, and sustainability, necessitating compliance across residential, commercial, and industrial sectors. Additionally, the increasing emphasis on green building practices and net-zero construction projects is driving the adoption of advanced compliance solutions in the region. As construction activity ramps up, stakeholders are increasingly turning to testing, inspection, and certification services to ensure adherence to the evolving regulatory landscape.
Asia Pacific
In contrast, the Asia Pacific region is rapidly emerging as a key player in the Building Code Compliance market, capturing around 30% of the global market share. This growth is fueled by rapid urbanization, increasing infrastructure investments, and a rising awareness of safety standards among stakeholders. Countries like China and India are experiencing significant construction booms, prompting a greater focus on compliance to meet both local and international building codes. The region is also witnessing a shift towards adopting advanced technologies, such as Building Information Modeling (BIM), to streamline the compliance process. As governments introduce stricter regulations and initiatives aimed at sustainable development, the demand for compliance services is expected to surge, making Asia Pacific a crucial region for future market growth.
Key Player Analysis
- Acme Analytical Laboratories
- ALS
- Applus+
- Bureau Veritas
- DEKRA
- Element Materials Technology
- Engineering Systems
- EnviroScience
- EAG Laboratories
- Eurofins Scientific
- Intertek
- MISTRAS
- NSF International
- QPS
- SGS
- SOCOTEC
- TUV Rheinland
- TUV SUD
- Building Control Alliance
Competitive Analysis
The competitive landscape of the Building Code Compliance Market features prominent players such as Intertek, SGS, Bureau Veritas, DEKRA, TUV Rheinland, TUV SUD, Element Materials Technology, Applus+, UL Solutions, NSF International, MISTRAS, Building Control Alliance, SOCOTEC, QPS, Acme Analytical Laboratories, ALS, Eurofins Scientific, EnviroScience, EAG Laboratories, and Engineering Systems. These companies leverage their extensive expertise and technological advancements to provide a range of compliance services, including testing, inspection, and certification. Strategic partnerships and acquisitions are common as firms aim to enhance their service offerings and expand their market reach. Additionally, innovation in digital tools, such as cloud-based compliance platforms and Building Information Modeling (BIM), is increasingly shaping the competitive dynamics. With growing awareness of safety regulations and sustainability standards, these key players are well-positioned to capitalize on emerging opportunities while addressing the complexities of building code compliance across various sectors.
Recent Developments
- In September 2024, Bureau Veritas granted approval in principle (AIP) to Ponant for its new twin-screw sailing passenger vessel concept, Swap2Zero.
- In September 2024, DEKRA’s inspection report was involved in a case where WeBuyCars refunded a buyer of a ‘dangerous’ car.
- In September 2024, Applus+ was recognized in TIME and Statista’s 2024 ranking of World’s Most Sustainable Companies.
- In September 2023, Eurofins EAG Laboratories announced the addition of a new laser ablation system to its worldwide fleet.
Market Concentration & Characteristics
The Building Code Compliance Market exhibits a moderate level of concentration, characterized by a blend of established firms and emerging players. Major companies, such as Intertek, SGS, and Bureau Veritas, dominate the landscape, benefiting from extensive experience and a broad range of compliance services. This concentration fosters a competitive environment where firms continuously innovate to enhance their offerings and meet evolving regulatory standards. The market is also influenced by technological advancements, particularly in digital tools and Building Information Modeling (BIM), which streamline compliance processes and improve efficiency. Additionally, the emphasis on sustainability and safety has led to increased collaboration among stakeholders, driving the development of integrated solutions. As the demand for compliance services grows across residential, commercial, and industrial sectors, the market will likely see further consolidation, with leading players expanding their capabilities to address the complexities of building regulations and ensure safety and compliance in construction projects.
Report Coverage
The research report offers an in-depth analysis based on Service Type, End-User, Sourcing Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for building code compliance services will increase as urbanization and construction projects expand globally.
- Regulatory frameworks will continue to evolve, necessitating ongoing adaptation and expertise in compliance.
- Integration of advanced technologies like AI and IoT will enhance compliance monitoring and efficiency.
- Sustainability will remain a top priority, driving the adoption of green building practices and related compliance standards.
- Digital tools and platforms will increasingly streamline compliance processes, reducing time and costs for stakeholders.
- The focus on safety will lead to more stringent enforcement of building codes, requiring robust compliance measures.
- Increased collaboration among industry players will foster innovation and the development of integrated compliance solutions.
- Education and training initiatives will expand to improve stakeholder awareness and understanding of building codes.
- Performance-based codes will gain traction, offering flexibility while requiring specialized compliance expertise.
- The market will see new entrants, enhancing competition and driving innovation in building code compliance services.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Building Code Compliance Market?
What factors are driving the growth of the Building Code Compliance Market?
What are the key segments within the Building Code Compliance Market?
Who are the major players in the Building Code Compliance Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Building Code Compliance Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Building Code Compliance Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 9,338.35 million → 2032: USD 19,278.20 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Building Code Compliance Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Building Code Compliance Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Building Code Compliance Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Building Code Compliance Market Drivers
- 3.3 Building Code Compliance Market Restraints & Challenges
- 3.4 Building Code Compliance Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Building Code Compliance Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Building Code Compliance Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Building Code Compliance category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Building Code Compliance Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Building Code Compliance Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Building Code Compliance. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Building Code Compliance Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Building Code Compliance Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Building Code Compliance Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Building Code Compliance (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Building Code Compliance
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Building Code Compliance Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Building Code Compliance Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Building Code Compliance Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Building Code Compliance Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Building Code Compliance Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Building Code Compliance Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Building Code Compliance Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Building Code Compliance Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
